
 Gynecological Cancers Market | 2026-2036
Gynecological Cancers Market Size, Share, and Industry Trends Forecast 2026-2036
Gynecological Cancers Market Outlook
Oncology hospitals are reorganizing procurement priorities around precision medicine capabilities, shifting volume toward institutions with integrated molecular diagnostics. Roche leverages its companion diagnostic infrastructure to sustain leadership in biomarker-driven therapy selection. AstraZeneca anchors its position through PARP inhibitor specialization across multiple gynecological indications. Pfizer competes via broad oncology portfolio scale and global distribution reach.
Gynecological cancers encompass malignancies of the female reproductive system including ovarian, cervical, uterine, vaginal, and vulvar cancers, diagnosed through histopathological examination, CA-125 and HE4 biomarker quantification, HPV genotyping, and imaging modalities such as transvaginal ultrasound and pelvic MRI with contrast enhancement. Chemotherapy retains the largest revenue share due to entrenched clinical protocols and broad eligibility criteria, while immunotherapy represents the fastest-expanding segment as checkpoint inhibitors gain regulatory approvals in recurrent and metastatic settings. Imaging systems command significant capital investment from end users upgrading to AI-enhanced diagnostic platforms.
The FDA accelerates market entry through breakthrough therapy and fast track designations, while the EMA's centralized procedure shapes commercial strategy across European member states and the PMDA governs reimbursement and access in Japan. Regulatory stringency around biomarker validation and companion diagnostic co-development directly determines which therapeutic platforms achieve premium pricing and formulary placement. Stakeholders must monitor evolving health technology assessment criteria and real-world evidence requirements that increasingly dictate market access outcomes.
Market Dynamics
Precision oncology protocols are restructuring treatment hierarchies across gynecological cancer care, forcing hospitals to consolidate molecular diagnostics capabilities or lose referral volume to academic medical centers with integrated biomarker infrastructure.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:The accelerated approval mechanism compresses commercialization timelines for novel PARP inhibitors and antibody-drug conjugates, enabling earlier patient access to transformative therapies.
- HPV Genotyping Expansion:Cervical cancer screening programs in Germany and Japan are integrating high-risk HPV molecular testing, expanding the addressable diagnostic population beyond cytology-dependent protocols.
- Academic Medical Center Consolidation:Leading oncology institutions in the United States are centralizing complex gynecological cases, concentrating demand for biomarker-driven therapeutic selection and companion diagnostic testing.
Market Restraints
- Companion Diagnostic Co-Development Costs:Parallel validation of biomarker assays with therapeutic candidates imposes capital requirements that exclude smaller diagnostic developers from premium pricing tiers.
- Reimbursement Uncertainty in Japan:PMDA assessment timelines for novel immunotherapy combinations create access delays that compress commercial runway before patent expiration.
- Chemotherapy Entrenchment:Established platinum-based protocols in recurrent ovarian cancer limit physician willingness to switch toward immunotherapy despite superior progression-free survival data in selected populations.
Strategic Opportunities
- Real-World Evidence Mandates:EMA's evolving health technology assessment criteria in Germany reward manufacturers with post-authorization study infrastructure, creating first-mover advantage in formulary placement negotiations.
- AI-Enhanced Imaging Integration:Transvaginal ultrasound platforms with embedded machine learning algorithms for adnexal mass characterization represent underpenetrated upgrade cycles in community hospital settings.
- Biomarker Portfolio Expansion:Homologous recombination deficiency testing beyond BRCA1/2 is opening addressable populations for PARP inhibitor therapy in uterine and cervical malignancies.
Industry Challenges
- Molecular Pathology Workforce Constraints:Specialized training requirements for next-generation sequencing interpretation and biomarker reporting create bottlenecks in diagnostic turnaround times.
- Cross-Border Trial Complexity:Divergent informed consent and tissue export regulations between the United States, European Union member states, and Japan fragment clinical development program execution.
- Legacy EHR Integration Friction:Precision oncology workflows require interoperability between molecular diagnostic laboratories, pathology systems, and electronic health records that many community oncology practices lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gynecological Cancers Market |
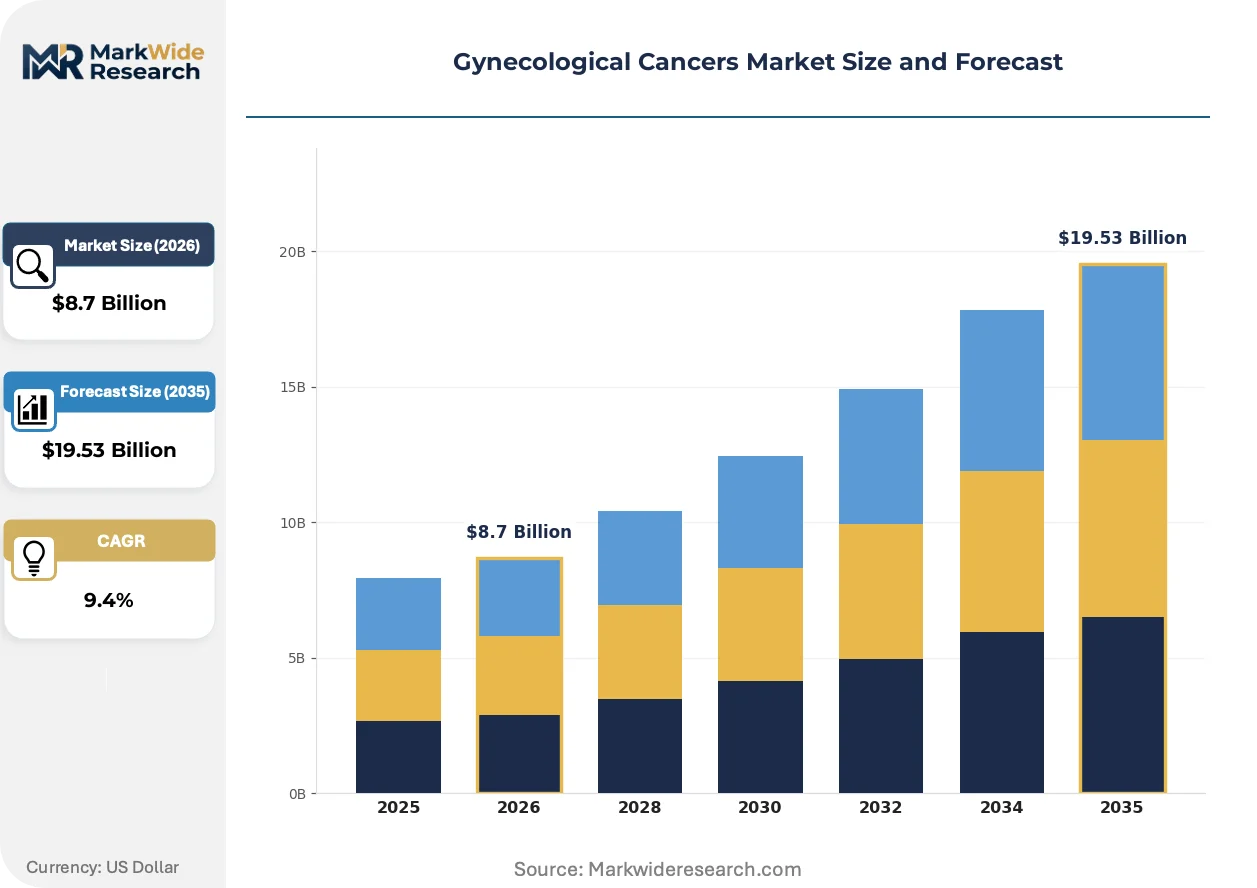
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Technology: Biomarkers, Genomics, Imaging Systems, Surgical Robotics End User: Oncology Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Research Institutes Application: Diagnosis, Treatment, Screening, Prognosis |
| Companies Covered | Roche, AstraZeneca, Pfizer, Merck & Co., Johnson & Johnson Services, Sanofi, Eli Lilly and Company, AbbVie, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gynecological Cancers Market Strategic Shifts
Liquid biopsy platforms are displacing tissue-dependent molecular profiling across gynecological cancer subtypes, while regulatory frameworks adapt to validate circulating tumor DNA assays for treatment selection and monitoring applications.
Next-generation sequencing panels are fragmenting the molecular diagnostic landscape for ovarian and endometrial cancers. Community oncology practices in the United States are adopting comprehensive genomic profiling at accelerating pace, replacing single-gene BRCA testing. This technology is fragmenting referral patterns as patients seek institutions with matched targeted therapy trial access.
EMA's centralized procedure for oncology medicines is harmonizing market access requirements across European member states. The regulation compresses national pricing negotiation timelines and elevates health technology assessment evidence standards. Germany's Federal Joint Committee (G-BA) early benefit assessment process most acutely affects manufacturers lacking comparative effectiveness data against standard-of-care chemotherapy.
Hospital procurement committees are elevating total cost-of-care criteria above unit price in therapeutic selection decisions. Oncology pharmacy directors in Japan are negotiating risk-sharing arrangements for high-cost immunotherapy agents, displacing traditional volume-based purchasing contracts. This behavioral shift concentrates most visibly in academic medical centers managing complex recurrent disease populations.
Gynecological Cancers Market Segmentation
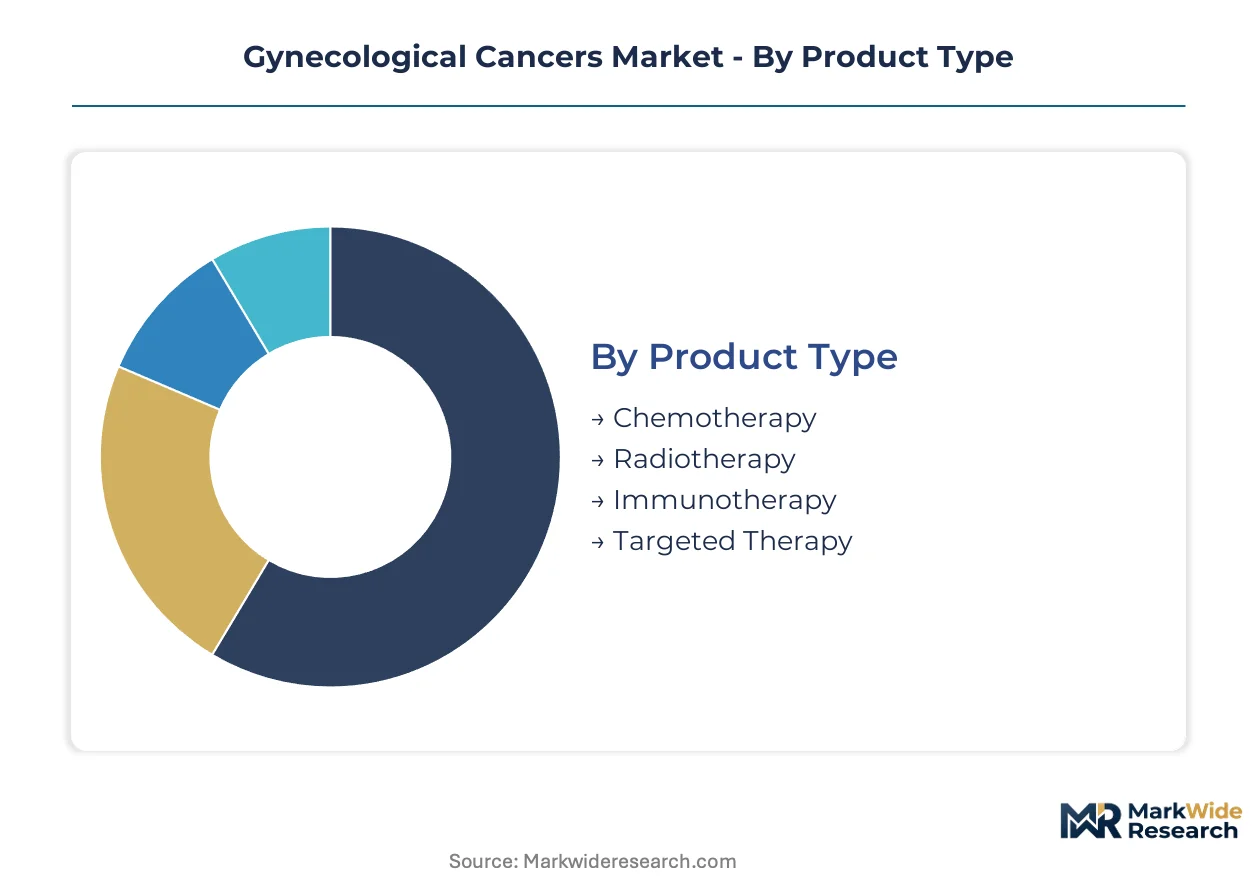
Gynecological cancer care fragments across distinct procurement channels, with academic medical centers driving premium therapeutic adoption while community settings anchor volume-based chemotherapy protocols. Treatment modality selection increasingly depends on biomarker infrastructure availability rather than physician preference alone.
Product Type:
Chemotherapy and immunotherapy flow through separate procurement channels, with platinum-based agents dominating hospital formularies and checkpoint inhibitors requiring specialty pharmacy distribution.
- Chemotherapy:Platinum-taxane combinations retain entrenched positioning in first-line ovarian and cervical protocols, with entrenched clinical guidelines limiting switching incentives. Demand concentrates in United States community oncology practices and German statutory health insurance networks where reimbursement pathways are codified.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors are displacing chemotherapy in recurrent and metastatic settings where biomarker expression thresholds are met. Academic medical centers in Japan and the United States capture disproportionate volume due to companion diagnostic integration requirements.
- Radiotherapy:External beam and brachytherapy modalities serve localized disease stages with established capital equipment depreciation schedules.
- Targeted Therapy:PARP inhibitors and angiogenesis inhibitors require molecular profiling infrastructure that fragments addressable populations.
By volume, chemotherapy leads. By growth pace, immunotherapy is ahead.
Technology:
Diagnostic technology investments stratify by end-user sophistication, with comprehensive genomic profiling concentrating in academic centers and single-biomarker assays serving community laboratories.
- Biomarkers:CA-125 and HE4 quantification remains standard for ovarian cancer monitoring, with HPV genotyping expanding cervical screening programs in Germany and Japan. Community laboratories in the United States process the majority of volume due to CLIA-waived platform availability.
- Genomics:Next-generation sequencing panels for homologous recombination deficiency are fragmenting referral patterns toward institutions with matched therapy trial access. Academic medical centers capture premium pricing for comprehensive profiling that community practices cannot support.
- Imaging Systems:MRI and CT platforms with AI-enhanced lesion characterization command capital replacement cycles in tertiary hospitals.
- Surgical Robotics:Minimally invasive platforms concentrate procedure volume in high-throughput oncology hospitals with dedicated gynecologic oncology services.
Imaging systems generate the largest capital expenditure commitments. Genomics commands the steepest expansion trajectory.
End User:
Procurement authority varies sharply across settings, with oncology pharmacy directors controlling therapeutic selection in hospitals and reference laboratories governing diagnostic test menus.
- Oncology Hospitals:Tertiary institutions with integrated molecular tumor boards capture complex case referrals and concentrate demand for biomarker-driven therapeutic selection. United States National Cancer Institute-designated centers and Japanese cancer center hospitals anchor premium protocol adoption.
- Diagnostic Laboratories:Centralized reference laboratories process high-throughput HPV and biomarker testing for regional health systems, with German medical laboratory associations and United States commercial reference labs dominating screening volume.
- Ambulatory Surgical Centers:Limited to early-stage procedures with established same-day discharge protocols.
- Research Institutes:Academic research organizations conduct biomarker validation and early-phase therapeutic trials.
Oncology hospitals absorb the majority of therapeutic expenditure. Diagnostic laboratories process the highest test volumes.
Application:
Clinical utility varies across the care continuum, with screening applications governed by population health mandates and prognosis applications requiring longitudinal data infrastructure.
- Diagnosis:Histopathological confirmation and imaging staging establish treatment pathways, with transvaginal ultrasound and pelvic MRI serving as gatekeepers to specialist referral in United States and German gynecologic oncology networks.
- Treatment:Therapeutic intervention spans surgical, radiation, and systemic modalities with reimbursement rates determining site-of-service selection. Japanese Diagnosis Procedure Combination pricing and German DRG frameworks directly influence protocol economics.
- Screening:Cytology and HPV molecular testing programs target asymptomatic populations with cost-effectiveness thresholds set by national health technology assessment bodies.
- Prognosis:Minimal residual disease monitoring via circulating tumor DNA remains investigational outside academic protocols.
Treatment commands the largest expenditure share. Screening reaches the broadest patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States precision oncology protocols flow into German diagnostic networks and Japanese cancer center procurement systems, establishing a three-corridor trade in biomarker validation expertise and companion diagnostic infrastructure.
United States
FDA breakthrough therapy designations compress commercialization timelines for PARP inhibitors and antibody-drug conjugates, accelerating patient access. National Cancer Institute-designated centers in Houston and New York consolidate complex gynecological case referrals, concentrating demand for molecular tumor board infrastructure and biomarker-driven therapeutic selection.
Germany
G-BA early benefit assessments reshape formulary placement negotiations for novel immunotherapy agents, elevating comparative effectiveness evidence requirements. HPV genotyping expansion within statutory health insurance networks broadens cervical cancer screening addressable populations beyond cytology-dependent protocols in Bavaria and North Rhine-Westphalia.
Japan
PMDA assessment timelines for checkpoint inhibitor combinations create reimbursement access delays that compress commercial runway. Cancer center hospitals in Tokyo and Osaka anchor premium protocol adoption, capturing disproportionate immunotherapy volume due to companion diagnostic integration mandates and Diagnosis Procedure Combination pricing frameworks.
United Kingdom
NICE technology appraisals govern NHS England commissioning decisions for targeted therapies, with real-world evidence requirements tightening post-authorization study obligations. London and Manchester academic medical centers drive genomic profiling adoption, fragmenting referral patterns toward institutions with matched therapy trial access.
Switzerland
Swissmedic marketing authorization procedures align with EMA centralized pathways while preserving national pricing autonomy. Basel and Zurich oncology networks concentrate pharmaceutical R&D proximity effects, enabling rapid protocol translation from clinical trial enrollment to community hospital adoption.
Gynecological Cancers Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with oncology franchise scale, creating a consolidated structure around companion diagnostic-therapy pairing capabilities. Three archetypes dominate: integrated diagnostic-therapeutic platforms, PARP inhibitor specialization houses, and broad oncology portfolio scale players. Competitive moves concentrate on biomarker portfolio expansion and academic medical center partnership networks.
Within the integrated diagnostic-therapeutic tier, Roche anchors companion diagnostic infrastructure leadership, while AstraZeneca exemplifies PARP inhibitor specialization across multiple gynecological indications. Pfizer occupies a position defined by broad oncology portfolio scale and global distribution reach. These three represent the dominant competitive anchors shaping procurement committee evaluations and molecular diagnostics integration requirements.
| Leading Market Players |
|---|
| Roche |
| AstraZeneca |
| Pfizer |
| Merck & Co. |
| Johnson & Johnson Services |
| Sanofi |
| Eli Lilly and Company |
| AbbVie |
| Boehringer Ingelheim International GmbH |
| Others |
Value Chain & Pricing Dynamics
FDA breakthrough therapy designation thresholds gate both supply qualification and price differentiation simultaneously, as manufacturers must co-develop companion diagnostics to access accelerated pathways while biomarker infrastructure investments stratify institutional purchasing power across academic medical centers and community oncology practices.
Pricing Analysis
Next-generation PARP inhibitors command 40-60% premiums over prior-generation chemotherapy protocols, while emerging antibody-drug conjugates position at investigational price points awaiting reimbursement negotiation. Three-tier pricing structure across premium, standard, and economy levels reflects biomarker infrastructure requirements, with academic medical centers absorbing premium tier costs and German statutory health insurance networks negotiating standard tier access. Price differentiation rests on companion diagnostic integration depth and molecular tumor board availability. Cost compression in the chemotherapy segment is intensifying because biosimilar entry erodes platinum-taxane margins. Community oncology practices exhibit highest price sensitivity due to limited formulary flexibility, while Japanese cancer center hospitals demonstrate lowest sensitivity given Diagnosis Procedure Combination pricing frameworks.
Supply Chain Analysis
Inventory buffers for checkpoint inhibitors extend to 90-120 days given cold-chain requirements and batch release testing protocols, constraining just-in-time delivery models. Active pharmaceutical ingredient manufacturing concentrates in Ireland, Switzerland, and Singapore for novel biologics, with fill-finish operations distributed across United States and German contract manufacturing networks. Supply chains draw from monoclonal antibody cell lines, sterile vial components, and temperature-controlled logistics infrastructure. Single-source vulnerability permeates the companion diagnostic reagent segment where proprietary assay platforms lock hospitals into sole-supplier arrangements. Distribution runs through specialty pharmacy channels for immunotherapy agents and hospital wholesale networks for chemotherapy protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision oncology penetration sits at early-cycle expansion, with liquid biopsy adoption and homologous recombination deficiency testing expansion providing measurable tailwinds in addressable patient population expansion.
For Market Incumbents: Compound biomarker portfolio breadth through parallel validation of homologous recombination deficiency assays beyond BRCA1/2, defending against emerging genomics specialists threatening diagnostic revenue capture. Deepen backward integration into next-generation sequencing platform development to secure supply control over molecular profiling infrastructure. Prioritize academic medical center partnership networks in Tokyo and Houston to anchor referral volume concentration. For New Entrants and Emerging Players: Anchor in community oncology practice settings where legacy EHR integration friction creates incumbent vulnerability and biomarker infrastructure gaps persist. Target ambulatory surgical centers in Germany's Bavaria and North Rhine-Westphalia regions for HPV genotyping platform placement, leveraging CLIA-waived assay availability to bypass molecular pathology workforce constraints. Pursue risk-sharing reimbursement arrangements with Japanese oncology pharmacy directors as differentiated market entry mechanism. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid biopsy platform development, elevating burn rates for pre-revenue diagnostic developers and compressing valuation multiples for Series C-stage companies lacking FDA submission timelines. Acquisition target archetype: vertically integrated diagnostic-therapeutic pairs with validated companion diagnostic assays and established hospital formulary placement. Signal to watch: EMA centralized procedure approval velocity for novel immunotherapy combinations as inflection indicator for European market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA breakthrough pathway access requires parallel biomarker validation with therapeutic candidates. |
| Academic Medical Center Partnership | NCI-designated centers in Houston and New York concentrate complex case referral volume. |
| Liquid Biopsy Platform Launch | Circulating tumor DNA assays displace tissue-dependent molecular profiling in ovarian monitoring. |
| HPV Genotyping Expansion | German statutory health insurance networks broaden cervical screening beyond cytology protocols. |
| Real-World Evidence Infrastructure | EMA health technology assessment criteria reward post-authorization study capabilities in formulary negotiations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oncology pharmacy directors, molecular pathologists, regulatory affairs leads at pharmaceutical manufacturers, and hospital procurement committee members. Secondary validation incorporated FDA breakthrough therapy designation filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and German G-BA early benefit assessment documentation. Bottom-up therapeutic volume modeling triangulated against top-down market size estimates derived from hospital formulary expenditure patterns and diagnostic laboratory test volume data.
Across the analysis window, the quantitative framework segmented revenue projections by treatment modality, technology platform, end-user institution type, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical adoption curves for prior-generation oncology therapies, adjusted for biomarker penetration rates and companion diagnostic availability timelines. Forecast inputs incorporated PMDA reimbursement assessment timelines, HPV screening program expansion trajectories, and AI-enhanced imaging platform replacement cycles.
Material uncertainties — regulatory approval delays, reimbursement negotiation outcomes, and molecular pathology workforce expansion rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding biomarker test adoption curves and immunotherapy eligibility expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Cancer/Tumor Profiling Market
Oncology
Cancer API Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Lung Cancer Treatment Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Bone Metastasis Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Pituitary Cancer Market
Oncology
Pancreatic Cancer Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Metastatic Cancer Drug Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
North America Tumor Ablation Market
Oncology
Ewing Sarcoma Treatment Market