
 Global Brain Monitoring Devices Market | 2026-2036
Global Brain Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brain Monitoring Devices Market Foresight
Silicon photonics is realigning sensor economics in non-invasive neuromonitoring by replacing traditional electrode materials with optical waveguide substrates that cut signal noise. Medtronic plc leverages deep vertical integration across implantable and external monitoring platforms to sustain pricing power in intensive care settings. Nihon Kohden Corporation anchors its competitive position through dense channel control across Japanese and Southeast Asian hospital networks. Koninklijke Philips N.V. differentiates via embedded AI analytics that compress raw EEG data into clinician-actionable alerts.
Brain monitoring devices comprise instrumented systems that acquire, amplify, and interpret electrical, metabolic, or hemodynamic signals from neural tissue, typically resolving microvolt-level potentials at sampling rates exceeding 256 Hz for clinical-grade electroencephalography. These systems serve primary commercial purposes in perioperative neuroprotection, epilepsy localization, and traumatic brain injury triage where real-time physiological feedback alters therapeutic decisions. Electroencephalography devices occupy the largest revenue pool owing to universal deployment in operating rooms and epilepsy monitoring units, while cerebral oximeters represent the fastest-expanding category as dual-channel near-infrared spectroscopy penetrates cardiac surgery and neonatal intensive care. Neurofeedback devices command premium pricing in cognitive therapy monitoring applications where software-enabled neuroplasticity protocols justify recurring subscription revenue.
The FDA's breakthrough devices program accelerates market access for novel neuromonitoring platforms, while the EU MDR imposes stricter clinical evidence requirements on legacy EEG systems seeking CE mark renewal. Japan's PMDA maintains rigorous electromagnetic compatibility standards that filter out lower-tier manufacturers from hospital procurement lists. Stakeholders must monitor how reimbursement coding for remote EEG interpretation reshapes capital deployment between bedside hardware and cloud-native diagnostic services.
Market Dynamics
Silicon photonics is compressing sensor economics across non-invasive neuromonitoring platforms by displacing legacy electrode substrates with optical waveguide architectures that eliminate electromagnetic interference. This materials transition is redistributing value capture from hardware manufacturers toward semiconductor foundries with photonics fabrication capabilities.
Growth Catalysts
- Neurological emergency protocols:University hospital networks in Germany are embedding multimodal brain monitoring into standardized stroke triage workflows, creating institutional procurement mandates for integrated EEG-cerebral oximetry systems.
- FDA breakthrough pathway:The FDA's evolving neurotechnology guidance is compressing approval timelines for novel neuromonitoring platforms, accelerating commercialization of AI-embedded diagnostic algorithms.
- Neonatal intensive care expansion:Dual-channel near-infrared spectroscopy is penetrating cardiac surgery and NICU settings, driven by evidence protocols linking cerebral oxygen saturation to neurodevelopmental outcomes.
Market Restraints
- Specialized semiconductor supply concentration:Silicon photonics foundry capacity concentrates among three contract manufacturers, exposing OEMs to allocation risk during capacity constraints.
- EU MDR clinical evidence burden:The EU MDR imposes retrospective clinical validation requirements on legacy EEG systems seeking CE mark renewal, forcing substantial documentation costs on established product lines.
- Disposable electrode cost structure:Silver-silver chloride electrode materials face commodity price volatility, compressing margins on high-volume external monitoring consumables.
Strategic Opportunities
- Remote EEG interpretation services:Reimbursement coding evolution for cloud-native diagnostic platforms is redirecting capital deployment from bedside hardware toward software-enabled recurring revenue models.
- Southeast Asian hospital network penetration:Dense channel control across Japanese and Southeast Asian procurement lists creates acquisition pathways for integrated monitoring platform vendors.
- Neurofeedback cognitive therapy:Software-enabled neuroplasticity protocols in cognitive therapy monitoring justify premium subscription pricing, opening recurring revenue streams outside acute care settings.
Industry Challenges
- Electromagnetic compatibility certification:Japan's PMDA maintains rigorous EMC standards that filter lower-tier manufacturers from hospital procurement lists, extending compliance timelines for new market entrants.
- AI algorithm validation complexity:Embedded analytics compressing raw EEG data into clinician-actionable alerts require extensive clinical validation across diverse patient populations, straining R&D resource allocation.
- Legacy system integration friction:Multimodal monitoring platforms must interface with existing hospital information systems, creating interoperability engineering burdens that delay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brain Monitoring Devices Market |
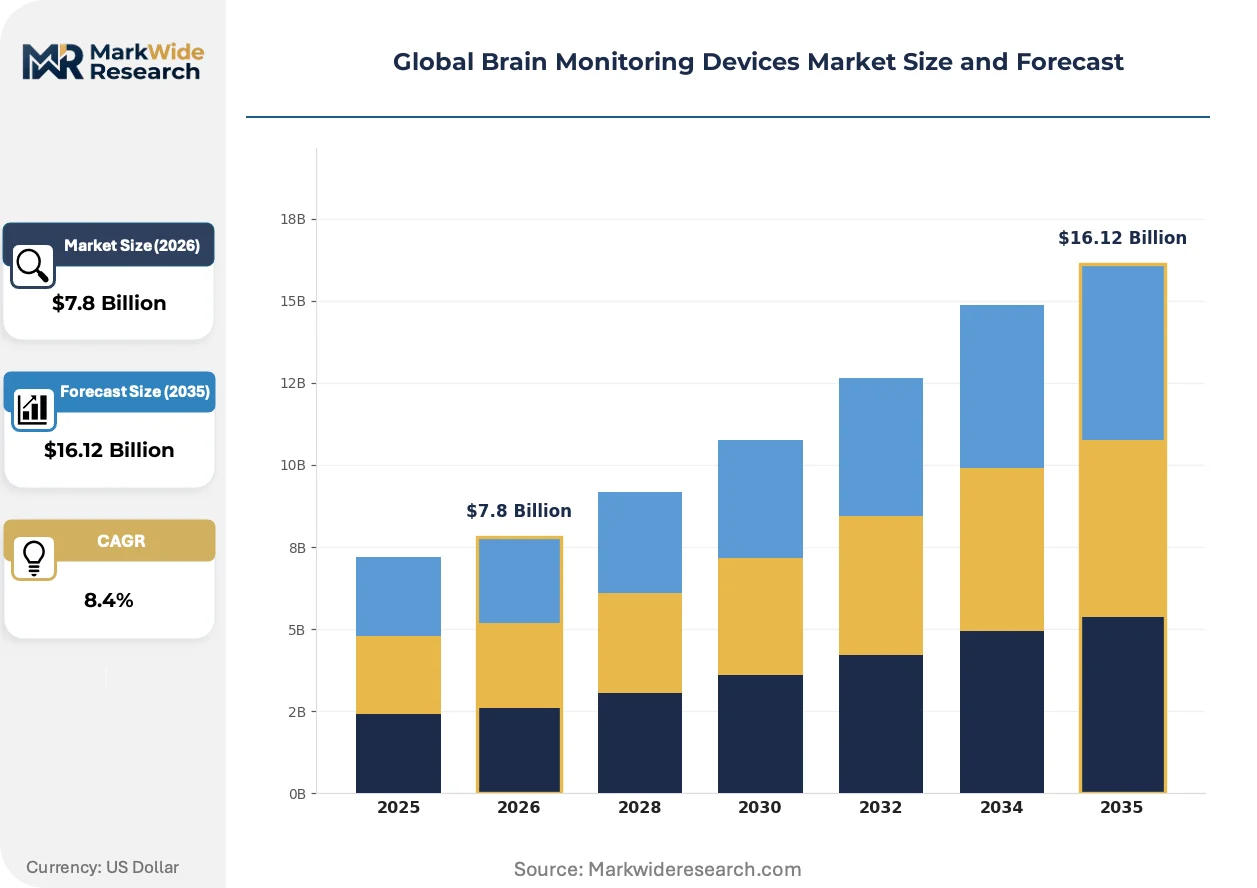
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography Devices, Magnetoencephalography Systems, Cerebral Oximeters, Brain Mapping Devices, Neurofeedback Devices Technology: Functional MRI, Near-Infrared Spectroscopy, Evoked Potentials, Positron Emission Tomography, Transcranial Doppler Ultrasonography Application: Neurological Disorder Diagnosis, Cognitive Therapy Monitoring, Sleep Studies, Brain Injury Assessment, Neurodegenerative Disease Tracking End User: Neuroscience Research Centers, Rehabilitation Facilities, Diagnostic Laboratories, Emergency Care Units, Specialty Clinics |
| Companies Covered | GE Healthcare, Advanced Brain Monitoring Inc., Medtronic plc, Masimo Corporation, Compumedics Limited, Natus Medical Incorporated, Koninklijke Philips N.V., Edwards Lifesciences Corporation, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brain Monitoring Devices Market Shifts & Advancements
Optical sensing architectures are displacing electrical acquisition methods across multiple neuromonitoring modalities, compressing signal noise while enabling wearable form factors. This photonics transition is redistributing competitive advantage toward semiconductor-integrated platform vendors.
Silicon photonics is overtaking traditional electrode materials in non-invasive brain monitoring by replacing conductive substrates with optical waveguide architectures that eliminate electromagnetic interference. Operating room and epilepsy monitoring unit buyers are adopting photonics-integrated EEG platforms at accelerating cadence as signal fidelity demonstrations accumulate. This technology is overtaking legacy electrical acquisition in premium system tiers, compressing value capture toward photonics foundries and away from conventional electrode manufacturers.
The EU MDR is imposing stricter clinical evidence requirements on legacy EEG systems seeking CE mark renewal, forcing substantial retrospective validation investments. This regulatory friction is advantaging newer platforms with prospective clinical datasets while disadvantaging decades-old product lines with limited documentation archives. Intensive care and epilepsy monitoring segments in European markets are responding by accelerating procurement of MDR-native systems ahead of legacy product sunset timelines.
Hospital procurement committees are unbundling hardware acquisition from diagnostic interpretation services, separating capital equipment purchasing from ongoing clinical decision support subscriptions. Traditional bundled sales models in perioperative neuroprotection are yielding to discrete contracting for devices, software, and remote monitoring services. This unbundling is most visible in United States health systems where reimbursement coding changes enable distinct billing for remote EEG interpretation.
Global Brain Monitoring Devices Market Segmentation
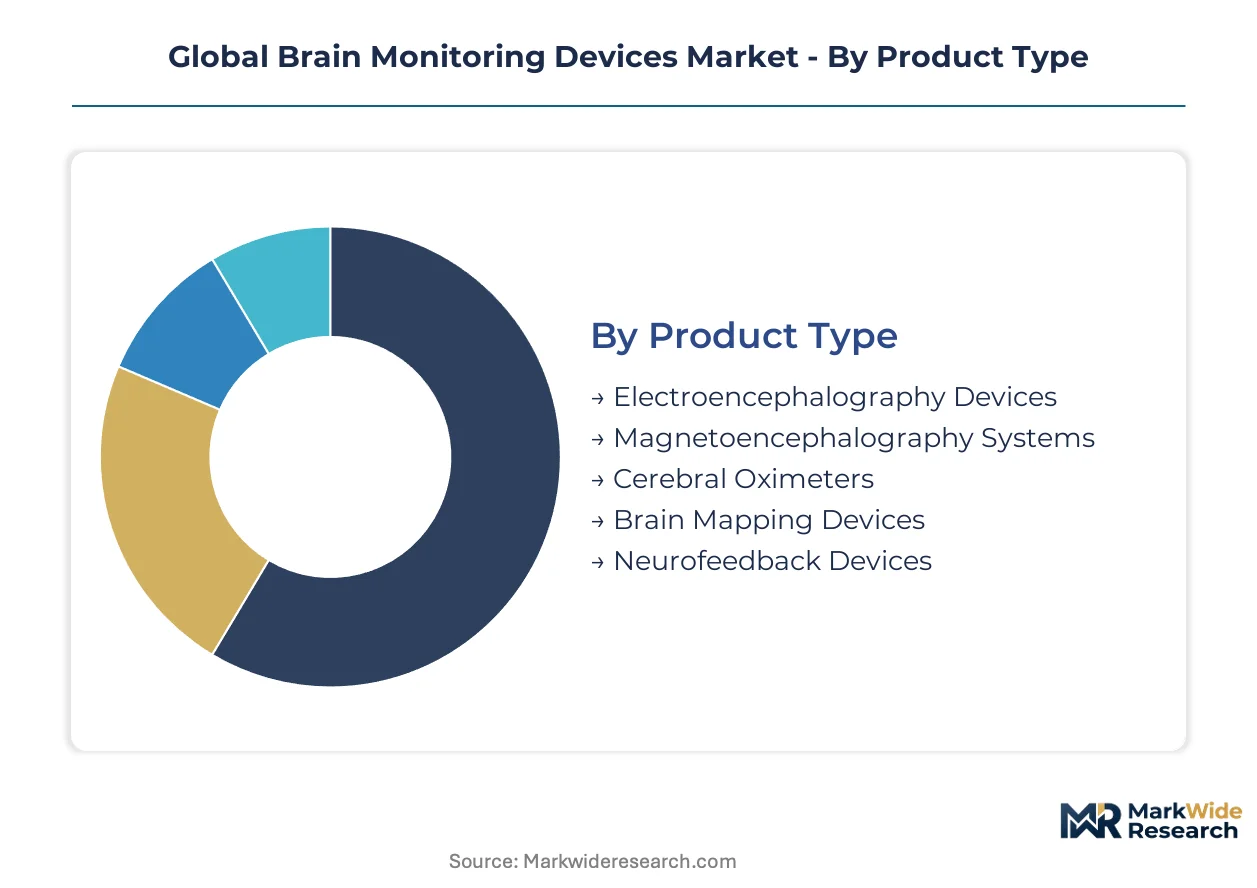
Brain monitoring device procurement varies sharply by clinical setting, with regulatory pathways and reimbursement codes determining which segments penetrate hospital budgets versus research grants. Technology selection hinges on whether the use case demands continuous bedside surveillance or episodic diagnostic imaging.
Product Type:
Electroencephalography devices carry the heaviest FDA 510(k) submission volume among neuromonitoring hardware, while cerebral oximeters face streamlined breakthrough device scrutiny for cardiac surgery indications. Magnetoencephalography systems require radioactive materials licensing that constrains site placement.
- Electroencephalography Devices:These systems acquire microvolt-level cortical potentials through scalp-mounted electrodes at sampling rates exceeding 256 Hz for clinical-grade interpretation. Demand concentrates in German university hospital networks embedding multimodal monitoring into stroke triage protocols, driven by institutional procurement mandates for integrated EEG-cerebral oximetry platforms.
- Cerebral Oximeters:Dual-channel near-infrared spectroscopy platforms measure regional cerebral oxygen saturation through emitter-detector pairs on the forehead. Adoption accelerates in neonatal intensive care units across the United States, where evidence protocols link cerebral oxygen saturation metrics to neurodevelopmental outcome tracking.
- Magnetoencephalography Systems:Superconducting quantum interference device arrays detect femtotesla-scale magnetic fields from neuronal currents, requiring liquid helium cooling infrastructure.
- Brain Mapping Devices:Multimodal integration platforms combine electrical, metabolic, and hemodynamic signals into unified cortical activation visualizations for surgical planning.
- Neurofeedback Devices:Consumer-facing and clinical systems enabling operant conditioning of EEG patterns through real-time auditory or visual feedback loops.
Electroencephalography devices sit at the top of the volume ranking, with cerebral oximeters climbing the fastest.
Technology:
Functional MRI commands premium capital expenditure tiers due to cryogenic magnet maintenance and radiofrequency shielding requirements, while near-infrared spectroscopy penetrates lower-cost ambulatory settings. Positron emission tomography faces cyclotron proximity constraints that limit geographic deployment.
- Functional MRI:Blood-oxygen-level-dependent contrast imaging detects hemodynamic responses to neural activation at millimeter spatial resolution. Research centers in Japan drive procurement volumes, constrained by PMDA electromagnetic compatibility certification timelines that filter lower-tier vendors from hospital procurement lists.
- Near-Infrared Spectroscopy:Optical absorption spectroscopy at 700-900 nanometers penetrates scalp and skull to measure cortical hemoglobin concentration changes. Cardiac surgery departments across Germany adopt dual-channel configurations fastest, propelled by evidence linking intraoperative cerebral desaturation to postoperative cognitive decline.
- Evoked Potentials:Time-locked EEG averaging isolates neural responses to sensory, motor, or cognitive stimuli for pathway integrity assessment.
- Positron Emission Tomography:Radiotracer distribution imaging quantifies metabolic activity through positron-emitting isotope decay detection.
- Transcranial Doppler Ultrasonography:Pulsed-wave Doppler through the temporal bone window measures cerebral blood flow velocity in major intracranial arteries.
Functional MRI dominates capital expenditure allocation, with near-infrared spectroscopy expanding most quickly.
Application:
Neurological disorder diagnosis attracts the densest regulatory filing activity across FDA and EMA pathways, while cognitive therapy monitoring operates under lighter wellness-device oversight in many jurisdictions. Sleep studies face distinct reimbursement coding that separates polysomnography from home monitoring modalities.
- Neurological Disorder Diagnosis:Epilepsy localization and stroke triage protocols drive continuous EEG and multimodal platform deployment. Emergency care units in the United States accelerate adoption fastest, reshaped by FDA neurotechnology guidance compressing approval timelines for AI-embedded diagnostic algorithms.
- Cognitive Therapy Monitoring:Software-enabled neuroplasticity protocols justify premium subscription pricing outside acute care settings. Southeast Asian rehabilitation facilities concentrate demand, where dense channel control across Japanese procurement networks creates acquisition pathways for integrated platform vendors.
- Sleep Studies:Polysomnography and home sleep apnea testing employ EEG, EOG, and EMG channels to stage sleep architecture and detect respiratory events.
- Brain Injury Assessment:Traumatic brain injury triage employs compressed EEG, pupillometry, and cerebral oximetry for rapid severity stratification.
- Neurodegenerative Disease Tracking:Longitudinal monitoring of Alzheimer's and Parkinson's progression through quantitative EEG markers and functional imaging biomarkers.
Neurological disorder diagnosis commands the largest installed base, with cognitive therapy monitoring gaining share fastest.
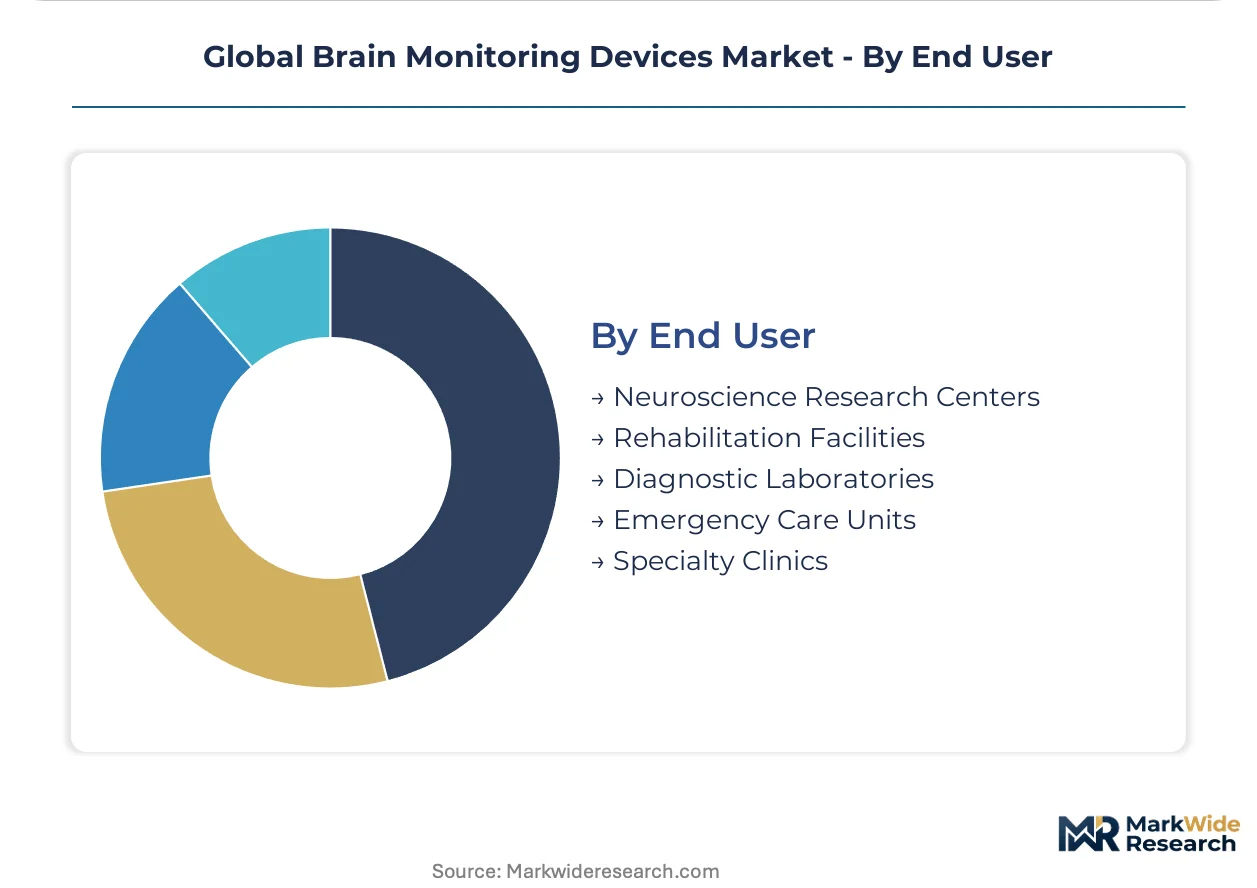
End User:
Neuroscience research centers tolerate longer validation timelines and higher technical complexity than clinical sites, while emergency care units prioritize FDA breakthrough pathway access for rapid deployment. Diagnostic laboratories face EU MDR retrospective evidence burdens that disadvantage legacy system vendors.
- Neuroscience Research Centers:Academic and institutional facilities pursuing basic and translational neuroscience employ the full spectrum of invasive and non-invasive modalities. German university hospital networks anchor procurement for multimodal platforms, integrating standardized stroke protocols that mandate EEG-cerebral oximetry system bundling.
- Emergency Care Units:Time-critical triage settings demand portable, rapid-deployment monitoring with automated interpretation support. United States health systems concentrate demand here, where reimbursement coding evolution for remote EEG interpretation redirects capital deployment from bedside hardware toward cloud-native diagnostic services.
- Rehabilitation Facilities:Post-acute settings employing neurofeedback and functional assessment for recovery monitoring.
- Diagnostic Laboratories:Centralized interpretation hubs processing ambulatory EEG and sleep study data through technologist and physician over-read workflows.
- Specialty Clinics:Epilepsy monitoring units and movement disorder centers with dedicated electrophysiology technical staff.
Emergency care units lead volume expansion, with neuroscience research centers maintaining the steepest technology upgrade cadence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital networks anchor procurement intensity for multimodal brain monitoring platforms, embedding standardized EEG-cerebral oximetry protocols into stroke triage workflows across Europe's densest neurocritical care cluster.
United States
Emergency care units concentrate demand acceleration for portable monitoring systems with automated interpretation capabilities. FDA breakthrough device pathways compress approval timelines for AI-embedded diagnostic algorithms, redirecting capital deployment toward cloud-native EEG interpretation services. Boston and San Francisco metropolitan clusters house the densest concentration of neurotechnology startups commercializing photonics-integrated platforms.
Germany
University hospital networks mandate integrated EEG-cerebral oximetry bundling within standardized stroke protocols, creating institutional procurement lock-in for multimodal systems. EU MDR retrospective evidence requirements filter legacy EEG vendors from CE mark renewal pathways, advantaging MDR-native platform suppliers. The Rhine-Ruhr and Bavarian medical technology corridors concentrate manufacturing capabilities for high-channel-count electrophysiology systems.
Japan
PMDA electromagnetic compatibility certification standards enforce rigorous filtering of lower-tier manufacturers from hospital procurement lists, extending compliance timelines for new market entrants. METI funding programs support domestic semiconductor photonics integration for next-generation neuromonitoring sensor architectures. The Kanto region surrounding Tokyo maintains the steepest hospital technology upgrade cadence for superconducting quantum interference device arrays.
China
NMPA medical device registration reforms accelerate market access for imported neuromonitoring platforms while tightening clinical evidence requirements for domestic manufacturers. National hospital tier classification systems concentrate premium EEG and cerebral oximetry procurement in tertiary-grade facilities across Beijing, Shanghai, and Guangzhou. The Yangtze River Delta medical device manufacturing cluster scales production of disposable electrode consumables for regional hospital networks.
India
CDSCO medical device rules impose risk-based classification on neuromonitoring hardware, creating differentiated registration pathways for invasive versus non-invasive systems. PLI scheme incentives attract contract manufacturing investment for electrode assemblies and optical sensor components. Maharashtra and Karnataka state hospital networks expand neurocritical care bed capacity fastest, driving demand for portable brain injury assessment platforms in tier-2 city clusters.
Global Brain Monitoring Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEMs secure silicon photonics foundry capacity and cloud-native diagnostic service capabilities. The vendor base stratifies across three tiers: diversified medical technology conglomerates with intensive care platform breadth, specialized electrophysiology houses with dense channel expertise, and emerging photonics-integrated challengers. Two archetypes capture disproportionate value: semiconductor-integrated platform vendors capturing sensor economics, and software-enabled service providers monetizing remote interpretation workflows. M&A activity concentrates on AI algorithm assets and photonics fabrication capabilities, while geographic expansion targets Southeast Asian hospital network penetration.
Within the diversified medical technology tier, Medtronic plc and Koninklijke Philips N.V. exemplify platform breadth strategies spanning implantable and external monitoring modalities. Nihon Kohden Corporation anchors the specialized electrophysiology archetype through dense channel control across Japanese and Southeast Asian procurement networks. These three entities occupy positions that reflect divergent competitive logic: conglomerate scale versus regional density versus integrated semiconductor capability.
| Leading Market Players |
|---|
| GE Healthcare |
| Advanced Brain Monitoring Inc. |
| Medtronic plc |
| Masimo Corporation |
| Compumedics Limited |
| Natus Medical Incorporated |
| Koninklijke Philips N.V. |
| Edwards Lifesciences Corporation |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Silicon photonics fabrication transitions are compressing sensor economics while concentrating supply among three contract foundries, redistributing value capture from legacy electrode manufacturers toward semiconductor-integrated platform vendors and reshaping procurement negotiations for hospital systems.
Pricing Analysis
Silver-silver chloride electrode commodity volatility passes through directly to disposable consumable margins, while photonics-integrated systems command premium positioning through FDA breakthrough pathway differentiation. Three-tier pricing structure across premium photonics-native, standard electrical-acquisition, and economy electrode-based tiers separates systems by signal fidelity and AI-embedded capability. Pricing pressure stems from EU MDR retrospective validation costs burdening legacy EEG vendors, compressing their margin room. Emergency care units exhibit highest price sensitivity due to capital budget constraints, whereas German university hospital networks demonstrate lowest sensitivity where institutional procurement mandates prioritize multimodal integration over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States health systems and German hospital networks, while distributor-mediated pathways serve Southeast Asian and Indian tier-2 city clusters. Photonics foundry capacity concentrates in Taiwan, South Korea, and Japan, with liquid helium cooling infrastructure for MEG systems anchored in the United States and Germany. Raw material dependencies span indium phosphide wafers, silver-silver chloride electrode substrates, and superconducting quantum interference device arrays. Single-source vulnerability in silicon photonics foundry allocation exposes OEMs to capacity constraints during demand surges. Distribution runs through specialized medical device distributors with GPO contracts in North America and direct hospital procurement committees in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Brain Monitoring Devices Market functions as a stable compounder, with neurological emergency protocol standardization across hospital networks generating recurring replacement cycles and software subscription revenue that smooths capital equipment volatility.
For Market Incumbents: Anchor competitive position through backward integration into silicon photonics foundry partnerships, securing captive supply of optical waveguide substrates against allocation risk. Deepen channel control across Japanese and Southeast Asian procurement lists where Nihon Kohden Corporation's density advantage creates switching costs. Prioritize MDR-native clinical datasets to exploit EU regulatory friction disadvantaging legacy EEG vendors with limited documentation archives.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in neurofeedback cognitive therapy monitoring offers white-space entry, where software-enabled neuroplasticity protocols justify recurring subscription revenue outside acute care reimbursement constraints. Target Southeast Asian rehabilitation facilities where dense channel control creates acquisition pathways for integrated platform vendors lacking established presence. Pursue cloud-native diagnostic service positioning to capture reimbursement coding evolution redirecting capital from bedside hardware toward remote EEG interpretation.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized electrophysiology houses with dense channel expertise but limited photonics integration, offering acquisition targets for semiconductor capability roll-up. Long-term viability frames around 5-10 year windows where AI-embedded diagnostic algorithm assets compound through regulatory approval moats. Watch FDA breakthrough pathway approval velocity as inflection signal for platform commercialization timelines and subsequent hospital procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures optical waveguide substrate supply against Taiwan and South Korea allocation constraints. |
| MDR-Native Clinical Dataset Build | Exploits EU regulatory friction disadvantaging legacy EEG vendors with limited documentation. |
| Cloud-Native Diagnostic Platform Launch | Captures United States reimbursement coding evolution toward remote EEG interpretation services. |
| Hospital System GPO Contract Expansion | Locks in procurement committee access across German university networks and United States IDNs. |
| AI Algorithm Regulatory Submission | Accelerates FDA breakthrough pathway timelines for automated EEG interpretation capabilities. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market cluster combining structured interviews with neurocritical care physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR submission databases, PMDA approval records, and hospital procurement system data. Bottom-up triangulation across equipment shipment tracking and top-down reconciliation against health system capital expenditure disclosures ensures dimensional consistency.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with segmentation modeling across product type, technology modality, clinical application, and end-user setting. CAGRs derive from logistic diffusion curves fitted to technology adoption patterns in neurocritical care, with hospital bed capacity expansion and regulatory approval velocity as industry-specific forecast inputs.
Caveats apply where silicon photonics foundry allocation constraints, EU MDR retrospective evidence burden severity, or reimbursement coding evolution timing could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Tricorder Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Brazil Cardiac Pacemakers Market