
 3D Display Market | 2026-2036
3D Display Market Size, Share, and Industry Trends Forecast 2026-2036
3D Display Market Analysis
CE marking under the EU's MDR and EMC directives is reorganizing which display manufacturers can serve European medical imaging clients. Samsung Electronics leverages in-house semiconductor fabrication to control backlight driver supply for its LED volume lines. BOE Technology Group anchors mainland China's panel capacity expansion with government-backed subsidies for OLED pilot lines. Sony differentiates through proprietary lenticular lens arrays in broadcast reference monitors.
A 3D display renders stereoscopic or autostereoscopic imagery through spatial multiplexing, time-sequential shuttering, or light-field modulation, typically achieving depth perception without head-mounted apparatus through parallax barrier or microlens overlay architectures bonded to TFT backplanes. Its primary commercial purpose spans entertainment immersion, surgical visualization, and automotive HUD depth cueing. OLED technology leads margin capture due to self-emissive pixel control eliminating cross-talk in time-multiplexed systems, while DLP dominates large-venue digital cinema projection where lumen output requirements exceed liquid crystal limitations. Medical imaging applications sustain premium pricing through diagnostic-grade calibration protocols that consumer television segments do not require.
FDA 510(k) clearance timelines constrain North American medical 3D display introductions, while REACH compliance in Europe restricts phosphor and rare-earth element sourcing for quantum-dot enhancement films. Japan's METI funds volumetric display research through national technology roadmaps. Stakeholders must monitor whether China's SAMR enforces new GB standards on blue-light exposure before committing regional product certification budgets.
Market Dynamics
OLED self-emissive architectures are compressing cross-talk margins in time-multiplexed stereoscopic systems, forcing legacy LCD manufacturers to retool bonding lines for microlens overlay integration or cede medical imaging premiums.
Growth Catalysts
- South Korean gaming studio procurement cycles:Esports arena deployments in Seoul and Busan accelerate 240Hz refresh hardware replacement schedules. Tournament broadcast specifications now mandate autostereoscopic reference monitors.
- China's MEE dual carbon mandates:Provincial energy intensity targets for panel fabs redirect capital toward low-temperature OLED vapor deposition. GB standards on display power consumption tighten quarterly.
- Japan's METI volumetric roadmap:National funding for light-field modulation research creates domestic supply chain clusters in Osaka and Nagoya precision optics corridors.
Market Restraints
- Rare-earth phosphor cost volatility:Europium and terbium price swings for quantum-dot enhancement films compress margins on premium LED volumes. ECHA REACH authorization delays extend raw material hedging windows.
- TFT backplane supply concentration:Low-temperature polysilicon substrate fabrication clusters in Hsinchu and Gumi create single-point vulnerability for microlens bonding capacity.
- Autostereoscopic viewing angle limitation:Parallax barrier architectures restrict effective depth perception to 15-degree sweet spots, constraining surgical team collaboration in multi-viewer operating theaters.
Strategic Opportunities
- Automotive HUD depth cueing:Windshield-projected volumetric navigation interfaces remain underpenetrated in German premium vehicle segments. NHTSA distraction guidelines currently favor static overlays over dynamic parallax.
- India's PLI scheme for display manufacturing:Subsidized fab construction in Gujarat and Maharashtra invites OLED pilot line joint ventures with domestic telecom equipment distributors.
- Light-field and holographic convergence:Spatial multiplexing algorithms from computational photography are merging with TFT backplane refresh protocols, enabling glasses-free 3D without head-tracking latency.
Industry Challenges
- Calibration technician scarcity:Diagnostic-grade luminance uniformity protocols for surgical monitors require specialized metrology skills concentrated in Japanese and German equipment service networks.
- FDA 510(k) timeline compression:Stereoscopic pathology review systems face 18-month clearance backlogs as radiological device review staff allocation prioritizes AI-enabled diagnostics over display hardware.
- Legacy PACS integration friction:Hospital IT infrastructure built on DICOM 2D viewers resists API retrofitting for real-time 3D slice rendering, delaying procurement committee approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Display Market |
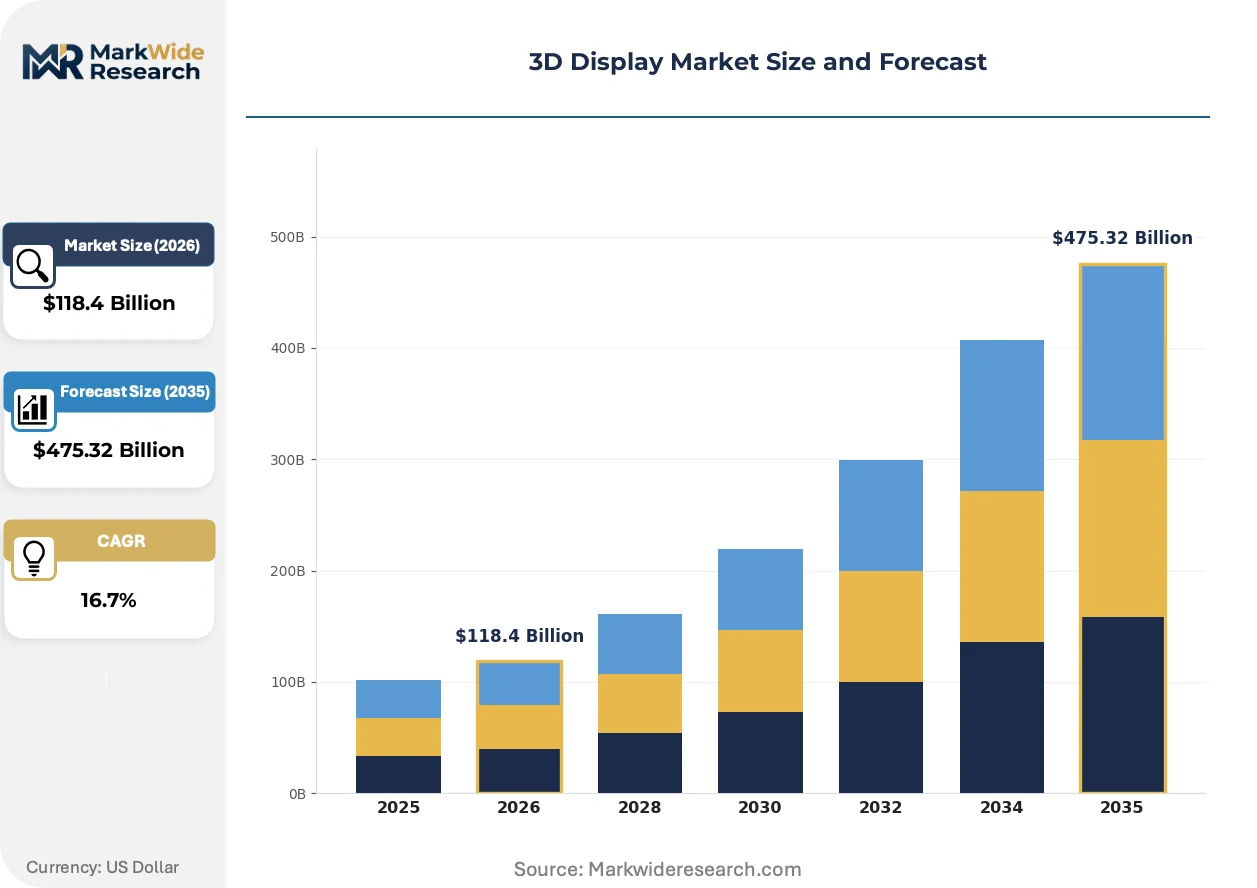
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $475.32 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, OLED, LCD, DLP Application: Television, Gaming, Medical Imaging, Virtual Reality End User: Residential, Commercial, Automotive, Aerospace Distribution Channel: Online Retail, Direct Sales, Retail Stores, Distributors |
| Companies Covered | Samsung Electronics Co. Ltd., LG Electronics Inc., Sony Corporation, Panasonic Corporation, Sharp Corporation, Toshiba Corporation, BOE Technology Group Co. Ltd., Leia Inc., Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Display Market Emerging Trajectories
Light-field modulation hardware is fragmenting incumbent lenticular lens supply chains while computational depth reconstruction from standard camera arrays threatens dedicated 3D capture device categories.
Microlens array bonding to flexible OLED substrates is decomposing the rigid glass-panel supply chain that has dominated volumetric display manufacturing since 2015. Automotive tier-1 suppliers in Stuttgart and Toyota City are sampling curved-dashboard prototypes for 2026 model year integration. The shift collapses tooling amortization schedules for flat-panel fabs while opening pilot line contracts to substrate handlers with roll-to-roll vapor deposition expertise.
EU MDR CE marking requirements for diagnostic displays are tightening luminance stability testing protocols beyond legacy IEC 60601-2-19 frameworks. German notified bodies now mandate 30,000-hour half-life verification for OLED panels used in radiological review. French imaging equipment distributors are stockpiling pre-certified inventory ahead of 2025 technical documentation deadlines, compressing order-to-delivery windows for non-EU manufacturers.
Hospital procurement committees are unbundling after-sales calibration service contracts from hardware purchase agreements. Third-party ISO 17025-accredited metrology labs in Boston and Munich now compete with manufacturer service divisions for multi-year maintenance tenders. The disintermediation is most advanced in Dutch university hospital networks, where centralized biomedical engineering departments negotiate directly with calibration specialists rather than through OEM channel partners.
3D Display Market Segmentation
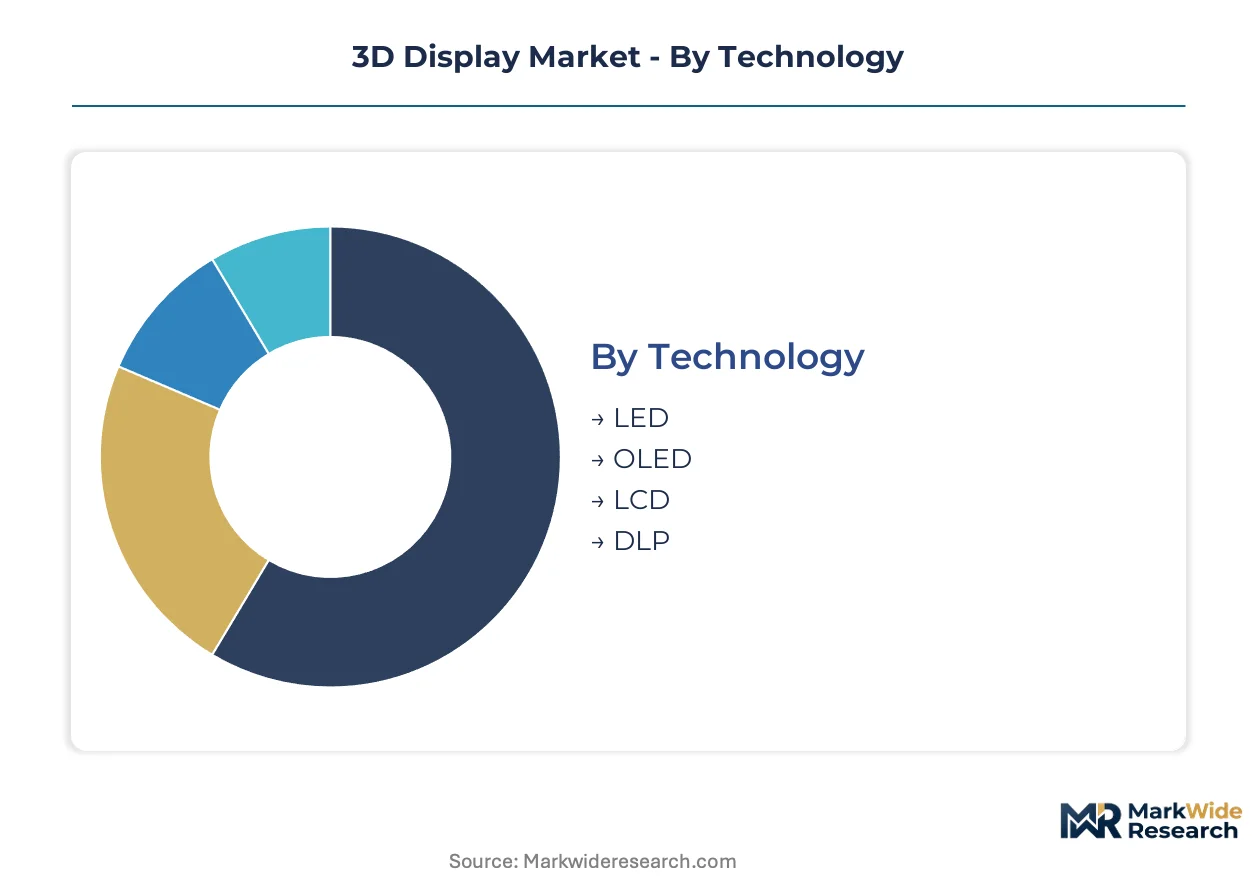
Technology substitution pressures fragment competitive positioning across display architectures. OLED self-emissive pixels displace legacy LCD bonding lines in medical and gaming segments where cross-talk margins determine purchasing decisions.
Technology:
OLED substitution is compressing legacy LCD margins in time-multiplexed stereoscopic systems, forcing retooling decisions at panel fabs serving premium applications.
- OLED:Self-emissive pixel architectures eliminate backlight cross-talk in time-sequential 3D systems. South Korean gaming studios in Seoul and Busan specify OLED reference monitors for tournament broadcast standards, driving procurement cycles.
- LED:Quantum-dot enhancement films with europium and terbium phosphors dominate large-venue digital cinema where lumen output exceeds liquid crystal limitations. Rare-earth cost volatility under ECHA REACH authorization delays compresses margin hedging windows.
- LCD:Microlens overlay bonding to TFT backplanes preserves installed base economics in cost-sensitive residential television segments.
- DLP:Digital micromirror devices sustain dominance in projection applications requiring extreme brightness for auditorium-scale volumetric rendering.
LED anchors the volume base while OLED gains share at the steepest rate.
Application:
Medical imaging commands pricing premiums through diagnostic-grade calibration protocols that consumer segments bypass entirely.
- Medical Imaging:Stereoscopic pathology review systems require FDA 510(k) clearance with 18-month timeline backlogs. Japanese precision imaging clusters in Osaka and Nagoya sustain premium procurement through METI-funded volumetric roadmaps.
- Gaming:Esports arena deployments mandate 240Hz refresh hardware and autostereoscopic reference specifications. South Korean tournament broadcast standards accelerate replacement schedules beyond consumer replacement cycles.
- Television:Residential demand concentrates on glasses-free autostereoscopic panels with parallax barrier architectures, constrained by 15-degree effective viewing angles.
- Virtual Reality:Head-mounted apparatus segments face displacement threat from light-field modulation advancing toward glasses-free spatial multiplexing.
Gaming anchors the volume base while medical imaging expands most quickly.
End User:
Automotive HUD applications remain underpenetrated as NHTSA distraction guidelines favor static overlays over dynamic parallax depth cueing.
- Commercial:Hospital procurement committees unbundle calibration service contracts from hardware purchases, opening third-party ISO 17025-accredited metrology labs in Boston and Munich to multi-year maintenance tenders.
- Residential:Consumer television demand clusters on price-sensitive autostereoscopic panels with limited viewing angle performance.
- Automotive:German premium vehicle segments in Stuttgart sample curved-dashboard volumetric prototypes for windshield-projected navigation interfaces.
- Aerospace:Cockpit head-up display applications require luminance stability verification beyond standard commercial specifications.
Commercial anchors the volume base while automotive climbs the fastest.
Distribution Channel:
Direct sales capture medical imaging premiums through bundled calibration technician deployment that online retail cannot replicate.
- Direct Sales:Manufacturer service divisions compete with third-party metrology labs for Dutch university hospital network tenders where centralized biomedical engineering departments negotiate calibration contracts directly.
- Distributors:French imaging equipment distributors stockpile pre-certified OLED inventory ahead of EU MDR technical documentation deadlines, compressing order-to-delivery windows for non-EU manufacturers.
- Online Retail:Consumer television and gaming hardware moves through platform channels with minimal technical consultation.
- Retail Stores:Big-box electronics chains handle volume residential sales with limited autostereoscopic demonstration capability.
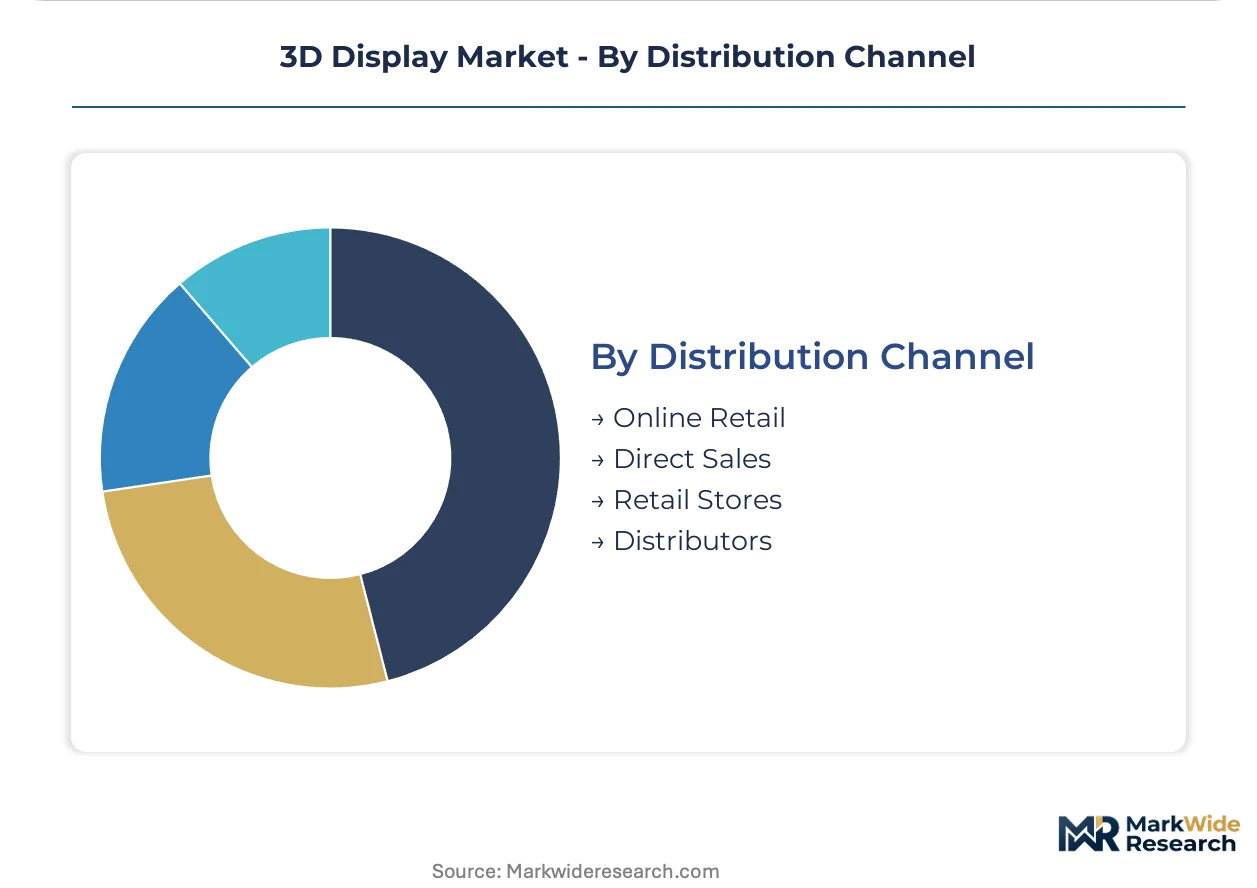
Direct sales anchors the volume base while distributors gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed industrial policies in East Asia are accelerating capital deployment into next-generation display fabrication, while European regulatory tightening on medical device certification is redrawing procurement geography.
China
Provincial energy intensity targets under MEE dual carbon mandates are redirecting panel fab investment toward low-temperature OLED vapor deposition. GB standards on display power consumption tighten quarterly, pressuring legacy LCD lines. Yangtze River Delta clusters in Suzhou and Hefei host government-subsidized pilot lines for flexible substrate handlers.
South Korea
Esports arena deployments in Seoul and Busan are accelerating 240Hz refresh hardware replacement schedules beyond consumer cycles. Tournament broadcast specifications now mandate autostereoscopic reference monitors for production facilities. Gumi and Hsinchu corridor fabs concentrate low-temperature polysilicon substrate capacity for microlens bonding.
Japan
METI national technology roadmaps are funding volumetric display research through precision optics corridors in Osaka and Nagoya. Diagnostic-grade calibration protocols for surgical monitors sustain premium procurement pricing that consumer segments cannot match. Japanese precision medical imaging clusters require 30,000-hour half-life verification under tightened EU MDR technical documentation.
United States
FDA 510(k) clearance timelines constrain stereoscopic pathology review system introductions with 18-month backlogs as radiological device review prioritizes AI-enabled diagnostics. Third-party ISO 17025-accredited metrology labs in Boston now compete with manufacturer service divisions for multi-year hospital maintenance tenders. Hospital procurement committees resist API retrofitting for real-time 3D slice rendering.
Germany
EU MDR CE marking requirements are tightening luminance stability testing protocols beyond legacy IEC frameworks for diagnostic displays. German notified bodies mandate extended half-life verification for OLED panels in radiological review. Stuttgart automotive tier-1 suppliers are sampling curved-dashboard volumetric prototypes for windshield-projected navigation interfaces.
3D Display Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology integration depth. The vendor base stratifies between scale-driven panel fabricators and application-specific system integrators. Three archetypes dominate: captive semiconductor fabricators controlling backlight driver supply, government-subsidized national champions expanding OLED pilot capacity, and precision optics specialists leveraging lenticular lens IP. Competitive moves center on backward integration into driver IC fabrication and geographic expansion through joint ventures in subsidized manufacturing zones.
Among East Asian electronics conglomerates, Samsung Electronics Co. Ltd. and LG Electronics Inc. exemplify scale-driven archetypes with captive semiconductor fabrication capabilities, while Sony Corporation occupies a position representing premium-tier differentiation through proprietary optical architectures. BOE Technology Group Co. Ltd. anchors the government-subsidized expansion vector with state-backed OLED pilot line investment.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| LG Electronics Inc. |
| Sony Corporation |
| Panasonic Corporation |
| Sharp Corporation |
| Toshiba Corporation |
| BOE Technology Group Co. Ltd. |
| Leia Inc. |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for rare-earth phosphors lock in quantum-dot film supply and stabilize input cost visibility for LED volume manufacturers facing europium and terbium price swings. These arrangements concentrate pricing power with vertically integrated panel fabricators in South Korea and China while squeezing margin buffers for smaller system integrators dependent on spot-market sourcing.
Pricing Analysis
Certification level creates the primary spread across the 3D display market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical monitors from consumer autostereoscopic panels and entry-level gaming hardware. Pricing pressure stems from China's GB standards tightening display power consumption thresholds quarterly, forcing legacy LCD lines into accelerated depreciation. Hospital procurement committees demonstrate lowest price sensitivity due to unbundled calibration service contracts, while residential television buyers drive aggressive cost compression through platform retail channels.
Supply Chain Analysis
Low-temperature polysilicon substrate fabrication in Hsinchu and Gumi represents the critical chokepoint for microlens bonding capacity across time-multiplexed stereoscopic systems. The supply chain draws from South Korean and Japanese precision optics corridors for lenticular lens arrays, Chinese Yangtze River Delta clusters for TFT backplanes, and German notified bodies for EU MDR certification. Single-source vulnerability concentrates in the Hsinchu-Gumi corridor where substrate fabrication capacity feeds multiple downstream bonding lines. Distribution runs through direct sales for medical imaging premiums and platform retail for consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are multiplying as hospital procurement committees unbundle hardware from calibration services, creating niches for third-party metrology specialists and disrupting integrated OEM channel structures.
For Market Incumbents: Secure captive driver IC fabrication capacity to defend backlight control in LED volume lines against Chinese government-subsidized OLED expansion. Backward integration into rare-earth phosphor hedging instruments mitigates REACH authorization delay risks. Reinforce direct sales relationships with Dutch university hospital networks where centralized biomedical engineering departments negotiate calibration contracts independently of distributor intermediaries. For New Entrants and Emerging Players: Differentiate on light-field modulation algorithms that eliminate parallax barrier viewing angle constraints in surgical collaboration environments. Target India's PLI-subsidized fab zones in Gujarat and Maharashtra for OLED pilot line joint ventures with domestic telecom distributors. Pursue ISO 17025 accreditation for metrology services to capture unbundled hospital maintenance tenders in Boston and Munich corridors. For Investors and Strategic Acquirers: Capital is best deployed toward precision optics specialists with proprietary lenticular lens IP and established relationships with Japanese METI-funded research corridors. Long-term viability hinges on convergence between computational depth reconstruction and TFT backplane refresh protocols. Watch for SAMR enforcement of new GB standards on blue-light exposure as an inflection signal for regional certification budget commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Fabrication | Samsung Electronics leverages captive semiconductor capacity to control LED backlight supply for volume gaming lines. |
| Joint Venture in PLI-Subsidized Manufacturing Zones | BOE Technology Group anchors mainland China expansion with government-backed OLED pilot line investment in Suzhou clusters. |
| ISO 17025 Metrology Lab Accreditation | Third-party calibration specialists in Boston compete with OEM service divisions for Dutch hospital network tenders. |
| EU MDR Pre-Certification Inventory Stockpiling | French imaging equipment distributors compress order-to-delivery windows ahead of tightened luminance stability deadlines. |
| Light-Field Modulation R&D Partnership | Sony differentiates broadcast reference monitors through proprietary lenticular lens arrays bonded to self-emissive substrates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation filings, METI-funded research corridor disclosures, and customs records for rare-earth phosphor trade flows. Interviews with display panel procurement managers, hospital biomedical engineering directors, gaming studio technical directors, and automotive HUD platform engineers informed demand-side calibration. Bottom-up triangulation across technology substitution rates and top-down validation against fab capacity announcements anchored volume estimates.
Segmentation dimensions modeled include display architecture (OLED, LED, LCD, DLP), application vertical (medical imaging, gaming, television, virtual reality), end-user category (commercial, residential, automotive, aerospace), and distribution channel structure. CAGRs were derived from installation base replacement cycles, regulatory compliance timeline compressions, and government subsidy disbursement schedules across the projection horizon. Forecast inputs incorporated esports arena deployment pipelines in Seoul and Busan, MEE dual carbon mandate enforcement trajectories, and NHTSA distraction guideline revision probabilities for automotive HUD penetration.
The analysis sits within stated boundaries; outcomes outside sustained government subsidy flows for OLED pilot lines, stable rare-earth phosphor authorization timelines under ECHA REACH, and continued METI volumetric research funding would require recalibration. Practitioners should keep alternative scenarios live as SAMR regulatory enforcement patterns and FDA radiological device review staff allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
QLED Display Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Field Emission Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Global Wearable Display Market
Display Technologies
Holographic Display Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
IGZO Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Smart Screen Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
Smartphone Display Market
Display Technologies
Global Industrial Display System Market