
 Global Ultra Wide Temperature TFT Display Market | 2026-2036
Global Ultra Wide Temperature TFT Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra Wide Temperature TFT Display Market Intelligence
The European Union's push for circular economy principles within the automotive sector, mandating longer product lifecycles and material traceability, is expanding the addressable market for durable electronic components. Samsung Display Co. Ltd. leverages its significant R&D in OLED technology to meet these stringent performance criteria. Concurrently, BOE Technology Group Co. Ltd. competes on manufacturing scale to supply large-volume orders for industrial and automotive clients. AU Optronics Corporation specializes in advanced display solutions for niche, high-margin applications.
An ultra wide temperature TFT display is a liquid crystal or OLED panel engineered to operate reliably across extreme thermal ranges, often from -40°C to over 85°C. This performance is achieved through specialized liquid crystal formulations and robust electronic components, ensuring consistent functionality for critical systems. Within applications, automotive displays constitute the largest segment due to vehicle electrification and cockpit digitalization. In-Plane Switching (IPS) technology is gaining significant traction over traditional options, offering superior color fidelity and wider viewing angles required in modern vehicle interiors.
Regulatory compliance is a critical market boundary, shaped by bodies like the US National Highway Traffic Safety Administration (NHTSA) which sets standards for in-vehicle display distraction. Concurrently, CE marking in Europe and GB standards in China dictate electronic safety and material composition for all imported display modules. Navigating these disparate regional requirements while managing production costs presents the central strategic challenge for component manufacturers.
Market Dynamics
The central tension shaping the market is the automotive industry's demand for consumer-grade display aesthetics, like high resolution and vibrant color, combined with industrial-grade resilience to extreme temperatures, vibration, and long operational lifecycles without performance degradation.
Growth Catalysts
- Automotive Cockpit Digitalization:The transition to all-digital instrument clusters and large central information displays in vehicles, particularly in Germany and Japan, necessitates displays that function flawlessly from cold starts in winter to high heat in direct sunlight.
- EU Circular Economy Mandates:European Union policies promoting longer product lifecycles and material traceability for electronics are creating demand for durable components, favoring ultra wide temperature displays that can extend the operational life of automotive and industrial systems.
- IPS Technology Adoption:The proliferation of In-Plane Switching (IPS) technology delivers the superior viewing angles and color fidelity required for modern user interfaces in vehicles and industrial machinery, driving replacement of older display technologies.
Market Restraints
- Specialized Material Costs:The advanced liquid crystal formulations and robust electronic components required to achieve wide temperature operation carry a significant cost premium, limiting adoption in price-sensitive industrial applications.
- Regulatory Fragmentation:Manufacturers face complexity and cost in certifying products for disparate regional standards, including NHTSA guidelines in the United States, CE marking in Europe, and GB standards in China.
- Performance Trade-offs:Engineering for extreme temperature stability can sometimes compromise other display metrics, such as response time or power consumption, creating design challenges for specific applications like high-frame-rate video.
Strategic Opportunities
- Aerospace and Defense Applications:Untapped opportunities exist in avionics and military ground vehicle displays, where extreme reliability and operation across wide thermal ranges are non-negotiable performance requirements and budgets are less constrained.
- Industrial Automation in India:India's expanding manufacturing sector and investments in industrial automation present a new growth frontier for durable human-machine interface (HMI) panels that can withstand harsh factory environments.
- Integration with Haptic Feedback:Combining ultra wide temperature displays with advanced haptic feedback technology creates opportunities for more intuitive and safer user interfaces in automotive and industrial control systems, especially in noisy environments.
Industry Challenges
- Automotive Certification Timelines:The lengthy and rigorous testing process to achieve automotive-grade qualifications, such as AEC-Q100 for components, presents a significant time-to-market barrier for new display technologies and suppliers.
- Supply Chain Concentration:The global supply of specialized liquid crystal materials and high-reliability driver ICs is concentrated among a small number of suppliers, creating potential bottlenecks and pricing volatility for display manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra Wide Temperature TFT Display Market |
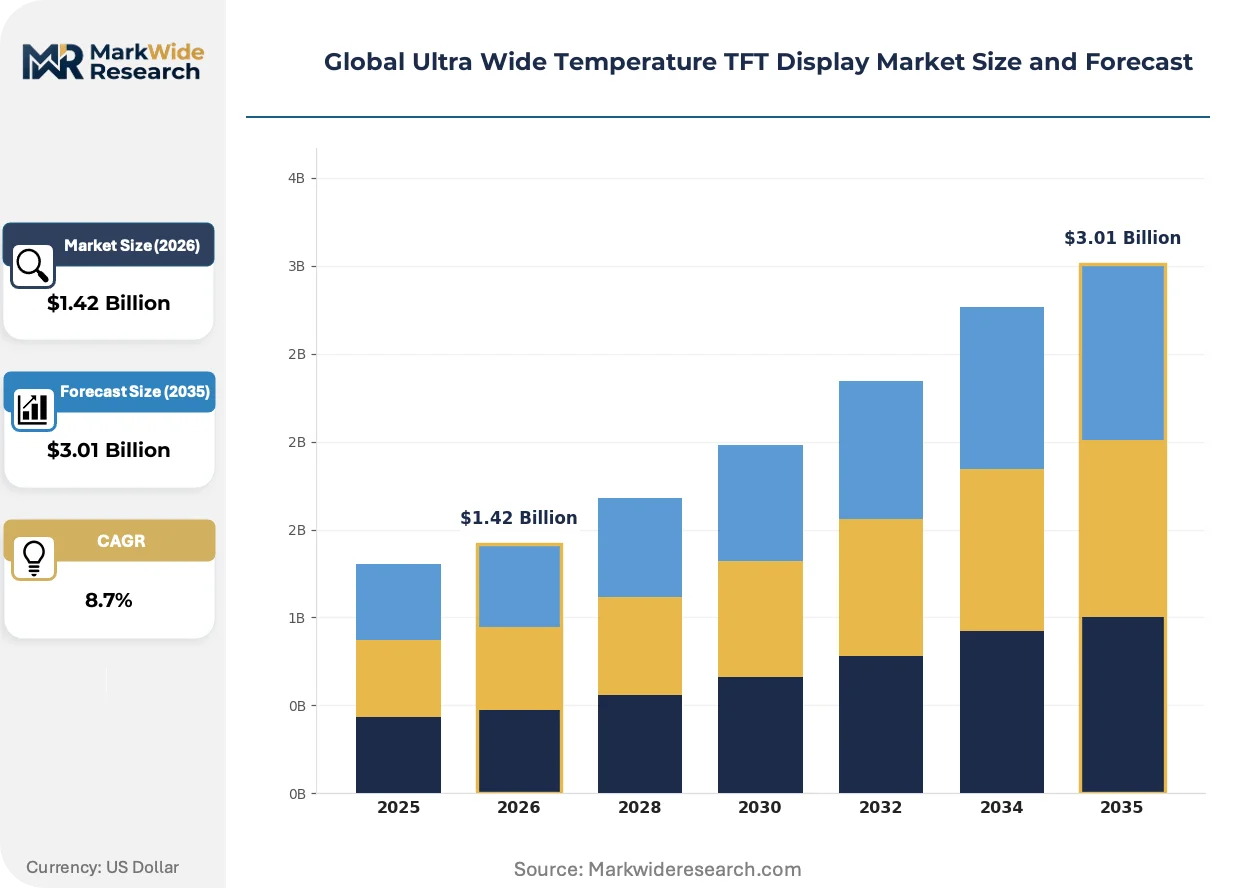
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, AMOLED Application: Automotive Displays, Industrial Controls, Medical Equipment, Consumer Electronics Technology: Thin-Film Transistor, Organic Thin-Film Transistor, In-Plane Switching, Vertical Alignment End User: OEMs, Tier-1 Suppliers, Retailers, Aftermarket Providers |
| Companies Covered | LG Display Co. Ltd., Samsung Display Co. Ltd., BOE Technology Group Co. Ltd., Innolux Corporation, AU Optronics Corporation, Japan Display Inc., Sharp Corporation, Tianma Microelectronics Co. Ltd., Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra Wide Temperature TFT Display Market Strategic Shifts & Innovations
The market is defined by a convergence of capabilities, where the durability demanded by industrial applications is merging with the visual performance expected from consumer electronics. This fusion is pushing innovation in materials science and system-level integration.
In-Plane Switching (IPS) technology offers vastly superior color consistency and wider viewing angles compared to older Twisted Nematic (TN) panels. The automotive sector is rapidly adopting IPS for primary flight displays in digital cockpits and for passenger-facing infotainment systems. This adoption is rewriting the baseline for acceptable in-vehicle display performance, making legacy technologies uncompetitive for new vehicle platforms.
Europe's Corporate Sustainability Reporting Directive (CSRD) compels manufacturers to provide detailed lifecycle and material traceability data. This regulation forces display makers to map their entire supply chain for key inputs like liquid crystals, polarizers, and backlights. Consequently, automotive and industrial OEMs are prioritizing suppliers who can deliver comprehensive compliance documentation to de-risk their own reporting obligations.
A notable shift from component-level procurement to system-level validation is underway. Automotive and industrial customers increasingly demand pre-integrated and pre-validated modules combining the display, touch controller, and cover glass, rather than sourcing individual parts. This disrupts the model for component-only suppliers and favors vendors with system integration capabilities, a trend most visible in Germany's automotive sector.
Global Ultra Wide Temperature TFT Display Market Segmentation
Understanding the distinct segments within the global ultra wide temperature TFT display market reveals the varied performance demands and procurement pathways. This granular view helps manufacturers align product development with specific application requirements and navigate diverse regulatory landscapes. Segmentation highlights where innovation is concentrated and where established technologies maintain market dominance.
Product Type:
The product type segmentation highlights the ongoing tension between high-volume, cost-effective solutions and premium, advanced display technologies.
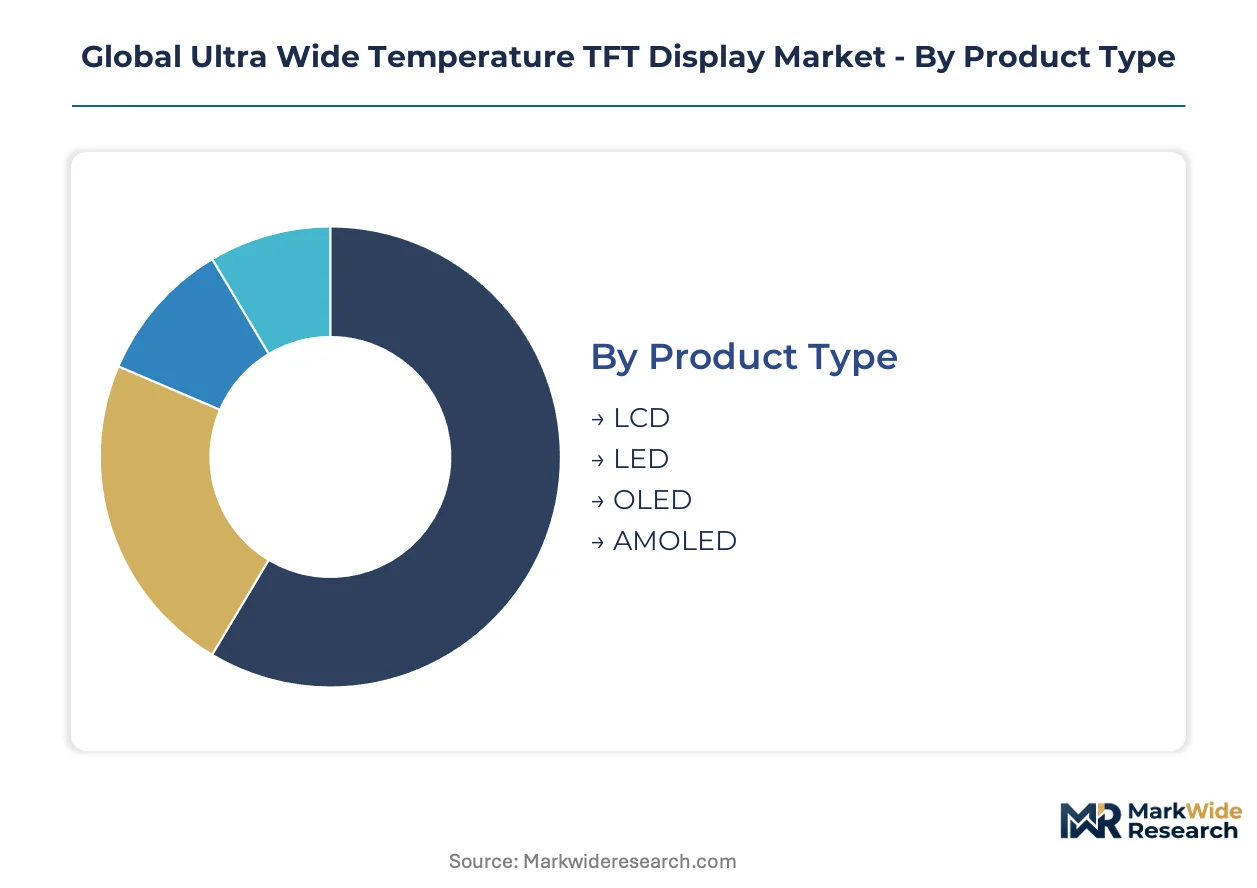
- OLED:Organic Light-Emitting Diode panels provide superior contrast ratios and faster response times, utilizing self-emissive pixels for vibrant imagery. Demand concentrates in high-end automotive cockpits and premium consumer devices, driven by aesthetic appeal and energy efficiency.
- LCD:Liquid Crystal Displays rely on a backlight and polarizing filters to control light transmission, offering a mature and cost-effective display solution. This technology remains a foundational choice for industrial control panels and medical equipment requiring robust, proven performance.
- AMOLED:Active Matrix Organic Light-Emitting Diode technology enhances OLED performance with individual pixel control, enabling thinner profiles and greater power efficiency.
- LED:Light Emitting Diode technology, primarily used as backlights for LCDs or in large format displays, provides bright illumination and extended lifespan.
Today's leader: LCD. Tomorrow's challenger: OLED.
Application:
This application-centric view illustrates how diverse end-use environments shape display specifications and market penetration strategies.
- Automotive Displays:These panels are engineered for extreme durability, operating reliably across wide temperature ranges and high vibration conditions within vehicle interiors. Demand is particularly strong in Germany and Japan, driven by the digitalization of cockpits and advanced driver-assistance systems.
- Industrial Controls:Displays for industrial applications require robust construction and long-term reliability to withstand harsh factory environments and continuous operation cycles. Manufacturers prioritize displays with extended lifespans and resistance to contaminants for human-machine interface panels.
- Medical Equipment:Displays in medical devices demand high resolution, precise color reproduction, and stringent regulatory compliance for diagnostic and monitoring functions.
- Consumer Electronics:This segment encompasses displays for smartphones, tablets, and laptops, where visual quality, slimness, and energy efficiency are primary design considerations.
The segment with the steepest expansion trajectory is Automotive Displays, while Industrial Controls provides foundational stability.
Technology:
The technology segmentation reflects the evolution from established display architectures to more advanced solutions offering enhanced visual performance.
- In-Plane Switching:IPS technology arranges liquid crystals horizontally, providing superior color fidelity and wide viewing angles critical for modern automotive cockpits and premium industrial HMI. This technology is rapidly displacing older panel types in new vehicle platforms due to user experience demands.
- Thin-Film Transistor:TFT technology forms the fundamental switching element for individual pixels in LCDs, enabling active matrix addressing for high-resolution displays. It remains the bedrock of most liquid crystal display manufacturing due to its mature process and cost efficiency.
- Organic Thin-Film Transistor:OTFTs are an emerging technology for flexible and transparent displays, offering potential for novel form factors in specialized applications.
- Vertical Alignment:VA technology provides high contrast ratios and deep blacks by aligning liquid crystals vertically, finding niche applications where contrast is prioritized over viewing angle.
Innovation in In-Plane Switching is driving new capabilities, while Thin-Film Transistor continues to refine established performance.
End User:
The end-user segmentation outlines the primary channels through which ultra wide temperature displays reach their final applications, influencing sales and distribution strategies.
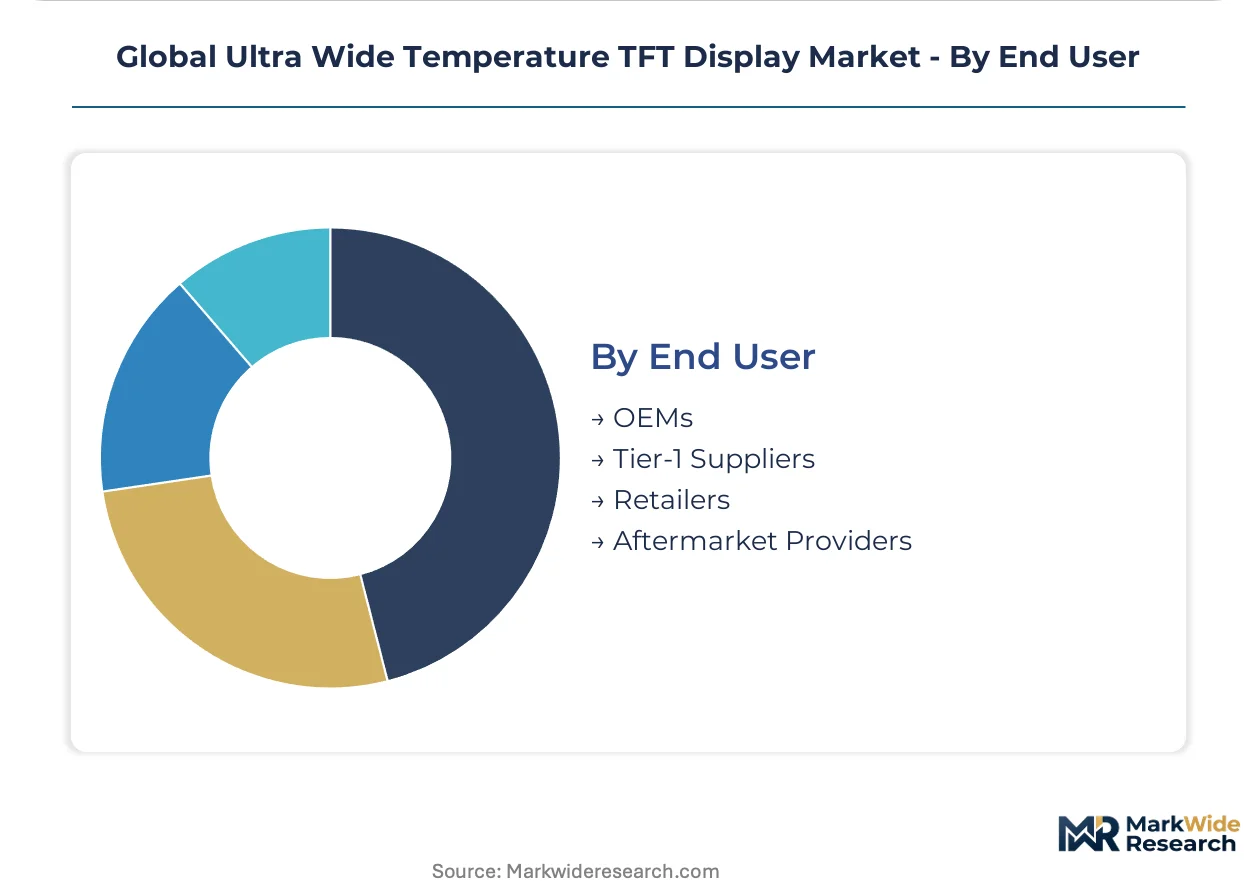
- OEMs:Original Equipment Manufacturers directly integrate displays into their final products, such as vehicles, industrial machinery, or medical devices. These customers typically require extensive customization and rigorous qualification processes for display modules.
- Tier-1 Suppliers:These companies assemble subsystems for OEMs, often integrating displays with other components like touch sensors and control boards into complete modules. Tier-1s require displays that meet specific integration standards and robust performance criteria.
- Retailers:Retailers primarily sell consumer-grade displays or smaller industrial units for direct purchase, often focusing on off-the-shelf solutions with less customization.
- Aftermarket Providers:This segment supplies replacement displays and upgrade kits for existing equipment, prioritizing compatibility and reliability for repair and enhancement services.
The direct procurement model of OEMs contrasts with the distribution network leveraged by Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ultra wide temperature TFT display industry historically scaled its production and innovation in key automotive and electronics manufacturing hubs. Initial demand for rugged displays emerged from critical applications in the United States, Germany, and Japan, establishing foundational market requirements. These regions continue to drive advancements in display durability and performance across diverse sectors.
United States
Demand for ultra wide temperature displays in the United States stems from advanced driver-assistance systems (ADAS) and defense applications. The US National Highway Traffic Safety Administration (NHTSA) sets crucial standards for in-vehicle display distraction, influencing design. Major automotive R&D centers in Michigan and technology innovation hubs in California drive adoption of advanced display solutions.
Germany
Germany's automotive sector, a global leader in premium vehicle production, is a primary driver for durable display technology. European Union policies, such as CE marking and circular economy mandates, influence product design and material traceability. The automotive clusters around Stuttgart and Munich are central to the development and integration of these specialized displays.
Japan
Japanese automotive manufacturers and industrial machinery producers exhibit strong demand for high-reliability displays capable of extreme temperature operation. Adherence to stringent JIS standards for quality and performance is a baseline requirement for components. Major electronics and automotive production zones in the Kanto region and around Nagoya consistently integrate advanced TFT displays.
China
China's rapidly expanding automotive market and significant investments in industrial automation fuel a substantial need for robust display solutions. GB standards dictate electronic safety and material composition for all display modules used within the country. Large-scale electronics manufacturing in the Yangtze River Delta and technology hubs like Shenzhen contribute significantly to production and domestic consumption.
India
India's growing manufacturing sector and its push for industrial automation present a significant opportunity for durable human-machine interface (HMI) panels. Government initiatives, such as the Production Linked Incentive (PLI) scheme, support domestic electronics manufacturing. Industrial corridors in Maharashtra and Karnataka are increasingly adopting advanced display technologies for factory environments.
Global Ultra Wide Temperature TFT Display Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the ultra wide temperature TFT display market, creating a complex competitive environment. The market exhibits a tiered structure, with a few large integrated manufacturers dominating core technology and scale production. Strategic archetypes include diversified display giants, specialized industrial component suppliers, and niche innovators. Companies primarily focus on capacity expansion and strategic partnerships to strengthen their market positions.
Within the diversified display giant archetype, Samsung Display Co. Ltd. leverages its significant R&D in advanced display technologies, especially OLED, to meet stringent performance criteria. BOE Technology Group Co. Ltd. exemplifies a scale-driven player, competing on manufacturing capacity to supply large-volume orders for industrial and automotive clients. AU Optronics Corporation occupies a position as a specialist in advanced display solutions, targeting niche, high-margin applications that demand specific performance characteristics.
| Leading Market Players |
|---|
| LG Display Co. Ltd. |
| Samsung Display Co. Ltd. |
| BOE Technology Group Co. Ltd. |
| Innolux Corporation |
| AU Optronics Corporation |
| Japan Display Inc. |
| Sharp Corporation |
| Tianma Microelectronics Co. Ltd. |
| Mitsubishi Electric Corporation |
| Others |
Cost & Logistics Intelligence
Specialized liquid crystal formulations and robust electronic components dictate the cost structure, translating into a premium pricing tier for ultra wide temperature TFT displays. This cost directly impacts module pricing for automotive and industrial OEMs.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for ultra wide temperature displays, particularly for automotive and industrial OEMs. Price differentiation stems from rigorous certification levels like AEC-Q100 and the degree of customization required for specific applications. Pricing pressure stems from the high material costs of specialized liquid crystal formulations and robust electronic components. Industrial applications exhibit higher price sensitivity, while aerospace and defense sectors prioritize performance over cost.
Supply Chain Analysis
Logistics and freight costs influence the final price of specialized display components, particularly for intercontinental shipments. Geographic supply of specialized liquid crystal materials and high-reliability driver ICs concentrates in Japan, South Korea, and China. This concentration creates a single-source vulnerability for display manufacturers, impacting production stability. Distribution runs through direct channels to automotive OEMs and Tier-1 suppliers, who demand pre-validated modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultra wide temperature TFT display market acts as a regulatory compounder, with EU Circular Economy mandates driving demand for durable electronic components. These policies necessitate longer product lifecycles and comprehensive material traceability.
For Market Incumbents: Lock in long-term supply agreements with key automotive OEMs and Tier-1 suppliers to secure volume and reduce market entry for niche innovators. Deepen R&D investment in advanced liquid crystal materials and robust electronic components to meet evolving performance criteria, particularly for automotive-grade qualifications like AEC-Q100. This strategy helps mitigate threats from new entrants and stringent certification timelines.
For New Entrants and Emerging Players: Enter via niche, high-margin applications such as aerospace and defense, where reliability commands a premium and budgets are less constrained. Target India's expanding manufacturing sector with durable human-machine interface panels designed for harsh factory environments. A specific go-to-market angle involves offering pre-validated modules integrated with advanced haptic feedback for intuitive industrial controls.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized material science and system-level integration capabilities are scarce, driving M&A activity. The market exhibits strong long-term viability over the next decade due to sustained demand for durable, high-performance components across automotive and industrial sectors. Acquire specialized industrial component suppliers possessing strong intellectual property in advanced material formulations. A signal to watch is increased M&A activity among Tier-1 automotive suppliers seeking to secure display technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Regions | Expands BOE Technology Group's ability to meet large-volume orders from automotive clients in China. |
| R&D in Advanced Liquid Crystal Materials | Samsung Display Co. Ltd. can extend operational temperature ranges and enhance display performance for ADAS. |
| System-Level Integration Partnerships | Enables AU Optronics Corporation to deliver pre-validated display modules to German automotive OEMs. |
| Certification for Aerospace and Defense | Unlocks new revenue streams by meeting non-negotiable reliability requirements for avionics applications. |
| Haptic Feedback Technology Integration | Creates intuitive user interfaces for industrial control systems, enhancing safety in noisy environments. |
Research Approach
Coverage spans the United States, Germany, Japan, and China, with primary inputs from each region informing market dynamics. This analysis combines insights from interviews with OEM platform engineers, Tier-1 procurement leads, and material science R&D directors. Secondary validation draws from regulatory documents like NHTSA guidelines, EU CE marking, and JIS standards, alongside vehicle production databases. A robust bottom-up and top-down triangulation approach ensured data consistency.
Granularity extends to product type, application, technology, end user, and regional regulatory compliance, modeled across the analysis window. The analytical framework integrated historical performance data with future projections for each segment. Compound annual growth rates were derived from a comprehensive assessment of these trends and market drivers. Key industry-specific forecast inputs included vehicle electrification rates and industrial automation investment.
Inputs from major display manufacturers and automotive OEMs were available through the study window; gaps in emerging market data introduce uncertainty bands. Forecasts reflect assumptions on regulatory evolution and technological adoption; supply chain concentration and rapid shifts could revise projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
4K VR Displays Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
OLED Panel Market
Display Technologies
Portable Video Wall Market
Display Technologies
Video Wall Display Market
Display Technologies
3D Display Market
Display Technologies
Portable Projector Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Commercial Display Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Computer Monitor Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Electroluminescent Display Market