
 Holographic Display Market | 2026-2036
Holographic Display Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Display Market Intelligence
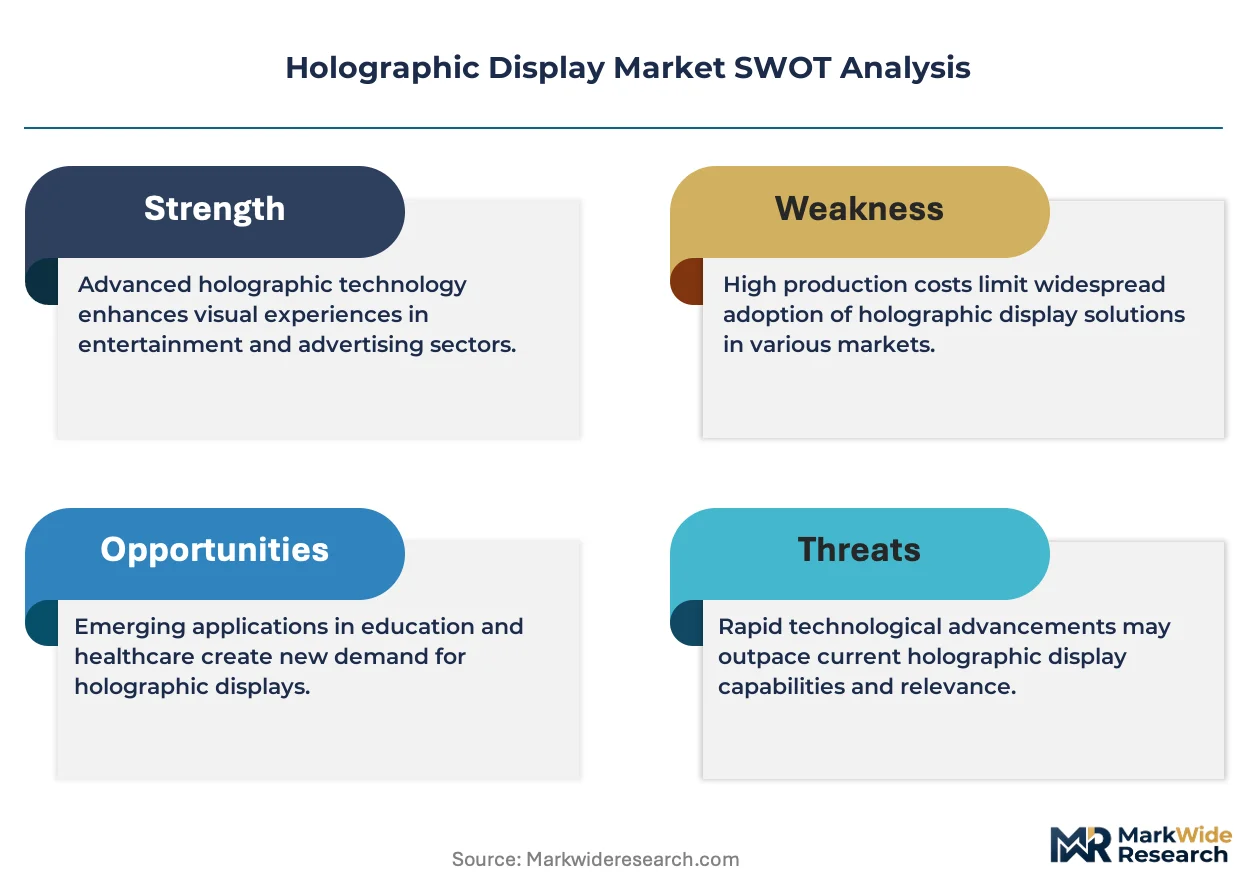
Software-defined light-field calibration is rebalancing how holographic display vendors monetize hardware deployments. Leia Inc. leverages mobile-integrated diffractive backlighting to sustain presence in consumer electronics channels. Light Field Lab, Inc. anchors its position through large-format direct-view panels designed for entertainment venues and brand installations. HOLOCO GmbH specializes in compact holographic modules for automotive head-up displays, competing against established LCD projection suppliers.
A holographic display renders three-dimensional imagery through coherent light interference patterns recorded on photosensitive media or generated via spatial light modulators, typically operating at refresh rates exceeding 60 Hz to eliminate perceptible flicker in volumetric scenes. Its primary commercial purpose spans medical visualization, automotive instrument clusters, and immersive advertising where depth cues reduce operator error and elevate engagement. Laser-based systems occupy the premium tier due to speckle-controlled coherence and extended color gamut, while MicroLED architectures represent the fastest-growing product category as epitaxial lift-off yields improve and pixel pitch shrinks below 10 micrometers. Medical Imaging and Automotive Displays capture diverging margin pools, with surgical navigation demanding sub-millimeter spatial accuracy and infotainment applications prioritizing field-of-view expansion.
The FDA regulates holographic medical devices under 510(k) premarket notification and De Novo classification pathways, constraining software validation requirements for diagnostic use. The FCC governs electromagnetic emissions from laser-based and MicroLED holographic systems, with SAR testing protocols extending into near-eye display categories. The EU AI Act and MDR framework impose conformity assessment obligations on holographic surgical guides incorporating machine-learning overlays. Stakeholders must monitor evolving interoperability standards between light-field render engines and existing PACS infrastructure to secure hospital procurement contracts.
Market Dynamics
Software-defined light-field calibration is rebalancing vendor monetization models away from hardware-only sales toward recurring software licensing, while FDA 510(k) streamlining accelerates medical device commercial entry and concentrates procurement among academic medical centers with integrated surgical navigation budgets.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process for holographic medical devices compresses time-to-market for surgical planning systems, enabling faster hospital procurement cycles across United States academic networks.
- Epitaxial Lift-Off Yields:Improved manufacturing processes for MicroLED architectures reduce pixel pitch below 10 micrometers, expanding addressable applications in automotive head-up displays and compact medical visualization modules.
- Defense Contractor Pilots:United States military training programs are validating light-field displays for command-and-control applications, creating reference deployments that cascade into civilian simulation markets.
Market Restraints
- Laser Component Supply Concentration:Speckle-controlled coherent light sources for premium-tier holographic systems depend on concentrated specialty laser manufacturing in Germany and Japan, exposing buyers to single-source vulnerability.
- Input Cost Volatility:Indium and gallium prices for MicroLED epitaxial wafers fluctuate with rare earth mining output from China, compressing gross margins on high-volume consumer electronics integrations.
- EU MDR Conformity Burden:The Medical Device Regulation framework imposes extended clinical validation timelines on holographic surgical guides with machine-learning overlays, delaying European commercialization relative to United States entry.
Strategic Opportunities
- Underpenetrated Automotive HUD Channel:Compact holographic modules remain sub-five-percent penetrated in premium vehicle segments outside Germany and Japan, creating whitespace for suppliers competing against established LCD projection incumbents.
- EU AI Act Tailwind:Conformity assessment obligations for AI-enabled surgical visualization create first-mover advantage for vendors pre-certifying light-field render engines under the bloc's risk-based classification system.
- Spatial Light Modulator Convergence:Integration of liquid-crystal-on-silicon modulators with diffractive optical elements enables new form factors in near-eye displays, opening enterprise training applications previously served by VR headsets.
Industry Challenges
- Optical Engineering Talent Scarcity:The intersection of wave optics, semiconductor fabrication, and real-time rendering algorithms requires specialized skill sets concentrated in Boston, Stuttgart, and Tokyo metropolitan clusters.
- PACS Interoperability Certification:Hospital procurement contracts demand seamless integration with existing picture archiving and communication infrastructure, requiring multi-year validation cycles with major radiology equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic Display Market |
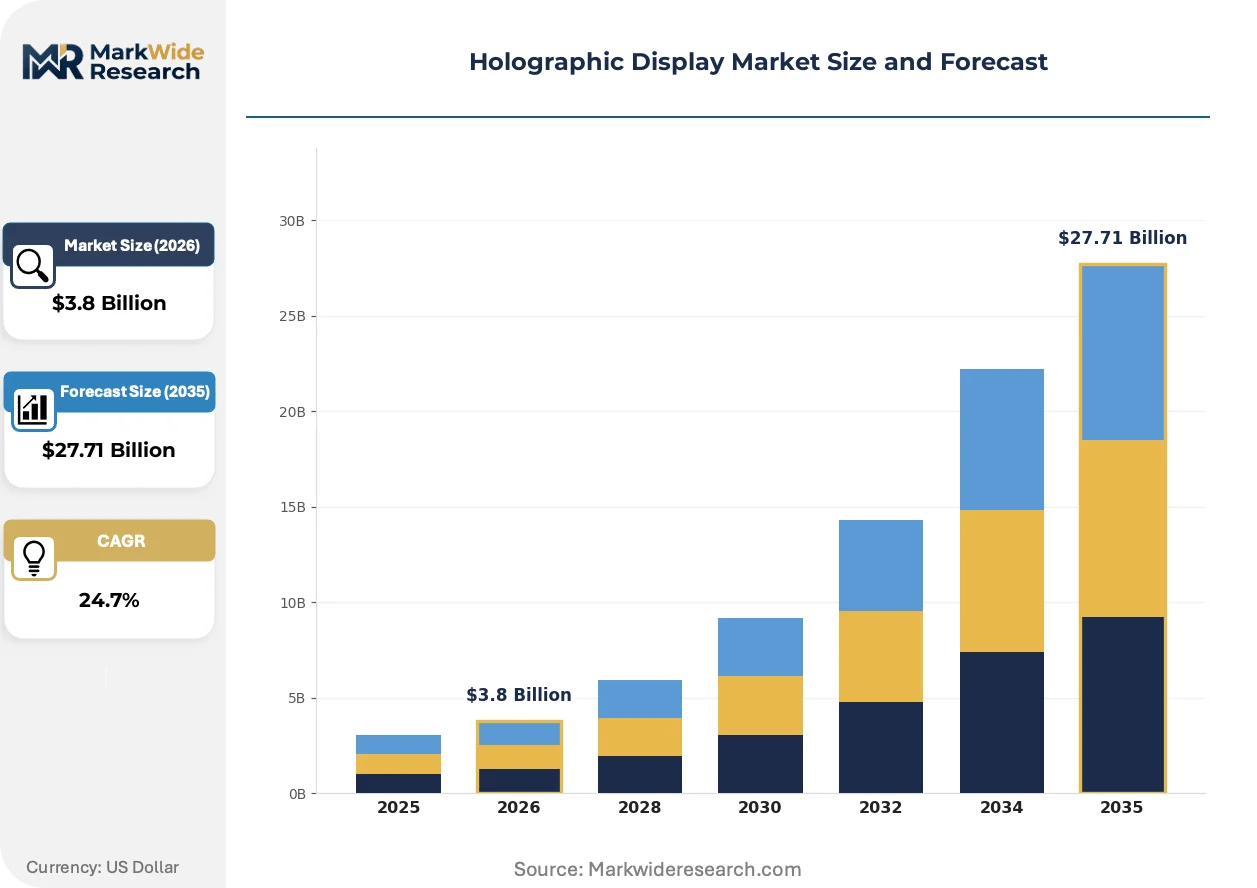
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.71 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser-based, MicroLED, LCD, OLED Application: Telecommunications, Automotive Displays, Medical Imaging, Advertising End User: Retail, Education, Healthcare, Entertainment Technology: Light Field, Holography, Augmented Reality, Virtual Reality |
| Companies Covered | Axiom Holographics, Leia Inc., HOLOCO GmbH, RealFiction Holding AB, Light Field Lab, Inc., Shenzhen Muxwave Technology Co., Ltd, Looking Glass Factory Inc., Holoxica Limited, Fursol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Display Market Strategic Shifts & Innovations
Light-field rendering engines are converging with established medical imaging workflows, while regulatory pre-certification programs and defense validation protocols reshape competitive entry barriers across holographic display categories.
MicroLED architectures are expanding into surgical navigation systems through sub-millimeter spatial accuracy enabled by shrinking pixel pitch. Academic medical centers in the United States are piloting these panels for radiology review and pre-operative planning at accelerating procurement velocities. This technology is expanding into applications previously reserved for laser-based volumetric systems, compressing the premium-tier addressable market while broadening total accessible volume.
The EU AI Act's risk-based classification system for machine-learning-enabled medical devices is mandating conformity assessment procedures for holographic surgical guides with diagnostic overlays. Manufacturers must demonstrate algorithmic transparency and clinical validation across intended use populations before CE marking authorization. European hospital procurement committees are now prioritizing pre-certified vendors, advantaging early movers with established quality management systems.
Defense training budgets are consolidating light-field display procurement through multi-year installation contracts at United States command centers and simulation facilities. Traditional projector-based immersive systems face displacement as speckle-controlled holographic panels demonstrate superior depth cue fidelity for tactical rehearsal. This buyer concentration is most visible in Virginia and California defense corridors, where prime contractors are integrating direct-view holographic walls into next-generation training infrastructure.
Holographic Display Market Segmentation
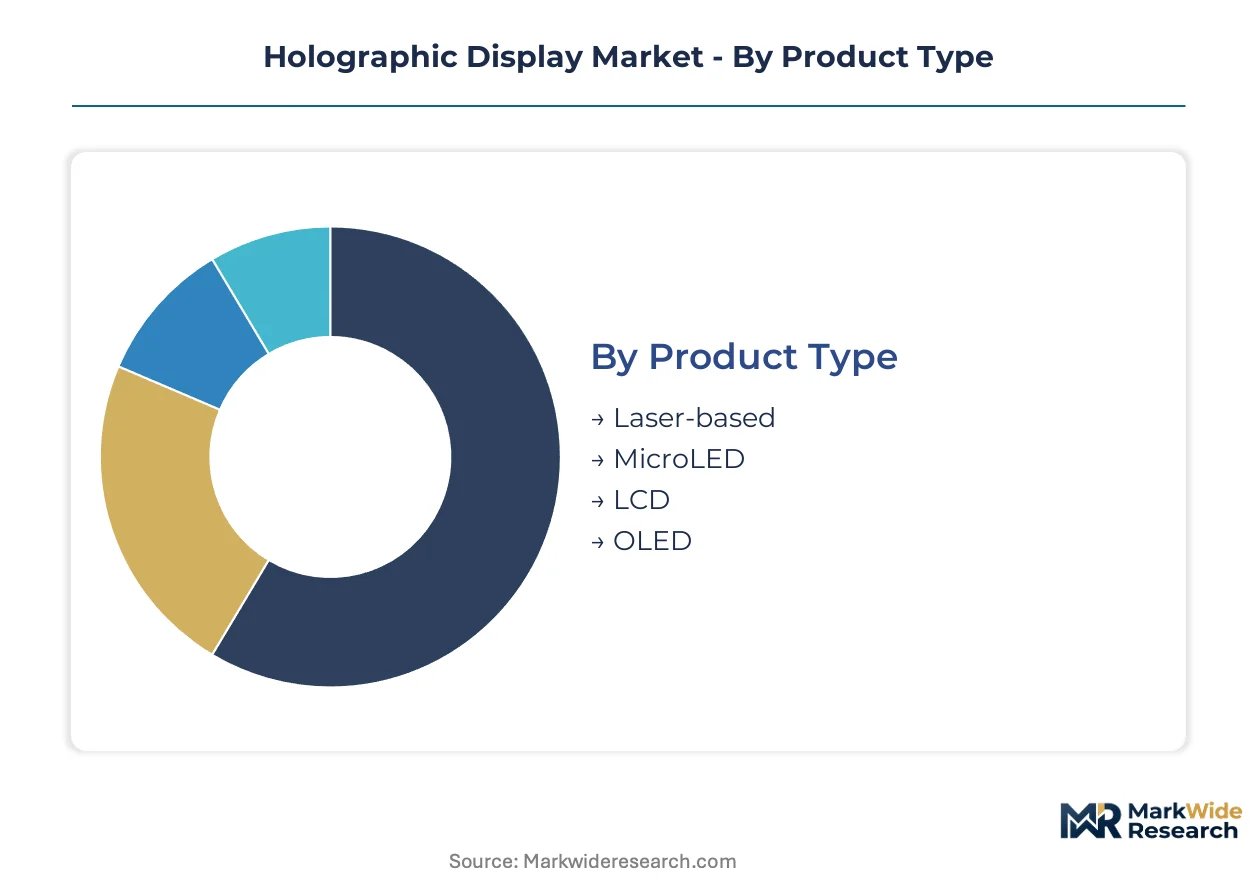
Holographic display segmentation reveals diverging margin pools across product architectures and end-use applications. Technical specifications and regulatory pathways reshape vendor positioning within each category, concentrating procurement among buyers with integrated visualization budgets.
Product Type:
Component sourcing for coherent light engines and emissive micro-arrays concentrates manufacturing in German and Japanese specialty fabs, creating tiered supply security profiles across the four architectures.
- Laser-based:Speckle-controlled coherent interference systems deliver extended color gamut through stabilized gas or solid-state emitters. Academic medical centers in the United States prioritize these systems for surgical navigation demanding sub-millimeter spatial accuracy, though single-source vulnerability in specialty laser manufacturing constrains procurement security.
- MicroLED:Epitaxial lift-off architectures with pixel pitch below 10 micrometers enable compact form factors for automotive head-up displays. Indium and gallium price volatility from Chinese rare earth output compresses gross margins on high-volume consumer electronics integrations, yet improving wafer yields expand addressable applications fastest.
- LCD:Transmissive liquid-crystal panels with backlight modulation serve cost-sensitive advertising installations and basic volumetric signage.
- OLED:Organic emissive layers enable self-illuminated thin profiles for near-eye display prototypes in enterprise training.
Today's leader: Laser-based. Tomorrow's challenger: MicroLED.
Application:
End-use demand fragments across buyer types with diverging certification requirements and procurement cycles, from FDA-regulated hospital networks to brand marketing budgets.
- Medical Imaging:Volumetric visualization systems for radiology review and pre-operative planning require FDA 510(k) clearance or EU MDR conformity. United States academic medical centers with integrated surgical navigation budgets drive procurement concentration, while European hospital committees prioritize pre-certified vendors under AI Act risk classifications.
- Automotive Displays:Compact holographic modules for instrument clusters and head-up displays compete against established LCD projection suppliers. Premium vehicle segments outside Germany and Japan remain underpenetrated, creating whitespace for suppliers demonstrating field-of-view expansion.
- Telecommunications:Light-field render engines support remote collaboration and holographic presence applications in enterprise settings.
- Advertising:Depth-cue-enabled brand installations elevate engagement metrics in retail and entertainment venues.
Medical Imaging commands premium pricing. Automotive Displays climb fastest.
End User:
Customer procurement authority varies from centralized hospital networks to fragmented retail operators, reshaping vendor sales motion and contract structure.
- Healthcare:Hospital procurement committees demand PACS interoperability certification with existing radiology infrastructure, requiring multi-year validation cycles with major equipment vendors. Defense contractor pilots for medical training simulation create reference deployments that cascade into civilian adoption.
- Entertainment:Large-format direct-view panels for immersive venues and brand installations anchor Light Field Lab's commercial strategy.
- Retail:Point-of-sale holographic signage attracts foot traffic through volumetric product visualization.
- Education:Academic institutions pilot light-field displays for STEM visualization and remote instruction.
Healthcare leads contract value. Entertainment scales unit volume.
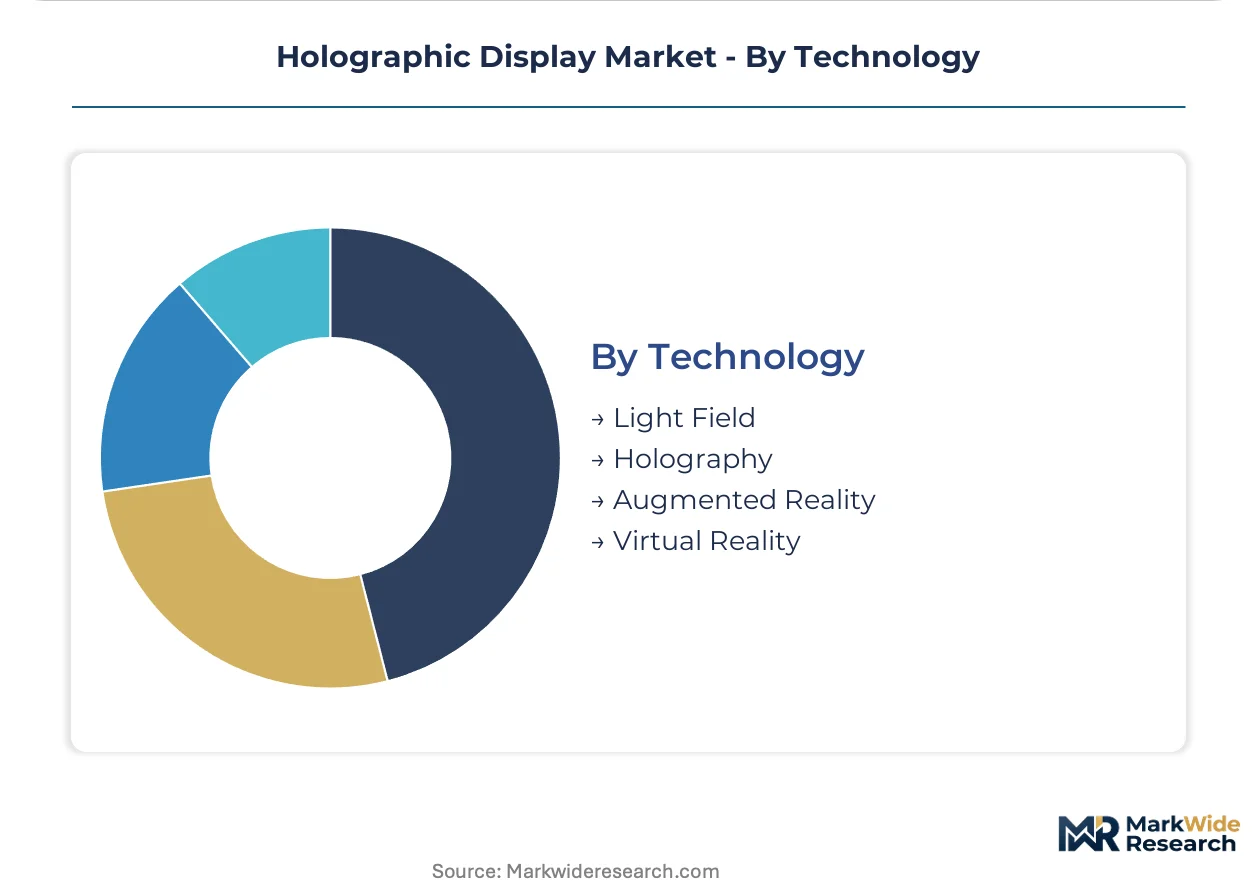
Technology:
Intellectual property concentration in wave optics and real-time rendering algorithms creates capability scarcity in Boston, Stuttgart, and Tokyo metropolitan clusters.
- Light Field:Software-defined calibration engines rebalance vendor monetization toward recurring licensing. Spatial light modulator convergence with diffractive optical elements enables new near-eye form factors, opening enterprise training applications previously served by VR headsets.
- Holography:Coherent interference pattern recording on photosensitive media or spatial light modulator generation operates above 60 Hz refresh to eliminate perceptible flicker.
- Augmented Reality:See-through waveguide combiners overlay holographic imagery on physical environments.
- Virtual Reality:Enclosed headsets with stereoscopic rendering face displacement risk from direct-view holographic alternatives.
Light Field dominates R&D investment. Holography defends installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense contractors validate light-field displays faster than European hospital procurement committees authorize holographic surgical guides, creating an Atlantic divide in commercialization velocity.
United States
Academic medical centers in Massachusetts and California expand volumetric visualization procurement for surgical navigation, while Virginia defense corridors integrate direct-view holographic walls into command training. FDA 510(k) clearance compresses time-to-market for medical device entrants. Boston and Los Angeles metropolitan clusters concentrate optical engineering talent for wave optics and real-time rendering development.
Germany
Automotive OEMs in Stuttgart and Munich pilot compact holographic modules for premium vehicle head-up displays, competing against established LCD projection suppliers. KBA type-approval requirements govern electromagnetic emissions from laser-based cockpit systems. Bavaria's precision optics manufacturing cluster around Munich supplies speckle-controlled coherent light sources for medical and defense applications.
Japan
Specialty laser manufacturers in Tokyo and Osaka metropolitan areas anchor premium-tier holographic system supply chains, creating single-source vulnerability for speckle-controlled emitters. METI industrial technology grants support spatial light modulator convergence research. The Chubu region around Nagoya houses semiconductor fabrication facilities advancing liquid-crystal-on-silicon integration.
China
Indium and gallium mining output from Inner Mongolia and Jiangxi provinces supplies MicroLED epitaxial wafer production, exposing manufacturers to rare earth price volatility. MIIT standards govern electromagnetic compatibility for automotive and medical holographic displays. Shenzhen electronics manufacturing clusters assemble diffractive optical elements for consumer electronics integrations.
United Kingdom
London-based immersive entertainment venues pilot large-format direct-view panels for brand installations and experiential advertising. MHRA conformity assessment aligns with EU MDR frameworks for holographic surgical devices post-Brexit. Cambridge optics research institutions collaborate with industrial partners on near-eye display prototypes for enterprise training.
Holographic Display Market Key Industry Players
Top-tier vendors anchor premium medical and defense applications, while mid-tier specialists populate automotive and entertainment channels. The vendor base stratifies across three capability tiers: coherent light engine specialists, MicroLED epitaxial fabricators, and software-defined calibration platforms. Strategic archetypes include integrated system houses, component pure-plays, and vertical software licensors. Capacity expansion and technology licensing dominate competitive moves as firms secure wafer supply and PACS interoperability certification.
Among Germany-based specialists, HOLOCO GmbH exemplifies the compact module archetype for automotive integration, while Light Field Lab, Inc. anchors the large-format direct-view segment for entertainment venues. Leia Inc. occupies a position within the consumer electronics calibration tier, representing software-defined monetization models. These three entities illustrate the geographic and technical fragmentation across holographic display supply chains.
| Leading Market Players |
|---|
| Axiom Holographics |
| Leia Inc. |
| HOLOCO GmbH |
| RealFiction Holding AB |
| Light Field Lab, Inc. |
| Shenzhen Muxwave Technology Co., Ltd |
| Looking Glass Factory Inc. |
| Holoxica Limited |
| Fursol |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in German precision optics clusters anchor premium-tier holographic display manufacturing, translating captive wafer supply into pricing discipline that resists commoditization pressure from Asian MicroLED assemblers.
Pricing Analysis
Capacity additions in Shenzhen electronics manufacturing clusters are reshaping price floors for diffractive optical element assemblies, compressing margins on consumer electronics integrations while surgical navigation systems sustain project-based contracting. Three-tier pricing structure across FDA-cleared premium, CE-marked standard, and uncertified economy levels separates academic medical center procurement from automotive HUD pilots and retail signage deployments. Cost compression in MicroLED tiers is intensifying because indium and gallium price volatility feeds directly into wafer economics. Hospital procurement committees demonstrate lowest price sensitivity given PACS interoperability requirements, while retail operators exhibit acute elasticity to unit cost fluctuations.
Supply Chain Analysis
Refurbishment flows for laser-based surgical systems create secondary market liquidity that extends equipment lifecycles and dampens replacement demand for original manufacturers. Component sourcing concentrates in Germany, Japan, and China, with specialty coherent light engines drawing from Stuttgart and Munich precision optics fabs while Shenzhen assembles diffractive backlights for consumer channels. Rare earth mining output from Inner Mongolia and Jiangxi provinces feeds MicroLED epitaxial wafer production, exposing manufacturers to commodity price volatility. Single-source vulnerability in speckle-controlled laser emitters from Tokyo and Osaka metropolitan areas threatens procurement security. Distribution runs through direct OEM relationships for medical and automotive tiers, with entertainment and retail channels utilizing specialized AV integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The holographic display market reads as a late-cycle quality story where hospital procurement committees are consolidating vendor relationships around FDA 510(k) pre-certification and PACS interoperability validation, privileging suppliers with established quality management systems over price-competitive challengers.
For Market Incumbents: Cement PACS interoperability certification with major radiology equipment vendors to lock in multi-year hospital procurement cycles. Deepen backward integration into specialty laser manufacturing through partnerships with Stuttgart and Munich precision optics clusters, neutralizing single-source vulnerability that emerging MicroLED specialists exploit. Defend against software-defined calibration platforms by bundling hardware deployments with recurring light-field render engine licensing.
For New Entrants and Emerging Players: Direct-to-clinician digital channels bypass entrenched hospital procurement committees for pilot deployments in academic medical centers with independent research budgets. Target underpenetrated premium automotive segments outside Germany and Japan where established LCD projection suppliers dominate but field-of-view expansion creates whitespace. Pursue EU AI Act pre-certification for machine-learning-enabled surgical guides to capture European hospital procurement prioritization of pre-validated vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among component pure-plays with captive wafer supply and established FDA quality management systems, relative to software-defined calibration platforms trading at premium multiples. Long-term viability over the next decade hinges on regulatory pre-certification velocity and defense contractor reference deployment conversion. Monitor FDA 510(k) clearance timelines for holographic surgical navigation systems as inflection indicator for hospital procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Streamlined clearance compresses time-to-market for surgical planning systems at academic medical centers. |
| EU AI Act Conformity Assessment | Pre-certification creates first-mover advantage for holographic surgical guides with diagnostic overlays. |
| PACS Interoperability Certification | Multi-year validation cycles with radiology equipment vendors secure hospital procurement contracts. |
| Defense Contractor Pilot Deployment | Command training installations cascade into civilian simulation markets and enterprise training applications. |
| Backward Integration into Laser Manufacturing | Captive supply of speckle-controlled emitters neutralizes single-source vulnerability from German and Japanese specialty fabs. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down specialty laser and MicroLED wafer supply tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, biomedical engineers at academic medical centers, automotive HUD program managers, and defense contractor simulation directors combined with secondary validation against FDA 510(k) filings, EU MDR conformity databases, FCC electromagnetic emissions records, and MIIT standards documentation. Triangulation across stakeholder inputs and regulatory filings ensures segment-level accuracy.
Historical trendline analysis of medical imaging equipment procurement cycles and automotive electronics content trajectories informed projection frameworks. Segmentation modeling spans product architecture, application vertical, end-user procurement authority, and technology platform across the analysis window. CAGRs derive from fitted growth curves adjusted for regulatory approval velocity and defense budget allocation patterns. Forecast inputs include FDA clearance timeline distributions, rare earth price volatility scenarios, and PACS interoperability certification completion rates.
The model assumes a particular technology adoption path; alternative pathways for spatial light modulator convergence with diffractive optical elements would alter the outlook toward near-eye display applications. Forecasts reflect assumptions regarding EU AI Act implementation timelines and defense training budget continuity that material regulatory delays or fiscal constraints could revise. Practitioners should monitor FDA 510(k) submission volumes and German automotive OEM holographic HUD pilot announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Electronic Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
AMOLED Display Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
OLED Display Market
Display Technologies
Smart Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Microdisplay Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Display Port Market