
 Alphanumeric LCD Modules Market | 2026-2036
Alphanumeric LCD Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Alphanumeric LCD Modules Market Analytics
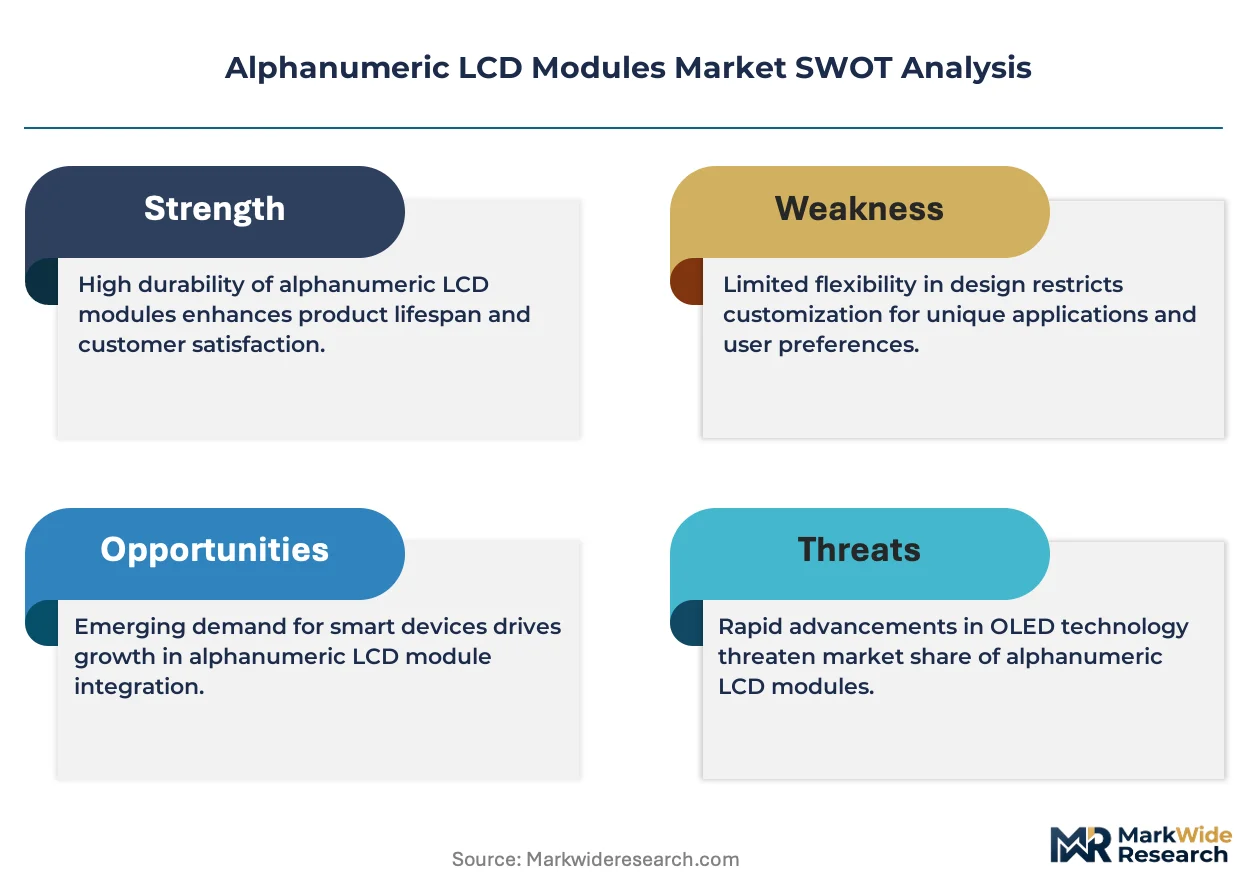
Wide-temperature industrial-grade specification tiers is rotating demand away from commercial-grade alphanumeric LCD modules. Winstar Display leverages captive TFT-LCD cell production to sustain cost advantages in character LCD sub-assemblies. Kyocera International anchors premium medical instrumentation segments with hermetically sealed COG modules. Raystar Optronics differentiates through custom segment configurations for automotive climate control panels.
Alphanumeric LCD modules are dot-matrix liquid crystal display units capable of rendering letters, numbers, and limited symbols through predefined character sets, typically organized in 8x5 or 11x5 pixel matrices with operating voltages between 3.3V and 5V. These modules integrate controller ICs such as HD44780-compatible drivers with LED or electroluminescent backlights to enable readable output in industrial control panels, medical devices, and automotive dashboards. Character LCD technology dominates unit volume across instrumentation applications where simple text readouts suffice, while LED backlit variants command margin premiums in outdoor signage and marine environments. Passive matrix addressing retains cost leadership in low-refresh industrial displays, though active matrix penetration grows in medical device interfaces requiring faster response times.
RoHS and REACH frameworks in Europe restrict hazardous substances in display module assemblies, compelling Asian contract manufacturers to certify lead-free soldering processes. The US FAA mandates DO-160G environmental testing for alphanumeric displays in avionics control panels, filtering out uncertified suppliers. Japan's METI enforces JIS C 6802 safety standards for laser and LED backlight emissions in industrial equipment. Stakeholders must monitor evolving EU F-Gas Regulation amendments affecting refrigerant monitoring displays, as these modules face redesign pressures from fluorinated gas phase-out timelines.
Market Dynamics
Industrial automation controllers in Germany, Japan, and South Korea are systematically replacing legacy seven-segment displays with dot-matrix alphanumeric LCD modules, creating sustained pull through 2035 as manufacturers modernize human-machine interfaces across factory floors.
Growth Catalysts
- RoHS and REACH substance restrictions:European environmental frameworks compel module makers to certify lead-free soldering and halogen-free backlight assemblies, opening certified supplier slots for Asian contract manufacturers who invest in compliant production lines.
- Medical instrumentation demand:Hermetically sealed chip-on-glass modules satisfy stringent sterilization protocols in surgical equipment and patient monitoring systems, anchoring premium specification tiers with extended operating lifecycles.
- Shenzhen electronics manufacturing cluster:Concentrated backlight LED and driver IC sourcing within this metropolitan hub reduces landed costs for character LCD sub-assemblies destined for industrial controllers.
Market Restraints
- Active matrix TFT substitution:Faster response times in medical device interfaces and automotive dashboards displace passive matrix alphanumeric modules in applications requiring animated graphics or video-capable displays.
- Indium tin oxide price volatility:Transparent electrode material costs fluctuate with mining output from concentrated South American and Southeast Asian suppliers, compressing margins on standard-grade modules.
- EU F-Gas Regulation phase-out timelines:Refrigerant monitoring displays face forced redesign cycles as fluorinated gas restrictions eliminate certain backlight cooling architectures from certified equipment categories.
Strategic Opportunities
- Marine and outdoor signage segments:Electroluminescent and high-brightness LED backlit variants command margin premiums in salt-spray environments where sunlight readability and IP67 sealing justify specification upgrades.
- Avionics control panel certification:DO-160G environmental testing mandates from the US FAA filter supplier pools, creating defensible positions for module makers with established shock, vibration, and altitude validation protocols.
- Wide-temperature industrial-grade tiers:Operating range extensions from 0°C-to-50°C commercial specifications toward -40°C-to-85°C ratings capture replacement cycles in oilfield equipment and cold-chain logistics infrastructure.
Industry Challenges
- HD44780 controller legacy compatibility:Maintaining pinout and instruction set equivalence with three-decade-old industry standards constrains firmware innovation while fragmenting driver IC sourcing across multiple semiconductor foundries.
- Electroluminescent backlight phosphor supply:Rare earth element dependencies in blue-green phosphor chemistries expose production schedules to export quota disruptions from concentrated mining jurisdictions.
- JIS C 6802 safety certification timelines:Japanese METI laser and LED emission testing protocols extend product introduction cycles by four to six months for backlight variants targeting industrial equipment OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alphanumeric LCD Modules Market |
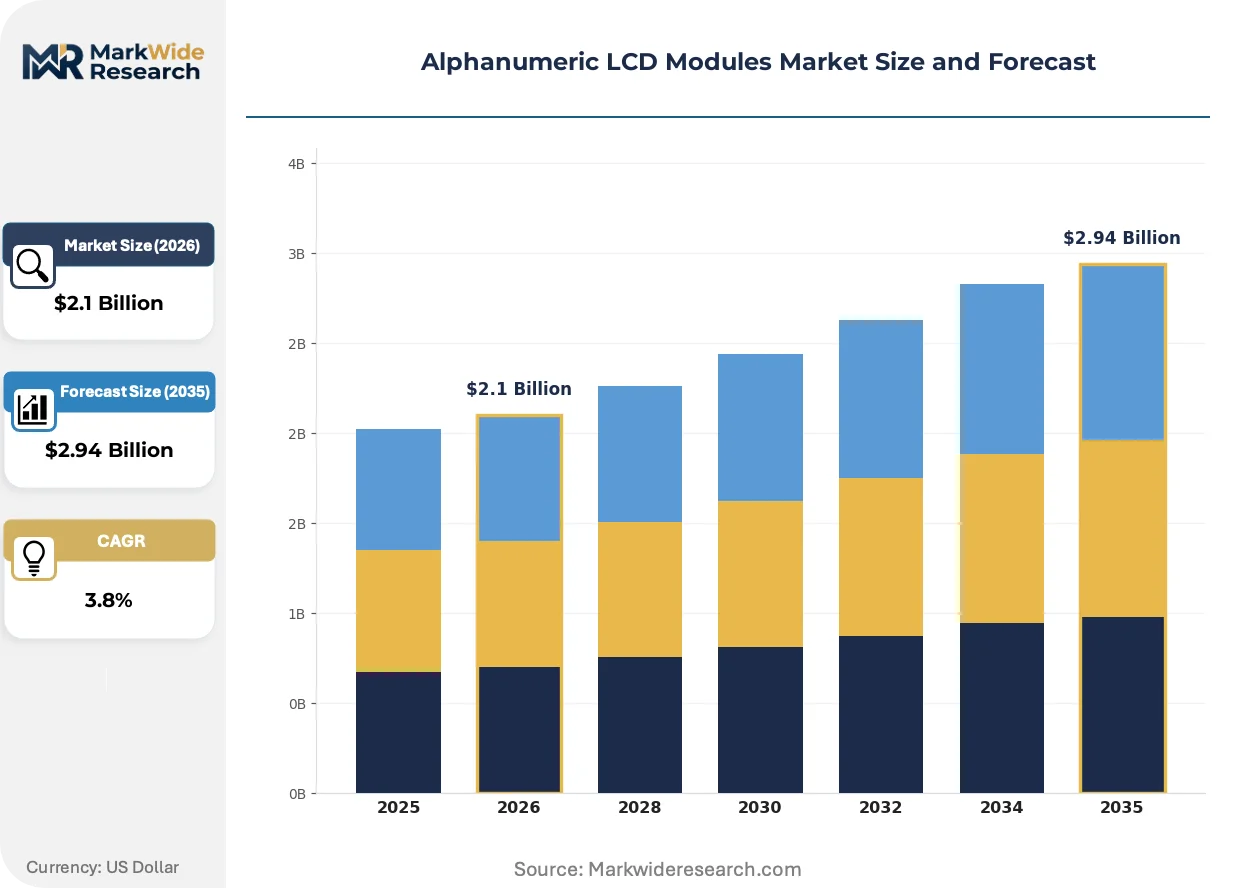
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Character LCD, Graphic LCD, OLED Display, TFT Display Technology: Passive Matrix, Active Matrix, LED Backlit, Reflective End User: Consumer Electronics, Automotive, Industrial Automation, Medical Devices Application: Displays, Control Panels, Signage, Instrumentation |
| Companies Covered | Lumex, AZ Displays, Focus LCDs, Newhaven Display, Winstar Display, Matrix Orbital, Raystar Optronics, Display Visions, Kyocera International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alphanumeric LCD Modules Market Evolving Landscape
Controller IC integration and backlight chemistry advances are compressing module thickness while extending operational envelopes, reshaping competitive differentiation around environmental resilience rather than pixel density.
Chip-on-glass bonding technology is decomposing the traditional PCB-backplane assembly in alphanumeric LCD modules. Medical device manufacturers in Germany and Japan adopt these thinner constructions for portable diagnostic equipment. The elimination of separate driver boards is decomposing cost structures in premium specification tiers while forcing PCB-assemblers downstream into commodity controllerless display service.
REACH authorization list expansions from ECHA are restricting additional substances in display module assemblies beyond original RoHS scope. Module makers must reformulate solder pastes and conformal coatings to maintain CE marking eligibility. Industrial automation OEMs in France and Italy now require full material disclosure documentation, filtering supplier pools toward vertically integrated Asian manufacturers with in-house chemistry laboratories.
Long-term service contracts with bundled display replacement schedules are displacing spot procurement in heavy industrial verticals. German automotive Tier-1 suppliers now negotiate seven-year supply agreements covering climate control panel modules with guaranteed backlight half-life thresholds. This contractual pattern concentrates procurement authority at headquarters technical teams rather than distributed plant-level purchasing functions.
Alphanumeric LCD Modules Market Segmentation
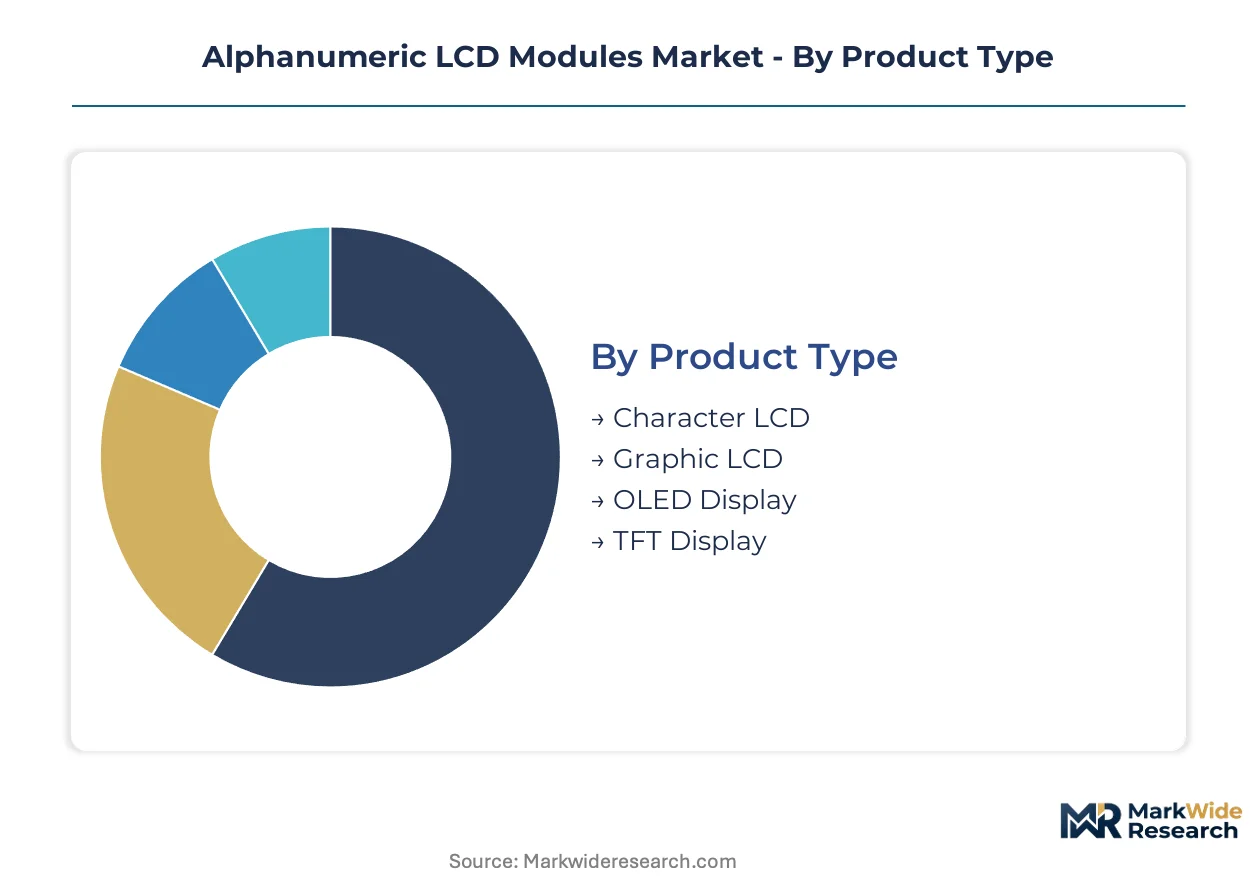
Alphanumeric LCD modules serve heterogeneous performance requirements across industrial, medical, and consumer domains. Segmentation reveals how regulatory thresholds and operating environment specifications partition procurement decisions.
Product Type:
REACH substance restrictions and RoHS lead-free mandates differentiate acceptable module constructions across European, Japanese, and US equipment categories.
- Character LCD:Dot-matrix units render letters and numerals through 8x5 or 11x5 pixel matrices with HD44780-compatible controllers. German industrial automation OEMs specify these for factory floor HMIs undergoing seven-segment display replacement cycles.
- Graphic LCD:Bitmap-addressable modules enable custom icons and limited graphical elements beyond predefined character sets. Medical device manufacturers in Japan adopt these for patient monitoring interfaces requiring waveform visualization.
- OLED Display:Self-emissive organic diodes eliminate backlight assemblies entirely, reducing module thickness for portable diagnostic equipment.
- TFT Display:Active matrix thin-film transistor technology delivers video-capable refresh rates for automotive dashboard clusters.
Established volume favors Character LCD; emerging adoption favors TFT Display.
Technology:
Cost tiers separate premium specifications from economy-grade alternatives based on environmental resilience and response time requirements.
- Passive Matrix:Simple row-column addressing sustains cost leadership in low-refresh industrial readouts where static text dominates. Shenzhen contract manufacturers concentrate output here for commodity instrumentation.
- Active Matrix:Individual pixel transistors enable faster response times for animated medical interfaces and automotive climate controls. South Korean display fabs anchor supply for this tier.
- LED Backlit:High-brightness diode arrays satisfy outdoor signage and marine applications with IP67 sealing requirements.
- Reflective:Ambient light dependence eliminates power consumption for battery-powered field equipment in oilfield and logistics tracking.
Passive Matrix retains dominant shipment share; Active Matrix captures expanding medical and automotive specification upgrades.
End User:
Application maturity and certification burden separate stable replacement demand from emerging specification frontiers.
- Industrial Automation:Controllers in Germany, Japan, and South Korea drive systematic seven-segment display replacement with wide-temperature modules.
- Medical Devices:Hermetically sealed chip-on-glass constructions satisfy METI JIS C 6802 and FDA sterilization protocols for surgical equipment.
- Automotive:Climate control panels and instrument clusters demand DO-160G shock and vibration validation for avionics-adjacent tiers.
- Consumer Electronics:Cost-optimized character modules serve appliance interfaces with minimal regulatory overhead.
Industrial Automation anchors replacement volume; Medical Devices command premium margin tiers.
Application:
Supply concentration in East Asian manufacturing clusters shapes landed cost structures across use-case categories.
- Control Panels:Factory floor HMIs in German automotive Tier-1 suppliers specify wide-temperature ranges with guaranteed backlight half-life thresholds.
- Instrumentation:Test equipment and analytical devices favor passive matrix character LCDs for simple numeric readouts with extended operational lifecycles.
- Signage:Marine and outdoor installations require electroluminescent or high-brightness LED variants with salt-spray resistance.
- Displays:General-purpose modules serve across verticals with standard commercial-grade 0°C-to-50°C specifications.
Instrumentation maintains stable procurement patterns; Control Panels are climbing the fastest as industrial modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display module fabrication clusters in Shenzhen, Seoul, and Tokyo metropolitan areas supply the majority of industrial-grade alphanumeric LCD output, with procurement patterns diverging sharply across regulatory jurisdictions.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg systematically replace legacy seven-segment displays with wide-temperature dot-matrix modules. The EU F-Gas Regulation forces redesign cycles for refrigerant monitoring equipment displays. Stuttgart and Munich anchor automotive Tier-1 supplier procurement headquarters negotiating long-term service contracts with guaranteed backlight half-life thresholds.
Japan
Medical device manufacturers in Tokyo and Osaka metropolitan areas specify hermetically sealed chip-on-glass constructions for surgical equipment interfaces. METI enforces JIS C 6802 safety standards for laser and LED backlight emissions, extending product introduction cycles. Nagoya-based industrial equipment OEMs drive demand for RoHS-compliant lead-free soldering certifications.
South Korea
Display fabs in Seoul Capital Area and Busan-Ulsan region anchor active matrix supply for automotive climate control panels requiring faster response times. KOSHA industrial safety frameworks influence module specifications for factory floor HMIs. Daegu-Gyeongbuk electronics manufacturing clusters concentrate driver IC sourcing for character LCD sub-assemblies.
United States
Avionics control panel manufacturers in California and Texas demand DO-160G environmental testing certification from the FAA, filtering supplier pools toward validated shock and vibration protocols. EPA hazardous substance restrictions align with RoHS scope for imported modules. Midwest industrial automation hubs in Illinois and Ohio specify wide-temperature ranges for oilfield equipment replacement cycles.
China
Shenzhen electronics manufacturing clusters dominate backlight LED and controller IC sourcing for cost-optimized character modules. MIIT standardization efforts push domestic module makers toward halogen-free backlight assemblies. Yangtze River Delta industrial zones in Jiangsu and Zhejiang provinces supply passive matrix displays for instrumentation applications with minimal regulatory overhead.
Alphanumeric LCD Modules Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the alphanumeric LCD modules landscape. The market structure fragments across captive display fabs, specialized module assemblers, and diversified electronics conglomerates serving distinct specification tiers. Three strategic archetypes dominate: vertically integrated Asian manufacturers with in-house TFT cell production, European-Japanese specialists in hermetically sealed medical-grade constructions, and Shenzhen-based contract manufacturers optimizing for commercial-grade volume. Competitive moves concentrate on backward integration into driver IC sourcing and geographic expansion into certified supply positions for European and North American industrial OEMs.
Among Taiwan and China-based display specialists, Winstar Display and Raystar Optronics occupy positions spanning industrial automation and automotive specification tiers. Kyocera International exemplifies the premium medical instrumentation archetype with Japanese manufacturing heritage. These three companies represent the competitive spectrum from cost-optimized volume production to hermetically sealed premium modules, with each anchoring distinct procurement channels across German factory automation, Japanese surgical equipment, and North American avionics certification pathways.
| Leading Market Players |
|---|
| Lumex |
| AZ Displays |
| Focus LCDs |
| Newhaven Display |
| Winstar Display |
| Matrix Orbital |
| Raystar Optronics |
| Display Visions |
| Kyocera International |
| Others |
Value Network & Pricing Analysis
DO-160G certification requirements from the US FAA simultaneously gate supplier qualification and stratify price tiers, forcing module makers to absorb validation costs upfront while capturing margin premiums in avionics-adjacent industrial segments. This regulatory anchor compresses margins on uncertified commercial-grade volumes while concentrating pricing power among validated Asian manufacturers serving North American aerospace OEMs.
Pricing Analysis
RoHS and REACH substance restrictions dictate the pricing tier structure across European and North American procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates hermetically sealed medical-grade modules from wide-temperature industrial variants and cost-optimized commercial units. Price differentiation rests on certification grade and volume scale, with German automotive Tier-1 suppliers negotiating seven-year service contracts bundling guaranteed backlight replacement schedules. Cost compression in standard-grade character modules is intensifying because Shenzhen contract manufacturers compete on landed cost for industrial automation controllers. Consumer electronics appliance interfaces exhibit highest price sensitivity; medical device OEMs in Japan and Germany demonstrate lowest sensitivity due to sterilization protocol requirements.
Supply Chain Analysis
Strategic stockpiling of indium tin oxide and rare earth phosphors dominates inventory strategy over just-in-time preferences, as concentrated South American and Southeast Asian mining jurisdictions expose production schedules to export quota disruptions. Supply concentrates in China, South Korea, and Japan, with Shenzhen electronics manufacturing clusters anchoring backlight LED and driver IC sourcing for cost-optimized character modules. Raw material dependencies center on indium tin oxide for transparent electrodes, rare earth elements for electroluminescent phosphors, and glass substrates from Corning-anchored supply. Single-source vulnerability in blue-green phosphor chemistries threatens electroluminescent backlight production schedules. Distribution runs through East Asian contract manufacturers to German industrial automation OEMs, Japanese medical device makers, and North American avionics suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service contracts with bundled display replacement schedules represent a faster-expanding recurring-revenue layer than hardware unit sales, as German automotive Tier-1 suppliers and oilfield equipment operators shift procurement toward guaranteed operational lifecycle coverage.
For Market Incumbents: Fortify defensible positions in DO-160G-certified avionics supply by deepening backward integration into driver IC sourcing and expanding Seoul-area active matrix capacity. Active matrix TFT substitution in medical interfaces threatens passive matrix volume; certification investment in JIS C 6802 and FDA sterilization protocols anchors premium medical instrumentation tiers against commoditization. For New Entrants and Emerging Players: Aftermarket replacement module logistics for seven-year service contracts presents a service-layer gap where incumbents under-serve, particularly for cold-chain logistics infrastructure in North American Midwest industrial hubs. Marine and outdoor signage segments offer most penetrable specification tiers, as salt-spray resistance and IP67 sealing requirements filter out uncertified competitors. Go-to-market angle: partner with Shenzhen contract manufacturers for electroluminescent backlight sub-assemblies while building DO-160G validation protocols in-house. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active matrix TFT supply for automotive climate control panels, as South Korean display fabs require specialized equipment for faster response time specifications. Long-term viability favors vertically integrated Asian manufacturers with captive TFT-LCD cell production and in-house chemistry laboratories for REACH compliance. Acquisition target archetype: mid-cap module assemblers with established FAA shock and vibration validation protocols but limited geographic footprint. Signal to watch: EU F-Gas Regulation amendment timelines forcing refrigerant monitoring display redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Sourcing | Captive supply of HD44780-compatible controllers insulates against semiconductor foundry fragmentation. |
| DO-160G Environmental Testing Certification | FAA validation protocols create defensible supplier positions for North American avionics control panels. |
| Hermetic Sealing Technology Investment | Chip-on-glass bonding satisfies METI JIS C 6802 and FDA sterilization requirements for surgical equipment. |
| Wide-Temperature Range Extension | -40°C-to-85°C ratings capture replacement cycles in oilfield equipment and cold-chain logistics. |
| Long-Term Service Contract Structuring | Seven-year agreements with guaranteed backlight half-life thresholds concentrate procurement authority at headquarters. |
Research Methodology
Cross-validation between primary interviews with industrial automation procurement directors and secondary analysis of SEC filings from display module manufacturers anchors the qualitative findings. Plant managers at German automotive Tier-1 suppliers, biomedical engineers at Japanese surgical equipment OEMs, and aftermarket service heads at North American oilfield equipment operators provided operational perspective. Secondary sources include FAA DO-160G certification databases, ECHA REACH authorization list updates, and customs records tracking indium tin oxide import flows. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around EU F-Gas Regulation phase-out timelines and indium tin oxide price volatility scenarios shapes the forecast confidence intervals. The analytical framework models product type, technology tier, end-user vertical, and application category across the projection horizon, with geographic regulatory clusters as an additional dimension. CAGRs derive from segment-level volume trajectories weighted by average selling price movements. Industry-specific inputs include seven-year service contract penetration rates in German automotive supply and JIS C 6802 certification completion timelines for backlight variants.
Forecasts assume regulatory continuity in RoHS, REACH, and FAA DO-160G regimes; material policy shifts would require re-modeling supplier qualification thresholds and redesign cycle frequencies. Specific risk factors that could revise projections include rare earth export quota disruptions from concentrated mining jurisdictions and active matrix TFT cost curves accelerating substitution beyond modeled rates. Practitioners should keep alternative scenarios live as EU F-Gas Regulation amendments and METI safety standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Smart Privacy Glass Market
Display Technologies
Portable Projector Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Projector Screen Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Interactive Video Wall Market
Display Technologies
QLED Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Seven Segment Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
3D Holographic Display Market
Display Technologies
Global Display Market
Display Technologies
E-Paper Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Global OLED Market
Display Technologies
Masks for Display Panel Market