
 Low Power Next Generation Display Market | 2026-2036
Low Power Next Generation Display Market Size, Share, and Industry Trends Forecast 2026-2036
Low Power Next Generation Display Market Intelligence
Consolidation among major consumer electronics manufacturers is hardening procurement requirements for advanced displays. Samsung Display leverages its dominant position in OLED manufacturing to secure large-volume contracts. LG Display differentiates with its expertise in flexible and large-format panel technologies for premium segments. BOE Technology Group competes on manufacturing scale, particularly within the high-volume smartphone supply chains in China.
Low power next generation displays are visual output devices engineered to minimize energy consumption through technologies that do not require a constant backlight. Their primary purpose is to extend battery life in portable electronics and reduce operational costs in continuously-on applications. OLED technology continues to dominate the smartphone application. MicroLED represents a high-growth technology for premium screens and automotive heads-up displays, where power efficiency is critical.
Energy efficiency mandates, such as the EU's Ecodesign Directive and the US EPA's ENERGY STAR program, directly influence product design and component selection. In China, compliance with national GB standards for energy consumption is essential for market access, pushing manufacturers toward low power solutions. Stakeholders must navigate the trade-offs between manufacturing cost, brightness, and power consumption to align with evolving device requirements.
Market Dynamics
The central dynamic shaping the market is the technical tension between rising consumer expectations for display brightness and resolution and the absolute requirement for minimal power draw in battery-powered devices. This trade-off forces innovation in material science and fabrication.
Growth Catalysts
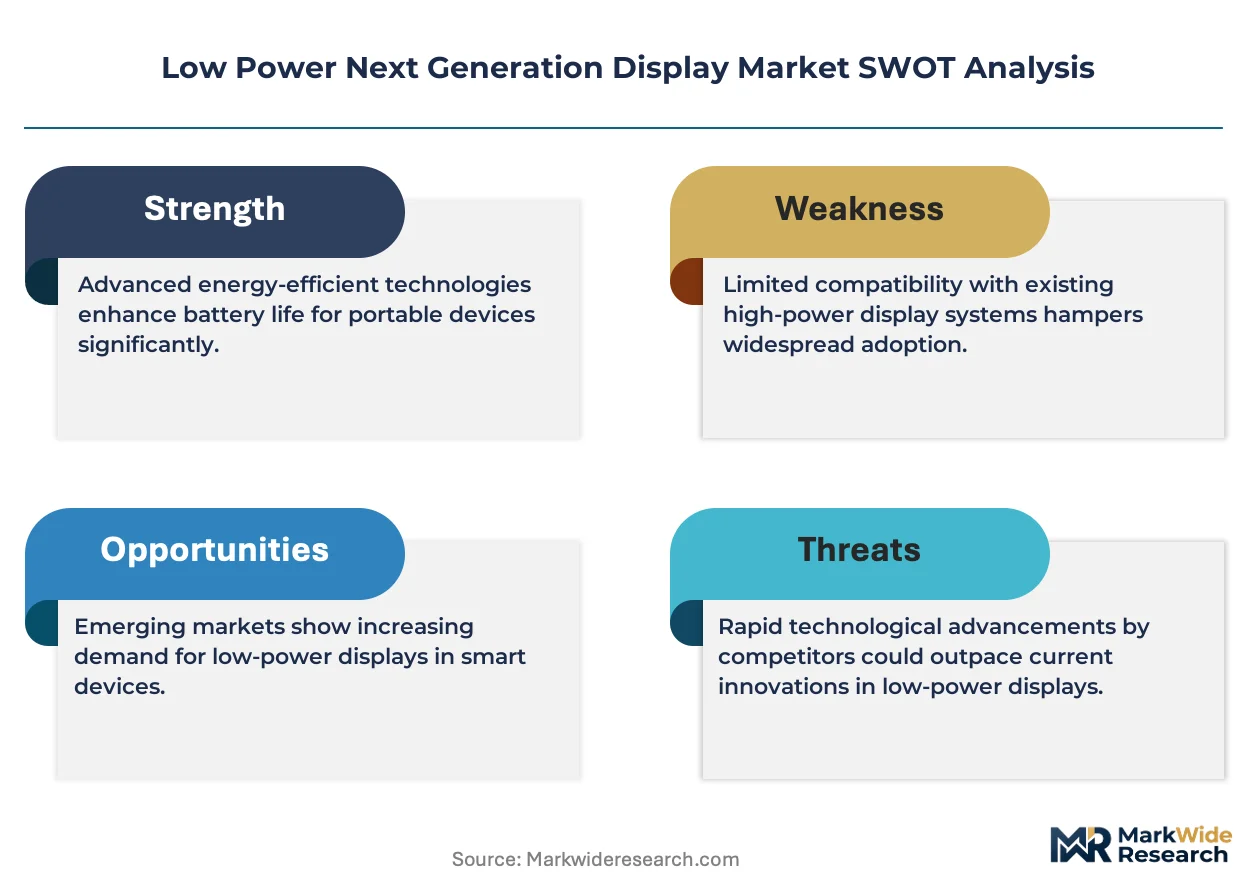
- Wearables Demand:The expansion of the wearables market, including smartwatches and augmented reality glasses, requires displays that offer high visibility and long operational periods between charges, directly stimulating demand for energy-efficient technologies.
- Automotive Integration:Vehicle electrification and the development of advanced driver-assistance systems are driving the adoption of low power displays for digital instrument clusters, infotainment systems, and large-format heads-up displays to reduce battery load.
- Energy Efficiency Mandates:Regulatory frameworks like the EU's Ecodesign Directive and the US EPA's ENERGY STAR program pressure OEMs to incorporate low power components, making these displays a preferred choice for achieving compliance.
Market Restraints
- High Manufacturing Costs:The fabrication of next generation displays, particularly MicroLED, involves complex mass transfer processes and high capital expenditure, which currently limits production scale and keeps unit costs elevated for mainstream applications.
- Material Supply Chain Risks:Production depends on specific organic materials and rare earth elements whose supply chains are geographically concentrated, exposing manufacturers to price volatility and potential sourcing disruptions that can impact production schedules.
- Performance Trade-offs:Achieving peak brightness and long-term color stability without increasing power consumption remains a significant technical barrier, especially for emissive technologies that can suffer from burn-in or degradation over time.
Strategic Opportunities
- Smart Home and IoT Devices:The proliferation of always-on smart home hubs, thermostats, and electronic shelf labels creates a substantial opportunity for displays that consume negligible power in standby mode while providing instant-on functionality.
- Flexible and Rollable Form Factors:Advances in flexible substrates enable novel product designs beyond foldable smartphones, including rollable televisions, expandable tablets, and conformable displays for architectural or industrial applications, opening new market segments.
- Medical Device Miniaturization:The need for smaller, lighter, and more power-efficient portable medical monitoring equipment and diagnostic tools presents a high-value opportunity for compact, low-voltage displays that can operate reliably on small batteries.
Industry Challenges
- Standardization Gaps:A lack of universally accepted metrics and testing protocols for comparing the power efficiency of different display technologies like OLED and MicroLED creates ambiguity for device designers and complicates component selection.
- Intellectual Property Complexity:The dense and overlapping patent landscape surrounding key manufacturing processes, especially for MicroLED pixel transfer and bonding, creates significant licensing hurdles and litigation risks for new market entrants.
- System Integration Hurdles:Engineering teams face considerable difficulty integrating ultra-thin, flexible displays with existing device chassis, power management integrated circuits, and software drivers, often requiring complete system-level redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Power Next Generation Display Market |
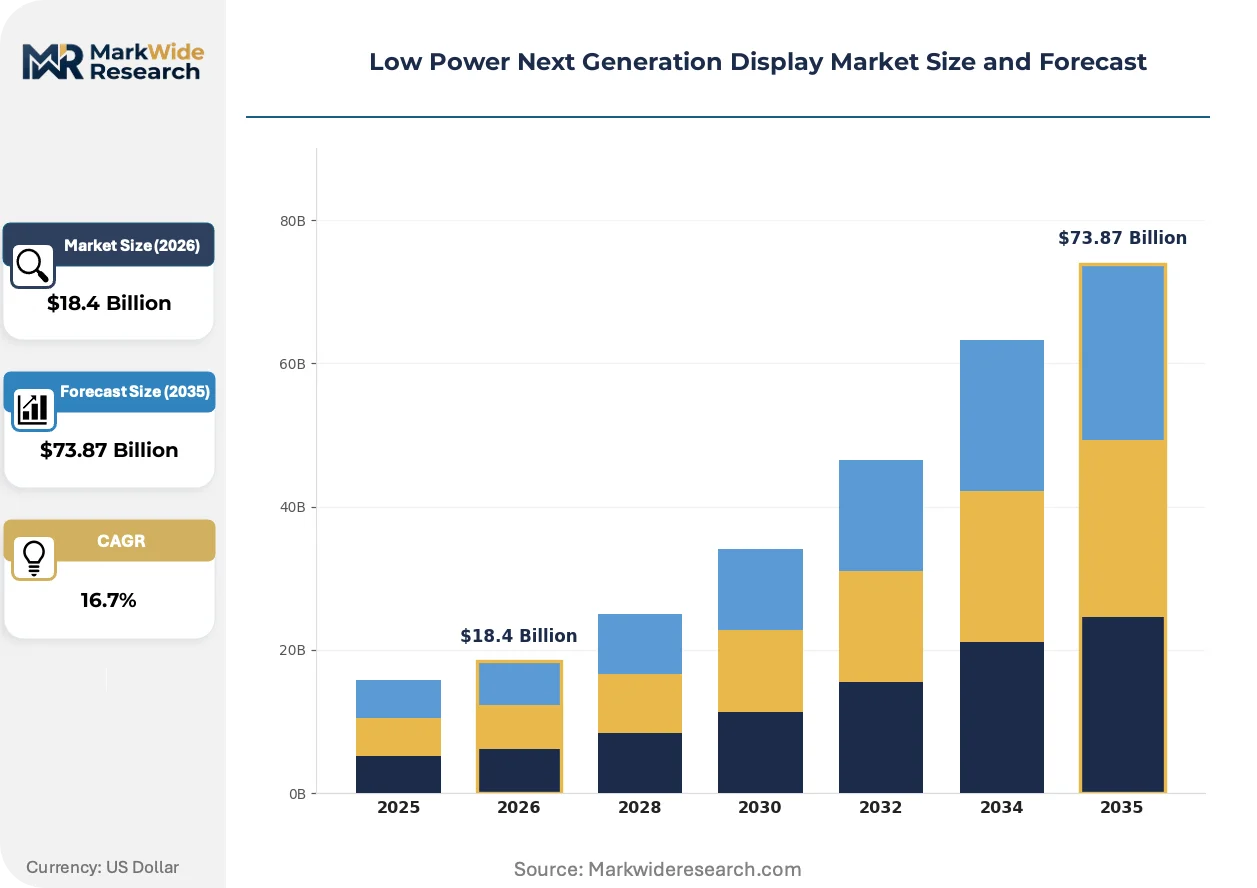
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $73.87 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: OLED, MicroLED, Quantum Dot, E-Ink, Electroluminescent, MEMS Application: Smartphones, Wearables, Automotive Heads-Up, Digital Signage, Aviation Cockpits, Gaming Consoles Product Type: Flexible Displays, Transparent Displays, Foldable Screens, Rigid Panels, Curved Monitors, Interactive Boards End User: Consumer Electronics Manufacturers, Vehicle Integrators, Advertising Agencies, Aerospace Firms, Entertainment Providers, Medical Device Makers |
| Companies Covered | Samsung Display, BOE Technology Group, LG Display, AU Optronics Corporation, Visionox Technology, Universal Display Corporation, Sharp Corporation, Sony Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Power Next Generation Display Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift in design philosophy, where energy efficiency is no longer a secondary benefit but a primary engineering goal. This change is driven by the demands of untethered, mobile-first applications that require extended operational autonomy.
MicroLED technology provides superior brightness, contrast, and power efficiency by utilizing arrays of inorganic, microscopic light-emitting diodes as individual pixels. Premium segments, especially automotive for heads-up displays and wearables for microdisplays, are leading early adoption. This technology is consolidating investment and R&D focus on emissive display architectures, diminishing the long-term viability of less efficient backlit LCDs in high-end applications.
China's national GB standards for energy consumption in consumer electronics have become progressively more rigorous. This regulatory pressure forces domestic and international brands to prioritize low power components to gain market access and maintain competitiveness. The high-volume smartphone and television segments are most impacted, compelling supply chains to accelerate the transition toward more efficient OLED and future MicroLED screens.
A significant change in product development strategy now elevates battery longevity to a primary purchasing driver, often ahead of peak display specifications. This is fundamentally altering the "more is better" approach to screen resolution and brightness that previously dominated portable electronics. This behavioral shift is most pronounced in the wearables and thin-and-light laptop categories, where all-day usability is a critical marketing and performance benchmark.
Low Power Next Generation Display Market Segmentation
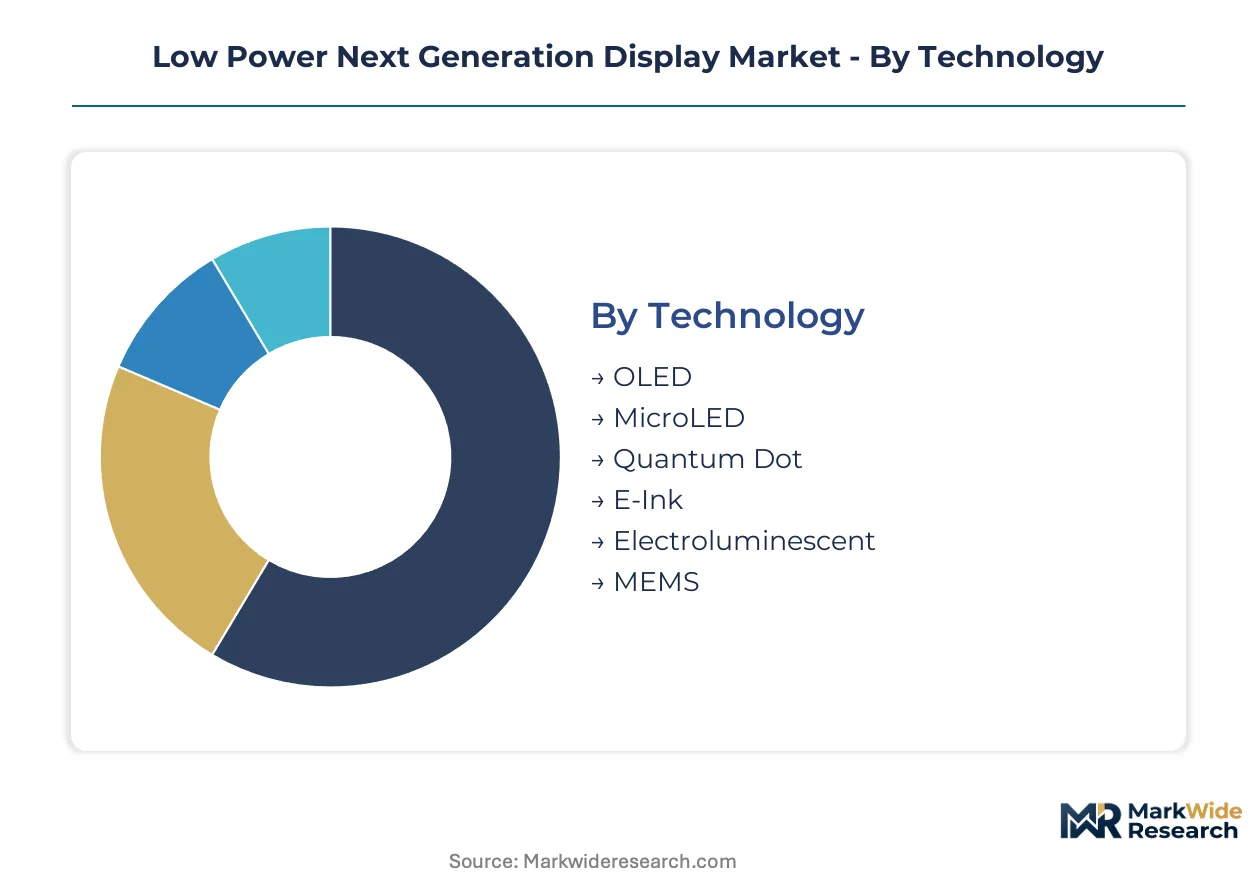
The Low Power Next Generation Display market categorizes solutions by key attributes, enabling stakeholders to align product development with specific end-user requirements. Understanding these distinctions helps manufacturers pinpoint precise technological investments and target optimal market entry points for advanced display solutions.
Technology:
The choice of display technology significantly influences power efficiency, visual performance, and manufacturing complexity for device makers.
- OLED:These organic light-emitting diode displays offer excellent contrast and power efficiency by individually illuminating pixels, particularly for dark content. Demand concentrates heavily in the smartphone sector, where Samsung Display dominates production volumes for premium devices.
- MicroLED:Utilizing arrays of microscopic inorganic LEDs, MicroLED technology delivers superior brightness, contrast, and long-term stability with minimal power draw. Early adoption focuses on high-end wearables and automotive heads-up displays, driven by the need for extreme durability and efficiency.
- Quantum Dot:Quantum Dot displays enhance color accuracy and brightness in LCDs and are being integrated into OLED structures to improve efficiency and color gamut. This technology is gaining traction in television and monitor segments.
- E-Ink:Known for bistability, E-Ink requires power only to change its image, making it ideal for extremely low-power, static information displays. E-readers and electronic shelf labels primarily utilize E-Ink for extended battery life.
- Electroluminescent:Electroluminescent displays offer thin, flexible, and robust illumination, often used for backlighting or simple graphic displays in industrial settings. Their inherent durability suits harsh operating environments.
- MEMS:Micro-electromechanical systems displays leverage tiny mirrors or shutters to modulate light, promising high efficiency and compact form factors for micro-projectors or specialized augmented reality applications.
OLED leads on scale; MicroLED leads on momentum.
Application:
The specific use case determines the required balance between display performance, power consumption, and form factor, driving distinct segment needs.
- Smartphones:These portable devices demand high-resolution, vibrant displays with exceptional power efficiency to extend battery life through daily use cycles. OLED technology dominates this segment due to its thin profile and superior visual characteristics.
- Wearables:Smartwatches, fitness trackers, and augmented reality glasses require compact, energy-efficient microdisplays capable of high visibility in varying light conditions. The expansion of this market directly stimulates demand for very low power display solutions.
- Automotive Heads-Up:Heads-up displays project critical information onto the windshield, necessitating high brightness, durability, and minimal power draw to avoid vehicle battery strain. MicroLED is emerging as a preferred technology for these demanding applications.
- Digital Signage:Public information displays and advertising boards need durable, bright panels that can operate continuously with reduced energy consumption. This application benefits from larger format, low power display solutions.
- Aviation Cockpits:Aircraft instrumentation requires displays with extreme reliability, wide viewing angles, and resistance to environmental factors, alongside stringent power management. Specialized low power panels enhance operational safety.
- Gaming Consoles:Portable gaming devices prioritize high refresh rates, low latency, and efficient power usage to provide immersive experiences without rapidly depleting battery reserves.
Smartphones represent the primary demand segment, while wearables exhibit a rapidly expanding trajectory.
Product Type:
The physical form factor and design flexibility of displays influence device aesthetics, ergonomic considerations, and novel product integrations.
- Flexible Displays:These displays can bend, curve, or roll without damage, enabling innovative device designs and conformable surfaces for various applications. Advances in flexible substrates facilitate new product categories beyond traditional electronics.
- Transparent Displays:Allowing light to pass through, transparent displays integrate digital information into physical environments, offering augmented reality experiences or unobtrusive data overlays. Retail and architectural applications are exploring this technology.
- Foldable Screens:Foldable displays enable larger screen real estate in a compact form factor, fundamentally altering the design paradigm for smartphones and tablets. This product type drives significant innovation in material science.
- Rigid Panels:Traditional flat display panels remain crucial for many applications, offering cost-effectiveness and mature manufacturing processes. Monitors, televisions, and many industrial interfaces still rely on rigid display structures.
- Curved Monitors:These displays provide a more immersive viewing experience, particularly for gaming and professional applications, by matching the natural curvature of the human eye. Ergonomics and visual comfort are key drivers.
- Interactive Boards:Large-format touch-enabled displays facilitate collaboration and engagement in educational, corporate, and public settings. These boards require robust low power displays for continuous operation.
Flexible displays are transforming device design, with foldable screens driving significant market innovation.
End User:
Customer operational models and integration expertise dictate the specific procurement requirements and technical support needed for low power displays.
- Consumer Electronics Manufacturers:These firms require high-volume, cost-effective display solutions with proven reliability for integration into smartphones, laptops, and wearables. Samsung and LG Display are primary suppliers for this segment.
- Medical Device Makers:Manufacturers of portable diagnostic tools and monitoring equipment need compact, low-voltage displays that offer high readability and operate reliably on small batteries. Miniaturization and power efficiency are critical for these devices.
- Vehicle Integrators:Automotive companies and their Tier 1 suppliers demand rugged, durable displays resistant to extreme temperatures and vibrations for instrument clusters and infotainment systems. Power reduction is essential for electric vehicle efficiency.
- Advertising Agencies:Agencies utilize digital signage and interactive displays for engaging visual campaigns in public spaces, prioritizing high brightness and energy efficiency for continuous operation.
- Aerospace Firms:Aircraft manufacturers require specialized displays that meet stringent safety certifications and perform reliably under extreme environmental conditions. Long-term stability and precise optical properties are paramount.
- Entertainment Providers:Companies producing gaming consoles, virtual reality headsets, and professional AV equipment seek displays with high refresh rates and vibrant color reproduction.
Consumer electronics manufacturers represent the largest purchasing volume, while medical device makers prioritize specialized, high-value solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and China exhibit distinct approaches to low power next generation display manufacturing. South Korea focuses on premium OLED and MicroLED technologies, while China emphasizes high-volume production for smartphones and televisions. This regional specialization shapes global supply dynamics for advanced display solutions.
South Korea
Demand for advanced displays in smartphones and premium automotive applications drives investment. The South Korean government actively supports display technology development through initiatives like the K-Display strategy. Major manufacturers in the Gyeonggi Province region, including Samsung Display and LG Display, lead global OLED and flexible display production.
China
High-volume smartphone and television segments require cost-effective, energy-efficient panels. China's national GB standards for energy consumption mandate the adoption of low power display solutions for market access. Display manufacturing hubs in the Yangtze River Delta and Pearl River Delta, including BOE Technology Group, expand capacity for OLED and LCD technologies.
United States
Wearables and automotive heads-up displays generate demand for compact, highly efficient microdisplays. The US EPA's ENERGY STAR program encourages the integration of low power components in consumer electronics, influencing product design. Silicon Valley and other tech clusters foster innovation in MicroLED research and advanced display integration for specialized applications.
Germany
Automotive integration, particularly for electric vehicles and ADAS, fuels demand for robust, low power displays. The EU's Ecodesign Directive pressures OEMs to incorporate energy-efficient components, impacting display selection. Research institutions and automotive suppliers in Bavaria and Baden-Württemberg collaborate on next-generation display solutions for vehicle cockpits.
Japan
Specialized medical devices and industrial equipment create demand for compact, reliable low-voltage displays. METI initiatives support advanced material science and precision manufacturing, critical for high-performance display components. Technology clusters around Tokyo and Osaka continue to develop innovative display technologies and fabrication processes.
Low Power Next Generation Display Market Key Industry Players
South Korean producers anchor one tier of the low power next generation display market; Chinese specialists hold significant positions in high-volume segments. The market structure exhibits consolidation among top-tier manufacturers, with a fragmented landscape below for niche applications. Strategic archetypes include integrated display manufacturers, specialized component suppliers, and system integrators focusing on specific end-user requirements. Dominant competitive moves involve significant capacity expansion and strategic partnerships to secure supply chains and accelerate technology adoption.
Among South Korean display fabricators, Samsung Display represents a leader in OLED manufacturing, securing large-volume contracts for premium devices. LG Display, another South Korean entity, exemplifies expertise in flexible and large-format panel technologies, particularly for premium segments. BOE Technology Group, a Chinese firm, occupies a position focused on manufacturing scale, particularly within the high-volume smartphone supply chains in China. These companies collectively anchor the supply of advanced display technologies across diverse applications, influencing material procurement and R&D directions within the sector. Their strategic investments shape the evolution of display form factors and efficiency benchmarks.
| Leading Market Players |
|---|
| Samsung Display |
| BOE Technology Group |
| LG Display |
| AU Optronics Corporation |
| Visionox Technology |
| Sharp Corporation |
| Sony Corporation |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
High capital expenditure for MicroLED fabrication directly influences the premium pricing tiers observed for advanced display solutions. This investment translates into elevated unit costs for early adoption segments.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume OLED panels, particularly in the smartphone sector. The dominant pricing model remains per-unit transactional, with price differentiation driven by display quality grade and manufacturing volume scale. Pricing softness stems from intense competition among major panel producers. Consumer electronics manufacturers exhibit high price sensitivity, while automotive integrators prioritize performance over cost.
Supply Chain Analysis
China's national GB standards for energy consumption reshape sourcing strategies for domestic market access. Geographic supply concentration centers on South Korea for premium OLED and MicroLED, and China for high-volume LCD and OLED production. Production draws from specific organic materials and rare earth elements, creating single-source vulnerability risks. Downstream distribution typically runs through long-term, direct contractual agreements with major OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low power display market presents geographic arbitrage opportunities, particularly due to the significant labor cost differentials between South Korea and China. This disparity influences manufacturing location decisions and component pricing strategies.
For Market Incumbents:Anchor R&D investments in advanced MicroLED fabrication processes to maintain technological leadership against emerging Chinese competitors. Expand high-volume OLED capacity in South Korea, leveraging existing infrastructure and skilled labor to secure large-volume contracts. Control over critical material supply chains acts as a lever against margin pressure.
For New Entrants and Emerging Players:Price-point gaps exist within the mid-tier wearables segment, offering an entry point for specialized display solutions. Target compact, low-voltage displays for medical device miniaturization, a high-value application with specific reliability requirements. A focused go-to-market strategy involves offering integrated display and power management solutions to device makers.
For Investors and Strategic Acquirers:Consolidation pressure builds where significant capital expenditure is required for advanced display technology development. Long-term viability favors firms with robust intellectual property in MicroLED and flexible display technologies. Acquire specialized component suppliers offering unique material science or mass transfer expertise. Watch for sustained improvements in MicroLED mass production yields as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | BOE Technology Group expands production scale for high-volume smartphone and television panels. |
| MicroLED R&D Alliances | South Korean manufacturers accelerate development of next-generation MicroLED technology for premium applications. |
| Flexible Substrate Investment | LG Display enhances capabilities for novel product form factors like rollable televisions and expandable tablets. |
| Supply Chain Diversification Programs | US EPA initiatives encourage resilient sourcing of critical display components to mitigate risks. |
| Automotive Display Partnerships | German vehicle integrators collaborate on robust, low power heads-up displays for electric vehicles. |
Research Approach
Coverage spans South Korea, China, the United States, Germany, and Japan, with primary inputs from each key region. Primary interviews engaged display engineers, procurement heads at consumer electronics firms, and automotive integrators. Secondary validation utilized EU Ecodesign Directive documents, US EPA ENERGY STAR reports, China GB standards, and company annual reports. A bottom-up and top-down triangulation approach ensured data consistency.
Granularity for the market model extends across technology, application, product type, end user, and display substrate material. The analytical framework projects market evolution over the projection horizon, with CAGRs derived from historical growth trends and future demand projections. Key forecast inputs include MicroLED mass transfer yield rates and electric vehicle adoption rates.
Caveats apply where raw material supply disruptions or MicroLED manufacturing cost volatility could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Vietnam Displays Market
Display Technologies
Touch Screen Display Market
Display Technologies
Interactive Display Market
Display Technologies
Global Medical Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Multi-Function Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Projector Screen Market
Display Technologies
Gaming Monitors Market
Display Technologies
Seven Segment Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Global Wearable Display Market
Display Technologies
Display Mask Market
Display Technologies
Digital Kiosk Display Market