
 Asia-Pacific Industrial Display Market | 2026-2036
Asia-Pacific Industrial Display Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Display Market Outlook
Aftermarket service revenue for legacy industrial display retrofits is narrowing as OEMs bundle extended warranty and remote diagnostics into initial equipment contracts. Advantech leverages its embedded computing heritage to dominate integrated HMI-display platforms for factory automation. BOE Technology Group anchors supply through captive Gen 10.5 LCD fab capacity serving panel demand from Korean and Japanese equipment builders. Samsung Electronics competes on OLED reliability certifications for aerospace cockpit and automotive supplier applications.
An industrial display is a hardened visual interface engineered for continuous operation across temperature extremes, vibration, and electromagnetic interference, typically specified with IP65 ingress protection, wide operating ranges from -20°C to 70°C, and 50,000-hour minimum backlight life for process control and machinery monitoring. LCD panels retain volume leadership in manufacturing floor deployments where cost sensitivity and proven supply chains outweigh premium display performance. Touchscreen technology captures expanding share in food processing and pharmaceutical cleanrooms where glove-compatible capacitive interfaces replace mechanical button arrays. Digital signage applications across transportation hubs and energy control centers are shifting toward LED direct-view architectures for luminance and longevity advantages.
China's MIIT enforces GB standards for electromagnetic compatibility and energy consumption that filter non-compliant display modules from industrial equipment certification pathways. Japan's METI administers JIS standards for display reliability in hazardous environments, while South Korea's MFDS and KOSHA frameworks govern pharmaceutical and workplace safety interfaces. Australia's TGA and India's BIS are tightening local testing requirements for imported industrial panels used in medical device manufacturing and critical infrastructure. Stakeholders must monitor divergence between national certification regimes when configuring pan-Asia-Pacific product platforms.
Market Dynamics
Semiconductor fabrication concentration in Taiwan and South Korea is compressing procurement timelines for ruggedized visualization systems, while China's MIIT energy mandates force simultaneous redesign of backlight architectures and power management circuits.
Growth Catalysts
- MIIT GB Standards:China's energy-efficiency mandates for industrial equipment compel display manufacturers to redesign backlight systems, creating replacement demand across eastern manufacturing corridors.
- Cleanroom Touchscreen Migration:Pharmaceutical and food processing facilities are replacing mechanical button arrays with glove-compatible capacitive interfaces, expanding panel refresh cycles.
- Taiwan-South Korea Fab Buildouts:Semiconductor fabrication facilities are accelerating procurement of ruggedized LCD and LED panels for process visualization and environmental monitoring.
Market Restraints
- Panel Supply Concentration:Captive Gen 10.5 LCD fab capacity concentrates supply leverage among select Korean and Japanese equipment builders, constraining pricing flexibility for downstream integrators.
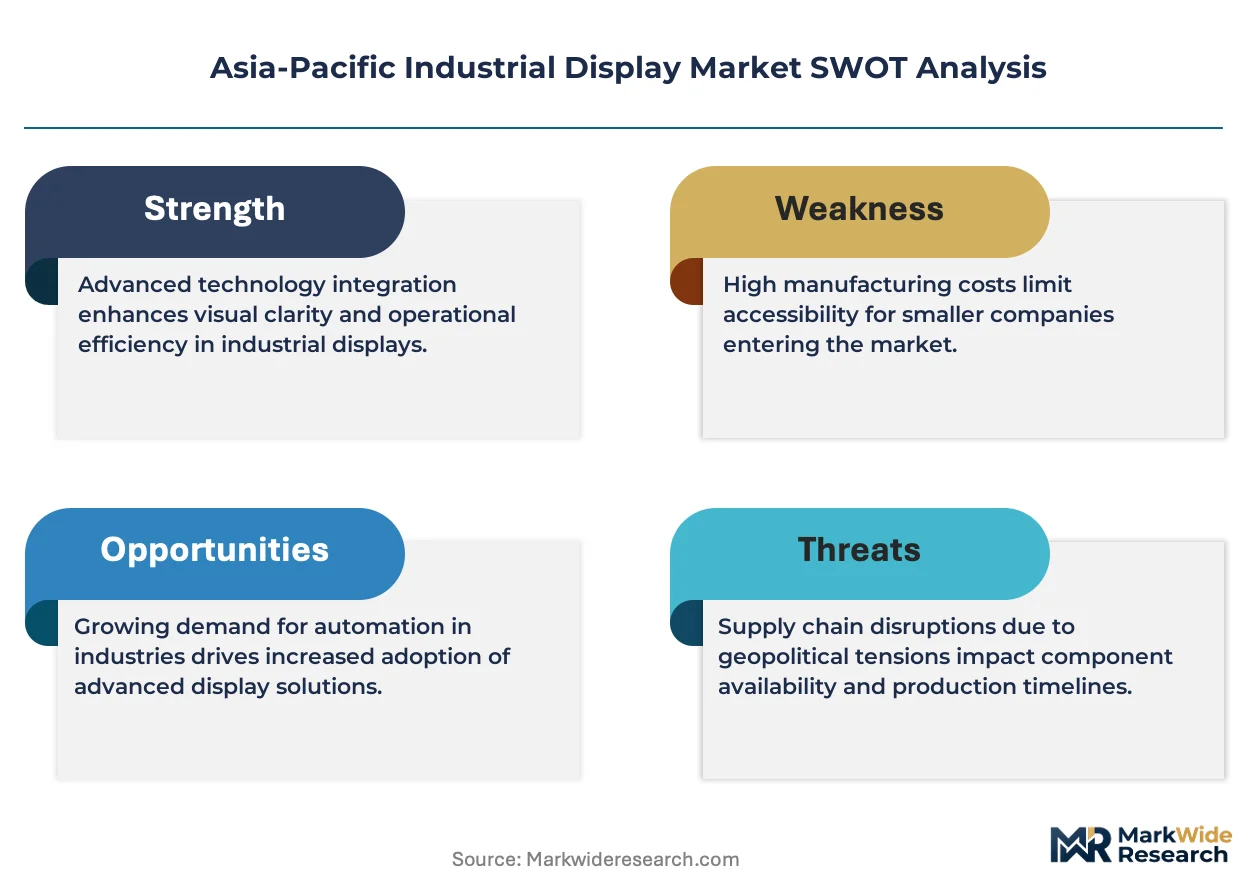
- Input Cost Volatility:Rare earth phosphors and driver IC substrates face price instability due to concentrated refining operations, compressing margin buffers for mid-tier panel assemblers.
- Regulatory Divergence:Divergent certification pathways between Japan's METI JIS standards, South Korea's MFDS frameworks, and Australia's TGA requirements fragment product platform economics.
Strategic Opportunities
- India BIS Tightening:India's Bureau of Indian Standards is expanding local testing requirements for imported industrial panels, creating first-mover advantages for domestic assembly partnerships.
- LED Direct-View Migration:Transportation hubs and energy control centers across the region are shifting from LCD-based digital signage to LED direct-view architectures for luminance and longevity.
- HMI-Display Convergence:Factory automation buyers are consolidating separate controller and display purchases into integrated platforms, rewarding embedded computing heritage.
Industry Challenges
- Certification Timeline Compression:Australia's TGA and India's BIS are extending approval durations for medical device manufacturing panels, delaying revenue recognition for new product introductions.
- Legacy System Integration:Pharmaceutical packaging lines in China's eastern corridor require backward-compatible signaling protocols, complicating firmware development for next-generation touch interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Display Market |
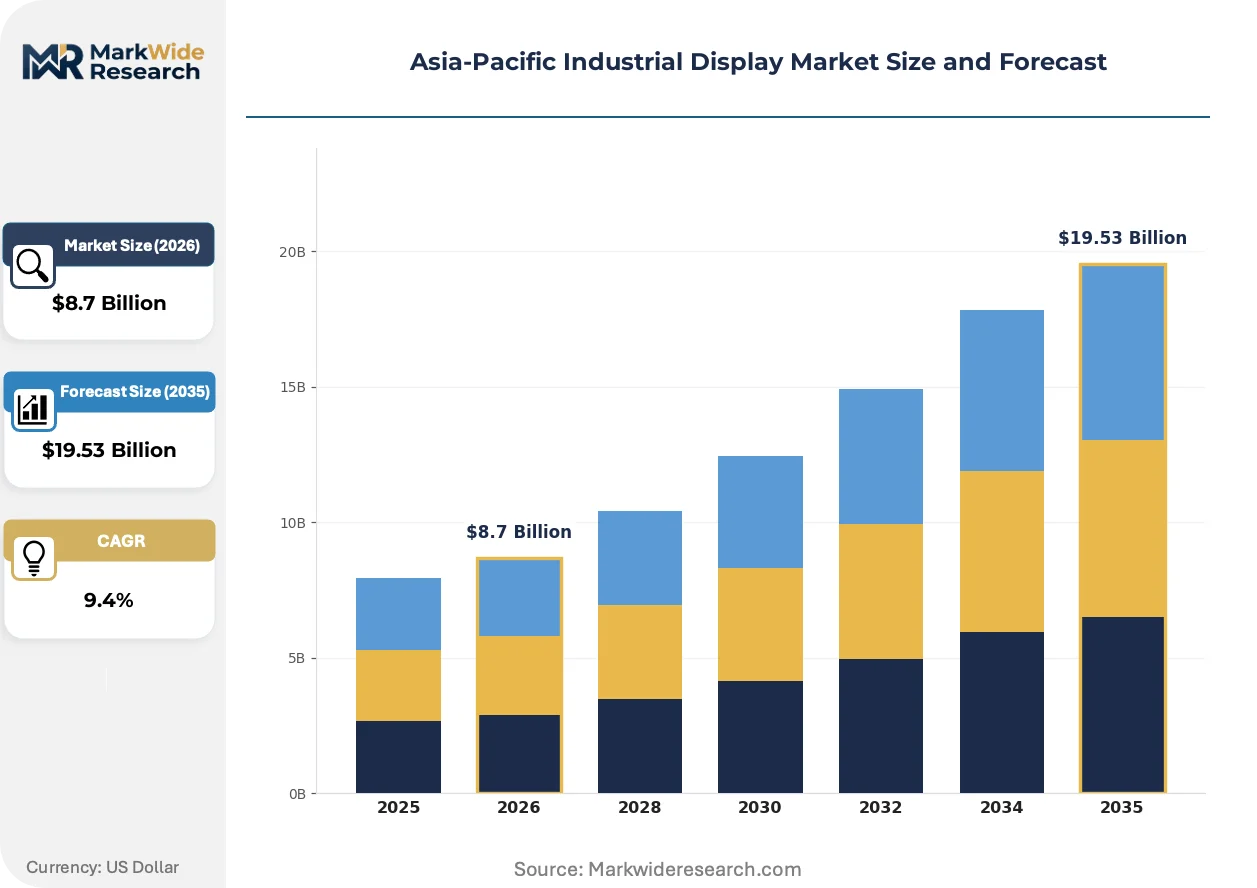
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, Plasma Application: Manufacturing, Transportation, Retail, Energy End User: Aerospace, Automotive Suppliers, Food Processing, Pharmaceutical Technology: Touchscreen, Projection, Digital Signage, Virtual Reality |
| Companies Covered | Winmate, NEC Display Solutions, Advantech, Panasonic Holdings Corporation, Sharp, AU Optronics, BOE Technology Group, LG Display, Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Display Market Strategic Shifts
Display technology evolution and procurement model restructuring are compressing traditional supplier hierarchies while regulatory divergence forces parallel product development tracks.
Projected capacitive touch layers with chemically strengthened cover glass are penetrating pharmaceutical cleanrooms and food processing facilities. Korean automotive suppliers are specifying these interfaces for glove-compatible operation at accelerated validation schedules. Resistive touch technology is rendering obsolete in premium cleanroom deployments where contamination control demands non-mechanical input surfaces.
METI's administration of JIS standards for display reliability in hazardous environments is tightening ingress protection and electromagnetic compatibility thresholds. Japanese petrochemical and mining equipment builders must now certify panels for explosive atmosphere compatibility, extending development cycles. Taiwan-based system integrators serving Japanese end-users are absorbing compliance costs through captive testing facilities rather than third-party laboratories.
Extended warranty bundling is displacing discrete aftermarket service contracts as the dominant commercial structure. OEMs serving China's automotive supplier corridor now embed remote diagnostics and predictive maintenance into initial equipment contracts, compressing independent service provider margins. This unbundling reversal is most visible in Suzhou and Shenzhen, where pharmaceutical packaging line operators prioritize total cost of ownership over upfront hardware expenditure.
Asia-Pacific Industrial Display Market Segmentation
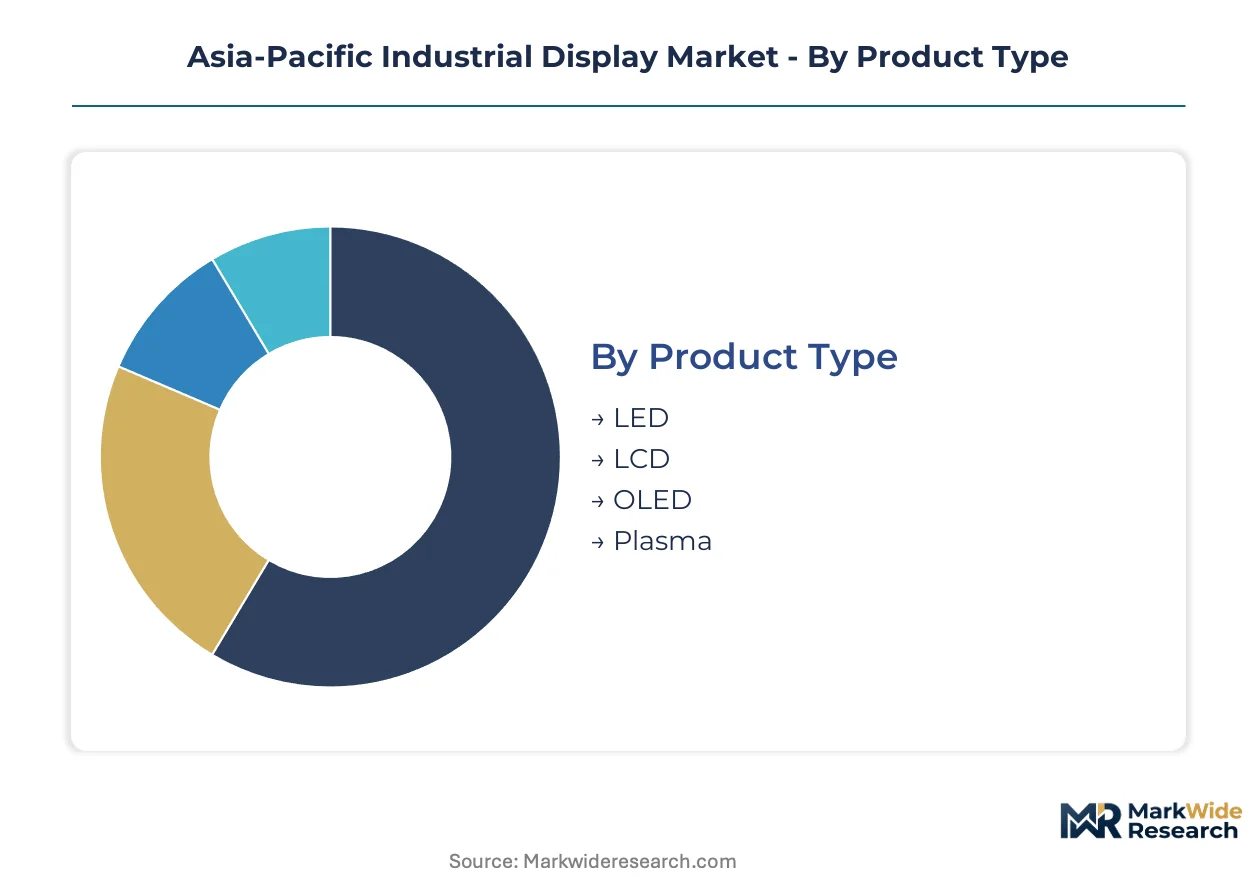
Industrial display procurement patterns diverge sharply across hardware specifications, deployment environments, and interface technologies. Stakeholders configure product platforms around certification requirements, operating temperature ranges, and backward compatibility constraints that vary by end-use sector.
Product Type:
Display hardware selection hinges on luminance requirements, backlight longevity, and total cost of ownership calculations across cleanroom, outdoor, and hazardous environment deployments.
- LED:Direct-view LED architectures deliver superior luminance and operational lifespan for transportation hubs and energy control centers. China's MIIT energy-efficiency mandates are accelerating LED retrofits across eastern manufacturing corridors.
- LCD:Ruggedized LCD panels with wide operating temperature ranges dominate semiconductor fabrication facilities in Taiwan and South Korea. Proven supply chains and cost sensitivity sustain volume leadership despite premium display alternatives.
- OLED:Self-emitting diode technology commands aerospace cockpit and automotive supplier applications where reliability certifications and contrast ratios justify procurement premiums.
- Plasma:Legacy plasma installations persist in select industrial monitoring contexts where burn-in resistance and color accuracy retain niche utility.
Established volume favors LCD; emerging adoption favors LED.
Application:
Deployment environments impose distinct ingress protection, electromagnetic compatibility, and interface durability specifications.
- Manufacturing:Factory floor visualization systems integrate HMI controllers with hardened displays for process monitoring. Taiwan and South Korean fab buildouts are compressing procurement timelines for ruggedized panels.
- Transportation:Digital signage across rail terminals and airports requires high-brightness direct-view architectures. LED migration is displacing LCD-based installations for longevity advantages.
- Retail:Customer-facing displays in pharmaceutical and food processing contexts prioritize glove-compatible touch interfaces.
- Energy:Control center operators specify wide-gamut panels for SCADA visualization and grid monitoring across Australia's critical infrastructure.
Manufacturing commands current procurement volumes; transportation infrastructure drives the steepest expansion trajectory.
End User:
Industry-specific regulations and contamination protocols dictate display certification pathways and interface hygiene requirements.
- Aerospace:Cockpit display systems require FAA-equivalent reliability certifications and extreme temperature resilience. Korean and Japanese equipment builders specify OLED panels for avionics applications.
- Automotive Suppliers:Production line HMI systems in China's eastern corridor demand backward-compatible signaling protocols. Suzhou and Shenzhen plants are consolidating controller and display purchases into integrated platforms.
- Food Processing:Glove-compatible projected capacitive touch layers with chemically strengthened cover glass are penetrating cleanroom deployments.
- Pharmaceutical:India's BIS tightening and Australia's TGA requirements are extending approval timelines for medical device manufacturing panels.
Automotive suppliers anchor near-term demand; pharmaceutical cleanrooms exhibit the fastest technology refresh cycles.
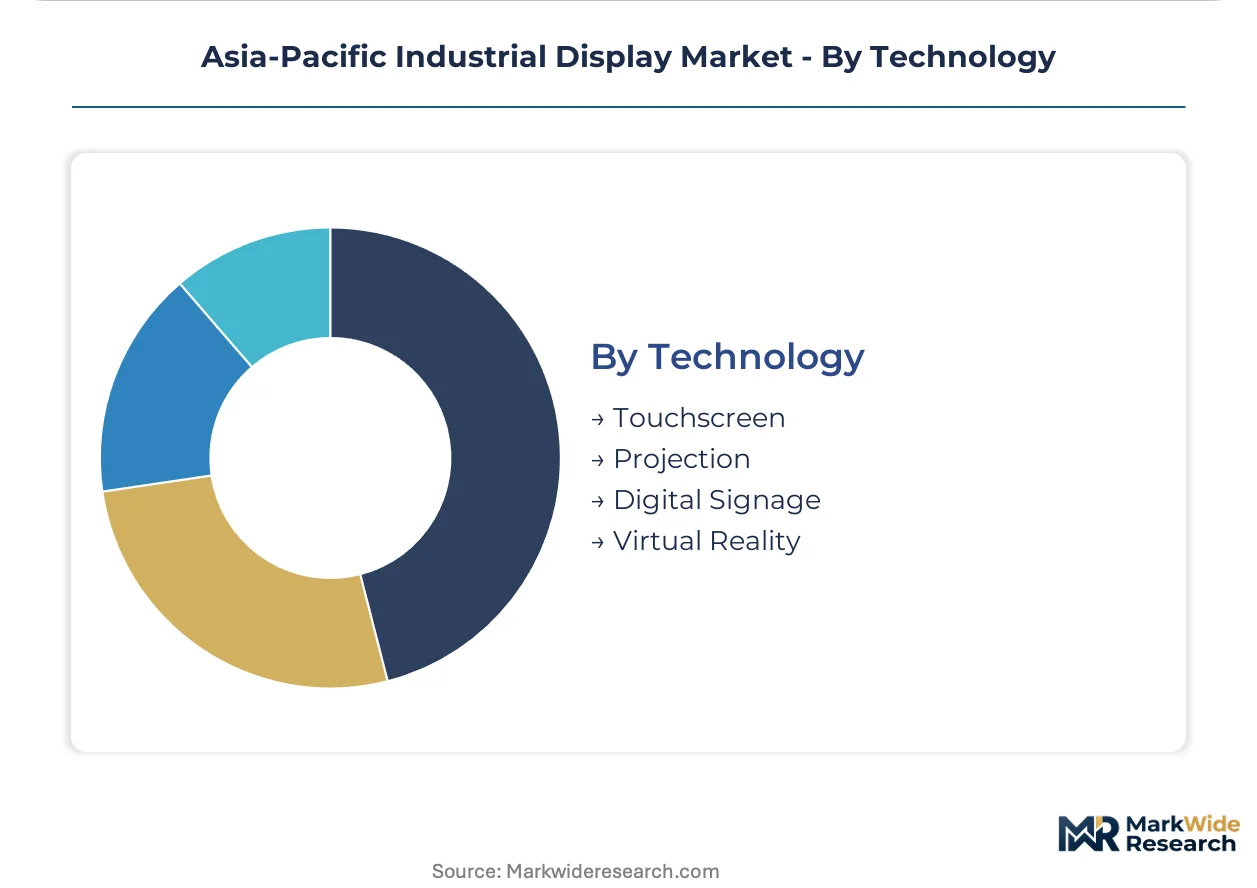
Technology:
Interface modalities are restructuring around contamination control, remote diagnostics capability, and operator training requirements.
- Touchscreen:Projected capacitive layers with glove-compatible operation are displacing mechanical button arrays. Korean automotive suppliers are specifying accelerated validation schedules for these interfaces.
- Projection:Large-format visualization for collaborative engineering and training environments retains utility where physical display footprint constraints apply.
- Digital Signage:Networked content distribution systems serve transportation and energy control applications across the region.
- Virtual Reality:Immersive training and remote maintenance assistance are emerging in Japanese petrochemical and mining equipment sectors.
Touchscreen interfaces dominate current procurement; virtual reality training systems are climbing the fastest among emerging modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive Gen 10.5 LCD fab capacity concentrates supply leverage among Korean and Japanese equipment builders, while China's MIIT energy mandates force simultaneous redesign of backlight architectures across eastern manufacturing corridors.
China
Automotive supplier plants and pharmaceutical packaging lines in Shanghai, Suzhou, and Shenzhen drive panel refresh cycles. MIIT GB standards for electromagnetic compatibility and energy consumption filter non-compliant display modules from industrial equipment certification pathways. The Yangtze River Delta manufacturing belt absorbs the bulk of LED retrofit demand as energy-efficiency mandates compress procurement timelines.
Japan
Petrochemical and mining equipment builders require JIS-certified panels for explosive atmosphere compatibility. METI administration of display reliability standards tightens ingress protection and electromagnetic compatibility thresholds. Nagoya-based system integrators serving domestic end-users absorb compliance costs through captive testing facilities rather than third-party laboratories.
South Korea
Semiconductor fabrication facilities accelerate procurement of ruggedized LCD and LED panels for cleanroom monitoring and process visualization. MFDS and KOSHA frameworks govern pharmaceutical and workplace safety interfaces. The Seoul Capital Area anchors demand from memory and logic chip foundries upgrading environmental monitoring systems.
Taiwan
Semiconductor fabrication concentration compresses procurement timelines for ruggedized visualization systems. Taiwan-based system integrators absorb Japanese compliance costs through captive testing facilities. The Hsinchu Science Park corridor generates concentrated demand for wide-temperature-range panels in wafer processing environments.
India
Medical device manufacturing and critical infrastructure applications face tightening local testing requirements. BIS expansion of domestic certification pathways creates first-mover advantages for assembly partnerships. Maharashtra and Gujarat industrial corridors exhibit rising procurement of imported panels for pharmaceutical packaging line modernization.
Asia-Pacific Industrial Display Market Competitive Environment
Embedded computing heritage and captive fab capacity split the market between integrated platform specialists and upstream panel suppliers. The vendor base organizes around three strategic archetypes: HMI-display convergence players, captive LCD fabricators, and OLED reliability certifiers. Consolidation pressure intensifies as factory automation buyers merge separate controller and display purchases. Capacity expansion and strategic partnerships dominate competitive maneuvering.
Within the integrated platform tier, Advantech leverages its embedded computing heritage. Among captive fabricators, BOE Technology Group anchors supply through Gen 10.5 LCD capacity. On the premium reliability vector, Samsung Electronics competes on OLED certifications for aerospace and automotive applications. These three exemplify the strategic archetypes reshaping procurement relationships across the region.
| Leading Market Players |
|---|
| Winmate |
| NEC Display Solutions |
| Advantech |
| Panasonic Holdings Corporation |
| Sharp |
| AU Optronics |
| BOE Technology Group |
| LG Display |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Captive Gen 10.5 LCD fab capacity in China concentrates upstream supply leverage among Korean and Japanese equipment builders, compressing margin pools for downstream integrators while OEMs extract value through extended warranty bundling and remote diagnostics.
Pricing Analysis
MIIT GB standards dictate the pricing tier structure across the Asia-Pacific industrial display market. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified explosion-proof panels from standard wide-temperature units and unbranded commodity displays. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because BOE's captive fab capacity floods mid-market supply. Automotive supplier plants in Suzhou exhibit the highest price sensitivity, while aerospace cockpit integrators accept substantial premiums for OLED reliability certifications.
Supply Chain Analysis
Export control regimes on advanced lithography equipment and semiconductor manufacturing tools limit technology flows into Chinese display fabrication, forcing parallel supply chain development. Geographic supply concentration centers on China, South Korea, and Taiwan for panel substrates and driver IC production. Raw material dependencies include rare earth phosphors for LED backlighting, chemically strengthened cover glass for touch layers, and high-purity silicon for TFT backplanes. Single-source vulnerability in specialized driver IC substrates creates structural risk for lead times. Distribution runs through system integrators serving fab buildouts and OEM direct contracts with automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of certified cleanroom-compatible touch interface engineering talent constrains product development velocity, creating durable advantages for incumbents with captive testing infrastructure and forcing new entrants toward partnership models.
For Market Incumbents: Harden certification moats by investing in captive METI JIS and MFDS testing facilities rather than third-party laboratory dependencies. Deepen backward integration into driver IC substrate sourcing to blunt rare earth phosphor price volatility. Consolidate controller and display purchases into integrated HMI platforms to compress independent service provider margins.
For New Entrants and Emerging Players: Build out domestic assembly partnerships in Maharashtra and Gujarat to capture first-mover advantages from India's BIS tightening on imported industrial panels. Target pharmaceutical cleanroom retrofit cycles where glove-compatible projected capacitive interfaces displace resistive technology. Lead with accelerated validation schedules for Korean automotive supplier specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward embedded computing heritage players with factory automation platform integration capabilities. Long-term viability over the coming decade hinges on controlling HMI-display convergence architecture rather than commodity panel supply. Watch for inflection when LED direct-view retrofits in transportation hubs exceed LCD replacement volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Certification Facility Investment | METI JIS and MFDS testing infrastructure accelerates approval timelines for Japanese and Korean end-users. |
| Backward Integration into Driver IC Substrates | In-house substrate production insulates margin buffers from rare earth phosphor price instability. |
| HMI-Display Platform Convergence | Integrated controller-display architectures capture factory automation procurement consolidation in China's eastern corridor. |
| LED Direct-View Manufacturing Scale-Up | Capacity expansion targets transportation hub and energy control center migration from LCD architectures. |
| Domestic Assembly Partnership in India | Maharashtra and Gujarat facilities exploit BIS tightening to displace imported panel market share. |
Study Parameters
Initial hypotheses were tested against primary input from fab equipment procurement managers, pharmaceutical cleanroom engineering directors, automotive tier supplier plant engineers, and industrial display system integrators and refined through secondary validation against MIIT GB standard filings, METI JIS certification registries, Korea MFDS medical device interface approvals, and customs trade data for panel substrate imports. Bottom-up demand modeling triangulated against top-down manufacturing investment tracking across semiconductor fabrication facilities.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions included display technology, application environment, end-user industry, and interface modality. CAGRs were derived from unit shipment trajectories and average selling price evolution across certification tiers. Industry-specific forecast inputs incorporated MIIT energy-efficiency mandate compliance timelines and semiconductor fab capital expenditure cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported display fabricators or sudden relaxation of export control regimes would shift outcomes. Material shifts in rare earth phosphor refining concentration or BIS certification pathway acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
IGZO Display Market
Display Technologies
Electronic Display Market
Display Technologies
4K Technology Market
Display Technologies
OLED Display Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Foldable Screens Market
Display Technologies
Global OLED Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Industrial Display Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Foldable Display Market
Display Technologies
Display Material Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Electrochromic Window Market