
 Field Emission Display Market | 2026-2036
Field Emission Display Market Size, Share, and Industry Trends Forecast 2026-2036
Field Emission Display Market Analysis
A wide capability gap between capital-heavy panel producers and specialized emitter developers is reorganizing competitive tiers in the Field Emission Display industry. Samsung Electronics Co., Ltd. leverages its vertically integrated semiconductor foundry network to control critical cathode material supply chains. LG Display Co., Ltd. anchors large-format production through dedicated fab capacity in Paju. Canon Inc. differentiates by sustaining proprietary electron emitter lithography equipment that downstream panel makers depend upon.
Field Emission Display denotes a vacuum microelectronic display technology utilizing arrays of cold cathode field emitters—typically Spindt-type metal tips or carbon nanotube structures—to excite phosphor coatings without heated filaments, achieving luminance exceeding 1000 cd/m² at sub-millisecond response times for high-contrast imaging in ambient light. The technology serves medical imaging and professional design applications where color accuracy and motion clarity override cost sensitivity. Self-emissive architectures dominate current revenue contribution owing to their simpler pixel drive circuitry and mature manufacturing templates. Quantum dot enhancement layers represent the fastest-growing technology segment as emitters pair with narrow-band color converters to meet broadcast-grade color gamut specifications. Automotive end-user demand is expanding fastest among application categories, driven by head-up display integration and instrument cluster digitization requiring wide operating temperature ranges.
Japan's PMDA imposes electromagnetic compatibility and optical safety standards on medical imaging displays that field emission technologies must satisfy for diagnostic equipment certification. The US FDA maintains parallel requirements for radiological display systems under 21 CFR 1020.32, restricting market access to validated panel suppliers. South Korea's MFDS coordinates with KATS on display product safety frameworks that govern automotive cockpit installations. Stakeholders must monitor cathode material sourcing constraints and phosphor supply chain concentration as production scales beyond pilot volumes.
Market Dynamics
Carbon nanotube cathode deposition is compressing manufacturing timelines while tightening emitter-to-phosphor alignment tolerances across panel fabs. This process shift is forcing capital reallocation from legacy Spindt-type metal tip equipment toward atomic-layer deposition systems capable of sub-10-nanometer coating uniformity.
Growth Catalysts
- Aerospace cockpit digitization:Wide-temperature operation requirements in avionics are pulling field emission displays into head-up display and instrument cluster retrofits. FAA airworthiness certification pathways for vacuum microelectronic displays are streamlining compared to liquid-crystal alternatives.
- Japan's METI energy-efficiency standards:Tightening luminous efficacy mandates for professional displays are advantaging cold cathode architectures over backlit panels in medical imaging procurement. PMDA diagnostic equipment frameworks now reference field emission color gamut specifications.
- Carbon nanotube synthesis advances:Chemical vapor deposition yield improvements at South Korea's Gyeonggi Province manufacturing corridor are reducing cathode material unit costs. Localized phosphor coating expertise in Paju is accelerating panel assembly throughput.
Market Restraints
- Phosphor supply concentration:Rare-earth element processing for high-purity europium and terbium phosphors concentrates in Chinese smelting operations, creating price volatility exposure for downstream panel assemblers.
- Vacuum sealing capex intensity:Field emission displays require hermetic glass-to-metal sealing equipment costing multiples of ambient-pressure display assembly lines, elevating break-even volumes for new entrants.
- OLED substitution threat:Organic electroluminescent panels are capturing medical imaging and automotive cockpit contracts where field emission previously held technical advantages in response time and luminance.
Strategic Opportunities
- Quantum dot enhancement convergence:Pairing carbon nanotube emitters with narrow-band color converters is opening broadcast-grade color gamut applications previously unreachable by vacuum microelectronic technology alone.
- US FDA 21 CFR 1020.32 radiological display validation:Field emission panels satisfying FDA diagnostic imaging requirements command premium positioning in radiology workstation procurement cycles.
- Automotive HUD integration:South Korea's KATS vehicle safety frameworks are mandating wider operating temperature ranges for instrument cluster displays, creating specification gaps that field emission architectures fill.
Industry Challenges
- Field emission lithography talent scarcity:Electron emitter patterning expertise concentrates among legacy vacuum tube engineers and semiconductor photomask specialists, with limited training pipeline expansion.
- Multi-regulatory certification timelines:Simultaneous pursuit of Japan PMDA electromagnetic compatibility, US FDA optical safety, and South Korea MFDS automotive approvals extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Emission Display Market |
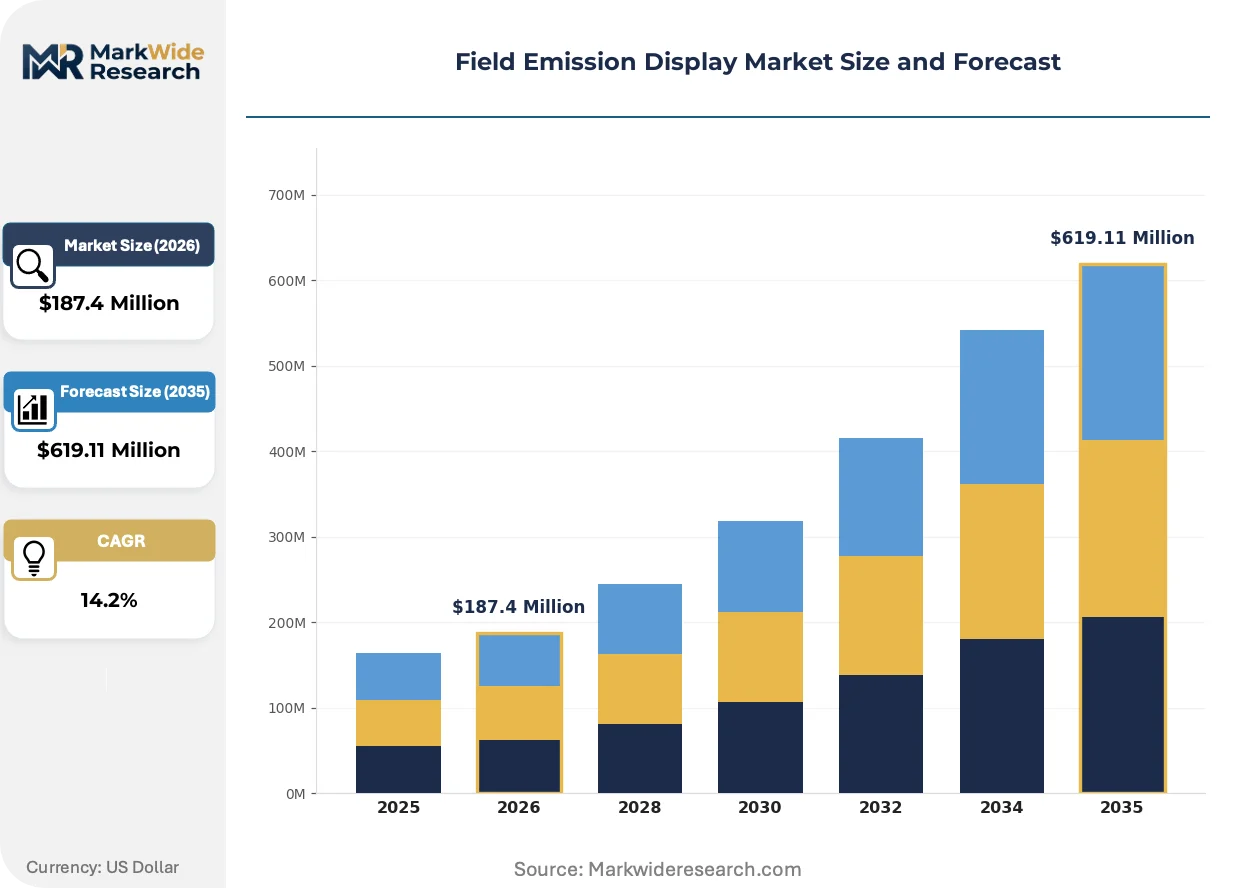
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
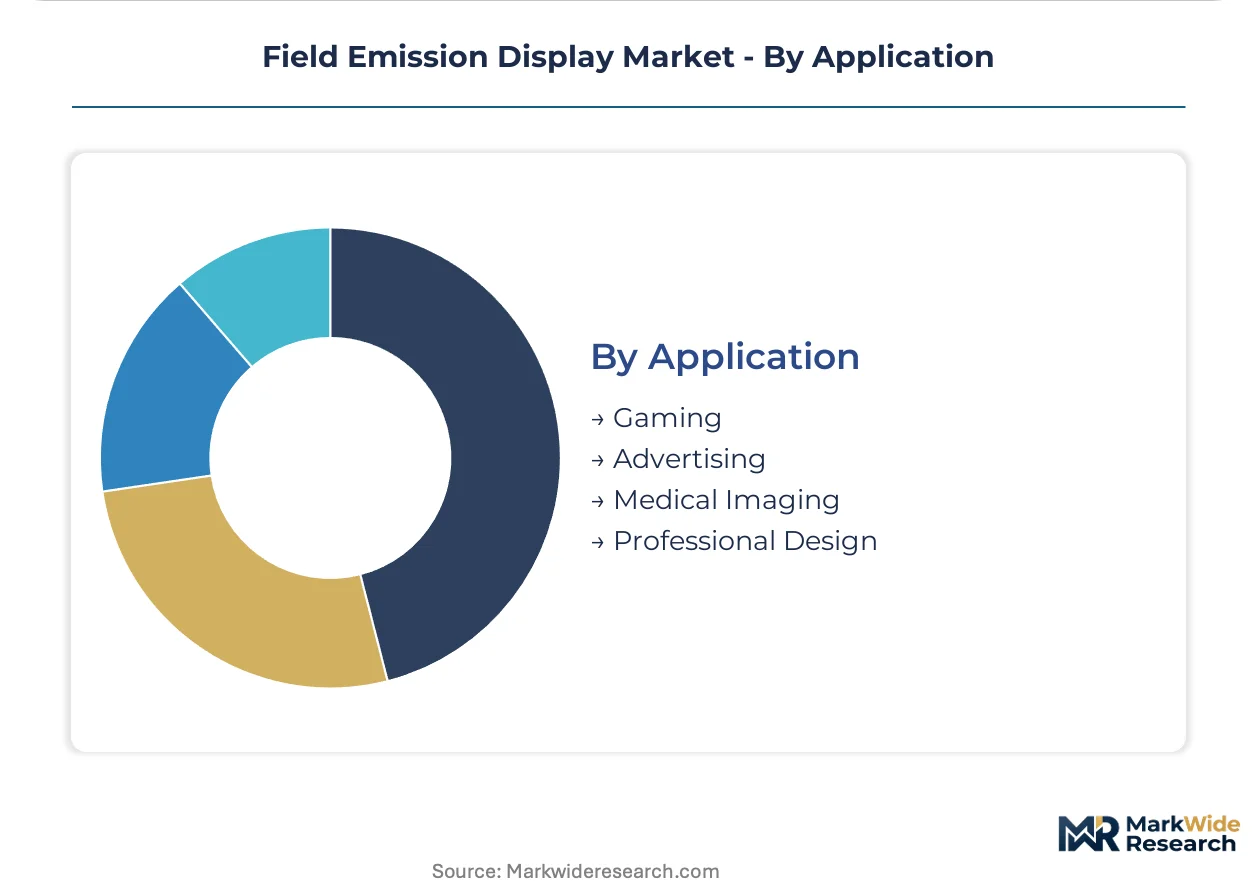
| Segmentation | Product Type: Monitors, TVs, Wearables, Digital Signage Technology: Self-Emissive, Quantum Dot, OLED, Micro LED End User: Commercial, Residential, Educational, Automotive Application: Gaming, Advertising, Medical Imaging, Professional Design |
| Companies Covered | LG Display Co., Ltd., Samsung Electronics Co., Ltd., Sharp Corporation, Japan Display Inc., Sony Corporation, Panasonic Corporation, AU Optronics Corp., Canon Inc., Universal Display Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Emission Display Market Emerging Trajectories
Manufacturing physics and regulatory specification tightening are jointly compressing emitter geometries while expanding addressable application spaces. These forces are reconfiguring equipment procurement priorities and buyer qualification workflows across the value chain.
Carbon nanotube field emitter arrays are miniaturizing tip diameters below 50 nanometers while maintaining emission current stability. Medical imaging OEMs in Japan and South Korea are qualifying these architectures for mammography and pathology workstation integration. The dimensional reduction is miniaturizing pixel pitch to sub-10-micron levels, enabling 8K resolution in 32-inch diagnostic formats previously constrained by Spindt-type metal tip density limits.
Europe's RoHS substance restrictions and REACH chemical registration requirements are constraining phosphor coating chemistries in displays imported or manufactured within EU member states. Manufacturers are reformulating cadmium-free quantum dot enhancement layers to maintain color performance under tightened hazardous substance thresholds. Automotive cockpit display suppliers serving European OEMs are accelerating alternative phosphor qualification to avoid supply interruption under evolving restricted substance lists.
Buyer consolidation among medical imaging equipment OEMs is compressing supplier qualification cycles and elevating volume commitment thresholds. Tier-one radiology workstation assemblers in South Korea and Japan are consolidating cathode material procurement under multi-year supply agreements, displacing spot-market sourcing. This concentration is most visible in Gyeonggi Province, where Samsung Electronics and LG Display captive demand now absorbs majority output from regional carbon nanotube synthesis facilities.
Field Emission Display Market Segmentation
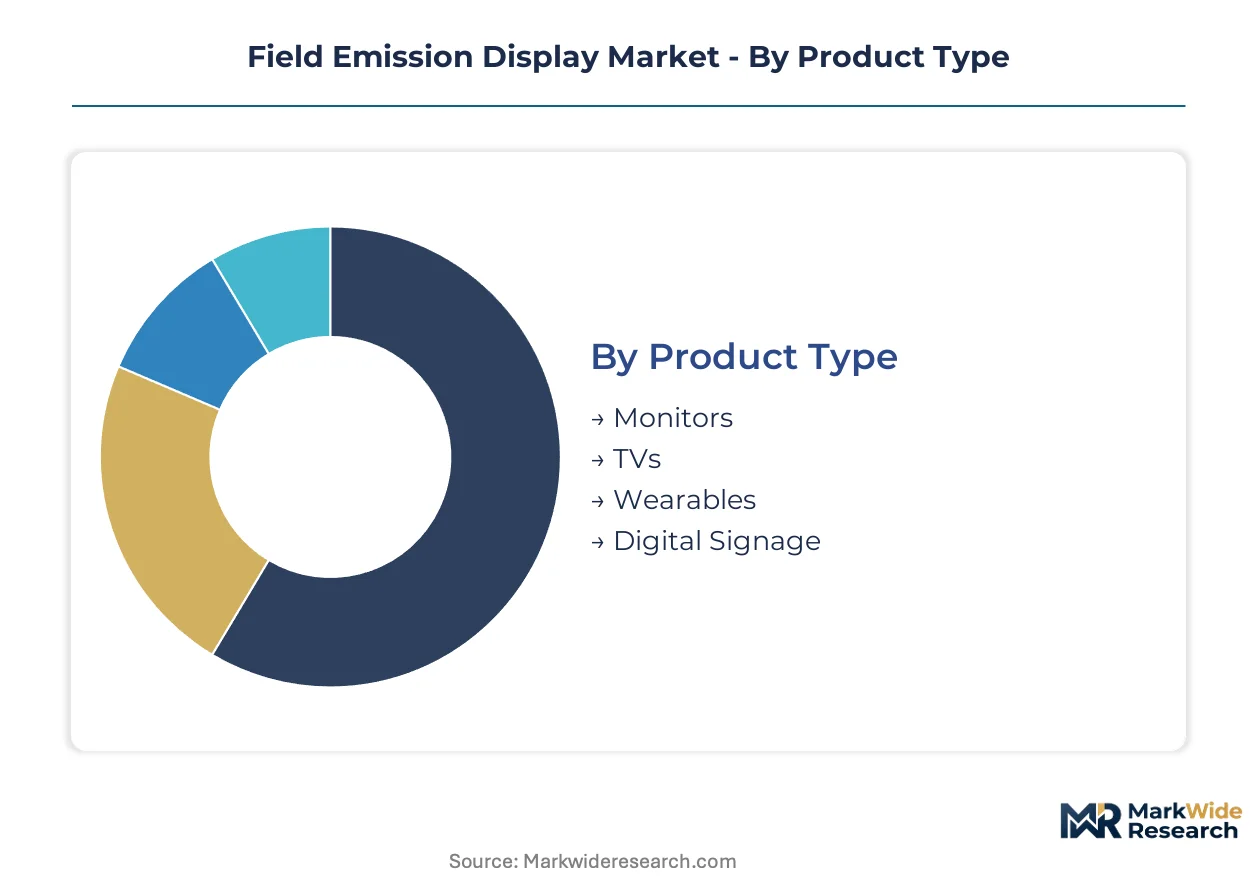
Field emission display segmentation reveals how technical specifications align with regulatory environments and manufacturing capabilities across distinct buyer categories. Each dimension carries unique supply chain and certification requirements that shape procurement patterns.
Product Type:
Domestic consumption in Japan and South Korea concentrates in medical-grade monitors and automotive cockpit displays, while export volumes flow toward European digital signage and North American professional workstations.
- Monitors:Diagnostic imaging panels dominate procurement in Japan's PMDA-regulated healthcare infrastructure. South Korean radiology workstation assemblers in Gyeonggi Province now specify sub-10-micron pixel pitch for 8K pathology formats. FDA 21 CFR 1020.32 validation requirements restrict supplier pools to validated panel makers.
- TVs:Broadcast-grade color gamut specifications drive quantum dot enhancement layer adoption. Japanese METI energy-efficiency standards advantage cold cathode architectures over backlit alternatives in professional display procurement.
- Wearables:Miniaturized field emitter arrays serve military and industrial head-mounted applications requiring wide temperature operation.
- Digital Signage:EU RoHS and REACH compliance requirements constrain phosphor chemistries for displays manufactured or imported into European markets.
Monitors hold the largest share; momentum sits with digital signage as European OEMs accelerate alternative phosphor qualification.
Technology:
Cost tiers separate mature vacuum microelectronic architectures from emerging quantum dot pairings that command premium positioning in broadcast and medical applications.
- Self-Emissive:Simpler pixel drive circuitry and mature manufacturing templates anchor current revenue contribution. Canon's proprietary electron emitter lithography equipment remains a critical dependency for downstream panel makers.
- Quantum Dot:Narrow-band color converters paired with carbon nanotube emitters unlock broadcast-grade color gamut applications. Samsung Electronics leverages vertically integrated semiconductor foundry networks to control cathode material supply chains for this architecture.
- OLED:Organic electroluminescent panels capture medical imaging and automotive contracts where field emission previously held technical advantages.
- Micro LED:Chip-scale emitter arrays compete for head-up display integration requiring extreme luminance in compact form factors.
Self-emissive technology commands the largest installed base; quantum dot enhancement layers are expanding most quickly as emitters pair with narrow-band converters.
End User:
Customer type determines volume scale and certification burden, with automotive and commercial buyers imposing the most stringent multi-regulatory approval timelines.
- Commercial:Medical imaging OEM consolidation compresses supplier qualification cycles and elevates volume commitment thresholds. Tier-one radiology workstation assemblers now lock cathode material procurement under multi-year supply agreements.
- Automotive:South Korea's KATS vehicle safety frameworks mandate wider operating temperature ranges for instrument cluster displays. FAA airworthiness certification pathways for vacuum microelectronic displays streamline compared to liquid-crystal alternatives in aerospace applications.
- Residential:Price-sensitive demand concentrates in Asian markets with established field emission manufacturing infrastructure.
- Educational:Institutional procurement favors cost-optimized panels with standard color gamut specifications.
Commercial end users generate the largest revenue share; automotive applications are climbing the fastest driven by head-up display integration and instrument cluster digitization.
Application:
Application-specific performance requirements stratify pricing across professional-grade certifications and consumer-oriented specifications.
- Medical Imaging:Mammography and pathology workstation integration in Japan and South Korea demands carbon nanotube field emitter arrays with tip diameters below 50 nanometers. PMDA electromagnetic compatibility and optical safety standards govern diagnostic equipment certification.
- Professional Design:Color accuracy and motion clarity requirements override cost sensitivity in broadcast and creative workstation procurement. LG Display anchors large-format production through dedicated fab capacity in Paju.
- Gaming:Sub-millisecond response times attract enthusiast segments seeking high-contrast imaging in ambient light conditions.
- Advertising:Digital out-of-home networks prioritize luminance and durability over color precision.
Medical imaging holds the largest share; professional design applications show the steepest expansion trajectory as broadcast-grade specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes field emission displays predominantly for PMDA-certified diagnostic imaging, while South Korea deploys identical hardware for automotive cockpit digitization and broadcast workstations. This divergence in end-use application shapes divergent certification burdens and supply chain configurations across the two manufacturing centers.
Japan
Medical imaging OEMs in Tokyo and Osaka drive procurement of mammography-grade panels with sub-50-nanometer emitter tip specifications. METI energy-efficiency standards tighten luminous efficacy mandates annually, advantaging cold cathode architectures in hospital procurement cycles. Canon Inc. sustains proprietary electron emitter lithography equipment in Kanto that downstream panel makers depend upon for PMDA compliance.
South Korea
Gyeonggi Province manufacturing corridors absorb majority output from regional carbon nanotube synthesis facilities for automotive HUD integration. KATS vehicle safety frameworks mandate wider operating temperature ranges for instrument cluster displays than liquid-crystal alternatives satisfy. LG Display anchors large-format production through dedicated fab capacity in Paju, locking cathode material procurement under multi-year supply agreements.
United States
FAA airworthiness certification pathways for vacuum microelectronic displays streamline compared to liquid-crystal alternatives in aerospace cockpit retrofits. FDA 21 CFR 1020.32 radiological display validation restricts supplier pools to validated panel makers for radiology workstation procurement. Defense contractors in California and Texas specify miniaturized field emitter arrays for military head-mounted applications requiring wide temperature operation.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg qualify field emission panels for head-up display integration under KBA vehicle type approval frameworks. EU RoHS substance restrictions and REACH chemical registration requirements constrain phosphor coating chemistries for displays manufactured or imported into European markets. Industrial equipment manufacturers in North Rhine-Westphalia specify high-luminance panels for machine vision systems in ambient light conditions.
Field Emission Display Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the field emission display industry. Samsung Electronics Co., Ltd. and LG Display Co., Ltd. control critical cathode material supply chains through captive semiconductor foundry networks and dedicated fab capacity respectively. Three strategic archetypes populate the competitive map: vertically integrated display conglomerates, specialized vacuum microelectronic equipment suppliers, and quantum dot enhancement layer developers. Dominant competitive moves include backward integration into carbon nanotube synthesis and multi-year supply agreement locking for rare-earth phosphor procurement.
Within the integrated conglomerate tier, Samsung Electronics Co., Ltd. and LG Display Co., Ltd. exemplify scale-driven positioning through Gyeonggi Province manufacturing concentration. Canon Inc. occupies a distinct equipment-supplier archetype, sustaining lithography dependencies among downstream panel makers. Japan Display Inc. represents the specialist fabrication model, serving medical imaging OEMs with PMDA-aligned certification workflows. These three anchors illustrate how geographic clustering around regulatory hubs shapes competitive differentiation more than technology alone.
| Leading Market Players |
|---|
| LG Display Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Sharp Corporation |
| Japan Display Inc. |
| Sony Corporation |
| Panasonic Corporation |
| AU Optronics Corp. |
| Canon Inc. |
| Universal Display Corporation |
| Others |
Supply Flow & Price Mechanics
Carbon nanotube cathode deposition replacing legacy Spindt-type metal tip fabrication is redrawing procurement geography toward South Korea's Gyeonggi Province while compressing unit economics through atomic-layer deposition yield improvements. This substitution dynamic concentrates pricing power among vertically integrated panel producers with captive semiconductor foundry networks, squeezing margins for equipment-dependent assemblers locked into Canon's proprietary lithography dependencies.
Pricing Analysis
After-sales service contracts and extended warranty bundles now drive lifetime value capture beyond initial panel transactions. Three-tier pricing structure across PMDA-certified diagnostic, KATS-compliant automotive, and standard commercial tiers separates procurement pools by certification burden rather than raw manufacturing cost. Price differentiation hinges on FDA 21 CFR 1020.32 validation status and carbon nanotube synthesis yield grades. Cost compression in commercial signage tiers is intensifying because OLED substitution threatens volume scale in ambient-light applications. Educational and institutional buyers exhibit highest price sensitivity; medical imaging OEMs locked into multi-year cathode supply agreements show least.
Supply Chain Analysis
Inventory buffers for rare-earth phosphor precursors have compressed to 6-8 weeks as europium and terbium processing concentrates in Chinese smelting operations. Carbon nanotube synthesis feeds from South Korea's Gyeonggi corridor and Japan's Kanto equipment cluster; phosphor coating expertise centers on Paju and Osaka medical-grade facilities. Single-source vulnerability in hermetic glass-to-metal sealing equipment elevates break-even thresholds for new panel assembly entrants. Distribution runs through tier-one radiology workstation assemblers in Tokyo and Seoul, with spot-market sourcing displaced by multi-year cathode procurement agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where simultaneous PMDA, FDA, and MFDS certification requirements create 18-24 month barriers that capital-heavy incumbents exploit against underfunded challengers.
For Market Incumbents: Secure backward integration into carbon nanotube synthesis capacity within South Korea's Gyeonggi Province to neutralize cathode material sourcing constraints threatening production scale. Lock multi-year rare-earth phosphor supply agreements before europium price volatility escalates. OLED substitution in automotive cockpit contracts demands accelerated quantum dot enhancement layer R&D to preserve technical differentiation in head-up display luminance specifications. For New Entrants and Emerging Players: FDA 21 CFR 1020.32 radiological display validation fast-tracks offer the most penetrable entry path for premium positioning in North American diagnostic imaging procurement cycles. Target European digital signage white-space where RoHS phosphor reformulation requirements displace incumbent chemistries. Partner with Canon's electron emitter lithography equipment installed base rather than competing on capital-intensive vacuum sealing fab buildouts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vacuum microelectronic equipment specialists holding proprietary patterning IP and installed base dependencies among tier-one panel makers. Five-to-ten year viability hinges on carbon nanotube yield convergence with OLED cost curves in medical and automotive segments. Monitor FAA airworthiness certification pathway streamlining for vacuum microelectronic displays as inflection signal for aerospace cockpit retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Nanotube Synthesis | Captive cathode material supply secures production scale against Gyeonggi Province concentration. |
| Multi-Year Rare-Earth Phosphor Supply Agreement | Locked europium and terbium procurement hedges Chinese smelting price volatility exposure. |
| FDA 21 CFR 1020.32 Validation Fast-Track | Premium radiology workstation positioning commands diagnostic imaging procurement preference. |
| Quantum Dot Enhancement Layer Development | Narrow-band color converter pairing unlocks broadcast-grade gamut applications beyond OLED reach. |
| Hermetic Sealing Equipment Partnership | Shared vacuum microelectronic fab capex reduces break-even volume thresholds for new entrants. |
Methodological Framework
Operator-level perspectives from cathode material procurement directors, vacuum microelectronic fab engineers, PMDA regulatory consultants, and radiology workstation OEM supply chain managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) radiological display filings, METI energy-efficiency standard amendments, KATS vehicle safety framework updates, and SEC 10-K display segment disclosures. Bottom-up panel production estimates triangulated against top-down medical imaging and automotive display demand forecasts.
Sensitivity analysis across carbon nanotube synthesis yield scenarios, phosphor rare-earth price bands, and OLED substitution penetration rates stress-tested projection robustness. Segmentation dimensions modeled span product type, technology architecture, end-user category, and application vertical alongside regulatory certification tier. CAGRs derived from regression against historical vacuum microelectronic display shipments and forward scenario weighting. Industry-specific inputs include FAA airworthiness certification timeline assumptions and quantum dot enhancement layer adoption curves in broadcast workstations.
Decision-makers should treat outputs as directional under base assumptions of sustained METI luminous efficacy tightening and stable Gyeonggi Province manufacturing concentration; material deviation in Chinese rare-earth export policy or OLED cost breakthroughs would warrant model refresh. Forecasts assume continued multi-regulatory certification burden without harmonization acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Foldable Screens Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Touch Screen Module Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Head Up Display Market
Display Technologies
Low Power Display Market
Display Technologies
Laptop Panels Market
Display Technologies
Display Port Market
Display Technologies
IGZO Display Market