
 3D Sensing and Imaging Market | 2026-2036
3D Sensing and Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
3D Sensing and Imaging Market Intelligence
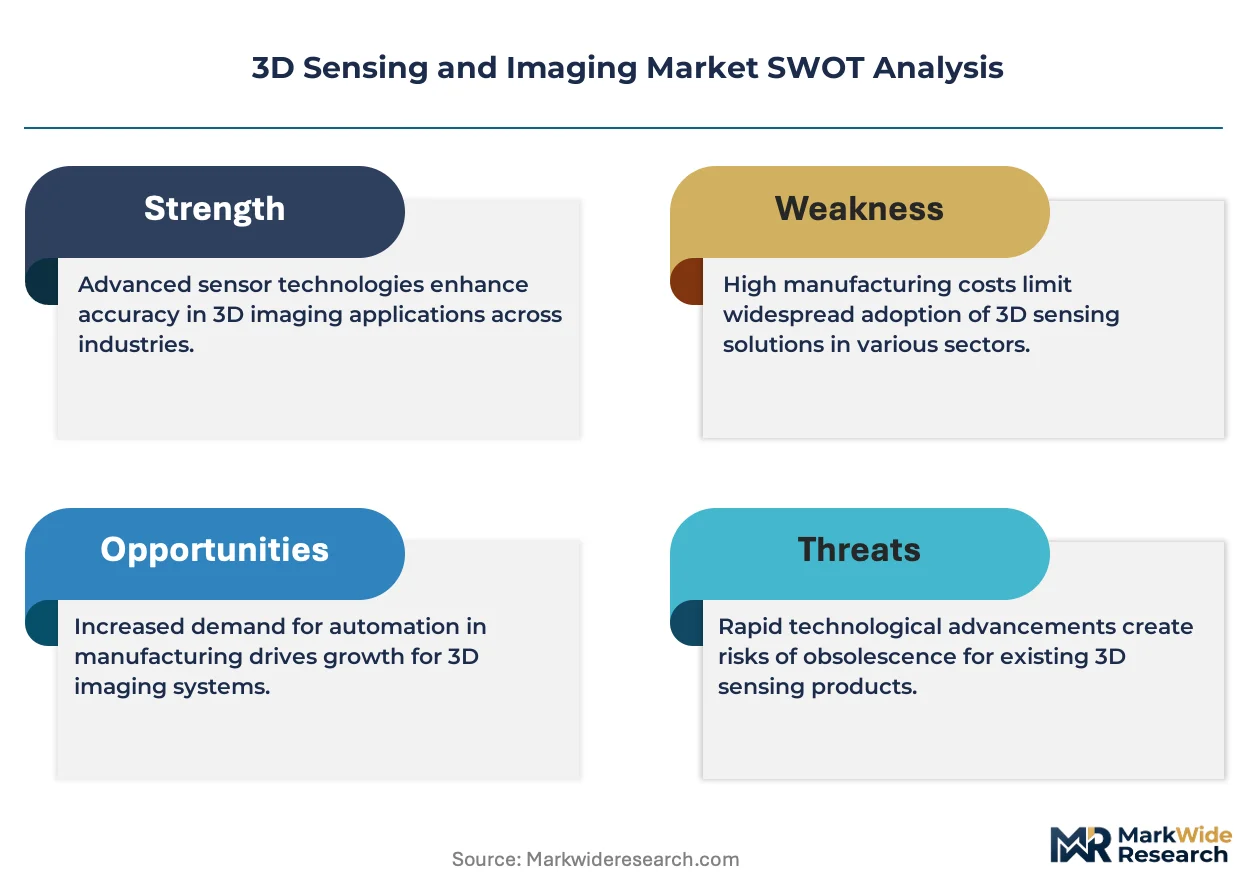
IEC 62471 photobiological safety certification is reorganizing competitive entry in infrared illumination modules for 3D sensing. Sony Group Corporation leverages its CMOS image sensor dominance to anchor supply for time-of-flight arrays in consumer devices. STMicroelectronics N.V. sustains vertical integration from MEMS fabrication to module assembly, competing directly with Infineon Technologies AG in automotive LIDAR sockets.
3D sensing and imaging encompasses technologies that capture depth, surface topology, and spatial geometry through active illumination or passive stereo correspondence, typically operating at near-infrared wavelengths between 850 and 940 nanometers to avoid visible-light interference. These systems serve industrial automation, biometric authentication, and autonomous navigation by converting optical signals into dense point clouds or depth maps. LIDAR Systems command premium pricing in automotive and aerospace deployments where millimeter-range accuracy proves essential. Time-of-Flight Sensors penetrate consumer electronics at volume scale, while Structured Light Sensors retain strength in precision metrology and facial recognition where sub-pixel resolution matters.
FDA laser product performance standards govern ophthalmic safety claims for near-infrared emitters in the United States, while the EU AI Act imposes conformity requirements on biometric identification systems deployed in European markets. IEC 60825 laser safety classifications further condition product design and market access for international shipments. Stakeholders must monitor evolving national AI governance frameworks and photonics export controls to anticipate certification burdens that will reshape sourcing strategies and regional manufacturing footprints.
Market Dynamics
Smartphone OEMs are consolidating 3D sensing module specifications around single-chip time-of-flight architectures, compressing design cycles from 18 months to under 12 months and forcing component suppliers to absorb NRE costs upfront.
Growth Catalysts
- EU AI Act biometric conformity requirements:Mandates for liveness detection in facial authentication systems are accelerating hardware refresh cycles across European consumer electronics and access control installations.
- Automotive LIDAR socket expansion:Level 2+ ADAS programs in Germany, Japan, and the United States are specifying solid-state scanning modules for highway pilot functions, pulling VCSEL array volumes upward.
- Industrial metrology automation:Structured light systems are displacing coordinate measuring machines in Shenzhen and Stuttgart precision manufacturing lines where sub-10-micron tolerance verification is required.
Market Restraints
- Indium phosphide substrate cost volatility:1550-nanometer LIDAR emitters depend on III-V compound wafer supply concentrated among Japanese and Taiwanese foundries, exposing automotive tier-1s to 20-40% spot price swings.
- IEC 60825 laser safety certification timelines:Near-infrared emitter modules face 6-9 month approval cycles that gate product launches and freeze engineering resources.
- CMOS image sensor supply concentration:Time-of-flight receiver arrays rely on captive capacity at two Japanese and Korean sensor houses, creating allocation risk during smartphone launch windows.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component assembly incentives are attracting VCSEL packaging operations to Tamil Nadu and Karnataka, creating captive supply for domestic smartphone and automotive programs.
- Digital twin convergence with photogrammetry:Integration of real-time 3D capture with industrial simulation software is opening facility-scale deployment contracts in German and South Korean automotive plants.
- Healthcare navigation robotics:FDA breakthrough device designation pathways are accelerating 3D vision module qualification for surgical and rehabilitation robot platforms in the United States.
Industry Challenges
- Multi-physics simulation talent scarcity:Optomechanical design for thermal-stable emitter arrays requires expertise spanning Zemax, COMSOL, and semiconductor packaging that commands 40% salary premiums in Munich and San Jose.
- Legacy factory system integration:Structured light metrology tools must interface with 1990s-era PLC architectures through custom OPC-UA middleware, extending deployment timelines and inflating service costs.
- IP licensing thicket around structured light patterns:Patent pools controlled by Israeli and US research institutions impose per-unit royalties that compress margins on sub-$50 consumer modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Sensing and Imaging Market |
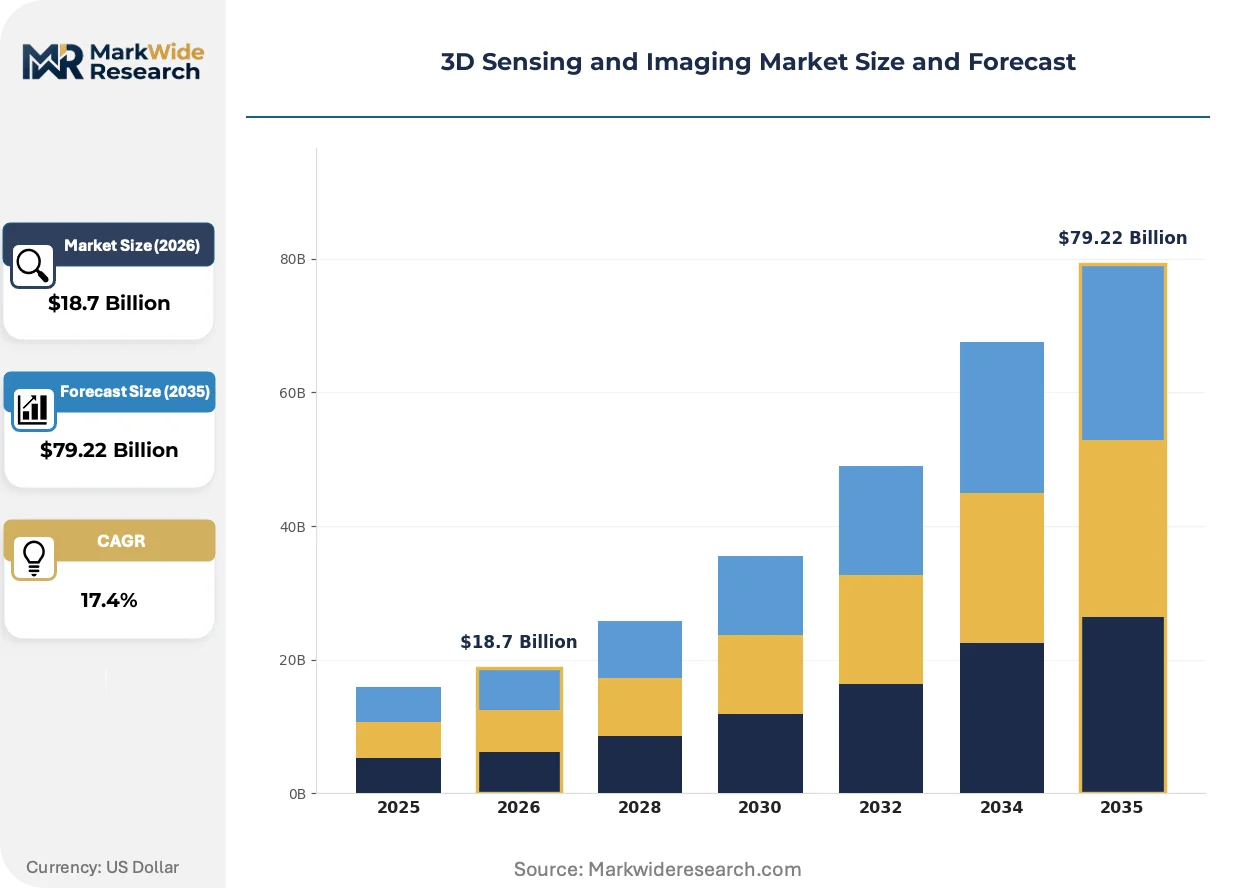
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time-of-Flight Sensors, Structured Light Sensors, Stereoscopic Cameras, LIDAR Systems, Photogrammetry Devices Technology: Laser Triangulation, Infrared, Ultrasound, Radar, Confocal Microscopy Application: Gesture Recognition, Augmented Reality, Robotics Navigation, Industrial Inspection, Security Surveillance End User: Consumer Electronics, Aerospace & Defense, Manufacturing, Agriculture, Construction |
| Companies Covered | Infineon Technologies AG, STMicroelectronics N.V., Microchip Technology Inc., Sony Group Corporation, Samsung Electronics Co., Ltd., OmniVision Technologies Inc., Qualcomm Incorporated, Keyence Corporation, Cognex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Sensing and Imaging Market Strategic Shifts & Innovations
Active illumination architectures are fragmenting into wavelength-optimized branches as end-use requirements diverge, with automotive safety mandates and consumer power budgets pulling designs in opposite directions.
Solid-state scanning LIDAR is bifurcating from mechanical spinning units as the dominant automotive perception architecture. MEMS mirror and optical phased array variants deliver 200-meter range at 120-degree horizontal field of view, satisfying highway pilot requirements. German and Korean OEMs are specifying these modules for 2026-2027 vehicle programs, compressing mechanical LIDAR to niche robotics and mapping applications where 360-degree coverage remains essential.
The EU AI Act Article 5 prohibitions on real-time biometric identification in public spaces are redirecting 3D sensing R&D toward privacy-preserving depth-only systems. Manufacturers are stripping facial recognition capabilities from European market SKUs, substituting gesture and presence detection firmware. This regulatory friction is most acute in French and Italian smart city deployments, where vendors must demonstrate data minimization to CNIL and Garante per la Protezione dei Dati Personale inspectors.
Consumer electronics procurement is compressing supplier qualification cycles from multi-year frameworks to annual competitive re-bidding. Smartphone OEMs in Shenzhen and Seoul are awarding time-of-flight socket contracts on 12-month rolling terms indexed to die yield and ASP trajectories. This behavior shift is most visible in Chinese domestic brand supply chains, where second-source mandates from MIIT industrial policy accelerate vendor rotation.
3D Sensing and Imaging Market Segmentation
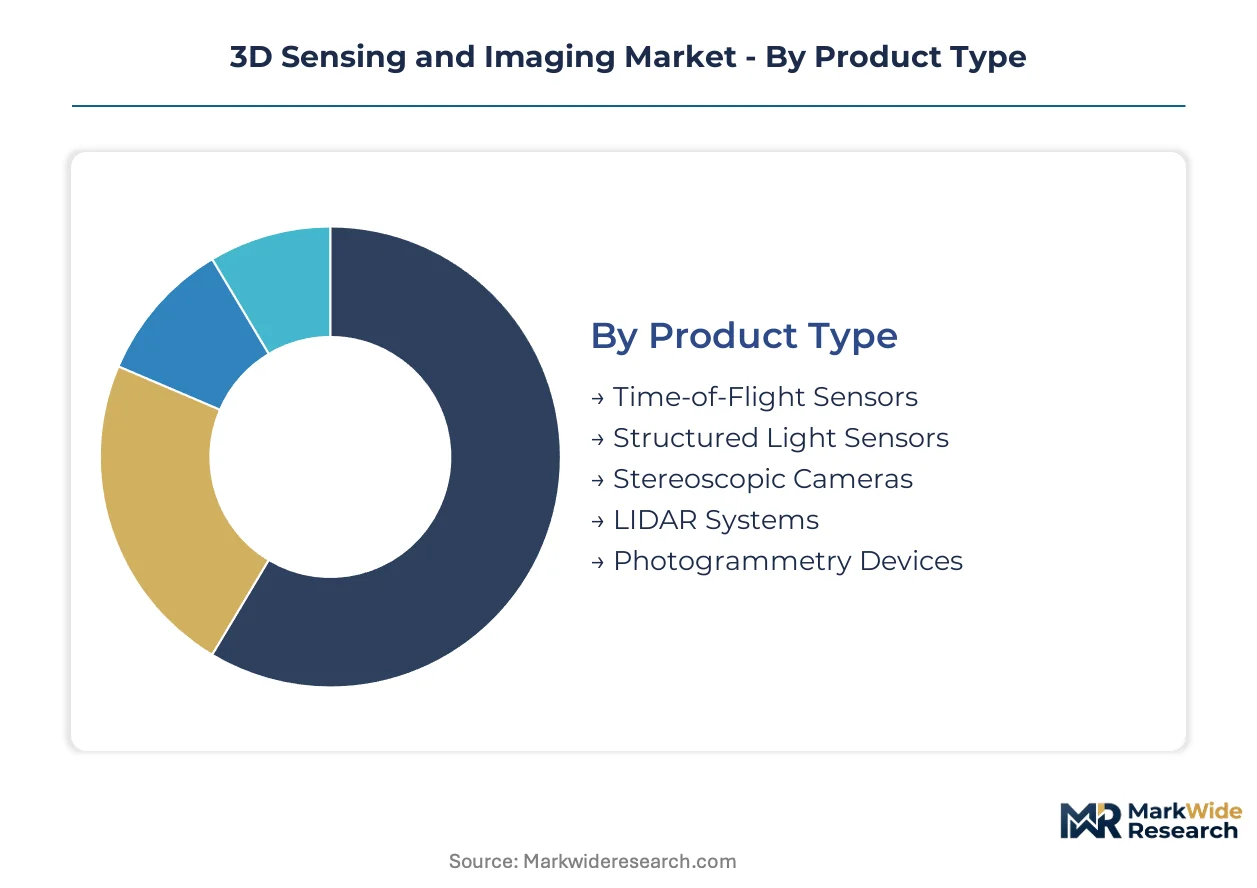
Technology choices in 3D sensing cascade through component sourcing, certification requirements, and end-use pricing power. Segment boundaries are blurring as time-of-flight architectures absorb adjacent functions, yet distinct margin pools persist where regulatory barriers or precision thresholds create captive demand.
Product Type:
Margin concentration sits with automotive-grade LIDAR and precision metrology modules where IEC 60825 certification and sub-millimeter accuracy specifications create pricing leverage.
- Time-of-Flight Sensors:Single-chip architectures dominate smartphone Face ID implementations and indoor navigation robotics. Shenzhen OEMs are consolidating socket awards around die-shrink roadmaps that compress module thickness below 3 millimeters.
- LIDAR Systems:Solid-state scanning variants with MEMS mirrors or optical phased arrays command premium positioning in Level 2+ ADAS programs. German and Korean automakers specify 200-meter range modules for highway pilot functions, pulling VCSEL array volumes from consumer electronics supply chains.
- Structured Light Sensors:Pattern projection systems retain strength in facial recognition and precision metrology where sub-pixel resolution matters.
- Stereoscopic Cameras:Passive depth estimation serves agricultural machinery and construction equipment where power budgets preclude active illumination.
- Photogrammetry Devices:Multi-camera arrays support industrial digital twin creation and heritage documentation workflows.
LIDAR Systems hold installed capacity. Time-of-Flight Sensors are rotating up the share rankings.
Technology:
Cost tier stratification separates high-volume consumer implementations from industrial and safety-critical deployments where wavelength selection determines performance ceilings.
- Infrared:Near-infrared emitters at 850-940 nanometers avoid visible-light interference in biometric and automotive applications. FDA laser product performance standards and IEC 62471 photobiological safety certifications govern emitter module design for US and European market access.
- Laser Triangulation:Structured light pattern projection achieves sub-10-micron tolerance verification in Stuttgart and Shenzhen precision manufacturing lines.
- Radar:Millimeter-wave sensing complements optical systems in adverse weather automotive perception.
- Ultrasound:Low-cost proximity detection serves consumer robotics and parking assistance where range requirements are modest.
- Confocal Microscopy:Sub-micron surface topology mapping supports semiconductor wafer inspection and medical device quality control.
Infrared dominates volume shipments. Laser Triangulation is climbing the fastest in value terms.
Application:
Customer type differentiation separates enterprise procurement cycles with 18-24 month qualification timelines from consumer electronics annual socket rotations.
- Gesture Recognition:Depth-only sensing systems are displacing camera-based tracking in automotive HMI and smart home controls. EU AI Act Article 5 prohibitions on biometric identification in public spaces are redirecting R&D toward privacy-preserving implementations for French and Italian smart city deployments.
- Industrial Inspection:Structured light metrology displaces coordinate measuring machines where sub-10-micron tolerance verification is required.
- Robotics Navigation:SLAM-capable depth modules serve warehouse automation and healthcare rehabilitation platforms.
- Augmented Reality:Dense depth mapping enables occlusion handling and spatial anchoring in headset devices.
- Security Surveillance:Liveness detection mandates under GDPR and EU AI Act are accelerating hardware refresh cycles across European access control installations.
Industrial Inspection holds installed capacity. Gesture Recognition is gaining share fastest as privacy regulations reshape product roadmaps.
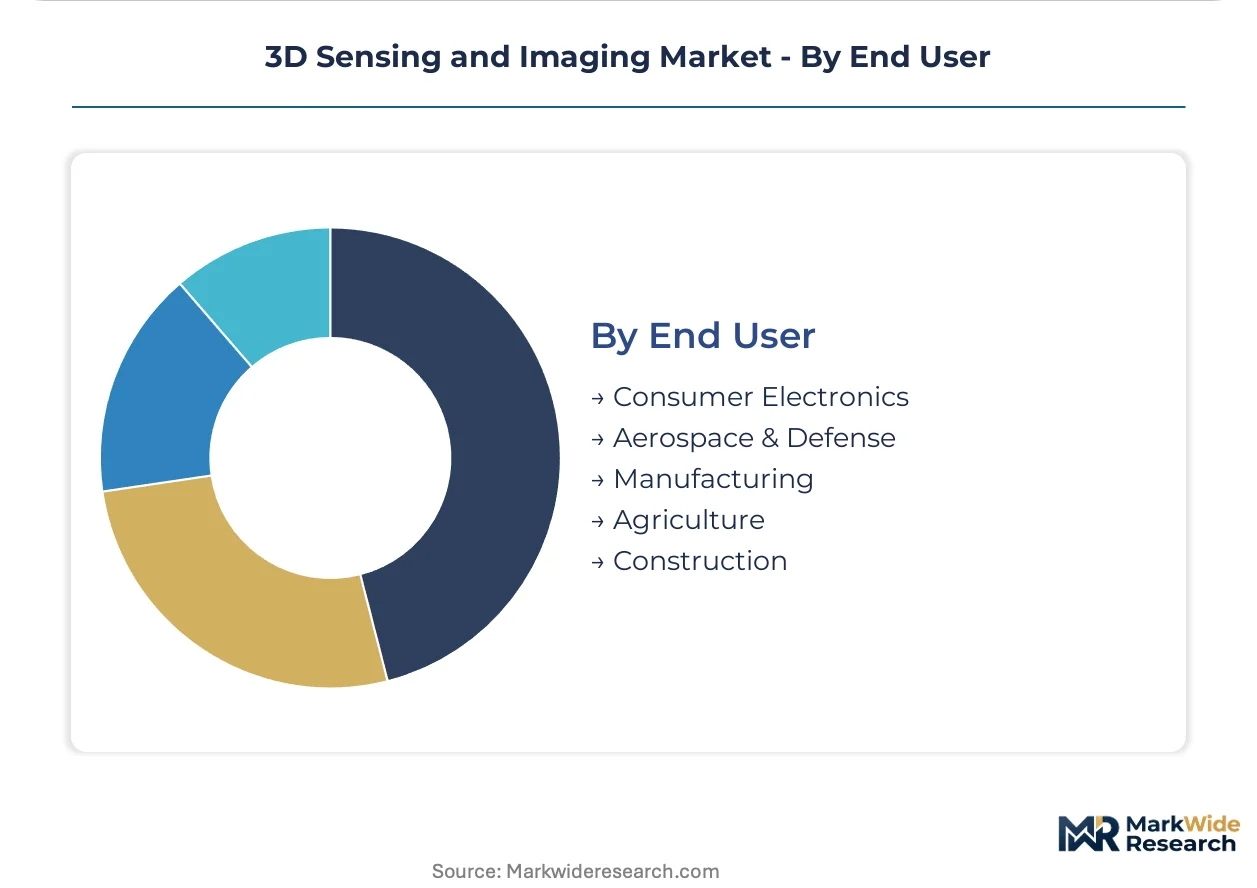
End User:
Supply concentration varies sharply, with consumer electronics depending on two Japanese and Korean CMOS sensor houses while aerospace and defense programs source through qualified domestic supply chains.
- Consumer Electronics:Smartphone OEMs in Seoul and Shenzhen compress supplier qualification cycles to 12-month rolling terms indexed to die yield trajectories. MIIT industrial policy mandates accelerate second-source vendor rotation in Chinese domestic brand supply chains.
- Manufacturing:German and South Korean automotive plants are integrating real-time 3D capture with industrial simulation software for facility-scale digital twin deployment.
- Aerospace & Defense:ITAR and export control compliance restricts sourcing to qualified domestic foundries and assembly operations.
- Agriculture:Autonomous machinery guidance systems adopt stereoscopic and time-of-flight architectures for crop monitoring and precision spraying.
- Construction:Photogrammetry and LIDAR support progress monitoring and as-built documentation for large infrastructure projects.
Consumer Electronics commands volume leadership. Manufacturing is expanding most quickly as digital twin convergence accelerates facility-scale deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is attracting VCSEL packaging operations to Tamil Nadu and Karnataka. The EU AI Act is accelerating hardware refresh cycles across European consumer electronics and access control installations. China's MIIT industrial policy mandates second-source vendor rotation in domestic smartphone supply chains.
United States
FDA laser product performance standards govern ophthalmic safety claims for near-infrared emitters deployed in biometric authentication systems. NHTSA Level 2+ ADAS specifications are pulling solid-state LIDAR module demand from automotive tier-1s. San Jose and Austin clusters concentrate optomechanical design talent commanding salary premiums for multi-physics simulation expertise.
Germany
Level 2+ highway pilot programs at German OEMs are specifying 200-meter range solid-state scanning modules. KBA type-approval processes intersect with EU AI Act conformity requirements for biometric identification systems. Stuttgart precision manufacturing lines are displacing coordinate measuring machines with structured light metrology for sub-10-micron tolerance verification.
China
MIIT industrial policy mandates accelerate second-source vendor rotation in domestic brand supply chains. Shenzhen OEMs compress supplier qualification cycles to 12-month rolling terms indexed to die yield trajectories. Yangtze River Delta and Pearl River Delta clusters dominate time-of-flight module assembly for consumer electronics export programs.
South Korea
German and Korean automotive plants are integrating real-time 3D capture with industrial simulation software for facility-scale digital twin deployment. MFDS regulatory frameworks govern medical device applications of 3D vision modules. Seoul Capital Area concentration of CMOS image sensor houses creates allocation leverage during smartphone launch windows.
Japan
METI industrial standards condition photonics export control compliance for near-infrared emitter modules. Japanese and Korean sensor houses concentrate captive capacity for time-of-flight receiver arrays. Kanto and Kansai clusters anchor precision MEMS fabrication for automotive LIDAR socket supply.
3D Sensing and Imaging Market Key Industry Players
Player mix skews toward diversified semiconductor conglomerates with captive CMOS sensor capacity. Consolidation pressure runs through smartphone OEM qualification cycles compressing from 18 months to under 12 months. Two strategic archetypes dominate: vertically integrated MEMS-to-module fabricators and fabless design houses licensing pattern projection IP. Competitive moves center on backward integration into VCSEL epitaxy and geographic expansion into India PLI-subsidized assembly operations.
Among diversified semiconductor conglomerates, Sony Group Corporation and Samsung Electronics Co., Ltd. occupy positions anchored by captive CMOS image sensor capacity. STMicroelectronics N.V. sits within the MEMS-to-module integration archetype alongside Infineon Technologies AG. These three entities exemplify the supply-side concentration that smartphone OEMs navigate through second-source mandates and annual competitive re-bidding protocols.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Microchip Technology Inc. |
| Sony Group Corporation |
| Samsung Electronics Co., Ltd. |
| OmniVision Technologies Inc. |
| Qualcomm Incorporated |
| Keyence Corporation |
| Cognex Corporation |
| Others |
Cost & Logistics Intelligence
IEC 60825 laser safety certification gates both supplier qualification and price differentiation simultaneously, with six-to-nine month approval cycles freezing engineering resources while creating tiered access for automotive-grade versus consumer-grade emitter modules. Shenzhen smartphone OEMs exploit this friction through annual competitive re-bidding that compresses NRE absorption costs into supplier margins.
Pricing Analysis
Certification level creates the primary spread between automotive LIDAR sockets and consumer time-of-flight modules. Three-tier pricing structure across IEC 60825 Class 1, FDA-grade biometric, and unqualified consumer tiers separates premium automotive perception systems from sub-fifty-dollar smartphone Face ID components. Cost compression in consumer electronics runs through die-shrink roadmaps that compress module thickness below three millimeters. Smartphone OEMs in Seoul and Shenzhen exhibit highest price sensitivity, while German automotive tier-1s prioritize range accuracy over unit economics.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Rotterdam lane expose VCSEL packaging operations to inbound logistics cost volatility. Taiwan, Japan, and South Korea concentrate captive CMOS image sensor capacity for time-of-flight receiver arrays. Indium phosphide substrates for 1550-nanometer LIDAR emitters and III-V compound wafers for near-infrared VCSELs feed from Japanese and Taiwanese foundries. Single-source vulnerability concentrates in automotive-grade MEMS mirror fabrication. Distribution runs through qualified tier-1 automotive suppliers and direct smartphone OEM procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration and firmware update subscriptions for industrial metrology systems are expanding faster than hardware shipments, creating service-attach economics that reshape vendor valuation multiples.
For Market Incumbents: Consolidate backward integration into VCSEL epitaxy to defend margin position against fabless design houses licensing pattern projection IP. Add captive capacity in Tamil Nadu and Karnataka under India's PLI scheme to offset second-source mandates from MIIT industrial policy. Certification investment in IEC 62471 photobiological safety creates switching costs that protect automotive LIDAR sockets. For New Entrants and Emerging Players: Differentiate on privacy-preserving depth-only firmware for EU AI Act compliance in French and Italian smart city deployments. Target healthcare navigation robotics in the United States where FDA breakthrough device designation pathways accelerate qualification timelines. Pursue facility-scale digital twin deployment contracts in German and South Korean automotive plants through photogrammetry-software integration partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state scanning LIDAR as MEMS mirror and optical phased array designs require precision optomechanical fabrication. Five-to-ten year viability favors vertically integrated MEMS-to-module fabricators with captive sensor capacity over royalty-dependent pattern projection licensors. Watch for allocation risk signals during smartphone launch windows as Korean and Japanese sensor houses throttle CMOS die supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCSEL Epitaxy | Captive wafer supply insulates automotive tier-1s from III-V compound spot price swings. |
| India PLI Scheme Assembly Expansion | Tamil Nadu and Karnataka operations capture domestic smartphone and automotive program demand. |
| Privacy-Preserving Firmware Development | EU AI Act Article 5 compliance opens French and Italian smart city deployment contracts. |
| Digital Twin Software Integration | Real-time 3D capture convergence with industrial simulation secures facility-scale contracts. |
| FDA Breakthrough Device Qualification | Accelerated pathways position surgical and rehabilitation robot platforms in United States healthcare. |
Research Approach
The analysis maps time-of-flight, structured light, and LIDAR sub-sectors, each validated through component supplier executives, automotive tier-1 procurement leads, and industrial metrology engineers. Primary interviews with smartphone OEM platform engineers, MEMS fabrication specialists, and regulatory affairs directors combined with secondary validation through SEC 10-K filings, customs and trade data, FDA laser product performance standards, and EU AI Act conformity documentation. Bottom-up module shipment aggregation and top-down semiconductor industry sizing provided triangulation checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include technology architecture, wavelength selection, certification tier, end-use application, and regional regulatory cluster. CAGRs derived from die yield trajectories, ASP compression curves, and automotive ADAS penetration assumptions. Industry-specific inputs encompass VCSEL array volumes pulled from consumer electronics to automotive sockets and EU AI Act hardware refresh cycle acceleration.
Material uncertainties — indium phosphide substrate cost volatility, IEC 60825 certification timeline extensions, and CMOS sensor allocation disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about smartphone OEM consolidation around single-chip architectures and German OEM solid-state LIDAR specifications for highway pilot functions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Contact Image Sensor Market
Imaging
Hybrid Imaging Systems Market
Imaging
Electron Microscopy Market
Imaging
Ingaas Image Sensor Market
Imaging
Digital Image Processing Market
Imaging
X-Ray Microscopes Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Medical X-Ray Detectors Market
Imaging
Holographic Imaging Market
Imaging
Virtual Reality Camera Market
Imaging
Hybrid Imaging Market
Imaging
Handheld Retinal Scanners Market
Imaging
Machine Vision System Market
Imaging
Japan Digital X-Ray Market
Imaging
Camera Lens Market
Imaging
Document Imaging Market