
 Tablets and Notebook Display Market | 2026-2036
Tablets and Notebook Display Market Size, Share, and Industry Trends Forecast 2026-2036
Tablets and Notebook Display Market Analytics
Oxide thin-film transistor backplane migration is tilting the cost-performance balance toward higher refresh rates and lower power draw in notebook panels. Samsung Electronics leverages captive OLED deposition capacity to dominate premium notebook supply. BOE Technology Group anchors massive Gen 10.5 LCD output in Hefei and Wuhan, competing aggressively on volume pricing. AU Optronics specializes in LTPS and IGZO variants for tablets requiring narrow bezel architectures.
Tablets and notebook displays are active-matrix flat-panel devices comprising glass substrates, thin-film transistor arrays, liquid crystal or organic emissive layers, color filters, and polarizer films, manufactured through photolithography, chemical vapor deposition, and precision cell assembly processes to render visual output for portable computing devices. LCD retains volume leadership across education and entry-tier professional notebooks where cost sensitivity governs procurement, while OLED commands margin pools in creator and gaming segments where contrast ratio and response time differentiate purchase decisions. Mini-LED backlighting occupies a transitional position, offering localized dimming without full OLED conversion costs.
REACH restricts hazardous substance use in display module adhesives and phosphor materials entering European distribution, while the EU Ecodesign Framework mandates minimum energy efficiency indexes for electronic displays sold across member states. China's GB standards govern electromagnetic compatibility and safety certification for domestic-market panels, with SAMR enforcing conformity assessment protocols. Korea's MFDS and METI coordinate on blue light exposure guidelines affecting panel spectral tuning requirements. Stakeholders must monitor regulatory divergence between energy efficiency mandates and emerging circular economy disclosure rules as compliance costs fragment across destination markets.
Market Dynamics
Enterprise refresh cycles for hybrid work hardware are compressing replacement timelines while OLED deposition capacity constraints force buyers into allocation queues. Panel makers must balance Gen 10.5 LCD scale economics against IGZO backplane migration costs.
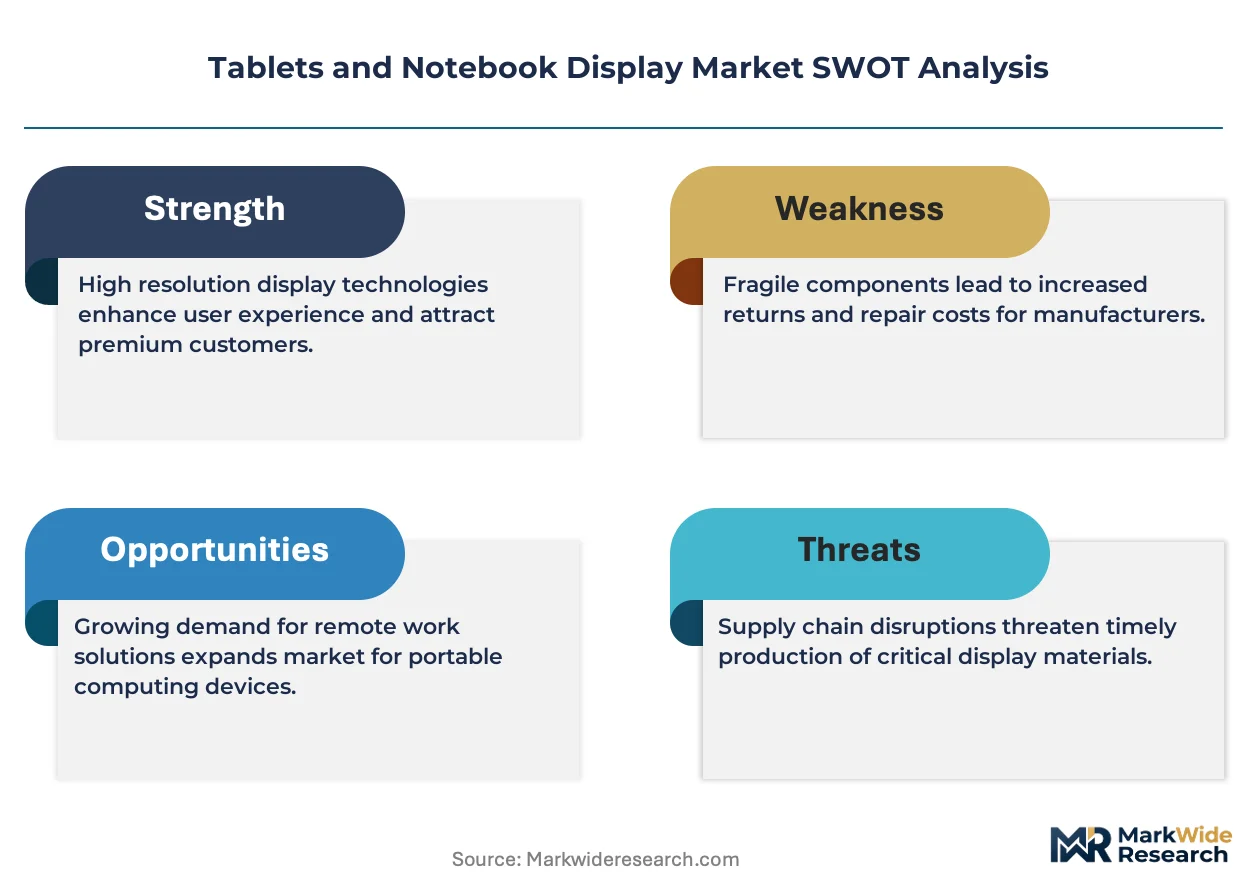
Growth Catalysts
- EU Ecodesign energy efficiency mandates:Minimum performance indexes for electronic displays accelerate retirement of legacy backlight architectures in European procurement.
- Oxide TFT backplane diffusion:IGZO and LTPS variants enable 120Hz+ refresh rates in ultrabook form factors without battery capacity penalties.
- China:Massive Gen 10.5 fab clusters in Hefei and Wuhan concentrate cost-competitive LCD supply for education and entry-tier notebook segments.
Market Restraints
- Input cost volatility:Rare earth phosphor prices and polarizer film substrates fluctuate with energy-intensive chemical processing costs.
- Supply concentration risk:Active matrix OLED deposition equipment and fine metal mask supply chains cluster in South Korean and Japanese equipment vendors.
- Technical limitation:Burn-in susceptibility in OLED notebook panels restricts deployment in static-image enterprise productivity workflows.
Strategic Opportunities
- Underpenetrated India:PLI scheme incentives for electronics manufacturing attract display module assembly investments serving domestic education procurement.
- Regulatory tailwind:China's dual carbon goals drive preferential financing for low-power IGZO and oxide TFT production lines.
- Technology convergence:Mini-LED backlighting with local dimming zones bridges LCD cost structures toward OLED contrast performance in creator-tier notebooks.
Industry Challenges
- Skill gap:Photolithography and chemical vapor deposition process engineers command premiums as Gen 8.5+ fab expansions compete for talent pools.
- Capex intensity:Gen 10.5 glass substrate handling and precision cell assembly equipment require multi-year depreciation schedules.
- Certification timeline:REACH substance restrictions and RoHS compliance testing extend qualification cycles for adhesive and phosphor material substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablets and Notebook Display Market |
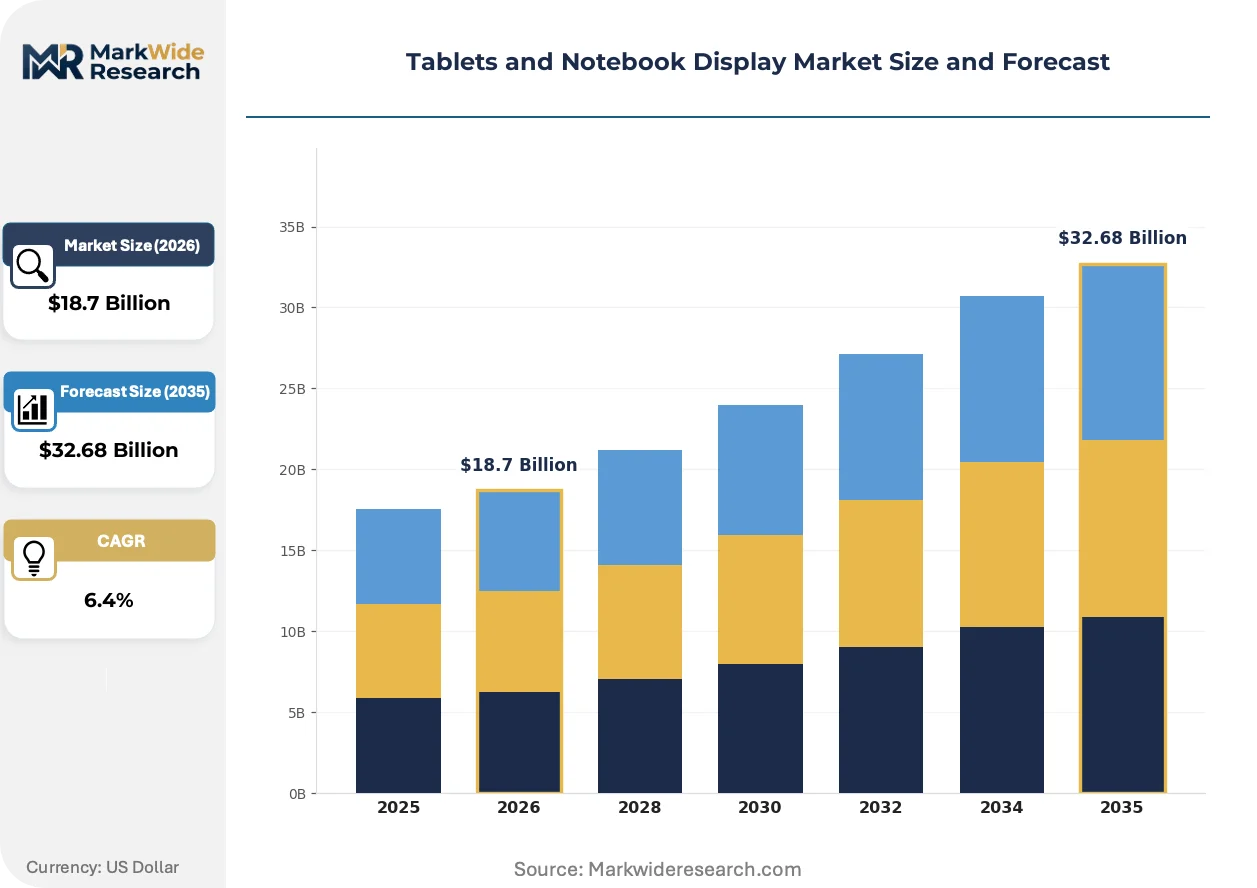
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, Mini-LED Technology: Touchscreen, Non-Touch, 4K, 1080p End User: Students, Professionals, Gamers, Designers Size: 11-inch, 13-inch, 15-inch, 17-inch |
| Companies Covered | Sharp Corporation, Japan Display Inc., Samsung Electronics, Tianma Microelectronics, Innolux Corporation, LG Display, AU Optronics, Toshiba, BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablets and Notebook Display Market Evolving Landscape
Display architecture decisions now hinge on power-performance tradeoffs rather than pixel density alone. Panel makers are repositioning around refresh rate differentiation and spectral tuning for blue light compliance.
LTPS and IGZO oxide thin-film transistor backplanes are migrating from premium tablet segments into mainstream notebook panels. Gaming and creator-tier laptop OEMs specify 120Hz to 240Hz variants for competitive differentiation. This migration from amorphous silicon is compressing margins on conventional LCD while opening premium pricing tiers for oxide-enabled performance tiers.
REACH substance restrictions and EU Ecodesign energy efficiency indexes are reshaping material selection and power budget specifications. Panel assemblers must reformulate adhesive chemistries and phosphor compositions to maintain European market access. Notebook OEMs serving EU institutional procurement now require supplier documentation on circular economy disclosure and repairability indexing.
Enterprise hardware refresh cycles are compressing from five-year to three-year intervals as hybrid work policies stabilize. IT procurement teams specify narrow-bezel, high-refresh panels for video collaboration endpoints. North American and Western European enterprise segments show strongest adoption of accelerated replacement schedules tied to Microsoft Teams and Zoom hardware certification programs.
Tablets and Notebook Display Market Segmentation
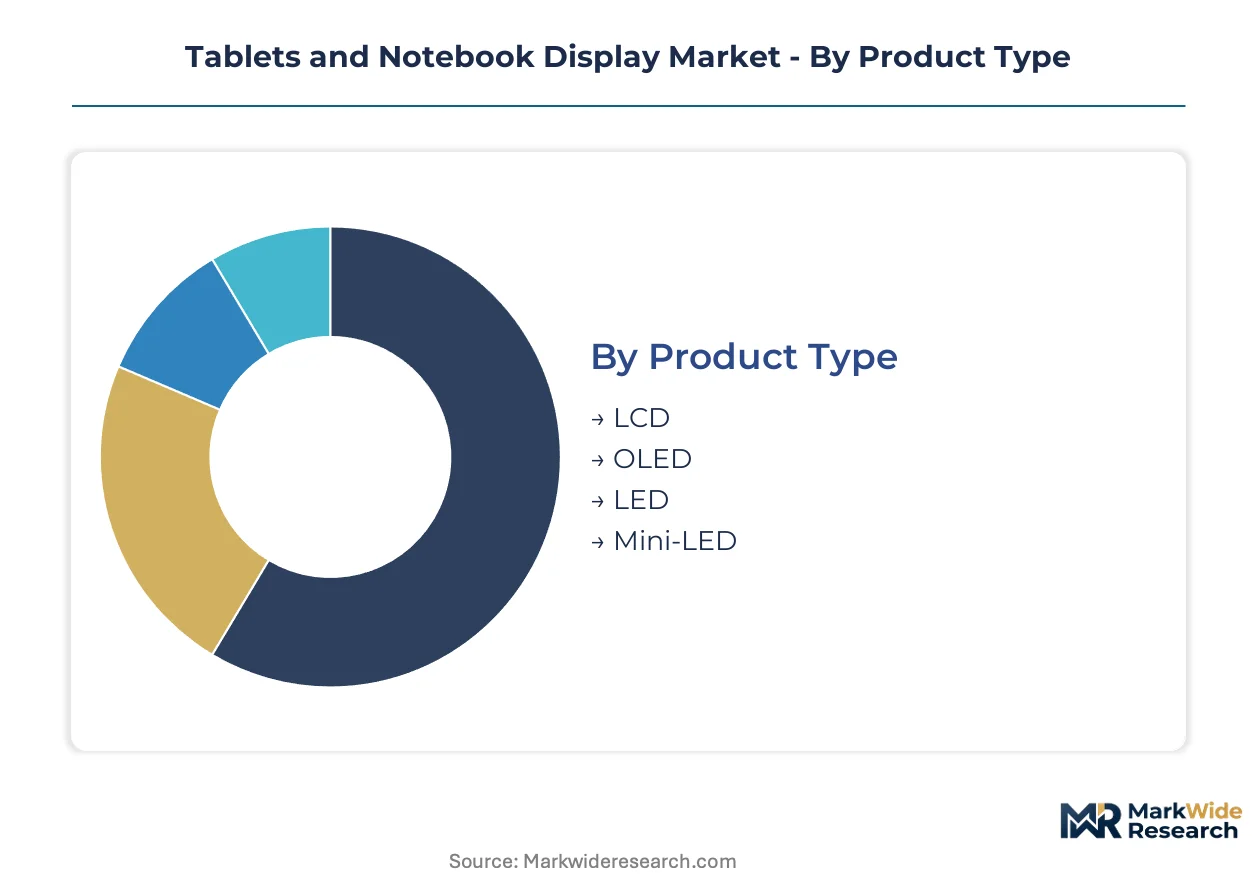
Display procurement decisions in tablets and notebooks split across technical specifications, use-case intensity, and form-factor constraints. Each segmentation axis reveals distinct margin pools and manufacturing scale requirements that shape supplier positioning.
Product Type:
Mature LCD volumes anchor education and enterprise procurement while emerging OLED and Mini-LED variants capture premium tier expansion.
- LCD:Twisted nematic and in-plane switching architectures dominate volume production using amorphous silicon backplanes. Education procurement in India and enterprise refresh cycles in Germany concentrate demand where cost-per-unit governs selection.
- OLED:Organic emissive layers deposited through fine metal mask evaporation enable per-pixel dimming and sub-millisecond response times. Creator and gaming notebook segments in South Korea and the United States absorb supply despite deposition capacity constraints.
- LED:Edge-lit and direct-lit backlight configurations serve entry-tier tablets where thickness and weight tradeoffs matter less than unit economics.
- Mini-LED:Thousands of localized dimming zones bridge LCD cost structures toward OLED contrast performance without burn-in susceptibility.
LCD handles the majority of throughput; OLED is the fastest mover on share.
Technology:
Cost tier stratification separates premium specification adoption from mainstream volume deployment across touch integration and resolution tiers.
- Touchscreen:Projected capacitive sensor layers bonded to display modules enable stylus and gesture input. Education tablets and hybrid work notebooks in Japan and France require touch certification for institutional procurement.
- Non-Touch:Eliminated sensor stack reduces stack thickness and BOM cost for price-sensitive clamshell notebooks.
- 4K:Ultra-high-definition panels target video editing and content creation workflows where pixel density directly impacts productivity.
- 1080p:Full HD resolution satisfies enterprise productivity and streaming consumption without GPU scaling penalties.
1080p maintains volume leadership; 4K panels are expanding most quickly in creator-tier segments.
End User:
Application intensity determines refresh rate requirements, color gamut specifications, and durability certifications across distinct user personas.
- Students:Ruggedized panels with anti-glare coatings and reinforced cover glass withstand classroom handling. India's education technology procurement drives volume concentration.
- Professionals:Narrow bezel designs and 120Hz refresh rates support video collaboration endpoints. Microsoft Teams and Zoom hardware certification programs accelerate replacement timelines in North American enterprise accounts.
- Gamers:240Hz+ refresh rates and sub-3ms response times prioritize competitive performance over power efficiency.
- Designers:Factory-calibrated wide color gamut coverage and high dynamic range compliance serve color-critical workflows.
Professionals generate the largest addressable base; gamers show the steepest specification escalation trajectory.
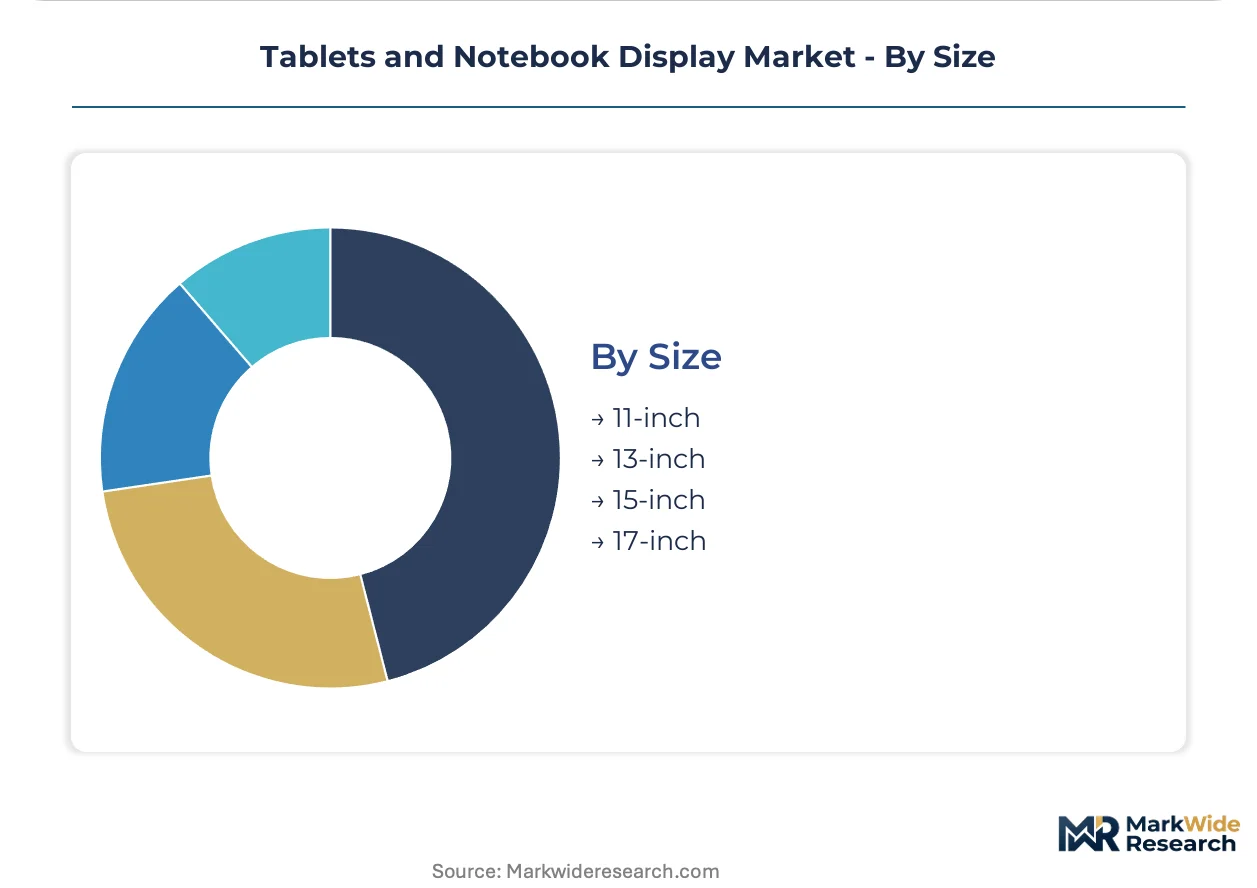
Size:
Form-factor portability tradeoffs segment demand across mobility-first tablets and productivity-optimized notebook configurations.
- 11-inch:Compact diagonal suits tablet mobility and entry-level education devices where one-handed operation matters. China's domestic education procurement absorbs significant volume.
- 13-inch:Balanced screen real estate and chassis weight dominate ultrabook and premium tablet segments. Japanese and German business travelers prioritize this form factor.
- 15-inch:Expanded workspace accommodates spreadsheet productivity and split-screen multitasking without external monitor dependency.
- 17-inch:Desktop replacement notebooks and mobile workstation configurations maximize screen area for engineering and creative applications.
13-inch panels command the highest unit volumes; 15-inch configurations are gaining share fastest in hybrid work deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel exports from South Korea and Taiwan supply assembly operations in Vietnam and Mexico, creating a triangular trade corridor that shapes regional procurement patterns. China's Gen 10.5 fab clusters in Hefei and Wuhan anchor volume production for education and entry-tier segments. Regulatory divergence between EU Ecodesign mandates and China's dual carbon goals is fragmenting compliance costs across destination markets.
China
Domestic education procurement and enterprise refresh cycles absorb massive LCD output from BOE Technology Group's Hefei and Wuhan facilities. SAMR enforces GB standards on electromagnetic compatibility and safety certification for panels entering distribution. The Yangtze River Delta concentration of Gen 10.5 glass substrate handling equipment supports cost-competitive volume manufacturing for export markets.
South Korea
Creator-tier notebook OEMs in Seoul Capital Area specify OLED panels for gaming and content creation workflows despite deposition capacity constraints. MFDS coordinates with METI on blue light exposure guidelines affecting spectral tuning requirements. Samsung Electronics leverages captive OLED deposition capacity in Gyeonggi-do to dominate premium notebook supply allocations.
United States
North American enterprise segments compress replacement timelines from five-year to three-year intervals under hybrid work policies. FCC certification requirements govern electromagnetic emissions for displays entering institutional procurement. Microsoft Teams and Zoom hardware certification programs in Seattle and Austin accelerate panel specification upgrades for video collaboration endpoints.
Germany
REACH substance restrictions and EU Ecodesign energy efficiency indexes reshape material selection for displays entering European distribution. ECHA enforcement extends qualification cycles for adhesive and phosphor material substitutions. Industrial procurement clusters in Bavaria and North Rhine-Westphalia prioritize narrow-bezel, high-refresh panels for productivity workflows.
India
PLI scheme incentives for electronics manufacturing attract display module assembly investments serving domestic education technology procurement. BIS certification governs safety and electromagnetic compatibility for panels entering the market. Tamil Nadu and Karnataka industrial corridors concentrate assembly operations targeting ruggedized tablet demand from state education departments.
Tablets and Notebook Display Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. The vendor base concentrates around captive OLED deposition capacity, massive Gen 10.5 LCD scale operations, and narrow-bezel LTPS specialization for tablets. Two strategic archetypes dominate: vertically integrated display conglomerates with in-house semiconductor and panel operations, and pure-play panel specialists focusing on backplane technology differentiation. Capacity expansion in oxide TFT lines and strategic partnerships for Mini-LED backlighting represent the dominant competitive moves reshaping positioning.
Among East Asian fabricators, Samsung Electronics, BOE Technology Group, and AU Optronics occupy distinct positions within this tripartite structure. Samsung Electronics exemplifies the captive-capability archetype through its integrated OLED deposition operations. BOE Technology Group anchors the scale-driven tier with massive Gen 10.5 LCD output concentration. AU Optronics represents the specialization vector through its focus on LTPS and IGZO backplane variants. Each occupies a position that reflects broader industry segmentation between premium OLED margins, volume LCD economics, and performance-tier differentiation.
| Leading Market Players |
|---|
| Sharp Corporation |
| Japan Display Inc. |
| Samsung Electronics |
| Tianma Microelectronics |
| Innolux Corporation |
| LG Display |
| AU Optronics |
| Toshiba |
| BOE Technology Group |
| Others |
Value Network & Pricing Analysis
Hefei and Wuhan's Gen 10.5 fab clusters concentrate massive LCD substrate capacity, granting BOE Technology Group disproportionate leverage over education and entry-tier notebook pricing. This geographic concentration of glass handling equipment and precision cell assembly lines compresses margins for volume LCD while amplifying allocation power for OLED deposition capacity in South Korea.
Pricing Analysis
Gen 10.5 LCD, Gen 8.5 oxide TFT, and nascent Gen 6 OLED deposition lines operate on three-tier pricing structure across premium, standard, and economy levels. Contract-based long-term offtake governs procurement between panel makers and notebook OEMs, with price differentiation driven by refresh rate certification and volume scale commitments. Pricing pressure stems from oxide TFT migration costs as buyers demand 120Hz specifications without absorbing backplane premiums. Education procurement in India exhibits highest price sensitivity, while creator-tier gaming segments absorb OLED premiums with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment and fine metal mask technology limit deposition tool flows to Chinese panel makers, constraining domestic OLED ramp speed. Active matrix fabrication concentrates in China, South Korea, and Taiwan, with rare earth phosphor substrates, polarizer films, and driver ICs anchoring raw material dependencies. Single-source vulnerability clusters around Japanese and Korean equipment vendors for precision evaporation systems. Distribution runs through module assembly operations in Vietnam and Mexico serving North American and European OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tablets and notebook displays face high-growth disruption as EU Ecodesign mandates force accelerated retirement of legacy backlight architectures ahead of replacement cycles. This regulatory inflection compresses procurement timelines while amplifying premium capture for oxide-enabled performance tiers.
For Market Incumbents: Insulate premium positioning through captive OLED deposition capacity and backward integration into driver IC design. Samsung Electronics demonstrates this archetype through Gyeonggi-do fabrication dominance. Defend against Mini-LED bridge technologies by accelerating IGZO backplane cost curves. Prioritize REACH-compliant adhesive reformulation to maintain European institutional access against ECHA enforcement timelines.
For New Entrants and Emerging Players: Ruggedized education tablets for Indian state procurement under PLI scheme incentives represent the most penetrable entry point, with Tamil Nadu and Karnataka assembly corridors offering tariff-advantaged module integration. Mid-tier oxide TFT supply for 120Hz ultrabooks in Southeast Asian enterprise accounts offers secondary white-space. Pursue JDM partnerships with established backlight unit suppliers to bypass multi-year depreciation barriers on Gen 10.5 equipment.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate display divisions lacking oxide TFT transition roadmaps. Long-term viability hinges on positioning against dual carbon financing windows in China and EU circular economy disclosure requirements. Watch for inflection signals in fine metal mask supply constraints relaxing, which would signal OLED deposition capacity expansion and margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxide TFT Backplane Migration | IGZO and LTPS variants enable 120Hz+ refresh without battery penalties, differentiating ultrabook specifications. |
| EU Ecodesign Compliance Investment | REACH reformulation and energy efficiency indexing secure institutional procurement access across German and French education channels. |
| Mini-LED Backlight Partnership | Localized dimming zones bridge LCD cost structures toward OLED contrast performance in creator-tier notebooks. |
| PLI Scheme Module Assembly | India's electronics manufacturing incentives attract display integration investments serving domestic education technology procurement. |
| Fine Metal Mask Supply Agreement | Long-term equipment vendor contracts reduce allocation queue exposure for OLED deposition capacity expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade databases, and SAMR certification registries. Display panel procurement directors, oxide TFT process engineers, and notebook OEM supply chain managers provided operational perspective on capacity allocation and specification migration timelines. Trade association disclosures from SID and ICDM supplemented technical parameter validation. Bottom-up shipment modeling triangulated against top-down value estimates across product type, technology tier, and end-user segmentation.
Forecast inputs span refresh rate adoption curves, oxide backplane yield ramps, and EU Ecodesign compliance deadlines across the analysis window. Segmentation dimensions include display technology, backplane architecture, touch integration, resolution tier, and regional procurement cluster. CAGRs derive from installed base replacement velocity and specification upgrade elasticities. Key inputs incorporate Gen 10.5 glass substrate throughput, OLED deposition tool lead times, and education procurement budget cycles.
Stress conditions across rare earth phosphor price volatility, export control escalation, and hybrid work policy reversal were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on oxide TFT yield maturation and Ecodesign enforcement consistency. Material shifts in REACH substance restriction scope or dual carbon financing withdrawal would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Medical Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Rugged Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Dot Matrix Display Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Video Wall Display Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
3D Holographic Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
Touch Screen Module Market
Display Technologies
Vietnam Displays Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Middle East and Africa Industrial Display Market