
 Mono LCD Displays Market | 2026-2036
Mono LCD Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Mono LCD Displays Market Insights
Aftermarket module refurbishment is tilting margin pools away from virgin panel production toward recalibration and legacy interface services. Tianma Microelectronics leverages captive glass substrate capacity to anchor high-volume industrial character display supply. Truly Semiconductors competes through specialized COG bonding lines that dominate small-format graphic display segments for medical instrumentation.
Mono LCD displays are passive-matrix liquid crystal devices built on twisted nematic or super-twisted nematic architectures, typically operating at 3.3V or 5V with viewing angles between 45 and 60 degrees, engineered for low-power alphanumeric and simple graphic readout in ambient-lit environments. Character displays remain the mature volume backbone across industrial HMI applications, while custom displays capture premium margin pools from medical device OEMs requiring bespoke form factors and extended temperature ratings. Module displays represent the fastest-growing configuration as integrators seek drop-in solutions with bundled LED backlight drivers and resistive touch layers.
China's SAMR enforces GB standards governing display electromagnetic compatibility and energy consumption thresholds that constrain non-compliant import access. The EU RoHS and REACH frameworks restrict hazardous substance profiles in display glass and driver IC packaging, reshaping material qualification cycles for suppliers serving European industrial and automotive end users. Stakeholders must monitor how emerging e-waste extended producer responsibility schemes alter module collection and refurbishment economics across their served geographies.
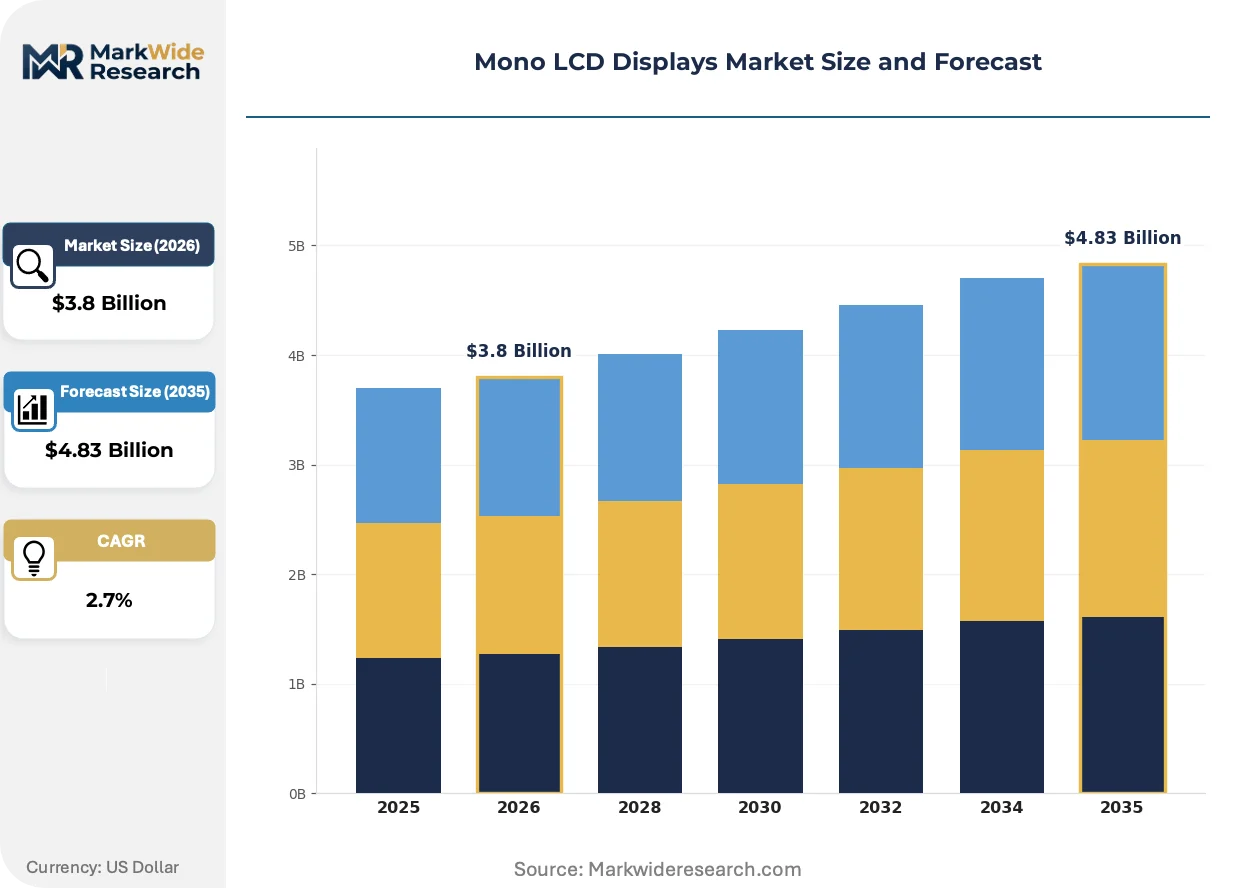
Market Dynamics
Industrial equipment manufacturers are consolidating module sourcing around drop-in solutions with integrated LED drivers and touch layers, compressing procurement cycles from component-level qualification to system-level integration.
Growth Catalysts
- GB Energy Efficiency Standards:China's SAMR mandates are tightening compliance thresholds for display power consumption, forcing module suppliers to redesign driver architectures and creating upgrade cycles across installed industrial HMI bases.
- Medical Device Form Factor Specialization:Bespoke mono LCD configurations with extended temperature ratings and custom aspect ratios are capturing premium positioning as OEMs seek differentiation in portable diagnostic equipment.
- Shenzhen Cluster Concentration:Module assembly corridors in Guangdong Province offer integrated COG bonding, backlight integration, and resistive touch lamination within single manufacturing footprints, reducing logistics friction for automotive Tier 1 suppliers.
Market Restraints
- Glass Substrate Supply Concentration:Captive capacity at major TFT-LCD manufacturers limits independent access to high-quality glass for STN architectures, constraining cost flexibility for mid-volume industrial display specialists.
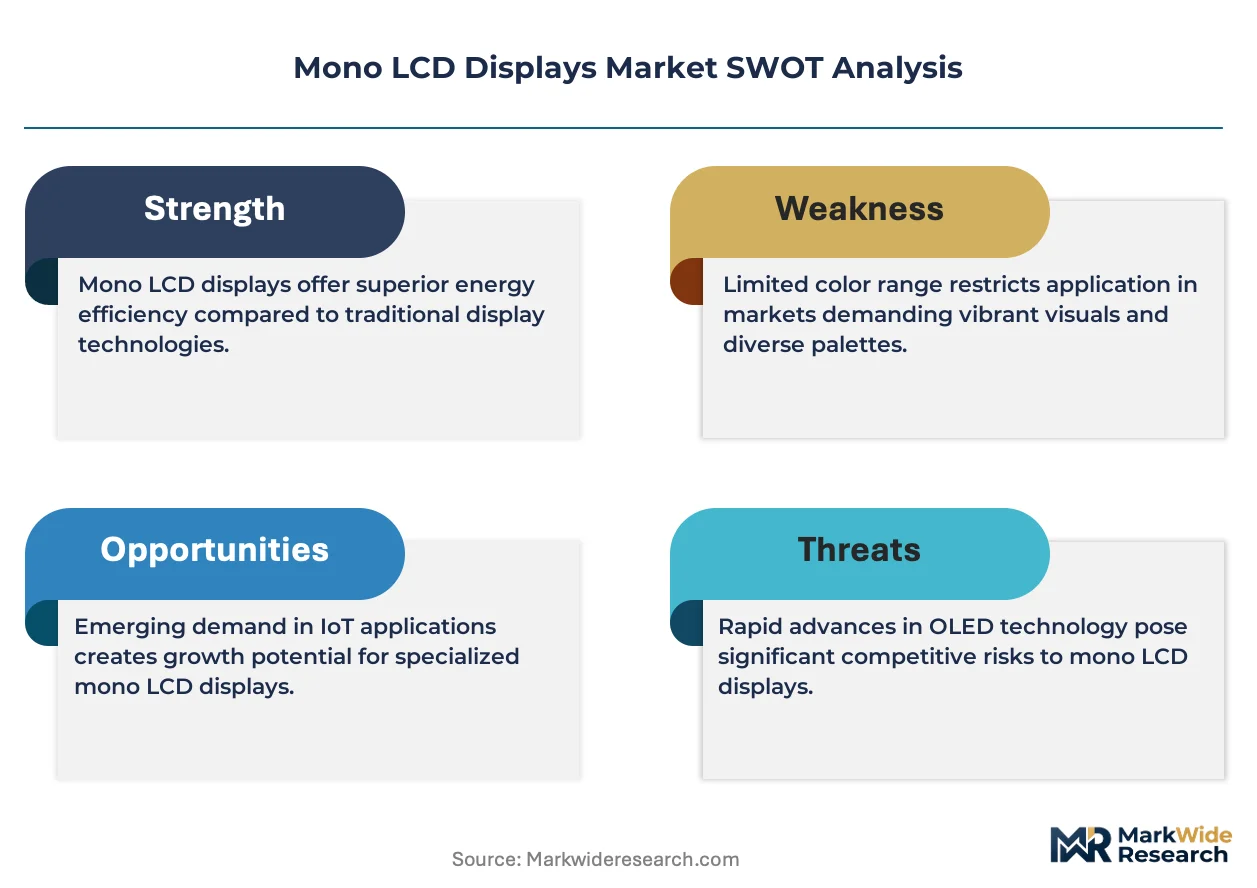
- AMOLED Substitution Pressure:Flexible organic displays are penetrating price-sensitive wearable and handheld instrumentation segments where mono LCDs previously dominated, compressing addressable volume in consumer-facing medical devices.
- EU REACH Material Qualification:Restricted substance lists for display glass and driver IC packaging extend qualification timelines by 8-14 months for suppliers without established European compliance infrastructure.
Strategic Opportunities
- Aftermarket Refurbishment Services:Legacy interface recalibration and backlight replacement for installed industrial equipment represents margin pools shifting away from virgin panel production toward service-based revenue models.
- Resistive Touch Integration:Convergence of mono LCD modules with analog touch layers in single-drop configurations reduces BOM complexity for process control interface designers seeking glove-compatible input surfaces.
- German Industrial Automation Demand:Mittelstand equipment manufacturers in Bavaria and Baden-Württemberg are expanding adoption of character displays for machine tool readouts, creating specialized volume for regional module distributors.
Industry Challenges
- COG Bonding Technician Scarcity:Chip-on-glass assembly requires specialized cleanroom operators capable of anisotropic conductive film placement at 50-micron pitch, with training pipelines failing to match expansion rates in Shenzhen and Dongguan manufacturing zones.
- Dual Carbon Compliance Timelines:China's MEE enforcement of carbon intensity benchmarks for electronics manufacturing is forcing facility retrofits that strain capital allocation between environmental equipment and capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mono LCD Displays Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Character Displays, Graphic Displays, Module Displays, Custom Displays Technology: TFT, LCD, LED, OLED End User: Industrial Equipment, Consumer Electronics, Medical Devices, Automotive Displays Application: Signage, Instrumentation, HMI, Retail |
| Companies Covered | Tianma Microelectronics, Truly Semiconductors, Kingtech Group Co., Ltd., Seacomp, ZhSunyco, Newhaven Display International Inc., New Vision Display (Shenzhen) Co., Ltd., E3 Innovation Inc., Winstar Display Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mono LCD Displays Market Trends and Innovations
Display architecture decisions are increasingly driven by integrated system requirements rather than standalone panel specifications, reshaping how module suppliers bundle backlight drivers, touch controllers, and interface electronics.
Super-twisted nematic technology dominates industrial HMI applications requiring wide viewing angles and passive-matrix simplicity. Automotive instrument cluster suppliers in Germany are adopting STN modules for secondary information displays where color is non-essential. Mono LCD functionality is migrating from discrete component procurement toward pre-validated subsystem sourcing with bundled thermal management.
REACH substance restrictions are tightening thresholds for lead content in display glass and halogenated flame retardants in driver IC packaging. European industrial OEMs now require full material disclosure documentation extending three tiers into the supply chain. Medical device manufacturers serving EU markets are accelerating qualification of alternative encapsulant materials to preempt regulatory friction.
Equipment buyers are consolidating vendor relationships around module suppliers offering integrated firmware customization and application engineering support. Distributors in the industrial automation channel are ceding specification influence to direct OEM-module manufacturer relationships. This pattern is most visible in German-speaking Europe, where machine builders prioritize single-source accountability for display subsystem performance.
Mono LCD Displays Market Segmentation
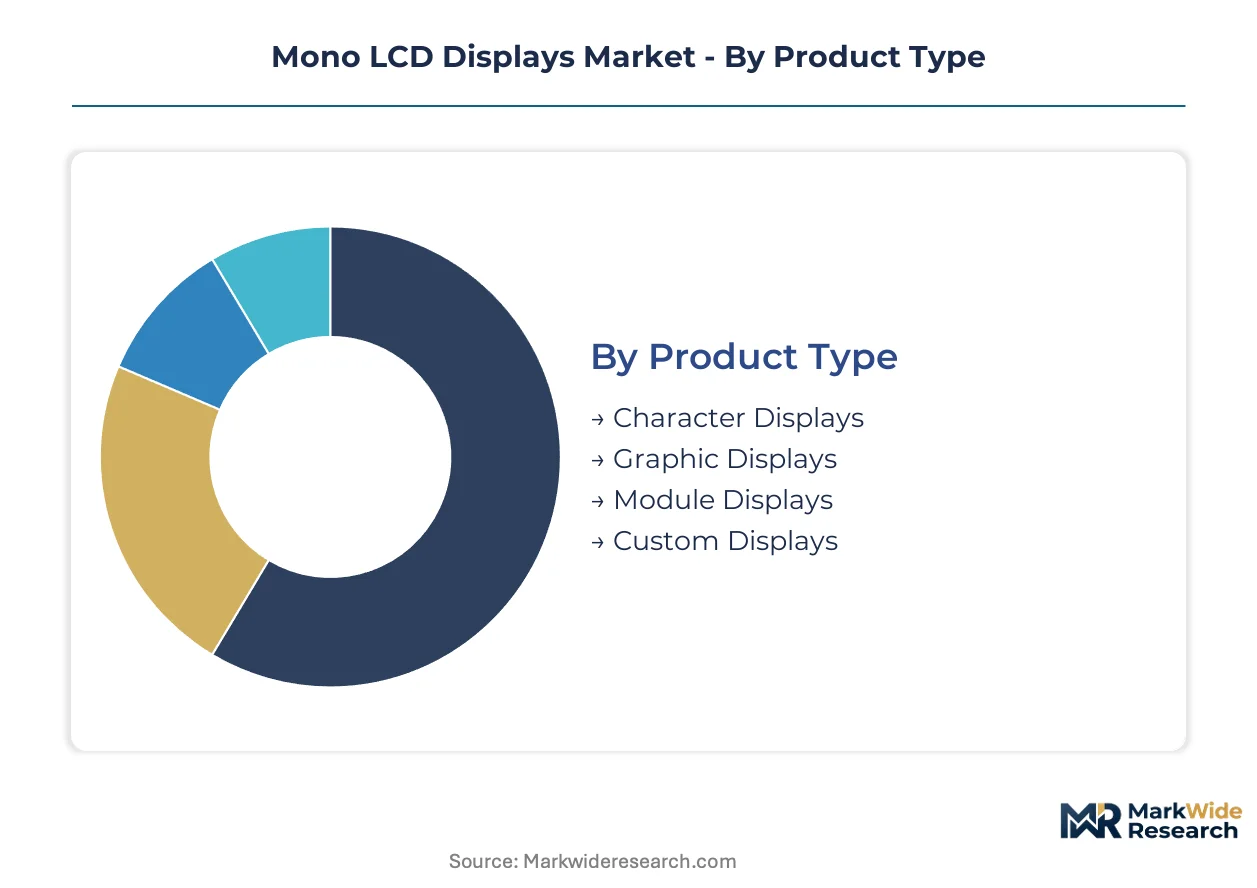
Mono LCD displays fragment across four distinct product architectures, each anchoring different margin pools and qualification requirements. Understanding where module displays diverge from character formats clarifies procurement strategies for industrial integrators and medical OEMs.
Product Type:
The use-case spectrum spans basic alphanumeric readouts through fully integrated subsystems with bundled electronics.
- Character Displays:These 16x2 and 20x4 line configurations dominate machine tool interfaces and process control panels. German Mittelstand equipment manufacturers in Bavaria source these for cost-optimized HMI readouts where color differentiation is unnecessary.
- Graphic Displays:Dot-matrix architectures enable simple icons and trend graphs in portable medical instrumentation. Demand concentrates among Shenzhen-based contract manufacturers serving diagnostic equipment OEMs requiring bespoke pixel densities.
- Module Displays:Drop-in solutions with pre-integrated LED backlight drivers and resistive touch layers reduce BOM complexity for automotive Tier 1 suppliers. These configurations are gaining share fastest as procurement shifts from component-level to subsystem-level sourcing.
- Custom Displays:Extended temperature ratings and non-standard aspect ratios command premium positioning in EU-regulated medical devices.
The dominant share belongs to Character Displays, while Module Displays is closing the gap fastest.
Technology:
Cost tier separation distinguishes mature passive-matrix architectures from emerging alternatives.
- TFT:Thin-film transistor backplanes enable higher refresh rates and wider viewing angles in industrial automation panels. China's SAMR energy efficiency mandates are forcing driver redesigns that favor TFT architectures over simpler alternatives.
- LCD:Twisted nematic and super-twisted nematic constructions remain the volume backbone for 3.3V and 5V operation in ambient-lit environments. German automotive instrument cluster suppliers adopt STN variants for secondary information displays.
- LED:Direct-lit backlighting modules serve signage applications requiring high luminance in variable ambient conditions.
- OLED:Flexible organic alternatives are displacing mono LCDs in price-sensitive wearable medical devices, compressing addressable volume in consumer-facing segments.
LCD architectures retain the dominant share, though TFT is expanding most quickly in industrial HMI refresh cycles.
End User:
Application maturity varies sharply across regulated versus unregulated equipment categories.
- Industrial Equipment:Process control interfaces and machine tool readouts constitute the mature volume base. REACH material qualification requirements extend supplier timelines by 8-14 months for European market access.
- Medical Devices:Portable diagnostic equipment demands custom form factors with extended temperature ratings. EU MDR compliance is accelerating qualification of alternative encapsulant materials.
- Consumer Electronics:AMOLED substitution pressure is most acute in handheld instrumentation segments.
- Automotive Displays:Secondary cluster information and climate control panels favor mono LCDs where color is non-essential.
Industrial Equipment commands the dominant share, while Medical Devices is climbing the fastest on premium positioning.
Application:
Customer procurement patterns separate specification-driven from cost-driven segments.
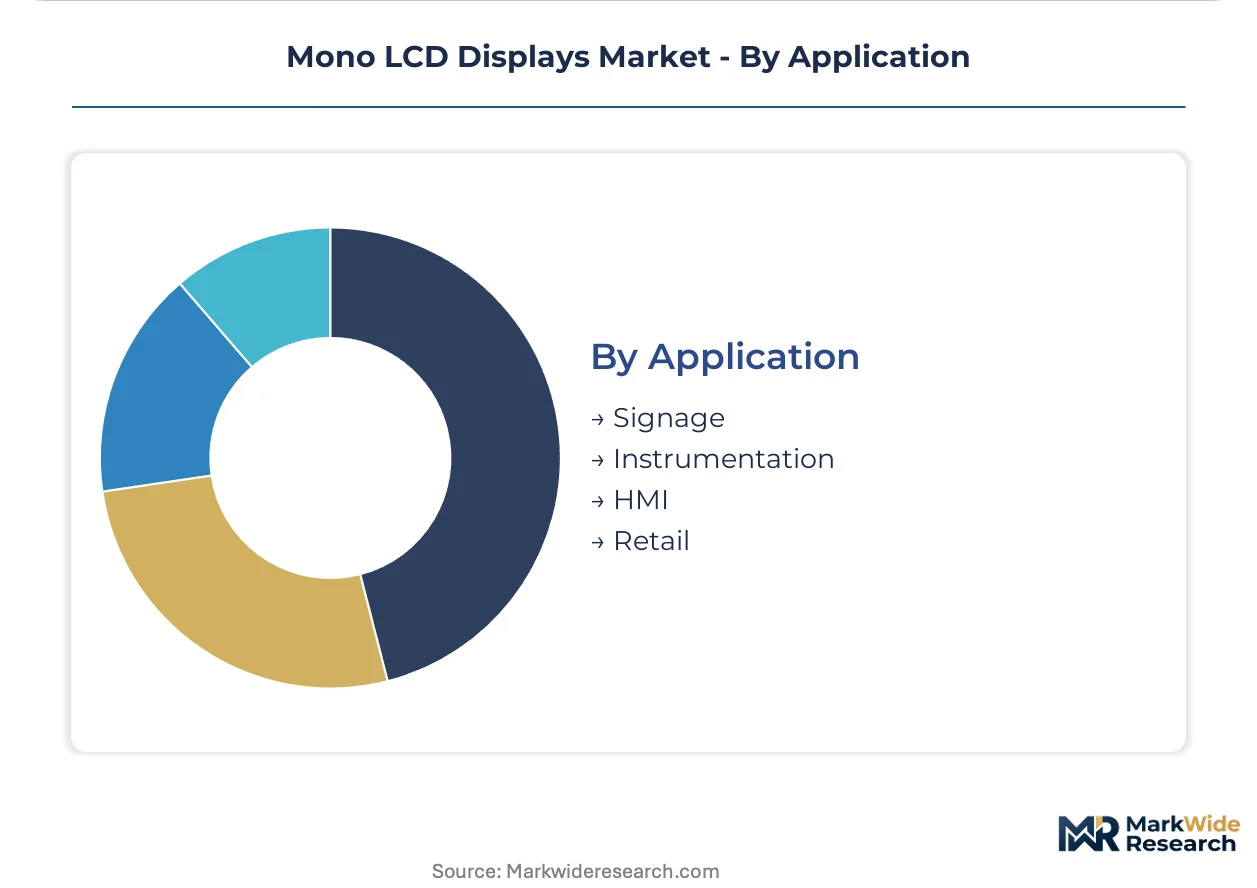
- HMI:Human-machine interface panels in manufacturing equipment require glove-compatible resistive touch and wide viewing angles. Shenzhen assembly corridors offer integrated COG bonding and touch lamination within single manufacturing footprints.
- Instrumentation:Test equipment and analytical instruments demand stable contrast ratios across operating temperature ranges.
- Signage:Public information displays prioritize luminance endurance over color fidelity.
- Retail:Point-of-sale terminals and shelf-edge labels drive volume in price-sensitive configurations.
HMI captures the dominant share, with Instrumentation gaining share fastest on medical and laboratory equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: German industrial buyers prioritize REACH-compliant subsystem sourcing, while Chinese integrators optimize for Shenzhen corridor logistics velocity and domestic GB standard alignment.
China
Shenzhen's electronics manufacturing corridor concentrates module assembly clusters serving medical device and automotive Tier 1 suppliers with integrated COG bonding and resistive touch lamination. SAMR enforces tightening GB energy efficiency standards that constrain non-compliant import access and force driver architecture redesigns. Dongguan manufacturing zones face COG bonding technician scarcity as training pipelines fail to match expansion rates.
Germany
Mittelstand equipment manufacturers in Bavaria and Baden-Württemberg expand adoption of character displays for machine tool readouts and process control interfaces. EU REACH frameworks restrict hazardous substance profiles in display glass and driver IC packaging, reshaping material qualification cycles. KBA-regulated automotive instrument cluster suppliers adopt STN modules for secondary information displays where color differentiation is non-essential.
United States
Industrial automation OEMs consolidate vendor relationships around module suppliers offering integrated firmware customization and application engineering support. FDA-regulated medical device manufacturers demand bespoke form factors with extended temperature ratings for portable diagnostic equipment. Midwest machine builders cede specification influence to direct OEM-module manufacturer relationships prioritizing single-source accountability.
Japan
METI-backed industrial equipment manufacturers source stable contrast ratio displays for test equipment and analytical instruments across operating temperature ranges. JIS standards govern electromagnetic compatibility thresholds that constrain module procurement from non-compliant suppliers. Chubu/Nagoya manufacturing belts concentrate precision instrumentation demand requiring glove-compatible resistive touch interfaces.
South Korea
MFDS-regulated medical device OEMs accelerate qualification of alternative encapsulant materials to preempt EU MDR regulatory friction. Seoul Capital Area electronics integrators seek drop-in module solutions with bundled LED backlight drivers to compress procurement cycles. Busan-Ulsan automotive suppliers evaluate mono LCD configurations for secondary cluster information panels where AMOLED cost structures prove prohibitive.
Mono LCD Displays Market Competitive Landscape
Capability concentration sits with captive glass substrate holders; scale advantage sits with high-volume COG bonding operators. The vendor base separates into three tiers: integrated display material suppliers, specialized module assemblers, and regional distribution-focused configurators. Dominant competitive moves include backward integration into driver IC sourcing and geographic expansion through Shenzhen corridor facility investments.
Among China-based fabricators, Tianma Microelectronics and Truly Semiconductors occupy positions at opposite ends of the value chain. Tianma Microelectronics exemplifies the captive-capability archetype through in-house glass substrate production. Truly Semiconductors represents specialized COG bonding competence concentrated in small-format graphic segments. Kingtech Group Co., Ltd. anchors the regional distribution tier with module configuration services for industrial integrators seeking drop-in solutions.
| Leading Market Players |
|---|
| Tianma Microelectronics |
| Truly Semiconductors |
| Kingtech Group Co., Ltd. |
| Seacomp |
| ZhSunyco |
| Newhaven Display International Inc. |
| New Vision Display (Shenzhen) Co., Ltd. |
| E3 Innovation Inc. |
| Winstar Display Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Shenzhen COG bonding facilities is compressing lead times and hardening pricing power for module integrators serving automotive Tier 1 suppliers. This utilization squeeze simultaneously rewards captive glass substrate holders with margin expansion while forcing independent assemblers toward spot-market substrate sourcing at elevated premiums.
Pricing Analysis
Long-term offtake agreements dominate procurement between German Mittelstand equipment manufacturers and established module suppliers, insulating buyers from spot volatility in glass substrate markets. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant medical-grade configurations from industrial HMI workhorse modules and price-sensitive retail signage formats. Cost compression in economy-tier character displays is intensifying because AMOLED alternatives are penetrating wearable medical device segments previously served by mono LCDs. Automotive Tier 1 suppliers exhibit lowest price sensitivity due to qualification lock-in effects, while retail POS terminal manufacturers face acute margin pressure from commoditized Asian imports.
Supply Chain Analysis
Tianma Microelectronics and Truly Semiconductors anchor contract-manufacturing concentration across China's Guangdong corridor, with captive glass melting capacity at the former and specialized COG bonding lines at the latter. Module assembly draws from Japanese driver IC fabrication, South Korean polarizer films, and domestic Chinese LED backlight components. Single-source vulnerability concentrates in anisotropic conductive film supply from limited qualified vendors. Distribution runs through Shenzhen electronics markets for spot procurement and direct OEM relationships for validated industrial subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AMOLED substitution in portable diagnostic equipment threatens mono LCD incumbents with volume erosion in the fastest-growing medical device segment. Defense requires repositioning around integration complexity and regulatory qualification moats that organic alternatives cannot easily replicate.
For Market Incumbents: Insulate core industrial HMI relationships by deepening captive glass substrate capacity and pre-qualifying alternative encapsulant materials ahead of EU MDR enforcement. Prioritize backward integration into driver IC sourcing to offset margin compression from Shenzhen COG bonding technician scarcity. Anchor long-term offtake agreements with Bavarian Mittelstand machine builders before module displays commoditize further.
For New Entrants and Emerging Players: Pursue aftermarket refurbishment services for legacy industrial equipment interfaces, where margin pools are shifting away from virgin panel production toward recalibration and backlight replacement revenue. Target German automotive instrument cluster suppliers seeking STN modules for secondary information displays where KBA regulations favor qualified incumbents but service gaps exist. Lead with integrated firmware customization capabilities to differentiate from commodity Shenzhen assemblers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across custom medical display configurations as EU MDR compliance extends qualification timelines and forces dedicated cleanroom investments. Long-term viability favors specialists with established REACH documentation infrastructure and direct OEM relationships in German-speaking Europe. Watch technician training pipeline expansion rates in Dongguan manufacturing zones as an inflection signal for COG bonding capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Sourcing | Captive semiconductor procurement reduces exposure to Japanese foundry lead time volatility. |
| REACH-Compliant Material Qualification | Preemptive ECHA documentation accelerates European medical device OEM access by 8-14 months. |
| Aftermarket Refurbishment Service Launch | Legacy interface recalibration captures margin pools shifting from virgin panel production. |
| COG Bonding Technician Training Pipeline | Dedicated cleanroom operator programs address Shenzhen-Dongguan expansion bottlenecks. |
| Integrated Resistive Touch Module Development | Single-drop configurations reduce BOM complexity for glove-compatible industrial HMI designers. |
Research Methodology
Desk research of SEC filings from display material suppliers, EU ECHA substance restriction databases, and Chinese SAMR GB standard releases preceded structured interviews with industrial automation procurement directors, medical device biomedical engineers, automotive Tier 1 supplier quality managers, and Shenzhen module assembler operations heads. Primary intelligence combined with secondary validation across customs trade records and hospital procurement databases enabled bottom-up volume triangulation against top-down industry association aggregates.
Assumptions held fixed include SAMR enforcement timelines for GB energy efficiency standards and REACH substance restriction phase-in schedules, while variables included AMOLED cost reduction trajectories and COG bonding technician training graduation rates. The analytical framework modeled product type, technology architecture, end-user industry, and application across the analysis window, with CAGRs derived from segment-level demand elasticity and substitution coefficient estimation. Forecast inputs incorporated German Mittelstand capital equipment spending patterns and Shenzhen electronics corridor logistics velocity indices.
Sensitivities concentrate around AMOLED penetration rates in portable medical devices and MEE carbon intensity benchmark enforcement timelines affecting Chinese manufacturing cost structures. Quarterly review of Dongguan COG bonding facility utilization rates and EU MDR alternative encapsulant qualification progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Volumetric Display Market
Display Technologies
OLED Laptops Market
Display Technologies
Collaboration Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
North America Industrial Display Market
Display Technologies
Vietnam Displays Market
Display Technologies
Display Material Market
Display Technologies
Computer Monitor Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Global UHD Display Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Industrial Display Market