
 Global Wearable Display Market | 2026-2036
Global Wearable Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Display Market Outlook
The EU AI Act is repositioning the compliance burden for wearable display manufacturers serving European healthcare and industrial segments. Samsung Electronics leverages vertical integration across OLED panel fabrication and finished device assembly to sustain cost advantages in smartwatch displays. LG Display anchors its competitive position through manufacturing scale in flexible OLED substrates for fitness bands and head-mounted displays. Japan Display specializes in high-resolution LTPS backplane technology, differentiating its offerings for augmented reality headsets.
Wearable displays are compact visual output devices engineered with pixel densities exceeding 500 ppi and luminance thresholds above 1000 nits for outdoor readability, serving as human-machine interfaces across health monitoring, immersive gaming, and industrial guidance systems. Smartwatches command the largest revenue pool among product types due to consumer volume scale, while head-mounted displays represent the fastest-expanding segment as microLED technology matures for augmented reality applications. OLED technology dominates current production owing to established supply chains, though microLED is displacing incumbent platforms in premium segments where power efficiency and daylight visibility determine purchasing decisions.
The FDA governs clinical-grade wearable displays in the United States through 510(k) premarket notification pathways, while the EU AI Act and MDR impose layered conformity obligations on devices deployed in European surgical and diagnostic settings. China's NMPA and SAMR enforce GB standards for electromagnetic compatibility and optical safety, shaping market access for foreign manufacturers. Stakeholders must monitor divergence between regional electromagnetic exposure limits and biometric data governance frameworks as these regulations determine which product architectures achieve multi-territory certification.
Market Dynamics
MicroLED transfer yield improvements are compressing unit economics for augmented reality headsets while EU AI Act reclassifications force architectural redesigns for clinical-grade wearables entering European surgical settings.
Growth Catalysts
- EU AI Act High-Risk Reclassification:Surgical head-mounted displays now face mandatory conformity assessments under MDR and AI Act frameworks, creating certified-supplier premiums for compliant manufacturers.
- South Korean Panel Ecosystem:Domestic OLED and microLED substrate clusters in Gyeonggi-do and Gumi anchor captive supply for smartwatch and fitness band display modules.
- Remote Diagnostics Protocols:Healthcare systems in Germany and Japan are embedding head-mounted displays into telemedicine workflows for specialist consultation during emergency interventions.
Market Restraints
- Indium Gallium Zinc Oxide Volatility:IGZO backplane material costs fluctuate with rare earth concentrate availability, pressuring margins on high-resolution LTPS alternatives.
- Wafer-Level Bonding Bottlenecks:MicroLED mass transfer yields remain below commercial thresholds, constraining volume scaling for sub-10-micron pixel architectures.
- Electromagnetic Exposure Divergence:SAR limits vary between FCC guidelines and China's GB 8702 standards, fragmenting RF engineering requirements for multi-territory products.
Strategic Opportunities
- India PLI Scheme Incentives:Display module assembly incentives under the Production Linked Incentive scheme attract component sourcing shifts for mid-tier smartwatch panels.
- MicroLED-OLED Hybrid Architectures:Tandem configurations combining OLED emitters with microLED backlights enable daylight-readable fitness trackers without full microLED cost burdens.
- Direct-to-Enterprise Distribution:Industrial safety wearables bypass consumer retail channels through specialized integrators serving construction and logistics operators in Australia and Canada.
Industry Challenges
- Optical Design Talent Scarcity:Waveguide engineering expertise concentrates in select research clusters, extending recruitment timelines for AR headset development teams.
- Biometric Data Governance Fragmentation:Divergent HIPAA, GDPR, and PIPL requirements complicate cloud-sync architectures for health-monitoring wearables with multi-jurisdiction users.
- Cleanroom Expansion Requirements:MicroLED fabrication demands Class 1000 or better environments, stretching capital deployment cycles for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Display Market |
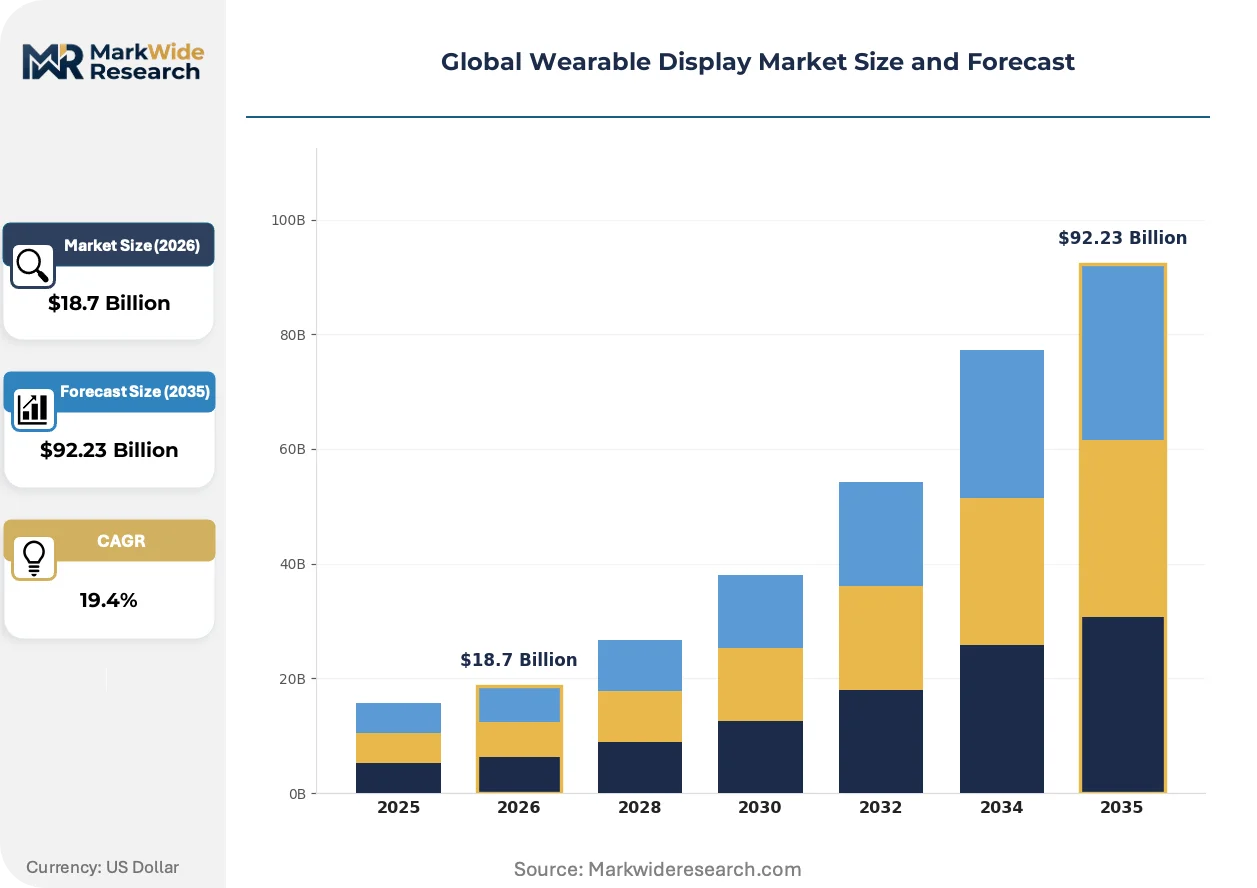
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Fitness Bands, Smartwatches, Head-Mounted Displays Technology: LED, OLED, MicroLED, E-ink End User: Healthcare, Fitness Enthusiasts, Industrial Workers, Consumers Application: Health Monitoring, Gaming, Navigation, Augmented Reality |
| Companies Covered | Samsung Electronics, LG Display, Japan Display, BOE Technology Group, AU Optronics, Kopin Corporation, eMagin Corporation, Seiko Epson, Sony Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Display Market Strategic Shifts
Transfer printing and laser lift-off techniques are reshaping display stack architectures while regulatory layering between medical device and AI system frameworks complicates product qualification pathways.
MicroLED epitaxy on sapphire substrates is electrifying brightness performance for outdoor-visible augmented reality headsets. Military and industrial safety buyers are accelerating procurement evaluations as luminance thresholds exceed 3000 nits. This brightness surge is compressing the addressable market for reflective LCD alternatives in premium head-mounted segments.
The EU AI Act's Annex III high-risk system classification is forcing surgical navigation wearables through dual MDR and AI conformity assessments. Manufacturers must now document algorithmic transparency and post-market monitoring protocols alongside traditional biocompatibility testing. German and French notified bodies are experiencing backlog extensions as submission volumes concentrate in the 2024-2025 window.
Hospital procurement departments are consolidating vendor lists around FDA 510(k) and CE-MDR dual-certified display suppliers. Single-certification manufacturers are losing access to integrated health system contracts in the United States and European Union. This consolidation is most visible in academic medical centers operating across multiple states or member countries with unified device evaluation committees.
Global Wearable Display Market Segmentation
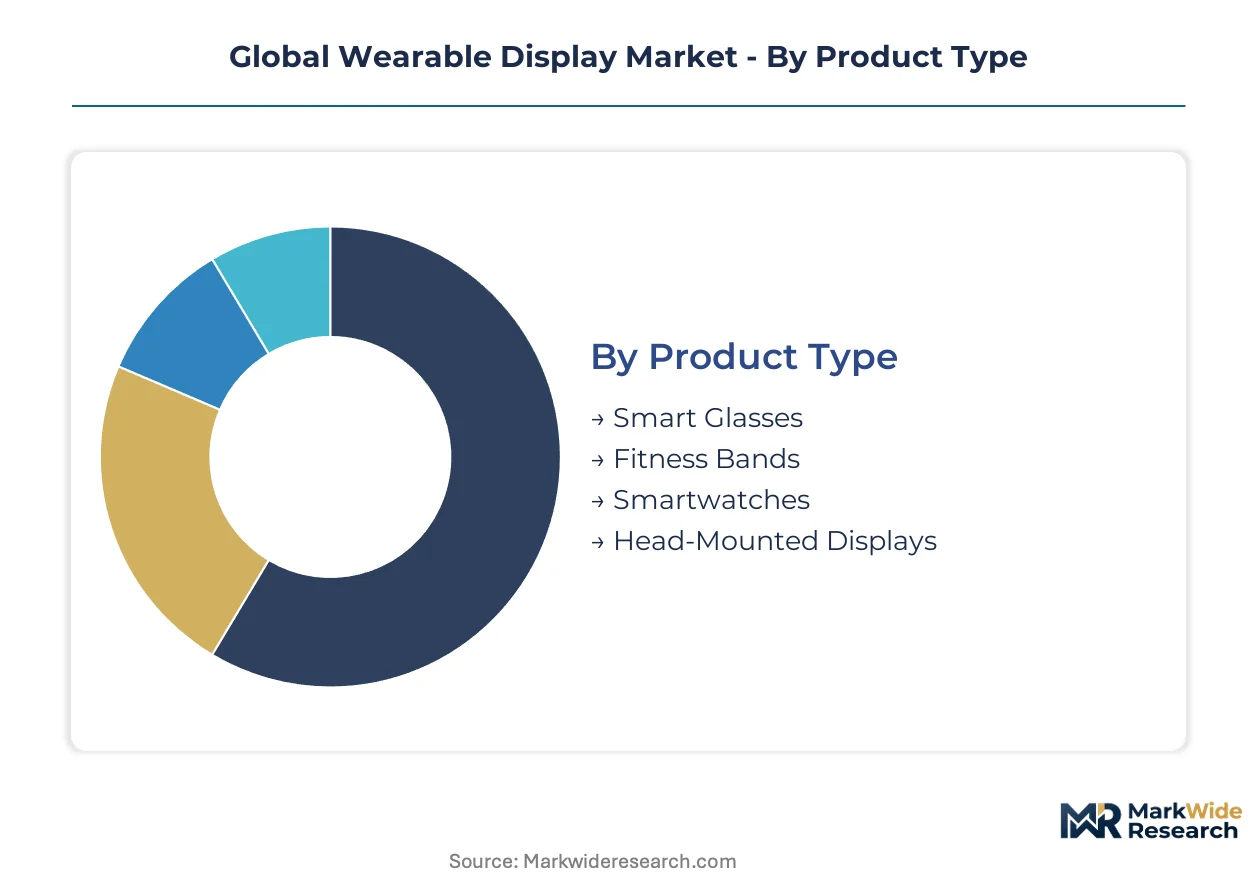
Wearable display architectures diverge sharply between mass-volume consumer devices and precision-engineered professional systems. Segmentation reveals how technical specifications, regulatory pathways, and end-use environments fragment manufacturing priorities across the value chain.
Product Type:
Volume concentration in wrist-worn devices contrasts with premium pricing power in head-mounted systems, creating a bifurcated revenue architecture.
- Smartwatches:OLED panels with pixel densities exceeding 500 ppi dominate this segment, serving health-monitoring ecosystems in South Korea and the United States. Samsung Electronics and LG Display anchor captive supply chains that compress module costs for mid-tier fitness integrations.
- Head-Mounted Displays:MicroLED transfer printing is reshaping brightness thresholds above 3000 nits for outdoor-visible augmented reality. German surgical navigation protocols and Japanese industrial safety mandates are accelerating procurement evaluations for clinical-grade systems.
- Smart Glasses:Waveguide optics paired with microLED light engines enable lightweight enterprise deployments in logistics and field service.
- Fitness Bands:Reflective LCD and basic OLED configurations balance battery endurance against cost constraints in price-sensitive Asian markets.
Today's leader: Smartwatches. Tomorrow's challenger: Head-Mounted Displays.
Technology:
Established supply chains favor incumbent platforms while epitaxy breakthroughs reposition emerging architectures for premium displacement.
- OLED:Flexible substrates with LTPS backplanes command current production volumes through mature Gyeonggi-do fabrication clusters. LG Display and Samsung Electronics sustain cost advantages via in-house driver IC integration and polarizer lamination.
- MicroLED:Laser lift-off techniques from sapphire wafers are compressing mass transfer yields toward commercial thresholds. Military luminance requirements and EU AI Act surgical certifications are concentrating demand in defense and academic medical center procurement channels.
- LED:Edge-lit configurations persist in cost-optimized fitness bands where pixel density requirements remain below 300 ppi.
- E-ink:Bistable electrophoretic displays serve ultra-low-power notification badges and hybrid smartwatch faces with week-long battery cycles.
Current dominance rests with OLED. MicroLED is climbing the fastest toward premium segment share.
End User:
Regulatory layering separates clinical-grade certification pathways from consumer retail channels, fragmenting go-to-market architectures.
- Healthcare:FDA 510(k) and EU MDR dual-certified displays command vendor consolidation in United States academic medical centers and German hospital procurement. Algorithmic transparency documentation under the EU AI Act Annex III classification is extending conformity timelines for surgical navigation wearables.
- Industrial Workers:ANSI Z87.1 eye safety compliance and FCC SAR limits shape RF engineering for multi-territory construction and logistics deployments in Australia and Canada.
- Fitness Enthusiasts:Biometric data governance fragmentation between HIPAA, GDPR, and China's PIPL complicates cloud-sync architectures for multi-jurisdiction users.
- Consumers:Price elasticity concentrates demand in mid-tier smartwatch configurations with standardized OLED panels from South Korean supply chains.
Healthcare certification premiums currently dominate value capture. Industrial safety procurement is expanding most quickly as luminance thresholds enable outdoor AR guidance.
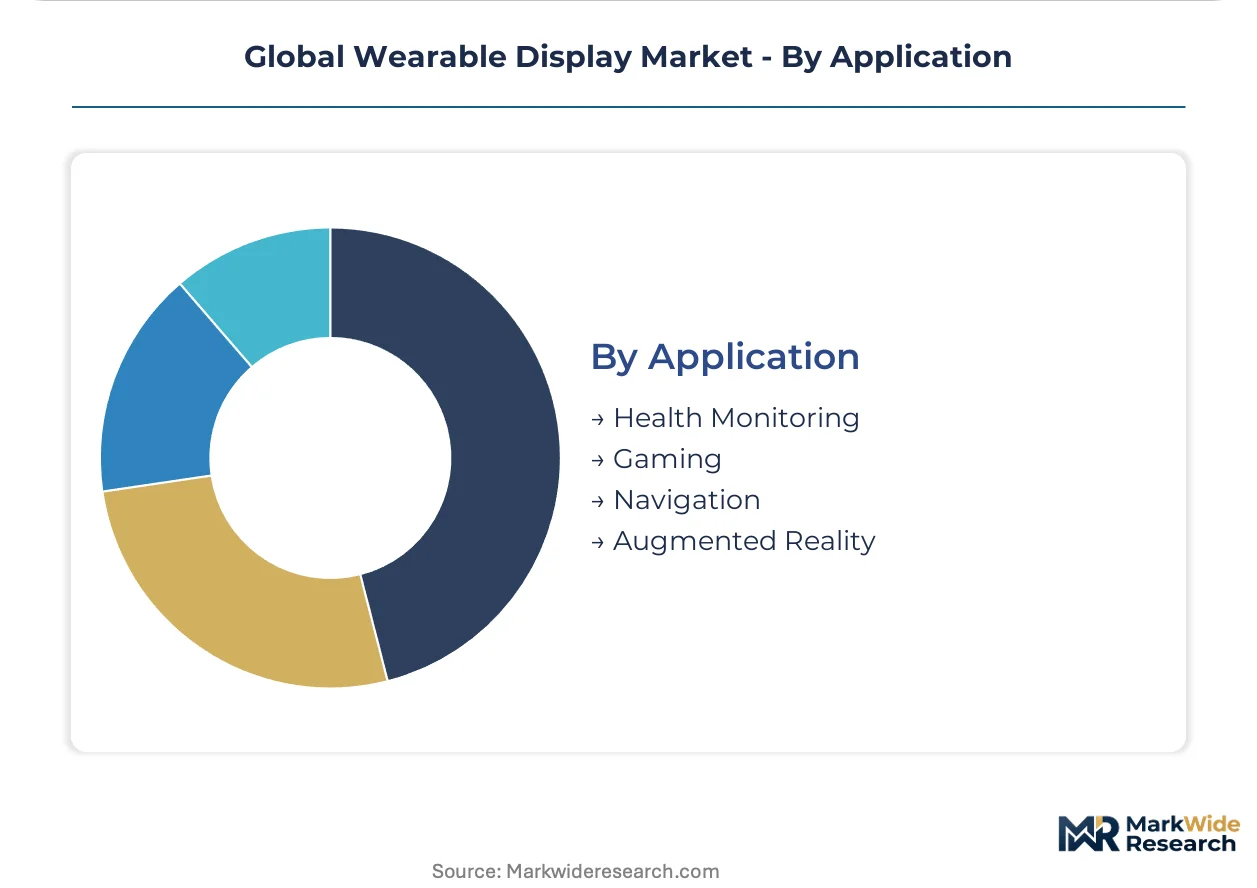
Application:
Use-case specificity determines optical stack complexity, from reflective readability in direct sunlight to sub-millisecond latency for immersive rendering.
- Augmented Reality:Waveguide engineering expertise concentrates in select research clusters, extending recruitment timelines for AR headset development teams. German automotive assembly lines and Japanese maintenance protocols are embedding AR guidance for complex procedural workflows.
- Health Monitoring:PPG sensor fusion with display stacks requires electromagnetic compatibility certification under China's GB 8702 and FCC Part 15 guidelines, fragmenting RF architecture requirements.
- Gaming:Refresh rates above 120 Hz and motion-to-photon latency below 20 milliseconds differentiate premium head-mounted systems for immersive entertainment.
- Navigation:GPS-integrated smart glasses with heads-up waypoint overlays serve cycling and hiking segments in North American and European outdoor recreation markets.
Augmented Reality commands the steepest expansion trajectory as microLED maturity enables daylight-visible enterprise deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent concentrates in South Korea's Gyeonggi-do corridor, where Samsung Electronics and LG Display anchor captive supply chains for OLED and emerging microLED architectures.
United States
FDA 510(k) certification requirements concentrate procurement authority in academic medical centers across Massachusetts and California. HIPAA compliance frameworks shape cloud-sync architectures for health-monitoring wearables with multi-state user bases. Boston's Route 128 corridor hosts waveguide engineering clusters serving defense and surgical navigation applications.
Germany
EU AI Act Annex III high-risk system classifications are extending conformity timelines for surgical head-mounted displays entering hospital procurement channels. MDR notified bodies in Berlin and Munich are experiencing submission backlogs through 2025. Bavaria's automotive assembly lines are embedding AR guidance systems for complex procedural workflows.
South Korea
Domestic OLED and microLED substrate clusters in Gyeonggi-do and Gumi compress module costs for smartwatch and fitness band integrations. MFDS medical device regulations align with international standards to facilitate export certification. Seoul Capital Area fabrication facilities sustain backward integration across driver IC production and polarizer lamination.
China
NMPA clinical-grade display approvals and GB 8702 electromagnetic compatibility standards fragment RF engineering requirements for multi-territory products. SAMR enforcement of optical safety protocols shapes market access for foreign manufacturers. Yangtze River Delta panel fabrication centers are scaling LTPS backplane capacity for augmented reality headset supply.
Japan
METI industrial safety mandates are accelerating procurement evaluations for head-mounted displays in manufacturing and maintenance protocols. PMDA convergence with international medical device standards streamlines dual-certification pathways for surgical navigation systems. Chubu region precision optics clusters specialize in high-resolution LTPS backplane technology for AR applications.
Global Wearable Display Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated vendor architecture. Panel fabrication scale concentrates among integrated electronics groups while waveguide engineering expertise remains locked in select research clusters. Three archetypes dominate: vertically integrated display conglomerates, specialty microLED epitaxy houses, and precision optics engineering boutiques. Capacity expansion in Gyeonggi-do and strategic partnerships for microLED transfer printing represent the dominant competitive vectors.
Within the integrated conglomerate tier, Samsung Electronics and LG Display occupy positions shaped by captive supply chain control across OLED substrate fabrication and finished device assembly. Japan Display exemplifies the precision-engineering archetype, anchoring high-resolution LTPS specialization for augmented reality headset applications. These three entities represent distinct strategic postures: scale-driven vertical integration, manufacturing breadth across flexible substrates, and focused backplane technology differentiation.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| Japan Display |
| BOE Technology Group |
| AU Optronics |
| Kopin Corporation |
| eMagin Corporation |
| Seiko Epson |
| Sony Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Academic medical center procurement committees in Germany and the United States command vendor consolidation around dual-certified suppliers, embedding FDA 510(k) and CE-MDR compliance premiums into contract structures. This buyer concentration rewards manufacturers with pre-qualified regulatory portfolios while squeezing margins on single-certification competitors.
Pricing Analysis
Bundled surgical navigation systems with post-market monitoring protocols separate from unbundled display module sales, with three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU AI Act Annex III and FDA 510(k) pathways drives price differentiation, while cost compression in mid-tier smartwatch panels intensifies due to South Korean captive supply advantages. Hospital procurement shows lowest price sensitivity; fitness band OEMs in price-sensitive Asian markets exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for clinical-grade head-mounted displays include refurbishment cycles for surgical navigation hardware and component recovery from end-of-life fitness bands. Manufacturing concentrates in South Korea, China, and Japan, with Gyeonggi-do OLED clusters and Yangtze River Delta LTPS facilities anchoring substrate supply. Indium gallium zinc oxide, rare earth concentrates, and sapphire wafer substrates feed into panel fabrication, with single-source vulnerability in microLED epitaxy equipment constraining capacity expansion. Distribution runs through specialized medical device integrators for healthcare segments and consumer electronics retail channels for wrist-worn devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as healthcare procurement shifts toward microLED-enabled surgical displays with 3000+ nits luminance and dual regulatory certification.
For Market Incumbents: Deepen backward integration into driver IC production and polarizer lamination to defend margin position against emerging microLED epitaxy houses. Prioritize capacity addition in Gyeonggi-do to maintain captive supply advantages as transfer printing yields approach commercial thresholds. Lock in long-term hospital system contracts before EU AI Act conformity backlogs clear. For New Entrants and Emerging Players: MicroLED transfer printing expertise offers the most penetrable wedge for premium AR headset supply to German automotive assembly lines and Japanese maintenance protocols. Target industrial safety procurement channels in Australia and Canada where ANSI Z87.1 compliance creates certification barriers for established consumer-focused suppliers. Pursue direct-to-enterprise distribution partnerships bypassing retail channel costs. For Investors and Strategic Acquirers: Defense contractors and academic medical center procurement offices are the most active acquirer categories in this space, consolidating waveguide engineering boutiques and microLED epitaxy specialists. Long-term viability over the next decade hinges on regulatory certification breadth rather than volume scale alone. Monitor microLED mass transfer yield announcements and EU notified body clearance timelines as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | CE-MDR and FDA 510(k) pre-qualification unlocks academic medical center vendor consolidation in Massachusetts and Bavaria. |
| MicroLED Epitaxy Partnership | Sapphire substrate supply agreements with South Korean clusters compress brightness threshold timelines for outdoor AR. |
| Waveguide Engineering Acquisition | Precision optics boutiques in Boston's Route 128 corridor anchor defense and surgical navigation development pipelines. |
| India PLI Assembly Shift | Display module incentives under India's Production Linked Incentive scheme attract mid-tier smartwatch sourcing diversification. |
| Enterprise Distribution Channel | Specialized integrators serving Canadian logistics operators bypass consumer retail margin erosion. |
Study Parameters
Bottom-up healthcare and industrial end-use modeling reconciled against top-down OLED and microLED substrate supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers at German hospital procurement departments, GPO contracts managers in the United States, display panel fabrication executives in Gyeonggi-do, and waveguide engineering directors in Boston's Route 128 corridor combined with secondary validation from FDA 510(k) filings, EU MDR notified body submission databases, MFDS medical device registrations, and SAMR GB standard enforcement records.
Input-output matrices map display technology adoption across product type, end user certification requirements, and application luminance thresholds over the projection horizon. Segmentation dimensions include technology platform, regulatory pathway, and regional procurement cluster. CAGRs derive from fitted growth curves against historical certification timelines and microLED yield improvement trajectories. Forecast inputs incorporate EU AI Act Annex III implementation pace and NMPA clinical-grade approval velocity.
The model holds under stable regulatory divergence between FCC SAR guidelines and China's GB 8702 standards; deviation in electromagnetic exposure limit harmonization or microLED transfer yield breakthroughs would shift volume allocation between OLED and emerging architectures. Practitioners should monitor EU notified body backlog clearance and sapphire substrate supply announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Holographic Display Market
Display Technologies
DLP Projector Market
Display Technologies
North America Computer Monitor Market
Display Technologies
3D Holographic Display Market
Display Technologies
Global Display Market
Display Technologies
Transparent Digital Signage Market
Display Technologies
Global Display Panel Market
Display Technologies
Phosphor Screen Market
Display Technologies
Smart Screen Market
Display Technologies
Projector Screen Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Smartphone Display Market