
 Camera with Flip Screen Market | 2026-2036
Camera with Flip Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Camera with Flip Screen Market Insights
Buyer concentration among professional content creators is decoupling from the legacy photography base as casual users and social media producers multiply across platforms. Canon leverages its service-network density to sustain replacement demand among wedding and event professionals. Sony dominates full-frame mirrorless flip-screen engineering, while Fujifilm differentiates through film-simulation color science and retro industrial design that commands premium positioning.
A camera with flip screen incorporates an articulating or vari-angle LCD panel mounted on a hinge mechanism, typically offering 180-degree forward rotation for self-framing and touch-input capability for focus and exposure control. The device serves commercial imaging workflows where operators must monitor composition while positioned in front of the lens. Mirrorless product types lead volume due to compact chassis design and live-view native architecture, while 4K video feature integration captures the fastest growth as streaming workflows displace still-only use cases. Wi-Fi connectivity and dual-display variants concentrate margin pools in prosumer and professional tiers where remote operation and multi-angle monitoring justify price premiums.
FCC equipment authorization governs radio-frequency modules in US-bound units, while EU RoHS and REACH directives restrict hazardous substances in flex-cable and solder formulations. China's MIIT enforces GB standards for electromagnetic compatibility and labeling, shaping factory-floor testing protocols for export and domestic models. Stakeholders must monitor how platform algorithm shifts toward vertical video formats reshape sensor aspect-ratio priorities and hinge-mechanism durability specifications.
Market Dynamics
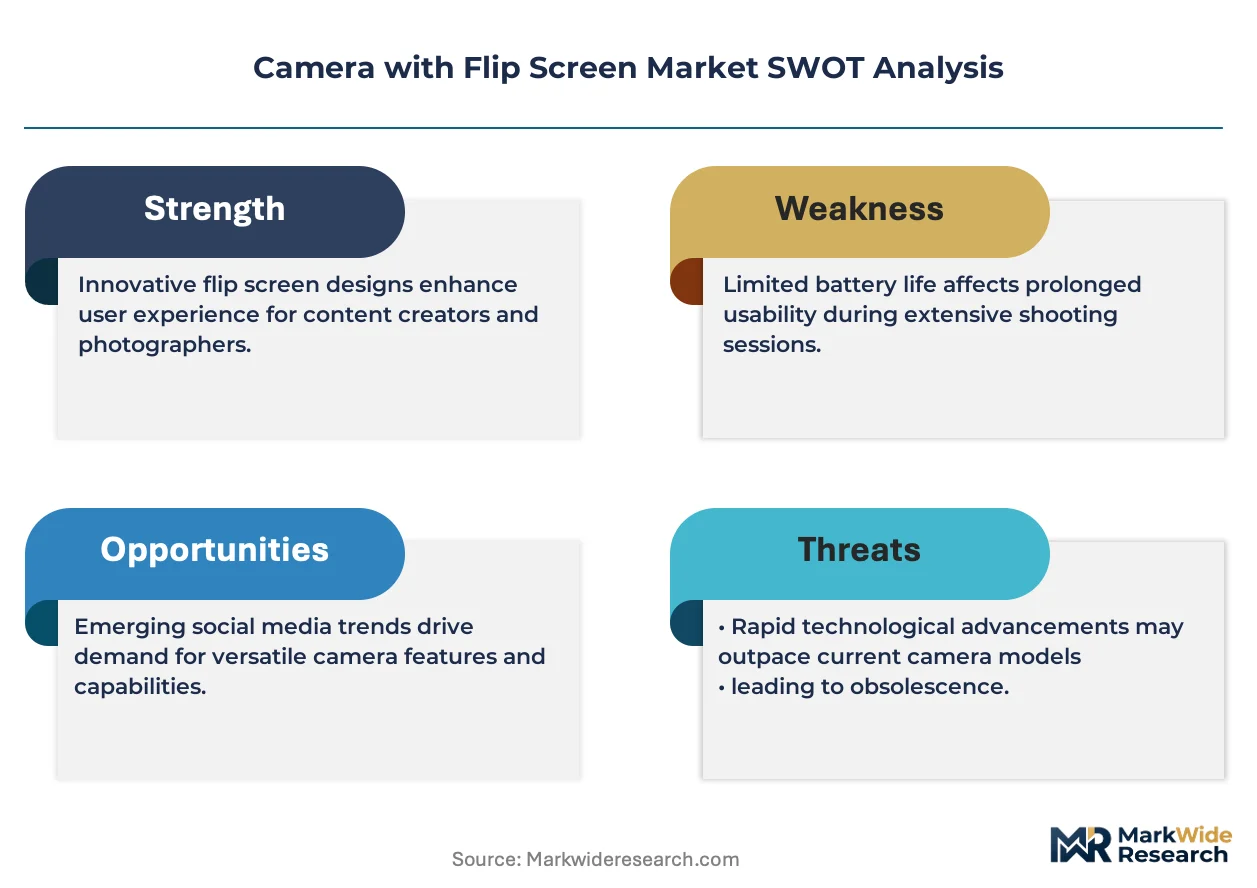
Sensor miniaturization and computational imaging advances are compressing hardware replacement cycles while shifting value capture toward software-defined features and cloud-connected workflows. This structural compression is forcing incumbents to defend margin pools through firmware subscription models and professional service tiers.
Growth Catalysts
- Platform algorithm shifts toward vertical video:TikTok, Instagram Reels, and YouTube Shorts prioritize 9:16 aspect-ratio content, driving demand for flip-screen cameras optimized for portrait-oriented capture workflows.
- China MIIT GB standards for electromagnetic compatibility:Streamlined factory-floor testing protocols accelerate domestic production scale and reduce export compliance friction for Shenzhen and Dongguan contract manufacturers.
- Live commerce penetration:Taobao Live and Douyin shopping streams create sustained hardware demand among individual sellers requiring professional self-monitoring capabilities.
Market Restraints
- CMOS sensor supply concentration:Sony and Samsung dominate image sensor fabrication, creating input cost volatility and allocation risk for second-tier camera assemblers.
- Smartphone computational photography substitution:Apple and Google multi-frame stacking and AI-driven portrait modes erode casual creator willingness to carry dedicated hardware.
- EU REACH substance restrictions:Hazardous substance limitations on flex-cable coatings and lead-free solder formulations increase BOM complexity and supplier qualification timelines.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives attract contract manufacturers to Noida and Chennai, creating regional supply alternatives to China concentration.
- AI-powered real-time background replacement:On-device neural processing engines enable virtual production workflows without green-screen infrastructure, opening mid-market creator segments.
- Direct-to-creator subscription channels:Bypassing traditional retail through Patreon-integrated hardware financing and firmware unlocks captures lifetime value from professional vloggers.
Industry Challenges
- Computational imaging talent scarcity:Firmware engineers with expertise in real-time HDR fusion and subject tracking command premium compensation, constraining R&D velocity at mid-tier manufacturers.
- FCC equipment authorization timelines:Radio-frequency module certification for Wi-Fi and Bluetooth connectivity creates six-to-nine month launch delays for US-bound product variants.
- Hinge mechanism durability standardization:Absence of unified cycle-test protocols across MIIT, FCC, and EU frameworks forces redundant validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera with Flip Screen Market |
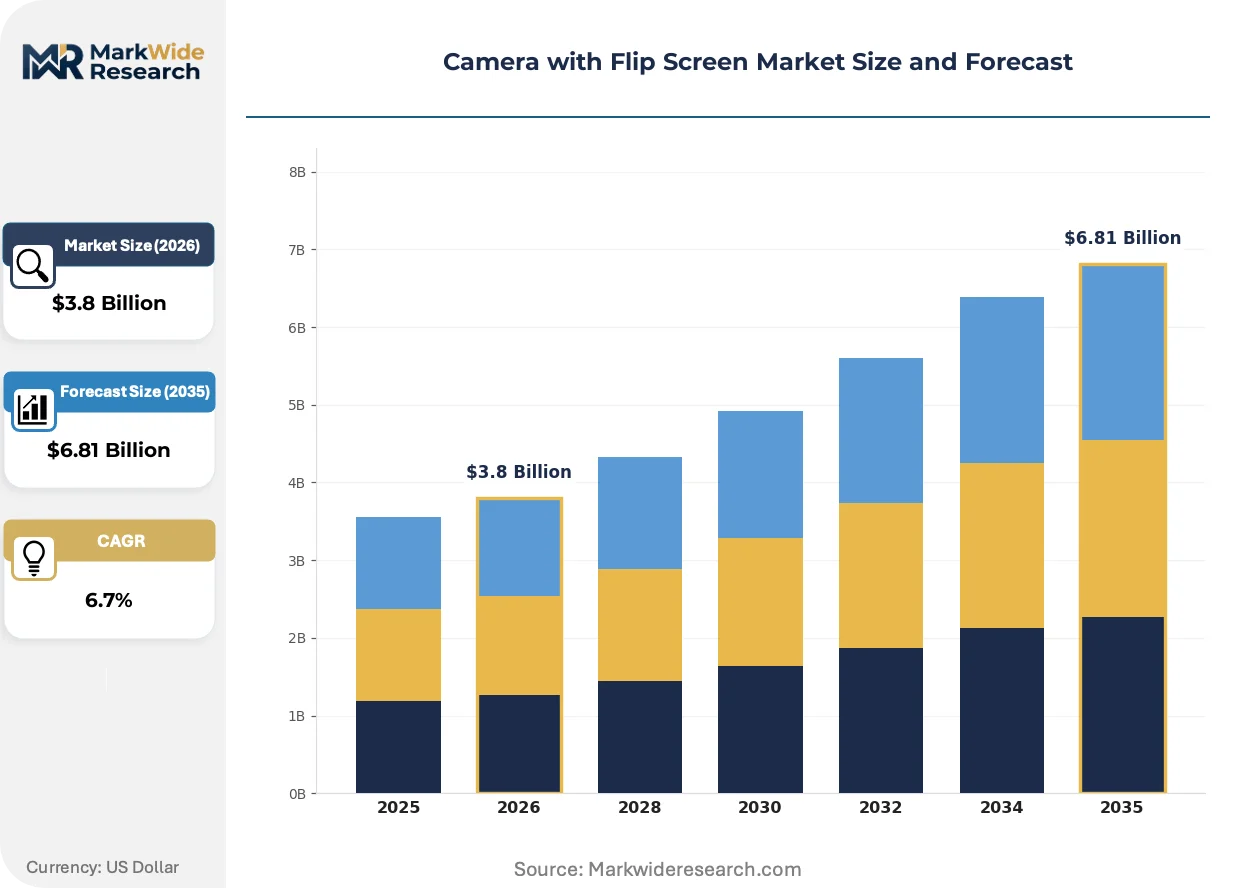
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Compact, Action End User: Professional Photographers, Vloggers, Content Creators, Casual Users Feature: Wi-Fi Connectivity, 4K Video, Touchscreen, Dual Display Application: Photography, Videography, Live Streaming, Social Media |
| Companies Covered | Sony, Panasonic, Fujifilm, Canon, Leica, CEDITA, Samsung, Nikon, Olympus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera with Flip Screen Market Trends and Innovations
Computational imaging and on-device AI processing are redefining what hardware must deliver, separating camera manufacturers into software-capable platforms and commodity enclosure assemblers. This bifurcation is compressing the addressable market for undifferentiated hardware while expanding margin pools for integrated workflow providers.
Stacked CMOS sensors with on-chip DRAM are electrifying readout speeds, enabling 4K 120fps capture without rolling-shutter artifacts. Wedding cinematographers and sports documentarians are adopting these sensors at replacement cycles under eighteen months. This velocity is compressing inventory holding periods for distributors and forcing earlier obsolescence of prior generation bodies.
EU CSRD sustainability disclosure requirements are mandating granular carbon-footprint reporting across electronics supply chains. Camera manufacturers must now document Scope 3 emissions from CMOS wafer fabrication through final assembly. Professional-tier product lines face the steepest compliance burden, with some vendors restructuring supplier contracts to capture primary emissions data from Shenzhen contract manufacturers.
Creator economy participants are consolidating purchasing authority through collective buying platforms and affiliate-direct arrangements. Individual YouTubers and TikTok influencers now negotiate volume discounts previously reserved for broadcast stations, disintermediating traditional camera retail. This concentration is most visible in Los Angeles and London, where creator co-working spaces aggregate equipment procurement for hundreds of independent producers.
Camera with Flip Screen Market Segmentation
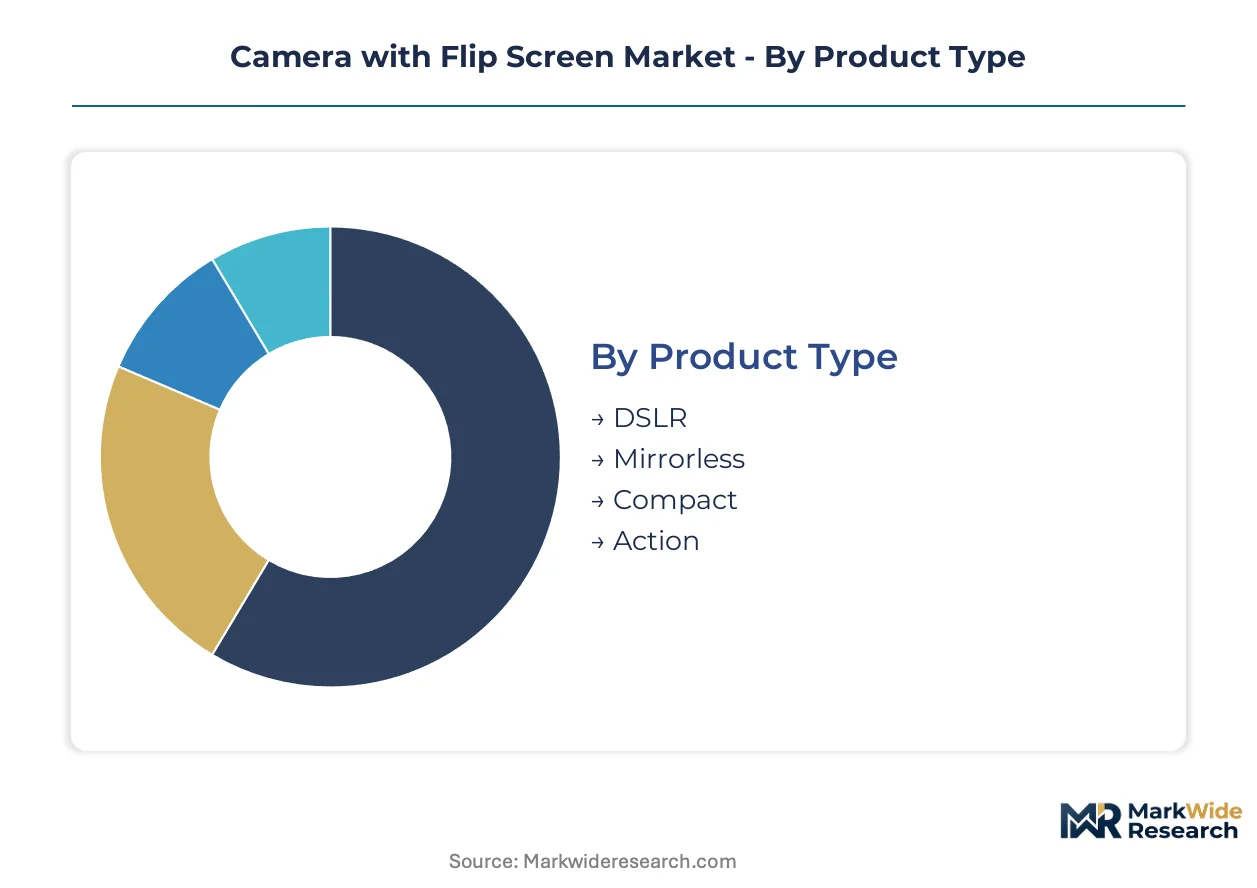
Segmentation in the camera with flip screen market reveals how hardware specifications, user workflows, and platform requirements create distinct purchasing cohorts. Manufacturers must align sensor formats, connectivity suites, and durability specifications to match the divergent priorities of wedding professionals, solo creators, and platform-native streamers.
Product Type:
Mirrorless chassis designs command volume leadership through compact form factors and native live-view architectures, while DSLR retains residual loyalty among legacy lens holders.
- Mirrorless:Short flange distances enable compact body designs with full-frame sensors. Demand concentrates among YouTube and TikTok creators in Los Angeles and London creator co-working spaces where equipment procurement aggregates across hundreds of independent producers.
- DSLR:Optical viewfinders and mature phase-detect autofirmware sustain replacement cycles among wedding photographers dependent on Canon's service-network density for event-season reliability.
- Compact:Fixed-lens designs with 1-inch sensors target travel vloggers prioritizing pocketability over interchangeable optics.
- Action:Ruggedized waterproof housings with hyper-wide lenses serve adventure sports documentarians capturing first-person POV footage.
Today's leader: Mirrorless. Tomorrow's challenger: Action.
End User:
Professional tiers anchor margin pools through firmware subscriptions and service contracts, while casual creator segments expand addressable volume through platform-optimized feature sets.
- Vloggers:Solo operators requiring 180-degree forward articulation for self-framing and touch-input exposure control. Procurement shifts toward collective buying platforms and affiliate-direct arrangements that disintermediate traditional camera retail.
- Professional Photographers:Wedding and event specialists demand dual-card redundancy and weather sealing. Replacement demand concentrates in North America and Western Europe where service-network proximity determines brand loyalty.
- Content Creators:Multi-platform producers prioritizing vertical video workflows and AI-powered background replacement without green-screen infrastructure.
- Casual Users:Smartphone graduates seeking dedicated hardware for milestone documentation and family imaging.
Vloggers expand most quickly. Professional photographers defend margin density.
Feature:
Connectivity and resolution specifications now determine tier placement more than sensor size alone, with wireless workflows and multi-angle monitoring justifying price premiums.
- 4K Video:3840x2160 capture at 60fps minimum has become table stakes for platform monetization eligibility. Wedding cinematographers adopt stacked CMOS sensors enabling 4K 120fps without rolling-shutter artifacts, compressing replacement cycles below eighteen months.
- Wi-Fi Connectivity:Real-time FTP transfer and smartphone tethering enable news photographers and sports documentarians to meet wire-service deadlines. FCC equipment authorization for radio-frequency modules creates six-to-nine month launch delays for US-bound variants.
- Touchscreen:Tap-to-focus and gesture-controlled menus reduce physical button dependency for gimbal-mounted operation.
- Dual Display:Secondary front-facing LCD panels assist vloggers monitoring composition while maintaining eye contact with the main lens.
4K Video anchors current purchasing. Wi-Fi Connectivity unlocks workflow integration premiums.
Application:
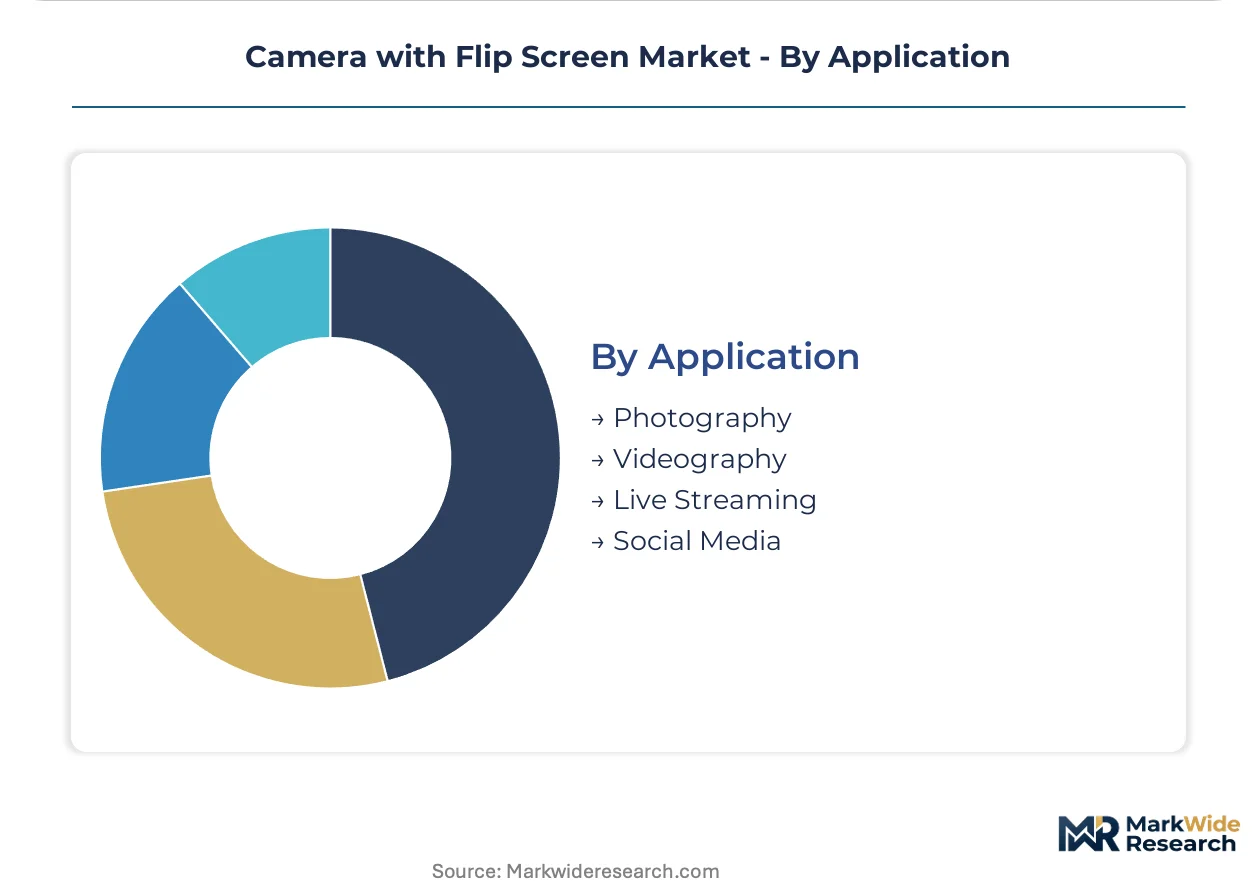
Still-capture workflows face compression as streaming and short-form video displace traditional photography revenue models among independent creators.
- Live Streaming:Sustained hardware demand from Taobao Live and Douyin shopping streams creates professional self-monitoring requirements among individual sellers. Clean HDMI output and unlimited recording duration separate broadcast-grade bodies from consumer tiers.
- Social Media:Vertical-native 9:16 capture optimized for TikTok, Instagram Reels, and YouTube Shorts. Platform algorithm shifts reshape sensor aspect-ratio priorities and hinge-mechanism durability specifications for portrait-oriented workflows.
- Videography:Documentary and commercial production requiring log gamma profiles and 10-bit 4:2:2 internal recording.
- Photography:Still-dominant workflows among fine art and portrait specialists prioritizing dynamic range and color fidelity over frame rates.
Live Streaming commands hardware investment intensity. Social Media gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's live commerce infrastructure generates hardware demand intensity that the United States' creator economy infrastructure has yet to match, while Japan's precision manufacturing base sustains premium sensor fabrication capabilities.
China
Taobao Live and Douyin shopping streams drive sustained demand for professional self-monitoring capabilities among individual sellers. MIIT enforces GB standards for electromagnetic compatibility and labeling, shaping factory-floor testing protocols for export and domestic models. Shenzhen and Dongguan host dense clusters of domestic brands and contract manufacturers where production scale accelerates.
United States
Wedding and event professionals concentrate replacement demand through service-network proximity considerations in major metropolitan markets. FCC equipment authorization governs radio-frequency modules in US-bound units, creating six-to-nine month launch delays for Wi-Fi and Bluetooth connectivity variants. Los Angeles creator co-working spaces aggregate equipment procurement for hundreds of independent producers.
Japan
Stacked CMOS sensor development with on-chip DRAM electrifies readout speeds for 4K 120fps capture applications. METI industrial policy supports precision manufacturing capabilities that underpin premium imaging component fabrication. Tokyo and Osaka metropolitan areas concentrate R&D facilities for computational imaging advances.
Germany
EU CSRD sustainability disclosure requirements mandate granular carbon-footprint reporting across electronics supply chains. REACH substance restrictions on flex-cable coatings and lead-free solder formulations increase BOM complexity for manufacturers serving European markets. Bavaria and Baden-Württemberg host engineering centers addressing professional-tier compliance burdens.
India
Production-linked incentive schemes attract contract manufacturers to Noida and Chennai, creating regional supply alternatives to China concentration. BIS certification requirements for electronics imports shape domestic market entry protocols for international brands. Maharashtra and Karnataka states emerge as assembly hubs for regional distribution.
Camera with Flip Screen Market Competitive Landscape
Japanese producers anchor the premium imaging tier; Chinese contract manufacturers hold volume production scale. The vendor base stratifies across three tiers: vertically integrated sensor-to-system platforms, modular assemblers sourcing CMOS from concentrated suppliers, and niche specialists in ruggedized or ultra-compact form factors. Strategic moves center on firmware subscription models and professional service tier construction to defend margin pools against hardware commoditization.
Among Japanese imaging specialists, Sony, Canon, and Fujifilm occupy positions across the premium-to-mid market spectrum. Sony exemplifies the full-frame mirrorless engineering archetype, while Canon represents service-network density strategies for professional retention, and Fujifilm occupies the color-science differentiation position. These three anchors demonstrate how computational imaging capabilities separate software-defined platforms from commodity enclosure assemblers.
| Leading Market Players |
|---|
| Sony |
| Panasonic |
| Fujifilm |
| Canon |
| Leica |
| CEDITA |
| Samsung |
| Nikon |
| Olympus |
| Others |
Pricing and Supply Chain Analysis
Creator economy consolidation through collective buying platforms and affiliate-direct arrangements is compressing distributor margins and forcing manufacturers toward direct-to-consumer pricing models that bypass traditional retail markups. This procurement shift concentrates volume discounts among Los Angeles and London creator co-working spaces while pressuring second-tier assemblers to absorb input cost volatility from concentrated CMOS sensor suppliers.
Pricing Analysis
Capacity additions in India under PLI schemes are reshaping price floors for mid-tier mirrorless bodies while premium full-frame segments defend margins through firmware subscription bundling. Three-tier pricing structure across premium, standard, and economy levels separates professional service-contract tiers from prosumer feature-unlock models and entry-level fixed-lens compacts. Cost compression in the standard tier intensifies because smartphone computational photography substitution erodes casual buyer willingness to pay. Vloggers and solo creators exhibit highest price sensitivity; wedding professionals demonstrate lowest sensitivity due to service-network dependency.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Dongguan feed hub-and-spoke patterns across Asia-Pacific, with secondary nodes in Noida and Chennai gaining share under India's PLI scheme. CMOS sensor fabrication concentrates in Japan and South Korea; hinge mechanisms and flex-cables source primarily from China. Single-source vulnerability in stacked sensor supply creates allocation risk during replacement cycle surges. Distribution runs through brand-direct channels, authorized professional dealers, and emerging creator economy platforms that aggregate procurement across independent producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on computational imaging differentiation that captures recurring firmware revenue and defends against hardware commoditization pressures from smartphone substitution.
For Market Incumbents: Deploy firmware subscription tiers as the primary lever to transform transactional hardware sales into recurring revenue streams. Deepen in-house production of computational imaging IP to reduce dependency on scarce real-time HDR fusion engineering talent. Consolidate professional service-network density in North American and Western European wedding markets where replacement demand concentrates. Counter smartphone substitution threat through AI-powered background replacement features that demand dedicated neural processing hardware. For New Entrants and Emerging Players: Creator co-working space procurement aggregators represent the most penetrable channel partner type for bypassing entrenched retail relationships. Target India's emerging live commerce infrastructure where BIS certification requirements create barrier advantages for early movers. White-space exists in ruggedized action camera segments optimized for vertical-native 9:16 workflows. Pursue direct-to-creator financing models integrated with Patreon-style subscription platforms to capture lifetime value from professional vloggers. For Investors and Strategic Acquirers: Asymmetric upside sits with modular assemblers possessing computational imaging firmware capabilities and established Shenzhen manufacturing relationships. Long-term viability over the projection horizon favors vertically integrated platforms over commodity enclosure manufacturers as software-defined features capture expanding margin pools. Acquisition targets should demonstrate on-device AI processing expertise and clean regulatory track records across FCC, MIIT, and EU frameworks. Signal to monitor: platform algorithm shifts toward vertical video formats that reshape sensor aspect-ratio priorities and hinge durability specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Launch | Transforms Canon and Sony hardware bases into recurring revenue streams with professional tier unlocks. |
| India PLI Manufacturing Footprint | Creates Noida and Chennai supply alternatives reducing China concentration risk for export markets. |
| AI Background Replacement Integration | Enables virtual production workflows without green-screen infrastructure for mid-market creator segments. |
| Creator Platform Direct Partnership | Bypasses traditional retail through Patreon-integrated financing capturing lifetime vlogger value. |
| CSRD Compliance Infrastructure | Documents Scope 3 emissions from CMOS wafer fabrication for EU professional-tier market access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with camera manufacturer product managers, firmware engineering leads, creator economy platform operators, and professional wedding photographer associations with secondary validation. SEC filings from Japanese imaging specialists, MIIT GB standard documentation, FCC equipment authorization databases, and EU REACH regulatory filings anchored the data foundation. Bottom-up shipment modeling by sensor format and feature tier triangulated against top-down market sizing across the analysis window.
Segment-weighting approaches applied differential growth assumptions to mirrorless versus DSLR chassis designs, 4K video capability tiers, and Wi-Fi connectivity bundles. The modeling framework incorporated replacement cycle compression from stacked CMOS adoption, platform algorithm shifts toward vertical video, and live commerce penetration rates. CAGRs derived from historical shipment trajectories adjusted for smartphone substitution elasticity and regulatory compliance timeline impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platform algorithm shifts, CMOS sensor allocation disruptions, and hinge mechanism durability standardization across MIIT, FCC, and EU frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Phosphor Screen Scanner Market
Imaging
Photoacoustic Imaging Market
Imaging
Global Digital Photo Frame Market
Imaging
Facial Recognition Machine Market
Imaging
Global in Ceiling Camera Market
Imaging
Global Trail Camera Market
Imaging
Camera Accessories Market
Imaging
Microwave Imaging Market
Imaging
Digitizer Market
Imaging
Video Capture Card Market
Imaging
Handheld Imager Market
Imaging
X-Ray Systems Market
Imaging
Global Cell Imagers Market
Imaging
Short-Wave Infrared Imaging Market
Imaging
3D Sensing and Imaging Market
Imaging
Global 3D Camera Market