
 Flat Panel Display (FPD) Market | 2026-2036
Flat Panel Display (FPD) Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Panel Display (FPD) Market Foresight
Metal oxide backplanes are broadening the performance envelope for high-resolution OLED panels by enabling faster electron mobility than conventional amorphous silicon. Samsung Electronics leverages vertical integration across semiconductor and display divisions to control quantum dot material supply. LG Display anchors large-format OLED production through dedicated Gen 8.5 fabs in South Korea. BOE Technology Group dominates Chinese domestic supply for advanced LCD and emerging OLED lines.
Flat Panel Displays are thin-screen visual output devices built on glass or flexible polymer substrates, employing active-matrix thin-film transistor addressing with pixel densities ranging from 100 to over 500 pixels per inch for applications from handheld devices to cinematic screens. Their primary commercial purpose is to render digital imagery across consumer, professional, and industrial interfaces with minimal depth and power draw. OLED technology leads premium segments due to self-emissive architecture eliminating backlight units and enabling perfect black levels, while LCD persists in cost-sensitive volume tiers where quantum dot enhancement films preserve competitiveness. Gaming Monitors represent the fastest-growing application segment as refresh rates above 144Hz and sub-5ms response times become standard specifications for competitive play.
The EU F-Gas Regulation restricts fluorinated greenhouse gases used in semiconductor and display manufacturing etching processes, compelling fab operators to adopt alternative chemistries or abatement systems. China's MIIT enforces GB standards for display energy consumption that shape product certification requirements for domestic sale and export eligibility. The US EPA oversees hazardous waste protocols for spent photoresist and etchant streams from TFT array fabrication. Stakeholders must monitor regulatory divergence between jurisdictions as carbon-border adjustments and substance restrictions increasingly determine facility location and technology roadmap decisions.

Market Dynamics
Energy-efficiency mandates under the EU Green Deal are accelerating OLED substitution for LCD in premium television manufacturing, while China's concentrated Gen 10.5 fab capacity locks in supply-side dominance for 65-inch and larger panels.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases in etching processes compel fab operators to adopt alternative chemistries, favoring OLED lines with cleaner process footprints over legacy LCD infrastructure.
- Metal oxide backplanes:Faster electron mobility than amorphous silicon enables high-resolution OLED panels at competitive yields, expanding addressable market into professional reference monitors and medical imaging displays.
- Gaming Monitors:Refresh rates above 144Hz and sub-5ms response times have become standard specifications for competitive play, pulling panel procurement toward premium-tier OLED and fast-LCD technologies.
Market Restraints
- Input cost volatility:Indium tin oxide and rare-earth phosphor prices fluctuate with mining supply from concentrated geographies, compressing margins for quantum dot-enhanced LCD manufacturers.
- Supply concentration risk:Gen 10.5 glass substrate production clusters in Chinese industrial corridors, creating single-point vulnerability for 65-inch and larger panel supply chains.
- Technical limitation:OLED blue emitter lifetime remains shorter than red and green subpixels, constraining brightness endurance in commercial signage applications requiring 24/7 operation.
Strategic Opportunities
- Automotive displays:Curved and transparent OLED integration into instrument clusters and head-up displays represents underpenetrated volume as electric vehicle interiors prioritize screen-centric cockpits.
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract module assembly investments, creating alternative supply nodes to Chinese panel finishing.
- MicroLED convergence:Transfer printing of LED chips onto TFT backplanes combines semiconductor precision with display-scale substrates, opening sub-100-inch direct-view applications where OLED burn-in risk disqualifies incumbent technologies.
Industry Challenges
- Process engineering talent scarcity:Vapor deposition and photolithography expertise for sub-10 micrometer patterning concentrates in South Korea and Taiwan, constraining fab ramp timelines in emerging manufacturing locations.
- GB standards compliance:China's MIIT energy consumption certification requirements demand redesigned driver ICs and power management circuits, extending product qualification cycles for export-bound manufacturers.
- Legacy equipment integration:Gen 6 and Gen 8.5 LCD tools require substantial retooling for OLED or quantum dot conversion, stranding capital for operators without balance-sheet capacity for parallel fab construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Panel Display (FPD) Market |
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $260.87 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, QLED, MicroLED, Electroluminescent, E-Ink Technology: TFT, IPS, VA, AMOLED, LTPS, Quantum Dot Application: Consumer Electronics, Aviation Displays, Gaming Monitors, Digital Signage, Control Panels, Wearable Devices End User: Television Manufacturers, Smartphone OEMs, Office Equipment Makers, Medical Device Producers, Automotive Suppliers, Security Systems |
| Companies Covered | Samsung Electronics, LG Display, Sony Corporation, AU Optronics, Panasonic Corporation, Sharp Corporation, Innolux Corporation, Universal Display Corporation, BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Panel Display (FPD) Market Shifts & Advancements
Active-matrix addressing architectures are evolving toward higher pixel densities and faster refresh protocols, reshaping competitive requirements across consumer, professional, and industrial display segments simultaneously.
MicroLED transfer printing is automating the placement of millions of discrete LED chips onto active-matrix backplanes with micron-scale precision. Display manufacturers in Taiwan and mainland China are piloting this technology for commercial signage and premium residential cinema screens. The process is automating yield optimization previously dependent on manual inspection, compressing production timelines for tiled direct-view displays exceeding 100 inches.
The EU F-Gas Regulation mandates phased reduction of sulfur hexafluoride and nitrogen trifluoride emissions from semiconductor and display etching operations. Fab operators must install abatement systems or switch to fluorine-based remote plasma sources, raising capital intensity for new capacity. OLED array fabrication faces tighter compliance timelines than LCD module assembly, advantaging producers with existing gas handling infrastructure in the Netherlands and Germany.
Enterprise procurement of commercial displays is consolidating around managed service contracts bundling hardware, installation, and predictive maintenance. Systems integrators are displacing traditional distributor networks in North American digital signage deployment. This model concentrates purchasing authority with national facility management firms, compressing vendor margins while locking in multi-year replacement cycles for indoor LED and LCD video walls.
Flat Panel Display (FPD) Market Segmentation

Display manufacturers configure product portfolios across four intersecting dimensions that determine technical specifications, margin profiles, and customer access. Technology selection locks in capital intensity and yield curves, while application focus shapes refresh rate, brightness, and durability requirements.
Product Type:
Self-emissive architectures eliminate backlight units entirely, shifting competitive advantage toward material deposition precision and emitter lifetime engineering.
- LCD:Liquid crystal cells modulate transmitted light from edge-lit or direct LED backlights. Television Manufacturers in China anchor procurement for 65-inch and larger panels from Gen 10.5 fabs, though EU energy-efficiency mandates compress margins against OLED substitution.
- OLED:Organic compounds emit light directly when current passes through stacked emissive layers. Smartphone OEMs concentrate demand for flexible and foldable panels where Samsung Display and BOE Technology Group compete on crease radius and hinge durability.
- QLED:Quantum dot enhancement films broaden color gamut on LCD backplanes without self-emissive architecture. Premium television lines use this intermediate technology where OLED burn-in risk concerns residential buyers.
- MicroLED:Discrete III-V compound LEDs transfer-printed onto active-matrix backplanes enable modular scaling beyond 100 inches. Commercial signage pilots in Taiwan and mainland China test automated die placement for yield viability.
- Electroluminescent:Thin-film phosphor layers emit light under alternating current excitation. Industrial control panels and military avionics specify this technology for extreme temperature tolerance and shock resistance.
- E-Ink:Microcapsules containing charged black and white particles rearrange under electric fields. Wearable Devices and e-reader manufacturers prioritize this bistable technology for multi-week battery endurance in ambient light.
Mature deployment sits with LCD. Newer deployment is concentrated in MicroLED pilot lines for direct-view commercial applications.
Technology:
Backplane electron mobility and subpixel addressing architecture determine resolution ceilings, power consumption, and manufacturing yield.
- TFT:Thin-film transistor arrays on glass substrates enable active-matrix addressing for LCD and emerging OLED lines. China's MIIT GB standards for energy consumption drive driver IC redesigns across domestic and export-bound production.
- IPS:In-plane switching rotates liquid crystal molecules horizontally to preserve color accuracy at wide viewing angles. Professional reference monitors and medical imaging displays specify IPS panels where color consistency across the screen surface is mandatory.
- VA:Vertical alignment tilts liquid crystal molecules perpendicular to the substrate for deep contrast ratios. Gaming Monitors combine VA panels with high-refresh backlights where response time and contrast compete with OLED alternatives.
- AMOLED:Active-matrix organic light-emitting diode integrates thin-film transistor switching with self-emissive organic stacks. Samsung Electronics controls quantum dot material supply through semiconductor division backward integration.
- LTPS:Low-temperature polysilicon crystallizes silicon on glass or flexible polymer for higher electron mobility than amorphous silicon. Smartphone OLED backplanes use LTPS for pixel densities exceeding 500 per inch.
- Quantum Dot:Cadmium-free or indium phosphide nanocrystals convert blue LED emission to narrow-band red and green. LG Display anchors large-format production through dedicated Gen 8.5 fabs in South Korea.
Volume concentration favors TFT for mainstream LCD. Steepest expansion trajectory belongs to LTPS as foldable smartphone form factors multiply addressable display area per device.
Application:
Environmental operating conditions and usage intensity separate consumer-grade specifications from industrial and transportation requirements.
- Consumer Electronics:Televisions, tablets, and laptops specify brightness, color gamut, and thin profiles for residential and mobile environments. BOE Technology Group dominates Chinese domestic supply for advanced LCD and emerging OLED lines in this segment.
- Aviation Displays:Cockpit primary flight displays and cabin entertainment systems require sunlight readability, electromagnetic interference shielding, and failure-resistant redundancy. Certification cycles extend product qualification timelines beyond consumer electronics norms.
- Gaming Monitors:Refresh rates above 144Hz and sub-5ms response times have become standard specifications for competitive play. Panel procurement pulls toward premium-tier OLED and fast-LCD technologies with adaptive sync protocols.
- Digital Signage:Commercial LED and LCD video walls operate 18-24 hours daily in retail, corporate, and transportation hubs. Managed service contracts bundle hardware, installation, and predictive maintenance, concentrating purchasing authority with national facility management firms.
- Control Panels:Industrial human-machine interfaces specify wide temperature ranges, glove-compatible touch layers, and ingress protection. Electroluminescent and high-brightness LCD technologies persist where OLED luminance decay under continuous operation is prohibitive.
- Wearable Devices:Smartwatches and augmented reality glasses prioritize round or irregular form factors, always-on visibility, and sub-millimeter thickness. Flexible OLED and reflective E-Ink technologies split this application by use case intensity.
Revenue scale peaks with Consumer Electronics. Margin expansion concentrates in Gaming Monitors where specification premiums justify panel cost absorption.
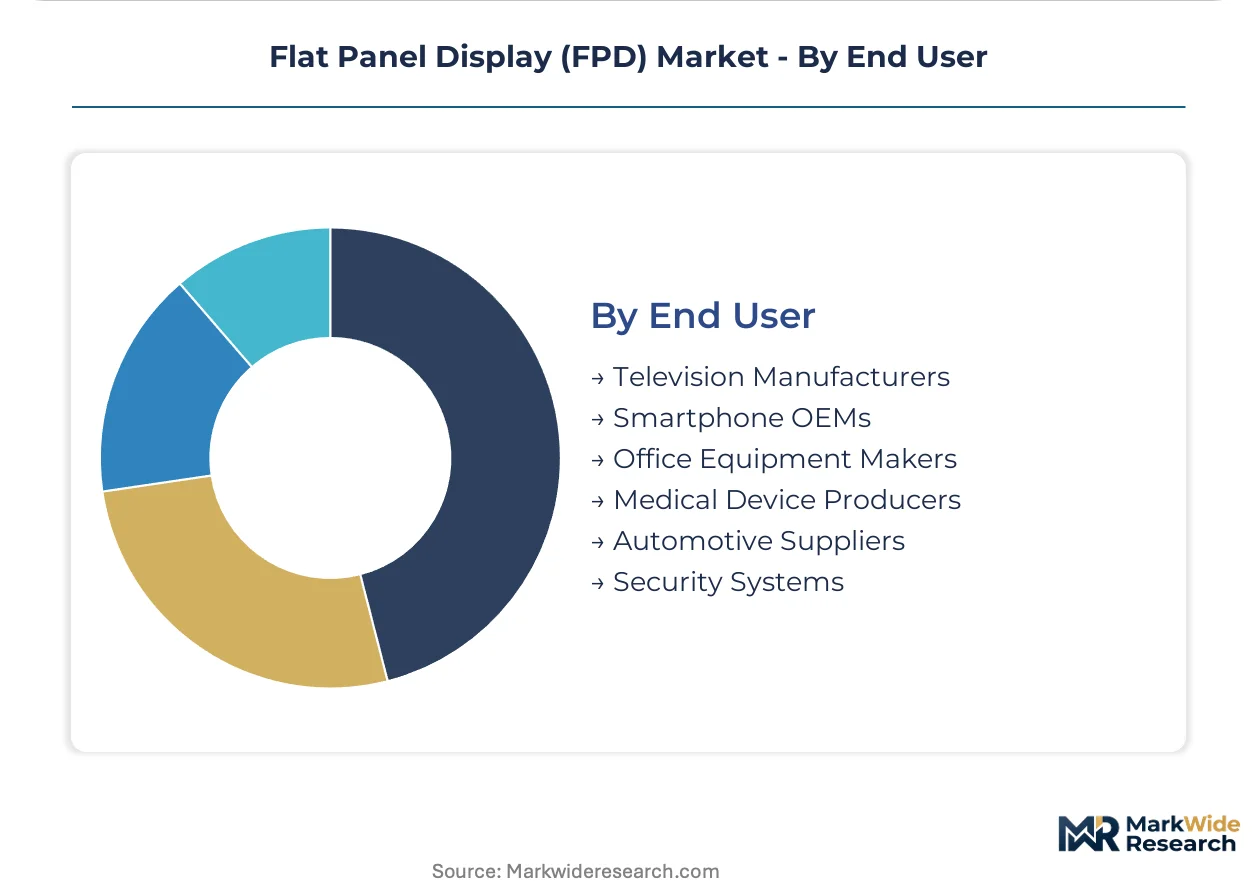
End User:
Procurement authority and volume concentration vary sharply between consolidated OEMs and fragmented industrial integrators.
- Television Manufacturers:Samsung Electronics and LG Display integrate semiconductor and display divisions to control quantum dot material supply and OLED emitter deposition. Annual panel procurement volumes exceed 50 million units for tier-one brands.
- Smartphone OEMs:Apple, Samsung, and Chinese brands specify custom driver ICs, cover glass treatments, and haptic integration. BOE Technology Group and Samsung Display compete for flexible OLED orders on crease radius and power efficiency.
- Office Equipment Makers:Multifunction printer and copier manufacturers source monochrome and color LCD panels for touch-based control interfaces. Procurement consolidates through display distributors rather than direct fab relationships.
- Medical Device Producers:Diagnostic imaging and surgical displays require DICOM calibration, antimicrobial surfaces, and long-term availability commitments. IPS and OLED technologies split this segment by grayscale precision versus contrast requirements.
- Automotive Suppliers:Tier-one cockpit integrators specify curved and transparent OLED for instrument clusters and head-up displays. Electric vehicle interiors prioritize screen-centric cockpits, expanding display area per vehicle.
- Security Systems:Surveillance monitor and access control terminal manufacturers prioritize 24/7 operation endurance and vandal-resistant enclosures. LCD persistence in this segment reflects cost sensitivity and burn-in avoidance.
Consolidated procurement sits with Television Manufacturers. Fragmented demand characterizes Security Systems where specification standardization remains limited.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates display procurement for 65-inch and larger panels, while South Korea and Taiwan anchor advanced OLED and semiconductor-grade manufacturing. The EU F-Gas Regulation and China's MIIT GB standards reshape facility investment patterns across three continents.
China
BOE Technology Group anchors massive Gen 10.5 fab capacity in Hefei and Wuhan for 65-inch and larger panels. MIIT enforces GB standards for display energy consumption that shape product certification for domestic sale and export eligibility. The Yangtze River Delta industrial corridor clusters glass substrate production and module assembly operations.
South Korea
LG Display concentrates large-format OLED production through dedicated Gen 8.5 fabs in Paju and Gumi. Samsung Electronics leverages backward integration across semiconductor and display divisions to control quantum dot material supply. The Gyeonggi-do province hosts vapor deposition and photolithography expertise for sub-10 micrometer patterning.
Taiwan
AU Optronics and Innolux Corporation supply advanced LCD and emerging OLED lines for global consumer electronics brands. The Hsinchu Science Park clusters TFT array fabrication and driver IC design capabilities. Taiwan's regulators enforce hazardous waste protocols for spent photoresist and etchant streams from TFT array fabrication.
United States
Enterprise procurement of commercial displays consolidates around managed service contracts bundling hardware, installation, and predictive maintenance. The EPA oversees hazardous waste protocols for spent photoresist from TFT array fabrication. Systems integrators in Texas and California displace traditional distributor networks in digital signage deployment.
Germany
The EU F-Gas Regulation mandates phased reduction of sulfur hexafluoride and nitrogen trifluoride emissions from display etching operations. Dresden and Munich host abatement system providers and gas handling infrastructure for OLED array fabrication. German industrial automation firms supply precision equipment for MicroLED transfer printing pilot lines.
Flat Panel Display (FPD) Market Competitive Landscape
Capacity expansion dominates the current landscape as producers race to convert Gen 8.5 and Gen 10.5 LCD infrastructure for OLED and quantum dot output. The vendor base clusters into three tiers: integrated conglomerates with captive semiconductor divisions, pure-play panel specialists with dedicated fab assets, and technology licensors with materials and deposition IP. Strategic archetypes include backward-integrated material suppliers, scale-driven Gen 10.5 operators, and niche flexible OLED developers. M&A activity and strategic technology licensing agreements constitute the dominant competitive moves.
Within the integrated conglomerate tier, Samsung Electronics and LG Display exemplify players combining semiconductor and display operations. BOE Technology Group anchors the scale-driven archetype with concentrated Gen 10.5 capacity. Universal Display Corporation occupies the technology licensor position with organic emitter IP. These three entities represent distinct strategic postures: captive material control, manufacturing scale concentration, and intellectual property monetization.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| Sony Corporation |
| AU Optronics |
| Panasonic Corporation |
| Sharp Corporation |
| Innolux Corporation |
| Universal Display Corporation |
| BOE Technology Group |
| Others |
Supply & Pricing Matrix
Indium tin oxide pricing volatility propagates from concentrated mining geographies through quantum dot-enhanced LCD tiers, compressing margins for manufacturers lacking backward integration into phosphor material supply while OLED lines command premium positioning through cleaner process footprints under tightening EU F-Gas Regulation compliance timelines.
Pricing Analysis
Volume procurement of 65-inch and larger panels from Gen 10.5 fabs anchors the economy tier, while OLED and MicroLED lines capture margin premiums through self-emissive architecture and modular scaling respectively. Price differentiation hinges on certification grade for EU energy-efficiency mandates and volume scale for television manufacturer procurement. Cost compression in quantum dot LCD is intensifying because indium and rare-earth phosphor input costs fluctuate with mining supply concentration. Television manufacturers exhibit highest price sensitivity in standard-tier procurement, whereas medical device producers accept premium positioning for DICOM-calibrated diagnostic imaging specifications.
Supply Chain Analysis
CE marking and GB standards certification gate access to EU and Chinese markets, forcing driver IC redesigns and power management circuit qualification cycles that extend product timelines. Glass substrate production clusters in China, South Korea, and Taiwan, with vapor deposition equipment and photolithography expertise concentrated in South Korean and Taiwanese industrial corridors. The supply chain draws from indium tin oxide, rare-earth phosphors, and III-V compound semiconductor wafers as critical inputs. Single-source vulnerability sits with Gen 10.5 glass substrate production in Chinese industrial corridors. Distribution runs through systems integrators displacing traditional distributor networks in North American digital signage deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance deadlines are forcing capital-intensive fab retooling that weaker balance sheets cannot absorb, accelerating consolidation toward integrated conglomerates with captive gas handling infrastructure and semiconductor division synergies.
For Market Incumbents: Deploy capacity conversion leverage by retooling Gen 8.5 and Gen 10.5 LCD infrastructure for OLED and quantum dot output before regulatory deadlines strand legacy equipment. Secure backward integration into quantum dot material supply to defend against phosphor price volatility, while expanding managed service contract bundling to lock in multi-year replacement cycles and compress competitor access to national facility management firms. For New Entrants and Emerging Players: Capture automotive display white space by targeting curved and transparent OLED integration into electric vehicle instrument clusters and head-up displays where screen-centric cockpit prioritization expands display area per vehicle. India's PLI scheme for electronics manufacturing offers module assembly entry points with production-linked incentives that offset Chinese supply concentration, using localized finishing to bypass tariff exposure and qualify for domestic content requirements. For Investors and Strategic Acquirers: MicroLED transfer printing yield breakthroughs in Taiwan and mainland China pilot lines are the leading indicator that direct-view commercial signage applications exceeding 100 inches will open sub-OLED price points. Long-term viability favors technology licensors with organic emitter and deposition IP over pure-play panel specialists facing stranded LCD capital. Watch for managed service contract consolidation with national facility management firms as the inflection signal for downstream purchasing authority concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Gen 8.5 Fab Conversion to OLED | LG Display's Paju and Gumi facilities demonstrate yield viability for large-format premium television supply. |
| Quantum Dot Material Backward Integration | Samsung Electronics' semiconductor division captive supply secures phosphor cost stability against mining volatility. |
| MicroLED Transfer Printing Automation | Taiwanese and mainland Chinese pilot lines automate die placement yield optimization for commercial signage scaling. |
| Managed Service Contract Bundling | Systems integrators in Texas and California displace distributor networks to concentrate purchasing authority. |
| India PLI Module Assembly Investment | Alternative supply nodes emerge to Chinese panel finishing through production-linked incentive qualification. |
Research Methodology
Document review covered SEC filings from display manufacturers, EU F-Gas Regulation implementation guidance, and China's MIIT GB standards documentation, complemented by interviews with fab operations directors, television manufacturer procurement leads, and automotive tier-one cockpit integrators. Secondary validation drew from customs trade data for glass substrate and driver IC shipments, as well as hazardous waste protocol filings with the US EPA. Bottom-up capacity modeling triangulated against top-down procurement volume estimates from consumer electronics OEMs.
Unit shipment and revenue projections across the analysis window reflect segmentation by technology type, application intensity, and regional regulatory cluster. The modeling framework incorporated OLED emitter lifetime constraints, LCD-to-OLED conversion yield curves, and gaming monitor refresh rate specification premiums as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical fab capacity expansion patterns against regulatory mandate timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to indium supply disruption, EU carbon-border adjustment implementation, and MicroLED transfer printing yield breakthrough viability. Forecasts reflect assumptions around regulatory compliance timelines, substitution elasticity between display technologies, and automotive display penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
OLED Panel Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Privacy Screens Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
E-Paper Display Market
Display Technologies
Computer Monitor Market
Display Technologies
Commercial Touch Display Market
Display Technologies
Global Wearable Display Market
Display Technologies
Screenless Display Market
Display Technologies
Video Projector Market
Display Technologies
Microdisplay Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Automotive LCD Display Market
Display Technologies
Global Haptic Touchscreen Market