
 Durometer Calibration Service Market | 2026-2036
Durometer Calibration Service Market Size, Share, and Industry Trends Forecast 2026-2036
Durometer Calibration Service Market Insights
Automotive quality assurance is hardening as the dominant demand vertical for durometer calibration services. Rex Gauge Company leverages its specialized heritage in Shore and IRHD durometer manufacturing to anchor laboratory calibration contracts with tier-one rubber suppliers. Alliance Calibration competes through geographic coverage, sustaining multi-site service agreements across manufacturing facilities requiring NIST-traceable hardness verification.
Durometer calibration service encompasses the verification, adjustment, and certification of hardness testing instruments against traceable reference standards using indentor geometry verification and force-application validation to ensure measurement accuracy in polymer and elastomer characterization. Laboratory calibration commands premium pricing due to controlled-environment precision and documented uncertainty budgets, while onsite calibration grows fastest among continuous-production manufacturers minimizing equipment downtime. Digital durometer segments attract disproportionate service revenue as electronic sensor drift necessitates more frequent recertification cycles than mechanical analog counterparts.
FDA cGMP requirements for medical device polymer validation, ISO 17025 laboratory accreditation mandates, and ASTM D2240 standard compliance collectively elevate calibration frequency obligations across regulated industries. NIST maintains the definitive force and length reference standards underpinning domestic traceability chains. Stakeholders must monitor evolving ASTM revision cycles and accreditation body interpretation changes that could abruptly expand scope requirements or invalidate existing calibration certificates.
Market Dynamics
ISO 17025 accreditation mandates and ASTM D2240 revision cycles are compressing calibration intervals across polymer testing operations, forcing service providers to expand laboratory capacity and accelerate certificate turnaround times.
Growth Catalysts
- Automotive OEM validation protocols:Tier-one rubber suppliers in Germany now require quarterly Shore hardness verification for every production line durometer, creating recurring revenue anchors for accredited laboratories.
- FDA cGMP polymer traceability:Medical device manufacturers must maintain NIST-traceable calibration records for all elastomer characterization instruments used in biocompatibility testing workflows.
- Digital sensor proliferation:Electronic durometers with piezoelectric load cells demand more frequent recertification than mechanical analog units due to voltage drift and temperature sensitivity.
Market Restraints
- Reference standard scarcity:NIST-traceable Shore hardness blocks require specialized metallurgy and indentor geometry verification that only three domestic suppliers currently manufacture.
- Laboratory capex intensity:Controlled-environment calibration chambers with thermal stability to 0.1°C demand substantial upfront investment, constraining new market entrants.
- ASTM revision friction:Pending D2240 amendments around durometer foot geometry could invalidate thousands of existing calibration certificates, creating compliance uncertainty.
Strategic Opportunities
- India automotive expansion:BIS certification requirements for imported polymer components are driving demand for local ISO 17025 accredited hardness calibration capacity near Chennai and Pune manufacturing clusters.
- Remote calibration telemetry:Cloud-connected durometers with embedded force sensors enable predictive recertification scheduling based on actual usage cycles rather than fixed intervals.
- EU MDR polymer validation:The Medical Device Regulation's enhanced biocompatibility documentation requirements expand calibration service scope for implant-grade silicone and thermoplastic elastomer suppliers.
Industry Challenges
- Metrology talent scarcity:Certified calibration technicians with documented measurement uncertainty calculation skills command premium wages and extended recruitment timelines.
- Multi-standard harmonization:Laboratories must simultaneously maintain ISO 17025, ISO 9001, and sector-specific accreditations, multiplying audit preparation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durometer Calibration Service Market |
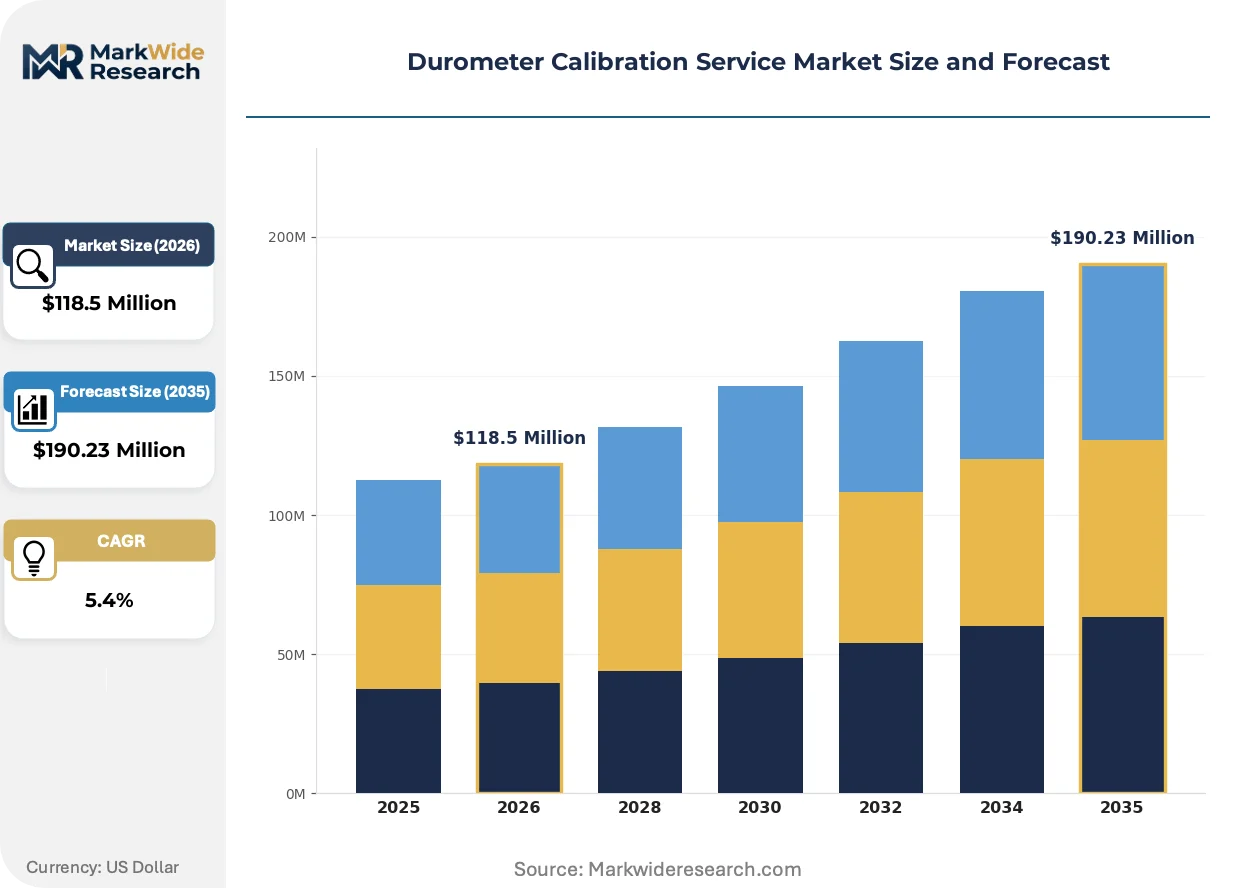
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $190.23 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Onsite Calibration, Laboratory Calibration, Portable Calibration, Emergency Calibration End User: Manufacturing Facilities, Research Laboratories, Quality Assurance Centers, Calibration Laboratories Equipment Type: Analog Durometers, Digital Durometers, Shore Durometers, IRHD Durometers, Barcol Durometers Application: Rubber Testing, Plastics Testing, Coating Hardness, Material Strength Analysis |
| Companies Covered | Alliance Calibration, Applied Technical Services, Cross Company, Rex Gauge Company, A.C.M Laboratory, Corporate Consulting Service & Instruments, CCSi, Coastal Calibration Laboratories, Redstone Calibration Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durometer Calibration Service Market Trends and Innovations
Calibration service delivery is fragmenting across centralized laboratory precision and distributed field deployment models, with digital connectivity bridging the operational gap between these competing architectures.
Portable reference force generators with integrated load cell verification are modularizing field calibration capabilities, allowing automotive tier suppliers to validate Shore A and Shore D instruments without production line shutdowns. Tier-two rubber compounders in Michigan and Ohio are adopting these systems fastest, compressing the traditional laboratory-to-facility service radius from hundreds of miles to on-premise execution.
REACH SVHC substance restrictions on certain polymer plasticizers are forcing recalibration of durometers previously used with now-noncompliant reference materials. European automotive suppliers must replace legacy hardness blocks and re-establish measurement uncertainty budgets, creating replacement demand for NIST-traceable alternatives. German calibration laboratories report the steepest volume increases from this regulatory cascade.
Automotive quality departments are unbundling calibration from original equipment purchase agreements, negotiating separate multi-year service contracts with independent metrology providers. This procurement fragmentation favors specialized calibration houses over manufacturer-captive service arms. The pattern is most pronounced among Japanese automotive transplants operating in Tennessee and Kentucky, where local ISO 17025 laboratories now capture hardness verification work previously routed to durometer OEM service networks.
Durometer Calibration Service Market Segmentation
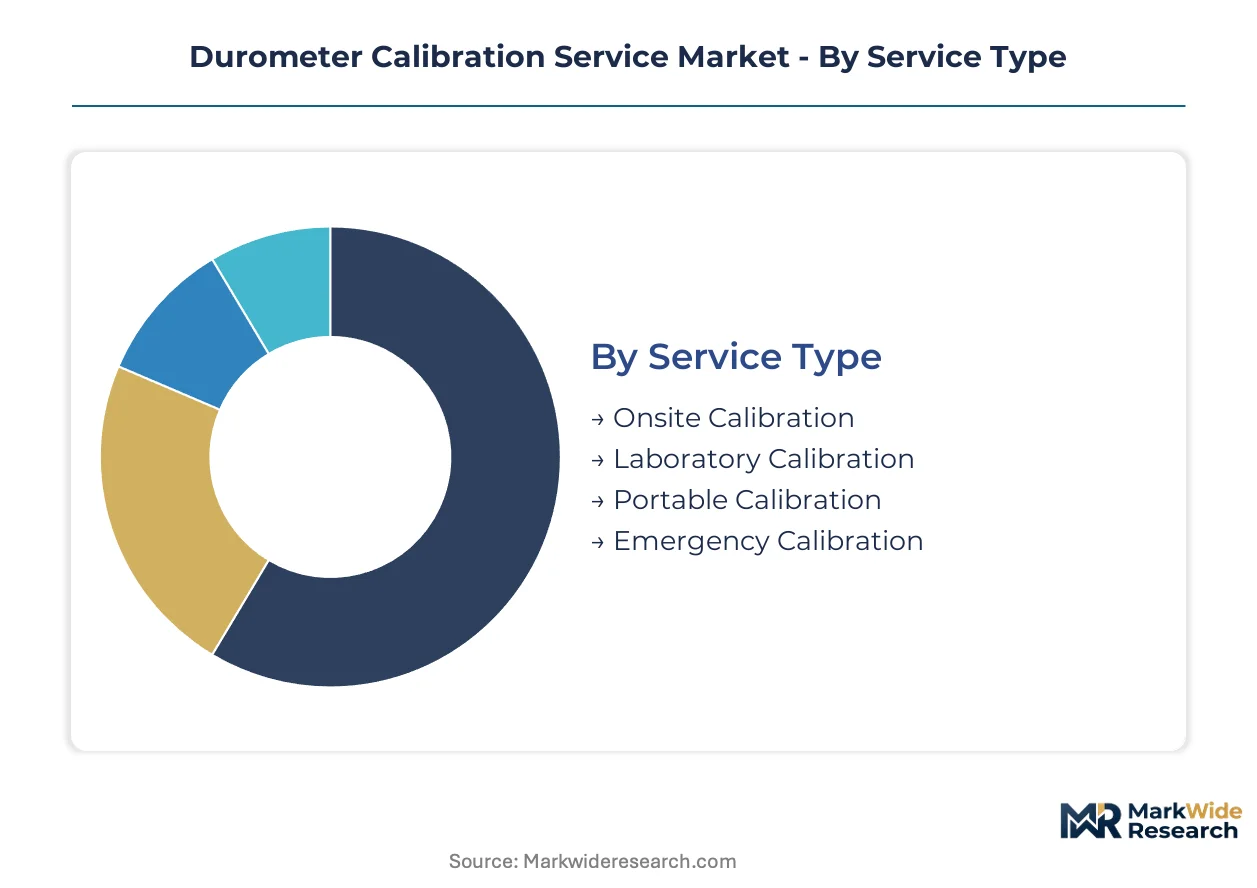
Calibration service procurement splits sharply between precision requirements and operational constraints. Buyers weigh traceability documentation against production downtime costs when selecting service modalities.
Service Type:
Cost tier determines buyer selection between premium laboratory precision and operational convenience.
- Laboratory Calibration:Controlled-environment verification with documented uncertainty budgets and ISO 17025 accreditation. German automotive OEMs and tier-one rubber suppliers in Stuttgart and Wolfsburg mandate this modality for regulatory submissions.
- Onsite Calibration:Field technicians execute Shore hardness verification without equipment removal. Continuous-production manufacturers in Tennessee and Kentucky automotive corridors favor this approach to eliminate line shutdowns.
- Portable Calibration:Modular reference force generators enable in-house validation. Tier-two compounders adopt these systems to compress service radius from hundreds of miles to plant-floor execution.
- Emergency Calibration:Expedited recertification for audit preparation or equipment failure recovery. Quality departments activate this tier when certificate expiration threatens production release.
Volume sits with Laboratory Calibration; growth tilts toward Onsite Calibration.
End User:
Application maturity separates established quality infrastructure from emerging compliance investments.
- Manufacturing Facilities:Production-line durometer fleets requiring scheduled recertification. Automotive stamping plants and rubber extrusion operations in Michigan and Ohio maintain the densest service contract density.
- Quality Assurance Centers:Centralized metrology hubs serving multiple production sites. These facilities aggregate calibration demand across distributed manufacturing footprints.
- Calibration Laboratories:Third-party accredited providers capturing outsourced verification work. Independent metrology houses in Germany and the US Midwest compete for multi-year service agreements.
- Research Laboratories:R&D-focused hardness characterization with lower volume but higher specification stringency. Polymer development centers require specialized indentor geometry verification.
Contract value concentrates in Manufacturing Facilities; expansion is climbing the fastest in Calibration Laboratories.
Equipment Type:
Technology generation drives recertification frequency and service pricing differentiation.
- Digital Durometers:Electronic sensors with piezoelectric load cells demand frequent recertification. Voltage drift and temperature sensitivity compress calibration intervals versus mechanical alternatives.
- Analog Durometers:Mechanical spring-based instruments with stable calibration retention. Legacy equipment in cost-sensitive operations maintains longer service cycles.
- Shore Durometers:ASTM D2240-compliant instruments for elastomer hardness measurement. Automotive suppliers validate Shore A and Shore D configurations quarterly.
- IRHD Durometers:International Rubber Hardness Degree instruments for thin-walled specimens. Tire manufacturers and technical rubber goods producers specify this modality.
- Barcol Durometers:Indentation instruments for reinforced plastics and composites. Aerospace and marine applications drive specialized calibration demand.
Service revenue pools with Digital Durometers; steepest expansion trajectory belongs to Shore Durometers.
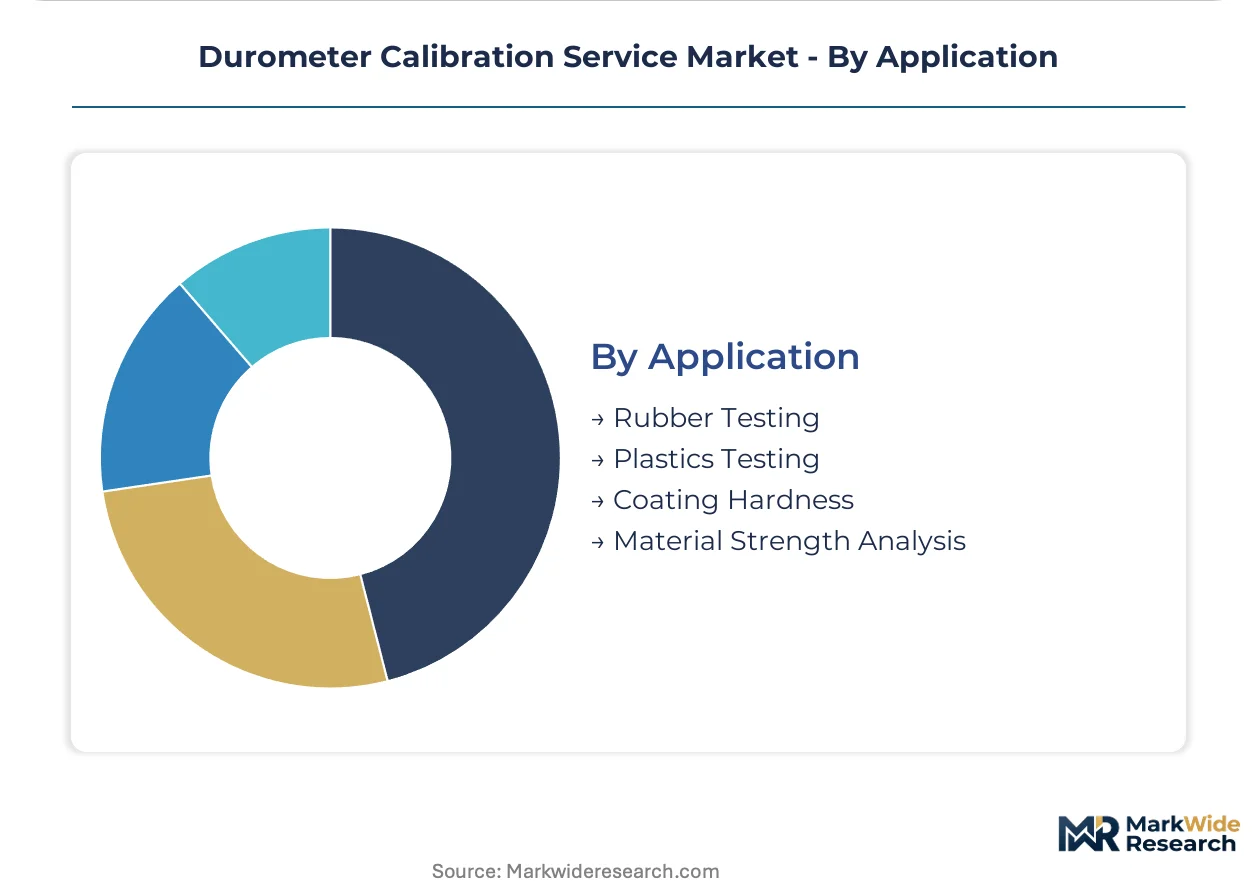
Application:
Regulatory exposure intensity segments calibration urgency across material testing workflows.
- Rubber Testing:Elastomer hardness verification for automotive seals, hoses, and vibration isolation components. FDA cGMP requirements and ISO 17025 mandates elevate calibration frequency.
- Plastics Testing:Thermoplastic and thermoset hardness characterization. REACH SVHC restrictions on certain plasticizers force recalibration with compliant reference materials.
- Coating Hardness:Surface hardness measurement for protective and decorative finishes. Industrial coating operations require traceable verification for customer specifications.
- Material Strength Analysis:Correlative hardness-to-tensile property validation. Structural polymer applications demand documented measurement uncertainty.
Revenue concentrates in Rubber Testing; EU MDR polymer validation requirements are expanding Plastics Testing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's automotive corridor concentrate ISO 17025 accredited calibration capacity. Tier-one rubber suppliers co-locate metrology operations near OEM assembly plants to compress Shore hardness verification turnaround.
Germany
Stuttgart and Wolfsburg automotive clusters drive quarterly Shore hardness verification mandates for production-line durometers. KBA vehicle type-approval requirements enforce traceable hardness documentation for elastomer seals and vibration components. Independent calibration laboratories in Baden-Württemberg capture multi-year service contracts from tier suppliers.
United States
FDA cGMP requirements for medical device polymer validation elevate NIST-traceable calibration frequency across elastomer characterization workflows. Tennessee and Kentucky automotive transplants unbundle calibration from OEM service networks, routing hardness verification to local ISO 17025 laboratories. Michigan and Ohio rubber compounders adopt portable reference force generators for in-house Shore A validation.
India
BIS certification requirements for imported polymer components are catalyzing local ISO 17025 accredited hardness calibration capacity. Chennai and Pune manufacturing clusters anchor demand for Shore and IRHD durometer verification services. CDSCO medical device regulations extend traceability mandates to implant-grade silicone hardness testing.
China
GB standards compliance for automotive rubber components tightens durometer calibration protocols across domestic supply chains. Yangtze River Delta polymer testing facilities invest in NIST-traceable reference blocks to serve export-oriented manufacturers. SAMR metrology supervision drives accreditation upgrades among regional calibration providers.
Japan
METI industrial standardization programs harmonize JIS hardness testing with ASTM D2240 for automotive export compatibility. Kansai region tire manufacturers maintain dense networks of IRHD durometer calibration contracts. PMDA medical device guidelines extend Shore hardness traceability requirements to biocompatibility assessment workflows.
Durometer Calibration Service Market Competitive Landscape
Top-tier vendors anchor laboratory accreditation density, while mid-tier specialists compete through geographic coverage and portable equipment deployment. The vendor base stratifies across ISO 17025 accredited laboratories, manufacturer-captive service arms, and independent field calibration operators. Three archetypes dominate: heritage durometer manufacturers leveraging original equipment relationships, multi-site metrology houses competing on turnaround velocity, and regional specialists capturing automotive cluster proximity. Consolidation pressures favor acquisition of accredited laboratories to expand geographic footprint, while technology licensing agreements accelerate portable calibration system deployment.
Within the heritage manufacturer tier, Rex Gauge Company occupies a position exemplifying original equipment anchoring for laboratory calibration contracts. Alliance Calibration and Applied Technical Services represent the multi-site coverage archetype, competing through sustained service agreements across distributed manufacturing footprints. Cross Company sits within the regional specialist category, capturing proximity-driven demand from automotive corridor concentrations.
| Leading Market Players |
|---|
| Alliance Calibration |
| Applied Technical Services |
| Cross Company |
| Rex Gauge Company |
| A.C.M Laboratory |
| Corporate Consulting Service & Instruments |
| CCSi |
| Coastal Calibration Laboratories |
| Redstone Calibration Services |
| Others |
Pricing and Supply Chain Analysis
Family-owned metrology specialists in Germany and the US Midwest anchor laboratory calibration capacity, their conservative capital deployment sustaining premium pricing discipline while limiting spot-market discounting. ISO 17025 accreditation investments create sticky customer relationships that resist price erosion despite competitive field-service expansion.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with expedited certificate turnaround commanding substantial markups over standard laboratory queues. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited laboratory verification from onsite field service and portable in-house systems. Price differentiation hinges on certification grade and geographic delivery cost, with NIST-traceable documentation attracting sustained premiums. Cost compression in economy-tier field calibration is intensifying because portable reference force generators displace traditional service radius models. Tier-one automotive suppliers exhibit lowest price sensitivity due to audit compliance imperatives, while tier-two compounders negotiate aggressively on volume contracts.
Supply Chain Analysis
ISO 17025 accreditation gating restricts viable laboratory supply to Germany, the United States, and Japan, where national metrology institutes maintain definitive force and length reference standards. NIST-traceable Shore hardness blocks, piezoelectric load cells, and controlled-environment calibration chambers constitute critical input dependencies. Single-source vulnerability concentrates in reference standard manufacturing, where only three domestic suppliers produce compliant hardness blocks. Distribution runs through direct multi-year service agreements rather than spot procurement, with automotive OEMs and tier suppliers locking in accredited laboratory capacity through exclusive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital sensor telemetry is displacing mechanical analog calibration cycles, compressing recertification intervals and forcing infrastructure reinvestment across service provider tiers.
For Market Incumbents: Extend ISO 17025 accreditation scope into remote calibration telemetry before digital-native competitors capture predictive maintenance contracts. Deepen backward integration into reference standard manufacturing to offset NIST-traceable block scarcity. Shore durometer OEM service networks represent the primary substitution threat as automotive buyers unbundle calibration from equipment purchase agreements. For New Entrants and Emerging Players: Capture portable calibration system deployment among tier-two rubber compounders in Michigan and Ohio, the most penetrable segment given compressed service radius requirements. Target BIS certification-driven demand near Chennai and Pune manufacturing clusters in India, where local accredited capacity lags automotive expansion. A hardware-as-a-service model with embedded recertification scheduling software offers defensible go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional ISO 17025 laboratories in Tennessee and Kentucky automotive corridors, where Japanese transplant procurement fragmentation creates acquisition targets with sticky customer relationships. Long-term viability over the coming decade rests on telemetry integration capabilities and multi-standard accreditation breadth. Watch for ASTM D2240 revision finalization as inflection indicator triggering certificate invalidation waves and replacement demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Calibration Telemetry Deployment | Cloud-connected durometers enable predictive recertification scheduling based on actual usage cycles rather than fixed intervals. |
| ISO 17025 Accreditation Expansion | Multi-standard harmonization across ISO 9001 and sector-specific mandates reduces audit preparation overhead for laboratory networks. |
| Portable Reference Force Generator Manufacturing | Modular field calibration systems compress service radius from hundreds of miles to plant-floor execution for tier-two compounders. |
| India Local Capacity Buildout | BIS certification requirements for imported polymer components drive demand for accredited hardness calibration near Chennai and Pune. |
| EU MDR Polymer Validation Services | Enhanced biocompatibility documentation requirements expand calibration scope for implant-grade silicone and thermoplastic elastomer suppliers. |
Research Methodology
Independent corroboration across calibration laboratory operators, automotive quality assurance directors, and metrology equipment manufacturers underwrites the qualitative findings in this study. Primary interviews with ISO 17025 accreditation body representatives, tier-one rubber supplier procurement managers, and NIST-traceable reference standard producers combined with secondary validation from ASTM standards documentation, FDA cGMP guidance filings, and national metrology institute technical reports. Bottom-up service provider capacity assessments and top-down end-user demand aggregation complete the analytical foundation.
Rate-of-change decomposition across service type, equipment technology generation, and end-user regulatory exposure intensity structures the forecast framework. Segmentation dimensions modeled include laboratory versus field delivery modality, digital versus analog instrument architecture, and automotive OEM versus medical device quality system requirements. CAGRs were derived from calibrated adoption curves for telemetry-enabled predictive calibration and regulatory mandate expansion timelines. Industry-specific inputs incorporate ASTM D2240 revision probability weights and EU MDR implementation pace assumptions.
The model holds under stable accreditation interpretation and standards revision timing; deviation in regulatory mandate acceleration or reference standard supply disruption would shift trajectory. Forecasts reflect documented assumptions regarding digital sensor proliferation rates and automotive procurement unbundling momentum. A model refresh is warranted upon material change in ASTM D2240 amendment finalization or NIST-traceable reference block manufacturing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
PXI Source Measure Unit Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Flow Meter Calibration Market