
 Biomedical Pressure Sensors Market | 2026-2036
Biomedical Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Biomedical Pressure Sensors Market Outlook
Project finance and equipment leasing for high-acuity monitoring suites is narrowing the competitive field to firms with balance-sheet depth or captive financing arms. Medtronic plc leverages its integrated capital-equipment leasing programs to anchor hospital procurement decisions across North American cath labs. TE Connectivity Ltd. sustains R&D intensity through dedicated healthcare verticals that specialize in miniaturized silicon-based transducers for catheter applications. Bosch Sensortec competes on manufacturing scale, using automotive-derived MEMS fabrication lines to control unit economics for disposable pressure sensors.
Biomedical pressure sensors are electromechanical or optical transducers that convert physiological fluid pressure into quantifiable electrical or photonic signals, typically operating within ranges of −50 mmHg to 300 mmHg with accuracy tolerances below ±1% full scale for hemodynamic monitoring. Their primary purpose is to enable real-time circulatory and respiratory assessment during critical care, surgery, and ambulatory disease management. Invasive sensors and catheter sensors command the deepest margin pools due to sterilization barriers and regulatory validation burdens that limit supplier substitution. Optical sensors represent the fastest-expanding technology segment, as fiber-optic platforms eliminate electromagnetic interference risks in MRI-guided interventions and radiofrequency ablation procedures.
The FDA enforces 510(k) and premarket approval pathways that shape sensor validation protocols, while the EU Medical Device Regulation requires notified-body conformity assessment for Class IIa and higher devices, directly conditioning market access timelines. ISO 13485 quality management certification operates as a baseline procurement filter across hospital systems and original equipment manufacturers, effectively segmenting contract-eligible suppliers. Stakeholders must monitor how FDA guidance on software-as-a-medical-device and the EU AI Act's risk classification for diagnostic algorithms will reshape sensor-integrated monitoring platforms.
Market Dynamics
Catheter-based hemodynamic monitoring is displacing external cuff systems in high-acuity settings, as hospitals prioritize continuous arterial pressure waveforms over intermittent readings for sepsis and shock management.
Growth Catalysts
- EU Medical Device Regulation:Stricter conformity assessment for Class IIa and higher devices is filtering out non-validated suppliers and consolidating procurement toward ISO 13485-certified platforms.
- Aging demographics in Japan and Germany:Expanding elderly populations with cardiovascular comorbidities are sustaining inpatient admission volumes for interventional cardiology and critical care.
- Fiber-optic pressure transduction:Elimination of electromagnetic interference in MRI suites and radiofrequency ablation labs is accelerating platform conversions from piezoresistive alternatives.
Market Restraints
- Platinum-iridium alloy costs:Electrode material price volatility in MEMS fabrication constrains margin flexibility for disposable sensor manufacturers.
- Single-source sterilization capacity:Gamma and ethylene oxide sterilization services concentrate in the United States and Germany, creating geographic supply vulnerability for catheter-delivered sensors.
- Biocompatibility validation timelines:ISO 10993 cytotoxicity and sensitization testing extends product development cycles by 18-24 months for new materials.
Strategic Opportunities
- Home-based hypertension management:Underpenetrated ambulatory monitoring in the United States presents white space for wearable optical pressure sensors with cellular telemetry.
- AI-integrated diagnostic platforms:Convergence of fiber-optic sensing with machine learning algorithms for predictive hemodynamic deterioration creates new value pools in surgical suites.
- Japan's reimbursement expansion:Ministry of Health, Labour and Welfare coverage for minimally invasive cardiac output monitoring is opening procurement budgets for advanced catheter systems.
Industry Challenges
- MEMS process engineering talent:Scarcity of specialists combining biomedical device experience with semiconductor fabrication expertise extends hiring timelines for R&D teams.
- Legacy hospital IT integration:Proprietary data protocols in existing patient monitoring networks complicate sensor-platform interoperability and slow adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomedical Pressure Sensors Market |
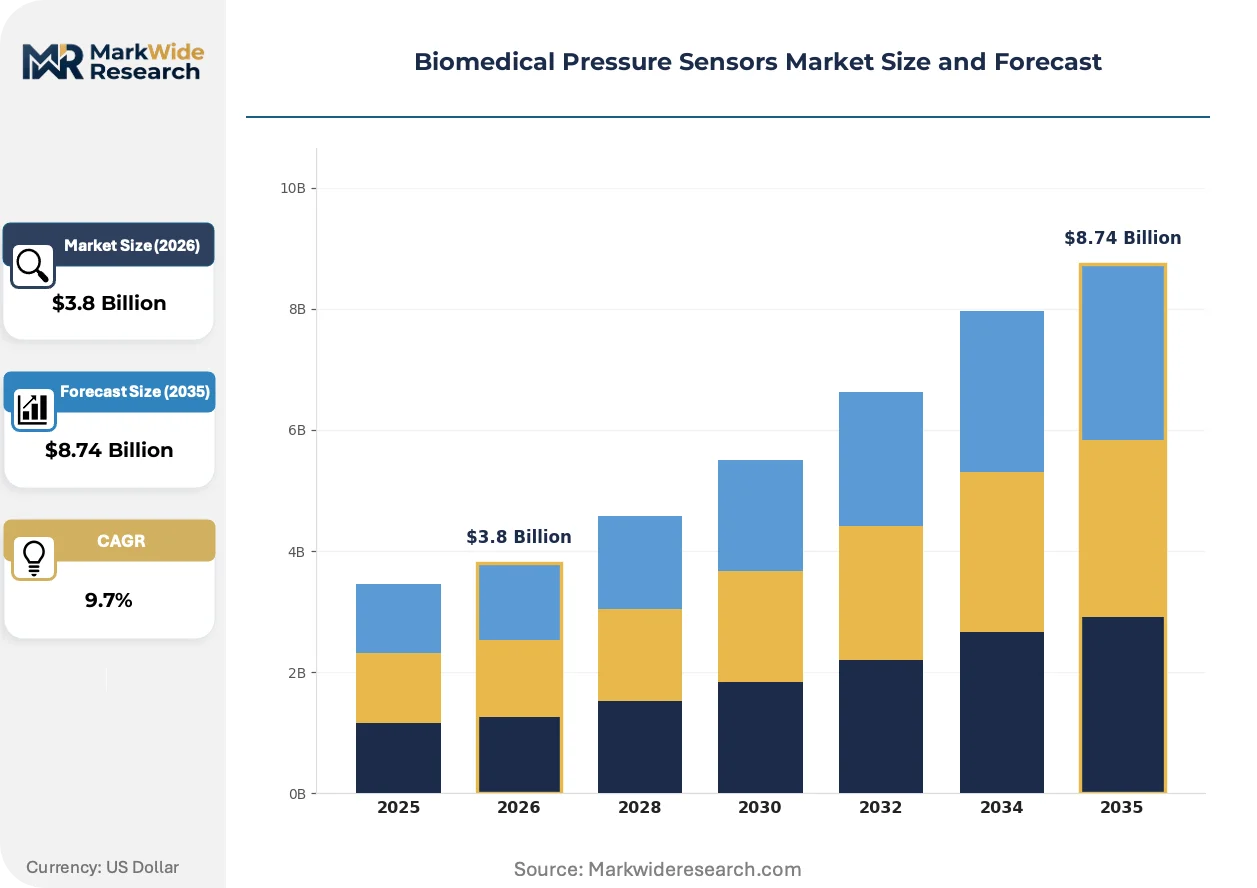
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Sensors, Non-Invasive Sensors, Wearable Sensors, Catheter Sensors Application: Cardiac Monitoring, Respiratory Monitoring, Blood Pressure Measurement, Surgical Procedures Technology: Silicon-Based Sensors, Strain Gauge Sensors, Capacitive Sensors, Optical Sensors End User: Hospitals, Home Healthcare, Research Laboratories, Rehabilitation Centers |
| Companies Covered | Honeywell International Inc., Medtronic plc, TE Connectivity Ltd., Sensirion Holding AG, Edwards Lifesciences Corporation, Smiths Group plc, Bosch Sensortec, First Sensor AG, Opsens Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomedical Pressure Sensors Market Strategic Shifts
Sensor architectures are converging with wireless telemetry and embedded analytics, compressing the traditional separation between data acquisition and clinical decision support. This integration is redrawing competitive boundaries between component suppliers and systems integrators.
Silicon-on-insulator MEMS pressure transducers are hybridizing with printed circuit board antennae to enable batteryless, inductively powered catheter tips. Interventional cardiology suites in the United States and Germany are piloting these platforms for real-time fractional flow reserve measurement. The technology is hybridizing the historically distinct roles of sensor OEMs and telemetry subsystem vendors, forcing partnership reconfigurations.
The FDA's evolving guidance on software-as-a-medical-device is reclassifying sensor-integrated algorithms as regulated diagnostic outputs. Manufacturers must now submit premarket notifications for firmware updates that previously required only internal validation. Hemodynamic monitoring platforms with embedded stroke volume variation calculators face the steepest compliance burden, with several US-based suppliers restructuring quality management systems to accommodate post-market surveillance requirements.
Hospital procurement committees are consolidating vendor relationships around full-suite hemodynamic monitoring contracts rather than discrete sensor purchases. This behavior concentrates purchasing power among integrated device manufacturers and disadvantages standalone sensor suppliers. The shift is most pronounced in German and Japanese hospital systems, where central purchasing organizations now mandate single-source accountability for catheter, transducer, and monitor interoperability.
Biomedical Pressure Sensors Market Segmentation
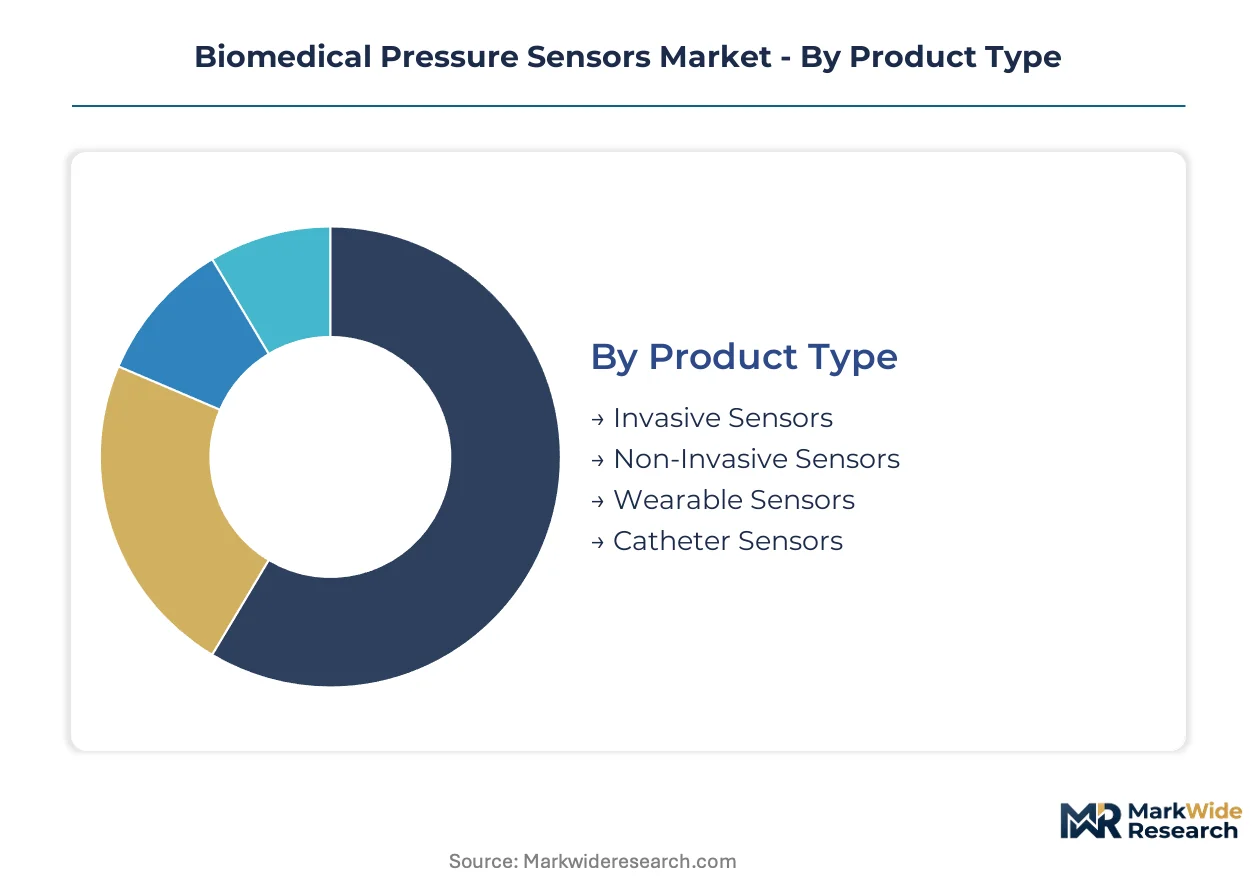
Segmentation in biomedical pressure sensors reveals distinct procurement rhythms and margin architectures across product types, applications, and technology platforms. Hospital procurement committees evaluate segments through divergent lenses: acute care prioritizes accuracy and sterilization assurance, while ambulatory markets emphasize cost-per-test and patient compliance.
Product Type:
Cycle times vary dramatically across this category, with disposable catheter sensors turning over in single-use intervals while invasive implantables persist for years. Wearable sensors occupy a middle ground with quarterly replacement schedules driven by battery and adhesive degradation.
- Invasive Sensors:Piezoresistive or capacitive elements hermetically sealed within biocompatible titanium housings, typically deployed in intracranial pressure monitoring and arterial line insertion. Demand concentrates in United States academic medical centers managing traumatic brain injury protocols, constrained by FDA 510(k) validation timelines that extend procurement cycles.
- Catheter Sensors:Miniaturized MEMS dies mounted on flexible polymer substrates at distal catheter tips, enabling real-time fractional flow reserve measurement during percutaneous coronary intervention. German and Japanese cath labs are expanding adoption as reimbursement frameworks recognize hemodynamic guidance value.
- Non-Invasive Sensors:External cuff-based oscillometric systems with silicon pressure transducers, dominating routine hypertension screening in primary care settings across all major markets.
- Wearable Sensors:Photoplethysmography-enhanced wristbands and patch formats, gaining traction in United States employer wellness programs and remote patient monitoring contracts.
Invasive sensors dominate installed base in neurocritical care and cardiac surgery suites. Catheter sensors are where expansion concentrates as interventional cardiology volumes recover.
Application:
Cost tier stratification shapes this category, with cardiac and surgical applications commanding premium pricing against commoditized blood pressure measurement.
- Cardiac Monitoring:Continuous hemodynamic assessment during catheterization, bypass surgery, and heart failure management, requiring ±1% accuracy across −50 to 300 mmHg ranges. United States hospital systems are consolidating procurement around integrated platforms that combine pressure sensing with electrophysiology mapping.
- Surgical Procedures:Real-time pressure feedback during neurosurgery, orthopedic implant insertion, and laparoscopic insufflation, where drift stability and sterilization compatibility determine vendor selection. German surgical device OEMs are qualifying second-source sensor suppliers to reduce single-source dependency.
- Blood Pressure Measurement:Intermittent diagnostic screening in outpatient settings, with automated cuff systems replacing manual sphygmomanometers in Japan's clinic networks.
- Respiratory Monitoring:Airway pressure transduction in mechanical ventilation and sleep apnea devices, experiencing volume growth in home healthcare channels.
Blood pressure measurement dominates installed base across outpatient networks. Cardiac monitoring is where expansion concentrates as value-based care contracts reward hemodynamic optimization.
Technology:
Supply concentration differentiates this category, with silicon MEMS fabrication consolidating among semiconductor foundries while optical sensor assembly remains more distributed.
- Optical Sensors:Fiber-optic Fabry-Pérot interferometers and Bragg grating configurations that eliminate electromagnetic interference, enabling MRI-compatible pressure monitoring during radiofrequency ablation. United States interventional suites are piloting these platforms for real-time tumor ablation guidance.
- Silicon-Based Sensors:Bulk-micromachined piezoresistive elements fabricated on SOI wafers, offering batch-processed cost structures for high-volume disposable applications. Japanese MEMS foundries are expanding healthcare-dedicated capacity to serve catheter OEM demand.
- Capacitive Sensors:Parallel-plate or comb-drive architectures with superior temperature stability, selected for implantable applications where long-term drift specifications are paramount.
- Strain Gauge Sensors:Metal-foil or semiconductor strain elements bonded to flexible diaphragms, retaining share in legacy industrial-medical crossover equipment.
Strain gauge sensors dominate installed base in legacy industrial equipment conversions. Optical sensors are climbing the fastest as MRI-guided intervention volumes expand.
End User:
Customer type determines procurement authority structures, with hospital central purchasing organizations wielding consolidated negotiating power against fragmented home healthcare decision-making.
- Hospitals:Integrated delivery networks with capital equipment leasing capabilities and multi-year sensor supply agreements, particularly concentrated in United States IDN consolidation and German hospital federation procurement. ISO 13485 certification operates as a non-negotiable entry filter.
- Home Healthcare:Dispensing pharmacies, durable medical equipment suppliers, and direct-to-consumer channels managing reimbursement complexity for ambulatory pressure monitors. United States Medicare competitive bidding programs are compressing margins for standard cuff systems.
- Research Laboratories:Academic and contract research organizations requiring calibrated reference sensors with traceable NIST documentation for protocol validation.
- Rehabilitation Centers:Post-acute facilities monitoring orthostatic hypotension and cardiovascular reconditioning, typically sourcing through group purchasing organizations aligned with hospital parent systems.
Hospitals dominate installed base across acute care monitoring infrastructure. Home healthcare is where expansion concentrates as remote patient monitoring reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and regulatory harmonization are redrawing procurement geography across biomedical pressure sensors. The FDA's 510(k) pathway, the EU Medical Device Regulation's Class IIa conformity assessments, and Japan's Ministry of Health, Labour and Welfare coverage expansions are conditioning where validated sensor platforms achieve commercial traction.
United States
Academic medical centers in Boston and the Research Triangle are expanding traumatic brain injury protocols that require intracranial pressure monitoring with ±1% accuracy specifications. The FDA enforces premarket notification requirements that extend validation timelines for new sensor materials. Interventional cardiology suites in Cleveland and Houston are piloting fiber-optic platforms for MRI-guided ablation procedures.
Germany
Hospital federation procurement organizations in North Rhine-Westphalia and Bavaria are consolidating vendor relationships around full-suite hemodynamic monitoring contracts. The EU Medical Device Regulation's notified-body conformity assessments for Class IIa devices are filtering supplier eligibility. Surgical device OEMs in Baden-Württemberg are qualifying second-source sensor suppliers to reduce single-source dependency in orthopedic implant insertion applications.
Japan
The Ministry of Health, Labour and Welfare's reimbursement expansion for minimally invasive cardiac output monitoring is opening procurement budgets for advanced catheter systems. Aging demographics in Kanto and Kansai regions are sustaining inpatient admission volumes for interventional cardiology. MEMS foundries in Nagoya are expanding healthcare-dedicated fabrication capacity to serve domestic catheter OEM demand.
China
Provincial hospital procurement reforms in the Yangtze River Delta are prioritizing traceable, ISO 13485-certified sensor platforms for critical care expansion. The National Medical Products Administration is aligning premarket review timelines with international standards to accelerate validated product entry. Shanghai-based interventional cardiology centers are adopting silicon-based disposable pressure sensors for percutaneous coronary intervention volume growth.
Switzerland
Swissmedic's conformity assessment procedures for Class IIa active implantable devices are conditioning market access for long-term implantable pressure sensors. Precision manufacturing clusters in the Lake Geneva region and Zurich are specializing in capacitive sensor architectures for implantable applications where drift stability specifications are paramount. Research partnerships between academic medical centers and sensor developers in Basel are advancing optical transduction platforms.
Biomedical Pressure Sensors Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers. Hospital central purchasing organizations and integrated delivery networks are consolidating vendor relationships around multi-year supply agreements that favor firms with captive financing capabilities. The vendor base segments into three strategic archetypes: diversified industrial conglomerates with healthcare verticals, pure-play MEMS fabricators with medical certifications, and interventional device integrators with in-house sensor development. Dominant competitive moves include backward integration into semiconductor fabrication and strategic partnerships with sterilization service providers to secure gamma and ethylene oxide capacity.
Among diversified industrial conglomerates, Honeywell International Inc. and Bosch Sensortec occupy positions that exemplify scale-driven manufacturing archetypes. TE Connectivity Ltd. represents the specialist tier of connectivity and sensor component suppliers with dedicated healthcare verticals. Medtronic plc anchors the integrated device manufacturer archetype, leveraging capital-equipment leasing programs to secure hospital procurement decisions. Sensirion Holding AG and First Sensor AG sit within the pure-play sensor fabricator segment, where ISO 13485 certification operates as a non-negotiable entry filter for contract eligibility.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Medtronic plc |
| TE Connectivity Ltd. |
| Sensirion Holding AG |
| Edwards Lifesciences Corporation |
| Smiths Group plc |
| Bosch Sensortec |
| First Sensor AG |
| Opsens Inc. |
| Others |
Value Chain & Pricing Dynamics
Platinum-iridium alloy refining capacity in South Africa and Russia concentrates electrode feedstock for MEMS pressure transducers, anchoring margin pools in sterilization-validated catheter sensor tiers where material traceability commands premium positioning.
Pricing Analysis
Certification level creates the primary spread across the biomedical pressure sensor landscape. Three-tier pricing structure across ISO 13485-premium, CE-marked standard, and economy non-certified levels segments procurement eligibility. Pricing pressure stems from United States Medicare competitive bidding compressing ambulatory cuff system margins. Hospital central purchasing organizations exhibit lowest price sensitivity for invasive implantables, while home healthcare distributors face acute margin compression on standard blood pressure monitors.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan, Japan, and Germany for MEMS fabrication dedicated to medical-grade pressure transducers. Platinum-iridium electrodes, biocompatible titanium housings, and specialized polymer substrates constitute critical input dependencies. Single-source sterilization capacity in the United States and Germany presents geographic supply vulnerability for gamma and ethylene oxide treatment of catheter-delivered sensors. Distribution runs through hospital group purchasing organizations and integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated monitoring platforms are shifting toward recurring-revenue service models, with calibration maintenance contracts and telemetry subscription layers expanding faster than discrete hardware unit sales.
For Market Incumbents: Build regulatory validation moats by accelerating FDA 510(k) pathway expertise and EU MDR notified-body relationship depth. Consolidate sterilization partnerships to secure gamma and ethylene oxide capacity against single-source geographic risk. Defensive positioning requires backward integration into MEMS foundry relationships or captive fabrication capacity. For New Entrants and Emerging Players: Establish a beachhead in United States home-based hypertension management, the most penetrable ambulatory segment where reimbursement frameworks remain underdeveloped. Target wearable optical pressure sensors with cellular telemetry for remote patient monitoring contracts. Go-to-market execution should prioritize direct relationships with durable medical equipment suppliers over hospital procurement committees. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play sensor fabricators with ISO 13485 certification and established catheter OEM supply relationships. Long-term viability over the mid-term projection horizon favors firms combining MEMS process engineering depth with healthcare vertical specialization. Watch FDA guidance evolution on software-as-a-medical-device as the inflection signal for algorithm-integrated platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification expertise compresses time-to-revenue for new sensor materials in United States cath labs. |
| EU MDR Notified-Body Partnership | Conformity assessment alignment secures Class IIa device access across German hospital federation procurement. |
| Hospital System Partnership | Multi-year supply agreements with integrated delivery networks anchor catheter sensor volume commitments. |
| Software Companion Development | Embedded stroke volume variation calculators face SaMD reclassification, requiring quality system restructuring. |
| Reimbursement Strategy | Japan MHLW coverage expansion for minimally invasive cardiac output monitoring opens catheter system budgets. |
Study Parameters
Operator-level perspectives from catheter OEM procurement managers, hospital biomedical engineers, GPO contracts specialists, and MEMS foundry operations directors anchored the qualitative base. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EU MDR notified-body registration databases, hospital procurement contract records, and CMS Medicare competitive bidding data. Bottom-up sensor unit demand modeling and top-down healthcare capital equipment spending analysis provided triangulation.
Scenario-bracketing around sterilization capacity constraints, platinum-iridium price volatility, and regulatory pathway timeline variations bounded forecast uncertainty across the projection horizon. Segmentation modeling spanned product architecture, application acuity tier, transduction technology, and end-user procurement authority. CAGRs derived from installed base turnover analysis and interventional procedure volume elasticity to sensor pricing.
Stress conditions across MEMS foundry utilization rates, notified-body audit backlogs, and reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against hospital capital expenditure surveys and catheter laboratory equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Biometric Sensors Market