
 QLED Display Market | 2026-2036
QLED Display Market Size, Share, and Industry Trends Forecast 2026-2036
QLED Display Market Analysis
The gap between premium QLED panels with full-array local dimming and entry-level edge-lit units is restructuring how brands allocate fab capacity and marketing spend. Samsung Electronics leverages its captive quantum dot supply chain to sustain pricing power in the ultra-premium tier. TCL competes aggressively on volume, while Sony differentiates through proprietary image processing algorithms co-developed with its semiconductor division.
QLED display denotes a liquid-crystal panel architecture that employs a blue LED backlight with a quantum dot enhancement film converting wavelengths to pure red and green, achieving wider color gamut coverage than conventional white-LED LCDs. The technology serves broadcast monitoring, cinematic home viewing, and color-critical creative workflows where Rec. 2020 coverage matters. TVs anchor current revenue, while gaming monitors represent the fastest-expanding margin pool as refresh rates climb past 144 Hz. Mini LED backlighting is displacing conventional edge-lit designs in professional workstations where HDR precision commands premium pricing.
South Korea's Ministry of Trade, Industry and Energy enforces energy efficiency labeling that penalizes high-consumption displays, while China's SAMR mandates GB standards for electronic product safety and electromagnetic compatibility. The EU Ecodesign Directive tightens standby power limits and material disclosure requirements for displays sold in member states. Stakeholders must track how RoHS exemptions for cadmium-containing quantum dots evolve, as this determines whether European market access requires reformulated phosphor alternatives or entirely new emissive architectures.
Market Dynamics
Quantum dot color conversion is rewriting supply chain economics as fabs pivot from phosphor-based backlighting to cadmium-free quantum dot enhancement films. This technology transition concentrates investment in Seoul and Shenzhen, where panel manufacturers face mounting regulatory pressure on fluorinated gas emissions.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbons in display manufacturing is accelerating adoption of solvent-based quantum dot deposition processes that eliminate fluorinated precursors entirely.
- Gaming monitor refresh rates:Esports venues and professional gaming leagues are mandating panels above 240 Hz, pulling quantum dot color volume into displays previously served by conventional white-LED LCDs.
- Shenzhen cluster expansion:TCL and BOE are adding dedicated QLED lines at their Bao'an and Longhua campuses, concentrating quantum dot film lamination capacity within a 50-kilometer radius.
Market Restraints
- Cadmium-free quantum dot yield:Indium phosphide alternatives suffer 15-20% efficiency penalties versus cadmium selenide cores, compressing margins for premium tier panels.
- Blue LED die concentration:Nichia and Epistar control 70% of high-efficiency gallium nitride epitaxy, creating single-source vulnerability for quantum dot backlight units.
- China MEE enforcement:Stricter volatile organic compound limits on quantum dot inkjet printing are extending qualification timelines for new film suppliers by 8-12 months.
Strategic Opportunities
- India BIS certification:The Bureau of Indian Standards is finalizing display energy consumption norms that favor wide-gamut quantum dot panels over inefficient conventional LCDs in premium segments.
- Broadcast monitoring:Color grading suites in Los Angeles and London are specifying Rec. 2020 coverage that only quantum dot enhancement films currently deliver at viable price points.
- Mini LED convergence:The pairing of quantum dot color conversion with 10,000-zone local dimming is creating a professional workstation tier between conventional QLED and emissive micro-LED.
Industry Challenges
- Quantum dot chemist scarcity:The intersection of colloidal synthesis and display optics requires specialists trained at fewer than twelve global academic programs, constraining R&D scaling.
- RoHS exemption uncertainty:The European Commission's pending review of cadmium exemptions for quantum dots is freezing capital allocation decisions for European-bound product lines.
- Film lamination yield:Quantum dot enhancement film wrinkling during roll-to-roll processing destroys 8-12% of finished panels at Gen 8.5 fab scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | QLED Display Market |
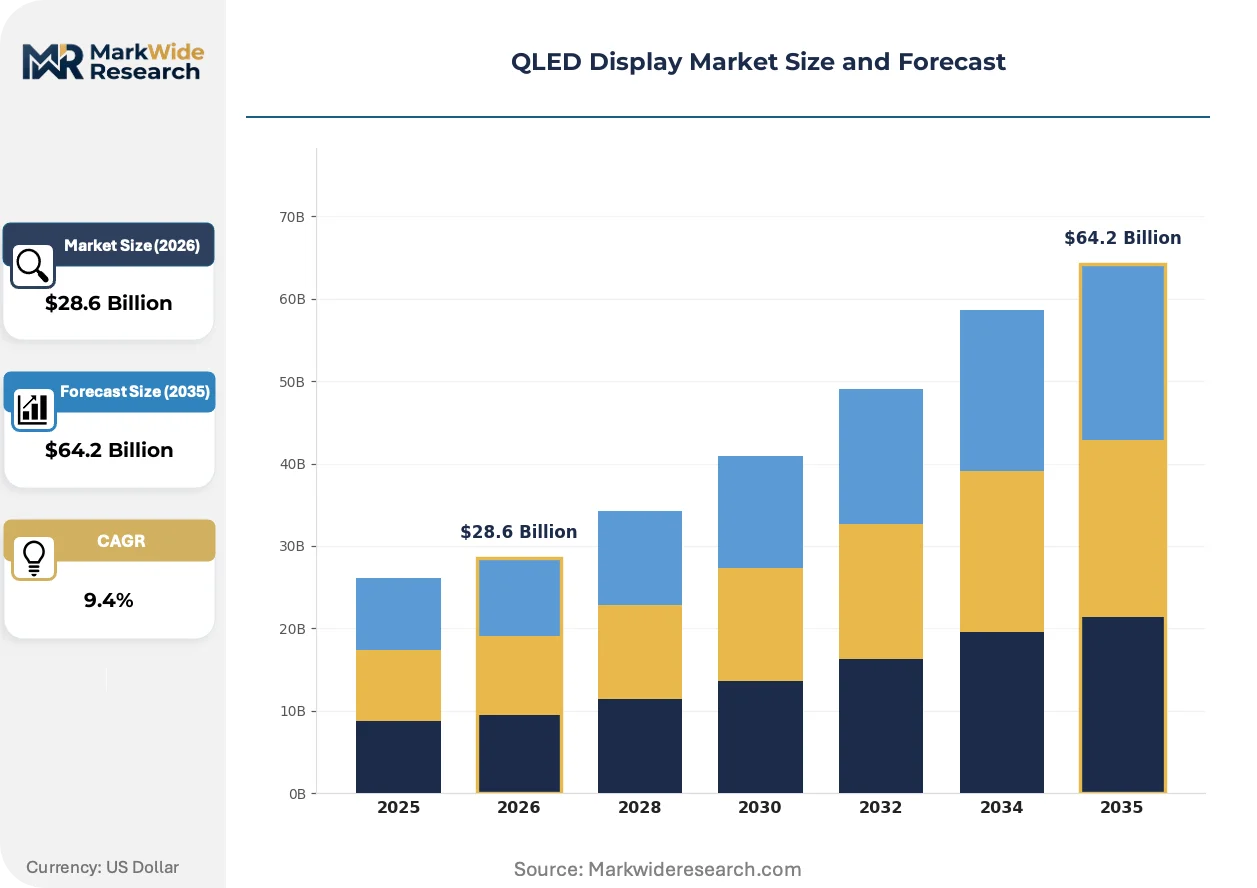
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TVs, Monitors, Commercial Displays, Digital Signage Technology: Edge-Lit, Direct-Lit, Mini LED, Quantum Dot Application: Home Entertainment, Gaming, Professional Workstations, Educational Use End User: Consumers, Corporates, Educational Institutions, Retailers |
| Companies Covered | Hisense, Skyworth, Samsung Electronics, Changhong, Panasonic, LG Electronics, Sony, Samsung Display, TCL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
QLED Display Market Emerging Trajectories
Display architecture is bifurcating between premium mini-LED quantum dot stacks and cost-optimized phosphor alternatives. This divergence is fragmenting fab equipment orders and reshaping how brands position color performance in consumer messaging.
Mini LED backlighting with quantum dot color conversion is rewriting HDR performance benchmarks in professional displays. Post-production houses in Culver City and Soho are specifying 2,000-nit peak luminance with full Rec. 2020 coverage that only this combination delivers. The technology is compressing the addressable market for conventional edge-lit QLED to sub-premium consumer tiers.
The EU Ecodesign Directive's tightened standby power limits are forcing firmware redesigns across quantum dot television lines. Manufacturers must now integrate discrete power management ASICs that cut vampire draw below 0.5 watts, adding $3-4 in bill-of-materials costs. South Korea's Ministry of Trade, Industry and Energy is mirroring these thresholds, creating a unified compliance target for Seoul-based panel makers.
Direct-to-consumer configuration tools are disrupting traditional retail channel dependency for premium QLED purchases. Samsung and LG have deployed online gamut visualization utilities that let buyers compare quantum dot versus conventional coverage against their existing displays. This channel shift is most visible in the United States, where Best Buy's Magnolia showrooms now function as appointment-only demonstration sites rather than primary transaction points.
QLED Display Market Segmentation
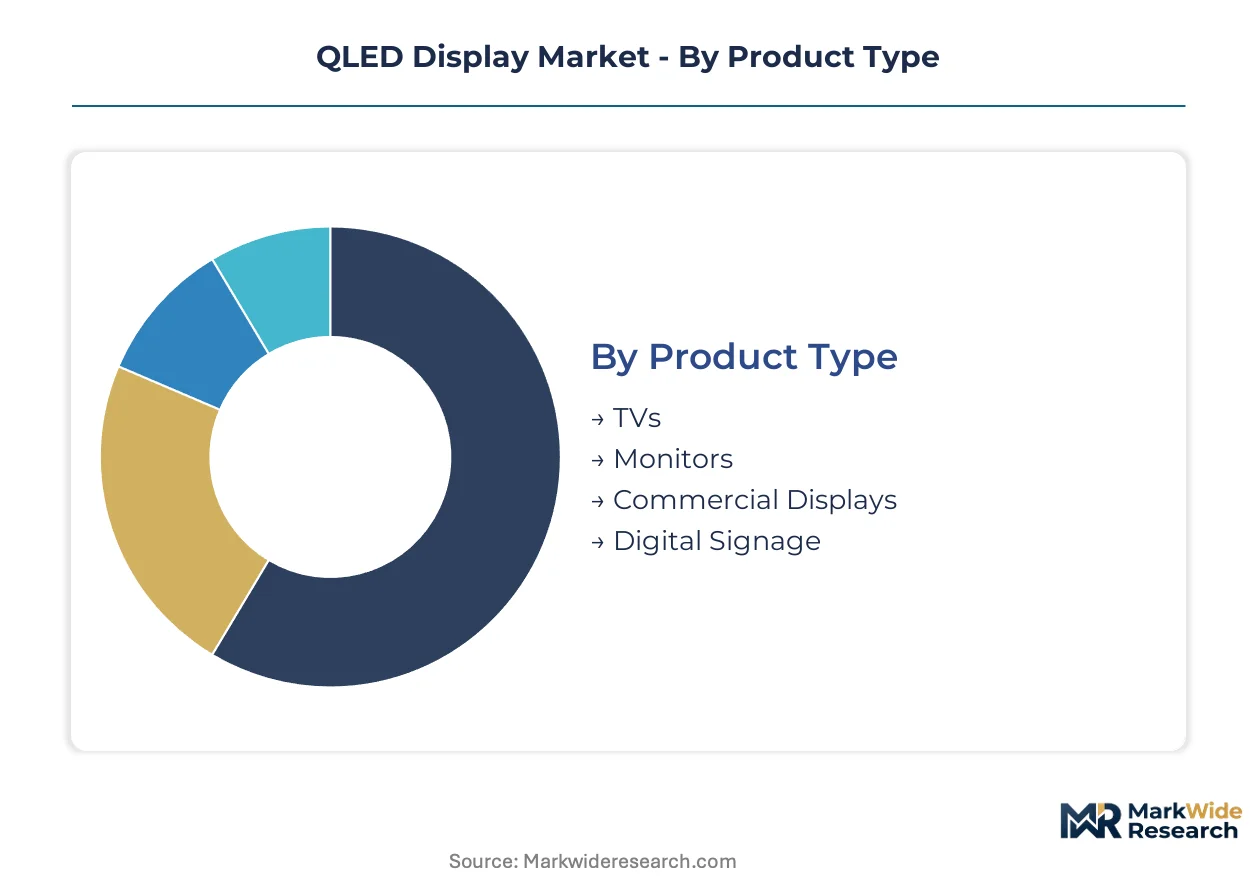
QLED display segmentation reveals how quantum dot color conversion technology fragments across price-performance tiers and use cases. Manufacturers must align fab capacity with distinct technical requirements rather than treating quantum dot enhancement as a uniform feature set.
Product Type:
The customization-to-standardization spectrum spans broadcast-caliber reference monitors at one extreme and mass-market televisions at the other, with commercial displays occupying engineered middle ground.
- TVs:Full-array local dimming with quantum dot enhancement films dominates premium living room installations. South Korean and Chinese fabs concentrate Gen 8.5 capacity here, driven by esports venue procurement and cinematic home theater demand.
- Monitors:Gaming-focused panels above 240 Hz refresh rates now mandate quantum dot color volume for league certification. Post-production suites in Culver City and Soho specify these for HDR color grading workflows where Rec. 2020 coverage is non-negotiable.
- Commercial Displays:Corporate lobby and control room installations prioritize 24/7 duty cycles with quantum dot stability.
- Digital Signage:Outdoor-rated units with high-nit output for transit hubs and retail facades.
Most installed capacity flows through TVs. Expansion is steepest in Monitors.
Technology:
Cost tier stratification separates premium mini-LED quantum dot stacks from value-engineered phosphor alternatives, fragmenting equipment procurement across fabs.
- Mini LED:10,000-zone local dimming paired with quantum dot color conversion creates professional workstation tier between conventional QLED and emissive micro-LED. Post-production houses specify 2,000-nit peak luminance that only this architecture delivers.
- Quantum Dot:Cadmium-free indium phosphide cores now dominate new film deposition as EU RoHS pressure tightens. Efficiency penalties versus cadmium selenide compress margins but preserve European market access.
- Direct-Lit:Conventional full-array backlighting with quantum dot enhancement for mid-tier consumer panels.
- Edge-Lit:Cost-optimized designs with limited dimming zones for entry-level volume.
Quantum Dot film lamination commands premium pricing. Mini LED integration is gaining share fastest in professional segments.
Application:
Volume concentration in home entertainment contrasts with margin concentration in color-critical professional workflows, reshaping how brands allocate R&D resources.
- Gaming:Esports leagues mandate panels above 240 Hz with quantum dot color volume, pulling technology into displays previously served by conventional white-LED LCDs. Tournament venues in Seoul and Los Angeles drive specification escalation.
- Professional Workstations:Color grading suites require Rec. 2020 coverage that quantum dot enhancement films uniquely deliver at viable price points. HDR precision commands 3-4x pricing versus consumer tiers.
- Home Entertainment:Cinematic viewing with streaming-optimized picture processing.
- Educational Use:Interactive whiteboards and hybrid classroom displays with eye-care certifications.
Home Entertainment absorbs majority volume. Gaming is climbing the fastest as refresh rate requirements escalate.
End User:
Customer type determines procurement modality, with consumers buying through direct-to-consumer configuration tools while corporates negotiate multi-year fleet contracts.
- Corporates:Financial trading floors and broadcast control rooms specify quantum dot panels for color accuracy under continuous operation. Procurement teams negotiate 3-5 year replacement cycles with on-site calibration services.
- Consumers:Online gamut visualization utilities now replace traditional retail dependency for premium purchases. Best Buy's Magnolia showrooms function as appointment-only demonstration sites rather than primary transaction points.
- Educational Institutions:University media labs and K-12 districts with technology refresh grants.
- Retailers:Digital signage network operators managing thousand-unit deployments.
Corporates anchor professional-tier demand. Consumers drive steepest expansion in premium home theater configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quantum dot chemists and display optical engineers cluster disproportionately around Seoul and Shenzhen, anchoring the industry's geographic footprint. Panel fabrication capacity concentrates where these specialized workforces intersect with established LED epitaxy supply chains. Regulatory pressure on fluorinated gas emissions is redrawing investment flows across four major production geographies.
South Korea
Seoul Capital Area fabs produce the majority of premium QLED panels for broadcast monitoring and gaming applications. The Ministry of Trade, Industry and Energy enforces energy efficiency labeling that penalizes high-consumption displays, pushing manufacturers toward mini-LED quantum dot architectures. Samsung Display operates dedicated quantum dot film lamination lines in Asan and Tangjeong, consolidating color conversion expertise within a 100-kilometer radius of Seoul.
China
TCL and BOE are expanding QLED capacity at Bao'an and Longhua campuses to serve domestic gaming monitor demand and export markets. The Ministry of Ecology and Environment's stricter volatile organic compound limits on quantum dot inkjet printing have extended qualification timelines for new film suppliers. Shenzhen's 50-kilometer manufacturing corridor now hosts the world's densest concentration of cadmium-free quantum dot deposition capacity.
United States
Post-production houses in Los Angeles and Culver City specify Rec. 2020 coverage for HDR color grading workflows, importing premium quantum dot panels from Asian fabs. The EPA regulates fluorinated gas emissions in display manufacturing equipment under the Clean Air Act, creating compliance costs for domestic assembly operations. Best Buy's Magnolia showrooms in major metros function as appointment-only demonstration sites for direct-to-consumer QLED configuration.
Japan
Nichia Corporation's dominance in high-efficiency gallium nitride epitaxy creates single-source dependency for blue LED dies feeding quantum dot backlight units. METI's technology roadmaps prioritize energy-efficient display architectures, aligning with corporate procurement preferences for low-power quantum dot monitors. Osaka-based optical component suppliers specialize in quantum dot enhancement film substrates for the professional workstation tier.
Germany
Broadcast equipment integrators in Munich and Berlin specify quantum dot panels for European control room installations requiring 24/7 color stability. The EU F-Gas Regulation's phasedown of hydrofluorocarbons accelerates adoption of solvent-based quantum dot deposition processes that eliminate fluorinated precursors. Stuttgart-area engineering firms develop calibration systems for quantum dot color volume verification in professional workflows.
QLED Display Market Vendor Landscape
Top-tier vendors anchor the premium quantum dot tier, while mid-scale fabricators compete on volume and cost-engineered alternatives. The vendor base stratifies between captive display manufacturers with in-house quantum dot supply chains and independent panel assemblers sourcing enhancement films from third-party chemical suppliers. Three strategic archetypes dominate: vertically integrated electronics conglomerates controlling epitaxy through final assembly; specialized quantum dot material suppliers licensing deposition technology; and contract manufacturers serving white-label retail brands. Competitive moves concentrate on capacity expansion in cadmium-free film deposition and strategic partnerships bridging LED die supply with color conversion expertise.
Within the vertically integrated tier, Samsung Electronics and Samsung Display exemplify the archetype of captive quantum dot supply chains sustaining pricing power in ultra-premium segments. TCL occupies a position as a volume-driven competitor expanding dedicated QLED lines at Chinese campuses. Sony represents differentiation through proprietary image processing rather than panel manufacturing ownership. Hisense and Skyworth sit within the tier of diversified electronics conglomerates leveraging quantum dot technology across television and commercial display portfolios. Panasonic and LG Electronics exemplify established display manufacturers navigating the technology transition from conventional phosphor backlighting toward quantum dot color conversion architectures.
| Leading Market Players |
|---|
| Hisense |
| Skyworth |
| Samsung Electronics |
| Changhong |
| Panasonic |
| LG Electronics |
| Sony |
| Samsung Display |
| TCL |
| Others |
Supply Flow & Price Mechanics
Mini LED quantum dot convergence versus conventional edge-lit architectures creates a stark bifurcation that manifests simultaneously in pricing premiums and supply chain specialization. The former commands three-tier pricing structure across premium, standard, and economy levels while concentrating component sourcing around Seoul and Shenzhen fabrication clusters.
Pricing Analysis
Bundled calibration services and extended warranty packages separate professional workstation tiers from unbundled consumer panels sold through direct-to-consumer channels. Price differentiation hinges on Rec. 2020 certification grade and volume procurement scale, with broadcast monitoring suites showing least sensitivity and educational institutions exhibiting highest price elasticity. Cost compression in entry-level edge-lit segments is intensifying because indium phosphide quantum dot efficiency penalties force margin trade-offs.
Supply Chain Analysis
Freight costs for quantum dot enhancement films from Seoul to Los Angeles post-production houses add meaningful landed cost premiums versus Shenzhen-to-Seoul intra-Asia routes. Supply concentrates in South Korea, China, and Japan, with blue LED die supply drawing from Nichia's Osaka epitaxy facilities and cadmium-free quantum dot inks sourcing from specialized chemical suppliers. Single-source vulnerability in gallium nitride epitaxy creates structural risk. Distribution runs through brand-direct configuration tools and Magnolia appointment-only showrooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The QLED display market functions as a stable compounder anchored by regulatory mandates on fluorinated gas emissions that perpetually refresh replacement demand across the installed base.
For Market Incumbents: Hedge against cadmium-free quantum dot yield penalties by securing captive indium phosphide synthesis capacity in Shenzhen or Seoul. Prioritize certification investment for EU F-Gas Regulation compliance to defend margin position in European broadcast monitoring segments against emerging phosphor-alternative entrants.
For New Entrants and Emerging Players: Enter via India's BIS certification pathway for display energy consumption norms, where wide-gamut quantum dot panels face favorable regulatory positioning against inefficient conventional LCDs. Target educational institution procurement cycles with bundled calibration services as the most penetrable white-space segment.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized quantum dot material suppliers licensing deposition technology to fabs lacking in-house colloidal synthesis expertise. The five-to-ten year viability window favors acquisition targets with RoHS exemption contingency planning. Watch for European Commission cadmium exemption review outcomes as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cadmium-Free Quantum Dot Scale-Up | Solvent-based deposition eliminates fluorinated precursors for EU F-Gas Regulation compliance. |
| Mini LED Backlight Integration | 10,000-zone local dimming creates professional workstation tier between QLED and micro-LED. |
| Direct-to-Consumer Configuration Launch | Online gamut visualization utilities bypass traditional retail channel dependency. |
| Gaming Monitor Refresh Rate Escalation | 240 Hz-plus panels with quantum dot color volume meet esports league certification mandates. |
| India BIS Certification Pathway | Energy consumption norms favor wide-gamut quantum dot panels in premium segments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with display panel procurement managers, quantum dot material chemists, broadcast engineering directors, and retail channel category buyers against secondary validation from SEC 10-K filings, Korean Ministry of Trade customs records, and EPA Clean Air Act enforcement databases. Bottom-up fab capacity modeling and top-down end-use demand estimation provided triangulation.
Segment-weighting across the analysis window applied technology tier, application use case, and geographic regulatory cluster dimensions. CAGRs derived from unit shipment trajectories and average selling price evolution across mini LED quantum dot, conventional quantum dot, and phosphor-alternative architectures. Forecast inputs incorporated gaming monitor refresh rate certification mandates and RoHS exemption timeline scenarios.
Inputs from panel manufacturer disclosures and regulatory filing databases were available through the study window; gaps in quantum dot inkjet printing yield data introduce uncertainty bands around cadmium-free film cost projections. Forecasts reflect assumptions on fluorinated gas regulation enforcement intensity and blue LED die supply concentration. A model refresh is warranted upon material change in European Commission cadmium exemption determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Portable Projector Market
Display Technologies
Paper-Thin Display Market
Display Technologies
LCD Panel Market
Display Technologies
IGZO Display Market
Display Technologies
Smart Display Market
Display Technologies
Display Glass Substrate Market
Display Technologies
3D Holographic Display Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Global 5K Display Resolution Market
Display Technologies
North America Head-Up Display Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Electronic Display Market
Display Technologies
Global Touchable Holographic Display Market