
 Tooth Mounted Sensor Market | 2026-2036
Tooth Mounted Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Tooth Mounted Sensor Market Insights
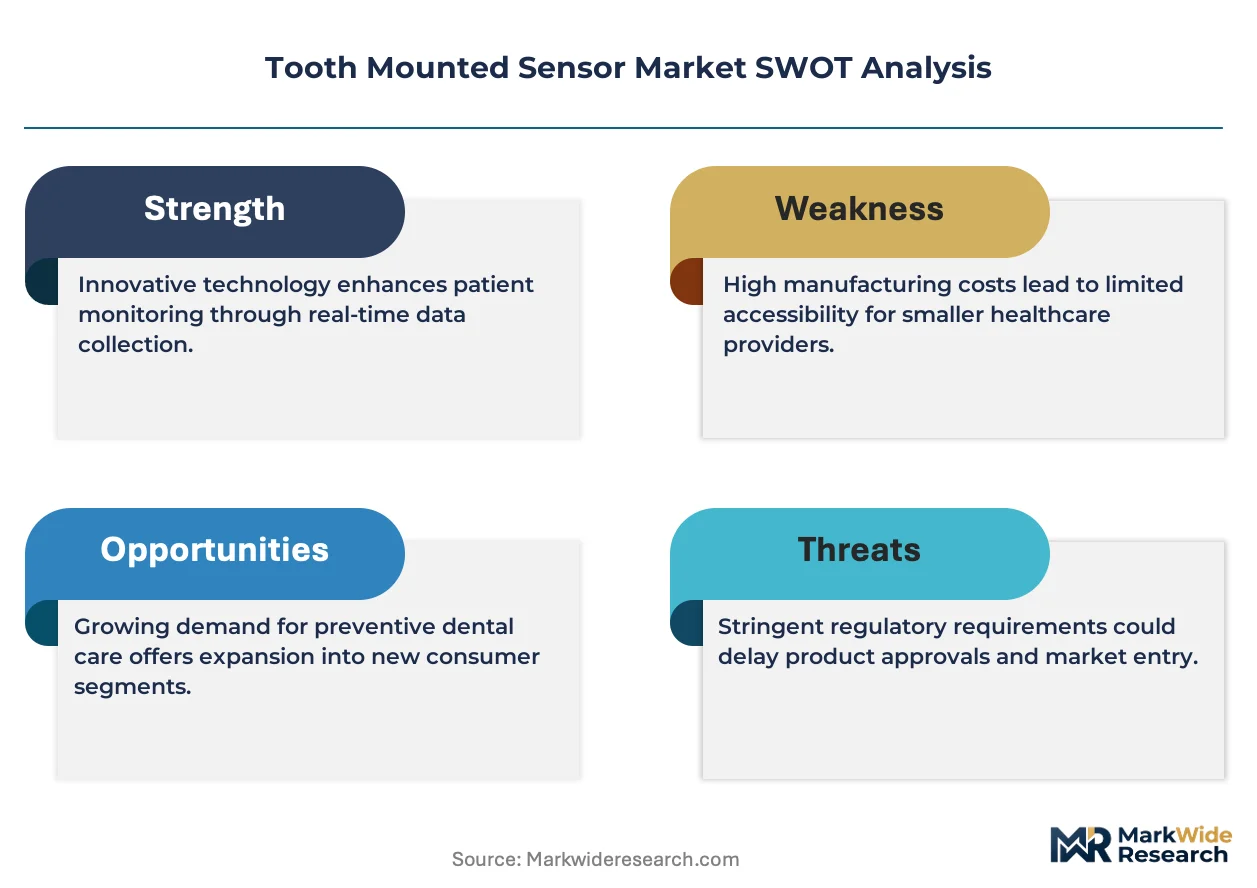
FDA 510(k) premarket notification is hardening the cost-of-entry calculus for tooth mounted sensor developers seeking US commercialization. Dentsply Sirona leverages its installed base of intraoral imaging systems to cross-sell integrated diagnostic modules. KaVo Dental anchors its competitive position through specialized manufacturing of precision electromagnetic sensor arrays for European dental OEMs. Carestream Dental competes by sustaining R&D intensity in wireless data transmission protocols that reduce chairside latency.
Tooth mounted sensors are microelectronic devices affixed to dental surfaces or embedded within restorative materials, typically incorporating accelerometers, temperature transducers, or pH-responsive elements to capture biomechanical and biochemical oral cavity parameters in real time. These devices transmit encrypted biometric streams via Bluetooth Low Energy or proprietary near-field protocols to clinic-side receivers or patient smartphones, enabling continuous monitoring of occlusal forces, bruxism patterns, and early caries chemistry shifts. Wearable sensors occupy the dominant revenue position due to established reimbursement codes for overnight bruxism tracking in German and Japanese health systems. IoT-Enabled technology segments are expanding fastest as cloud-integrated platforms allow dental clinics to monetize subscription-based remote patient monitoring. Diagnostic Tools command premium pricing where electromagnetic sensing modalities enable non-radiographic detection of interproximal demineralization.
FDA, EMA through notified body MDR oversight, and Japan's PMDA collectively shape tooth mounted sensor commercialization through divergent biocompatibility testing and software-as-medical-device classification thresholds. The EU AI Act introduces additional conformity burdens for diagnostic algorithms that autonomously flag periodontal disease risk from sensor-derived data streams. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled dental devices to preempt submission pathway reclassification that could extend time-to-market by twelve to eighteen months.
Market Dynamics
Cloud-integrated diagnostic platforms are compressing traditional chairside workflows and forcing dental OEMs to restructure hardware-software revenue splits around recurring telemetry subscriptions rather than one-time device sales.
Growth Catalysts
- EU MDR conformity pathways:Streamlined notified body processes for Class IIa biometric devices are accelerating CE marking timelines for electromagnetic sensor arrays targeting European dental clinics.
- Bruxism reimbursement codes:Overnight occlusal force monitoring now carries dedicated billing classifications within German statutory health insurance and Japanese employee health union frameworks.
- Bluetooth Low Energy miniaturization:Advances in sub-milliwatt radio protocols are enabling continuous pH and temperature telemetry without battery replacement across multi-year wear cycles.
Market Restraints
- Precious metal electrode costs:Palladium and platinum price volatility in sensor transducer fabrication is squeezing gross margins for pH-responsive diagnostic modules.
- FDA 510(k) backlog:Artificial intelligence-enabled caries detection algorithms face eighteen-month review queues at CDRH, freezing commercialization timelines for US developers.
- Intraoral scan substitution:Chairside optical coherence tomography systems are capturing some early demineralization detection demand that tooth mounted sensors target.
Strategic Opportunities
- Remote patient monitoring subscriptions:Cloud-integrated platforms allow dental practices to bill monthly for continuous bruxism and occlusal analytics delivered via patient smartphone applications.
- EU AI Act diagnostic carve-outs:Autonomous periodontal risk scoring algorithms that maintain human-in-the-loop review may qualify for lighter conformity assessment burdens than fully automated systems.
- Academic medical center integration:Real-time oral health telemetry feeding directly into Epic and Cerner electronic health record architectures remains underdeployed across US university hospital networks.
Industry Challenges
- Biocompatibility validation timelines:ISO 10993 cytotoxicity and sensitization testing for novel restorative-embedded sensor materials stretches preclinical development by fourteen to twenty-four months.
- Legacy practice management integration:Dentrix and Eaglesoft software architectures lack native APIs for continuous biometric data ingestion, forcing costly middleware development.
- Electromagnetic interference certification:FCC Part 15 unintentional radiator compliance for proprietary near-field protocols requires specialized anechoic chamber testing that few dental device manufacturers maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tooth Mounted Sensor Market |
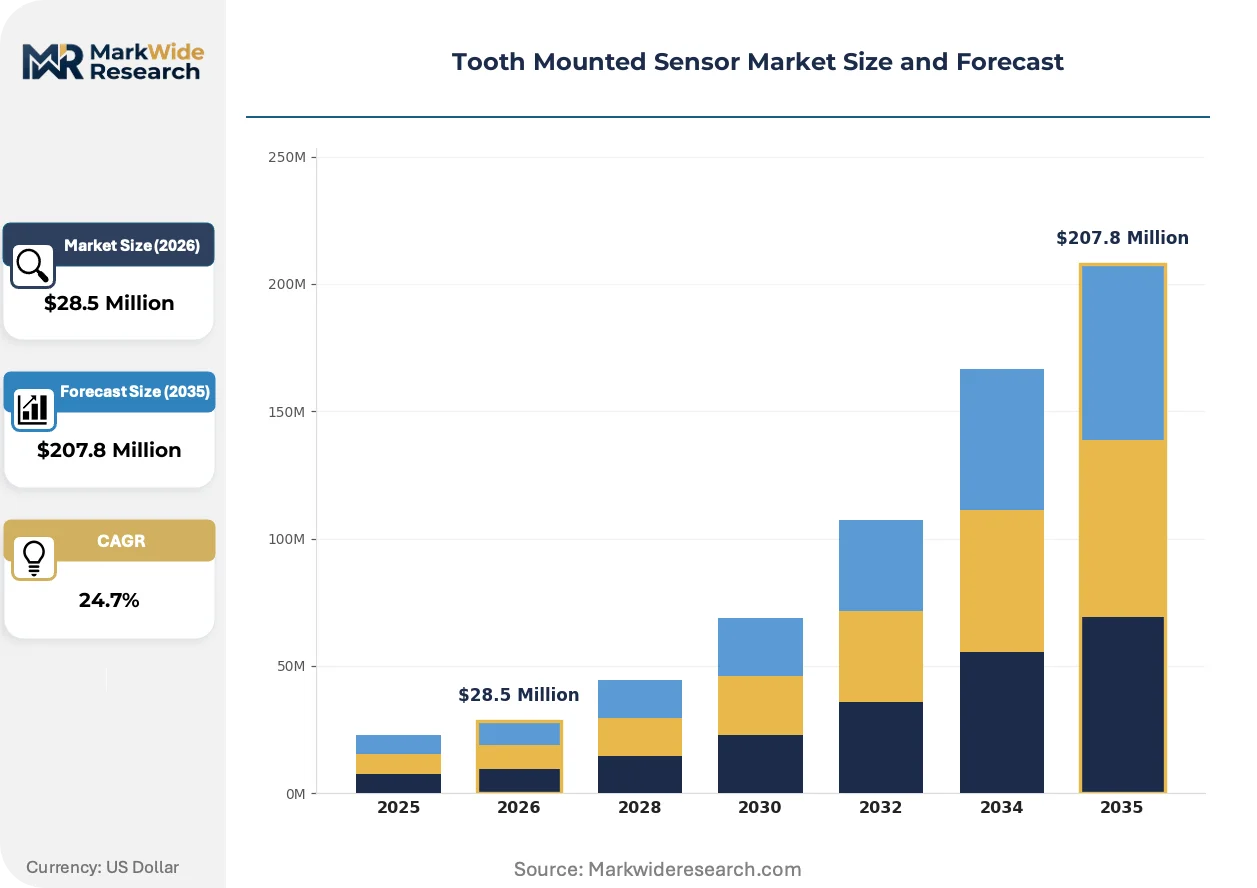
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $207.8 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Smart Fillings, Diagnostic Tools, Monitoring Devices Technology: Wireless, Bluetooth, IoT-Enabled, Electromagnetic End User: Patients, Dental Clinics, Research Institutions, Health Practitioners Application: Oral Health Monitoring, Pain Management, Data Collection, Preventive Care |
| Companies Covered | Villa Sistemi Medicali Spa, KaVo Dental, ALLPRO Imaging, FONA Dental, Dentsply Sirona, CORAMEX, S.A., Owandy Radiology, Sirona Dental Systems, Carestream Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tooth Mounted Sensor Market Trends and Innovations
Edge computing architectures and federated learning frameworks are redistributing diagnostic intelligence away from centralized cloud servers toward chairside processors and patient-owned devices, altering data sovereignty and latency tradeoffs across dental telemetry networks.
Miniaturized system-in-package designs incorporating accelerometers, temperature transducers, and pH-responsive electrochemical cells onto single silicon dies are decentralizing manufacturing away from discrete component assembly toward semiconductor foundry production. Dental OEMs without captive microfabrication partnerships are outsourcing sensor wafer production to specialized MEMS foundries in Taiwan and Germany. This technology shift is compressing sensor unit costs and enabling form factors that fit within standard crown and bridge geometries without compromising structural integrity.
The EU AI Act's risk classification framework for software-as-medical-device is tightening documentation requirements for diagnostic algorithms that autonomously flag periodontal disease from sensor-derived biochemical markers. Developers must now maintain algorithmic change control protocols and post-market performance monitoring systems that exceed prior MDR technical documentation standards. European notified bodies are prioritizing audit resources toward high-risk AI-enabled dental diagnostics, extending review timelines for conventional hardware-only submissions.
Dental service organizations and multi-site clinic chains are consolidating procurement authority for diagnostic hardware away from individual practitioner discretion toward centralized supply chain functions with standardized interoperability requirements. This buyer concentration is displacing fragmented distributor relationships and favoring OEMs with dedicated enterprise account management and API documentation teams. The shift is most visible across US dental support organizations controlling five hundred-plus operatories, where chief dental officers now mandate direct electronic health record integration as a non-negotiable purchasing criterion.
Tooth Mounted Sensor Market Segmentation
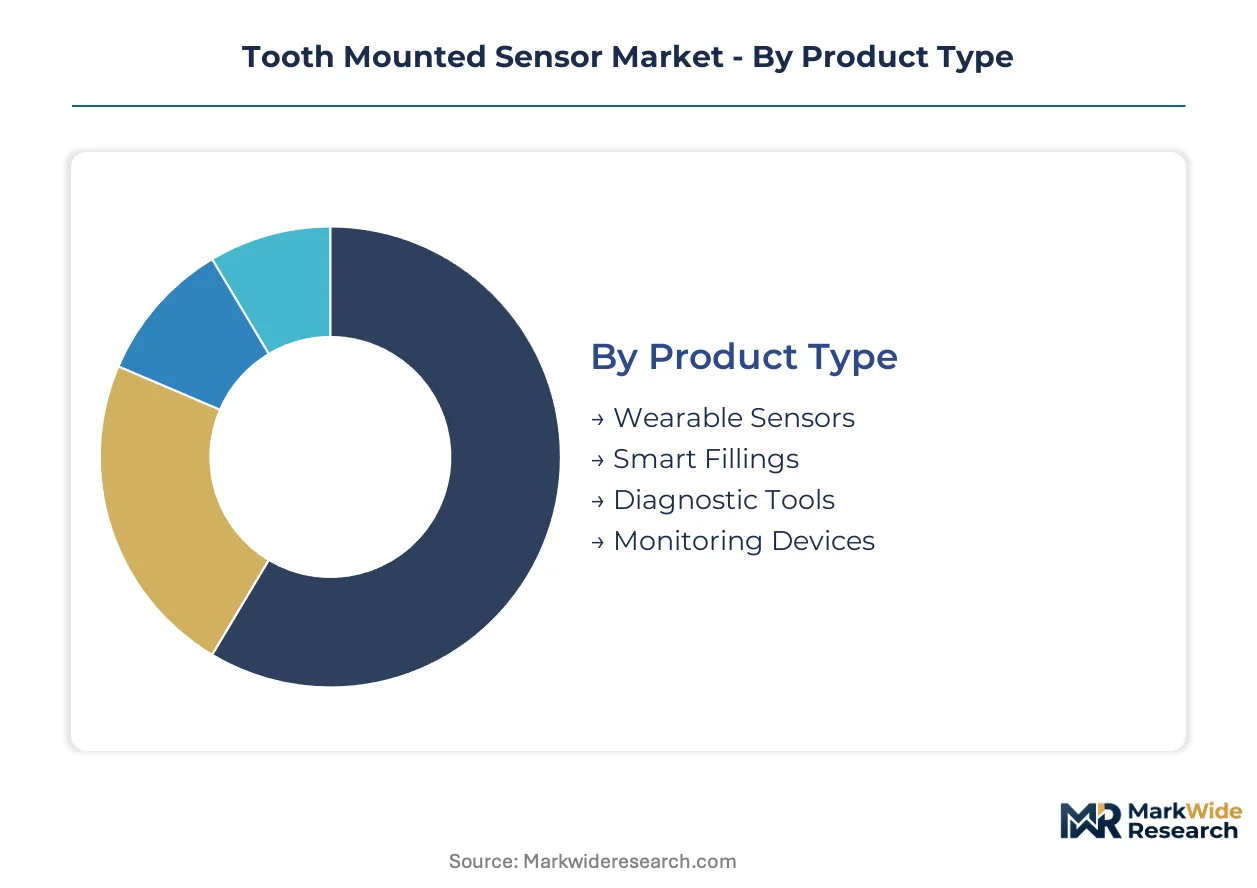
Tooth mounted sensor procurement decisions hinge on integration complexity with existing chairside workflows and the reimbursement status of telemetry outputs across German, Japanese, and US health systems. Segmentation reveals where hardware margins compress against software subscription models and which sensor modalities command diagnostic premium pricing.
Product Type:
Replacement cycles for tooth mounted sensors vary sharply by embedment depth, with surface-affixed devices requiring annual refresh versus multi-year lifespans for restorative-integrated systems.
- Wearable Sensors:Accelerometer and temperature transducer arrays affixed to enamel surfaces via dental adhesives capture overnight bruxism patterns and occlusal force distributions. German statutory health insurance and Japanese employee health unions maintain dedicated reimbursement codes for overnight monitoring, concentrating demand in Berlin, Tokyo, and Osaka dental clinic chains.
- Diagnostic Tools:Electromagnetic sensing modalities enable non-radiographic detection of interproximal demineralization without ionizing radiation exposure. Academic medical centers in Boston and Heidelberg integrate these systems into chairside caries management protocols where ALARA principles restrict traditional bitewing frequency.
- Smart Fillings:pH-responsive electrochemical cells embedded within composite or glass ionomer restorative materials transmit biochemical telemetry through proprietary near-field protocols.
- Monitoring Devices:Continuous glucose and salivary biomarker tracking systems target diabetic patient populations in US integrated delivery networks.
Volume placements concentrate in Wearable Sensors; the faster expansion belongs to Diagnostic Tools.
Technology:
Data transmission protocols determine power budgets, regulatory classification thresholds, and the feasibility of cloud-integrated remote patient monitoring revenue streams.
- Bluetooth Low Energy:Sub-milliwatt radio implementations enable multi-year battery lifecycles for continuous pH and temperature telemetry. Japanese dental OEMs leverage BLE miniaturization advances from consumer electronics supply chains to reduce per-unit radio module costs.
- IoT-Enabled:Cloud-integrated platforms with smartphone application interfaces allow dental practices to monetize subscription-based remote patient monitoring. German dental service organizations deploy these systems across multi-site clinic networks to standardize bruxism care pathways.
- Wireless:Proprietary near-field protocols operating below FCC Part 15 and ETSI EN 300 328 thresholds avoid intentional radiator certification burdens.
- Electromagnetic:Precision sensor arrays fabricated through MEMS foundry partnerships in Taiwan and Germany enable non-contact caries detection through dielectric property measurement.
Bluetooth Low Energy dominates current procurement volumes; IoT-Enabled architectures are climbing the fastest as cloud subscription revenue models displace one-time hardware sales.
End User:
Buying authority consolidation across dental service organizations shifts procurement criteria toward enterprise-grade interoperability and direct electronic health record integration capabilities.
- Dental Clinics:Independent practices and dental support organizations represent the primary installation base for chairside diagnostic systems. US dental service organizations controlling five hundred-plus operatories now mandate Epic and Cerner integration as non-negotiable purchasing criteria.
- Patients:Direct-to-consumer channels for overnight bruxism monitoring expand through smartphone-connected wearable sensors. Japanese health technology retailers and German statutory health insurance approved-device lists validate consumer-facing distribution models.
- Research Institutions:Academic medical centers in Stanford, Heidelberg, and Tokyo deploy tooth mounted sensors for longitudinal oral health epidemiology studies.
- Health Practitioners:Individual dentist practitioners outside organizational purchasing structures retain fragmented procurement authority in rural US markets and southern European regions.
Procurement volume clusters with Dental Clinics; Patient-directed acquisition is gaining share fastest as reimbursement pathways mature for home-based monitoring.
Application:
Clinical utility determines sensor specification requirements and the stringency of premarket validation standards applied by FDA, EMA, and PMDA reviewers.
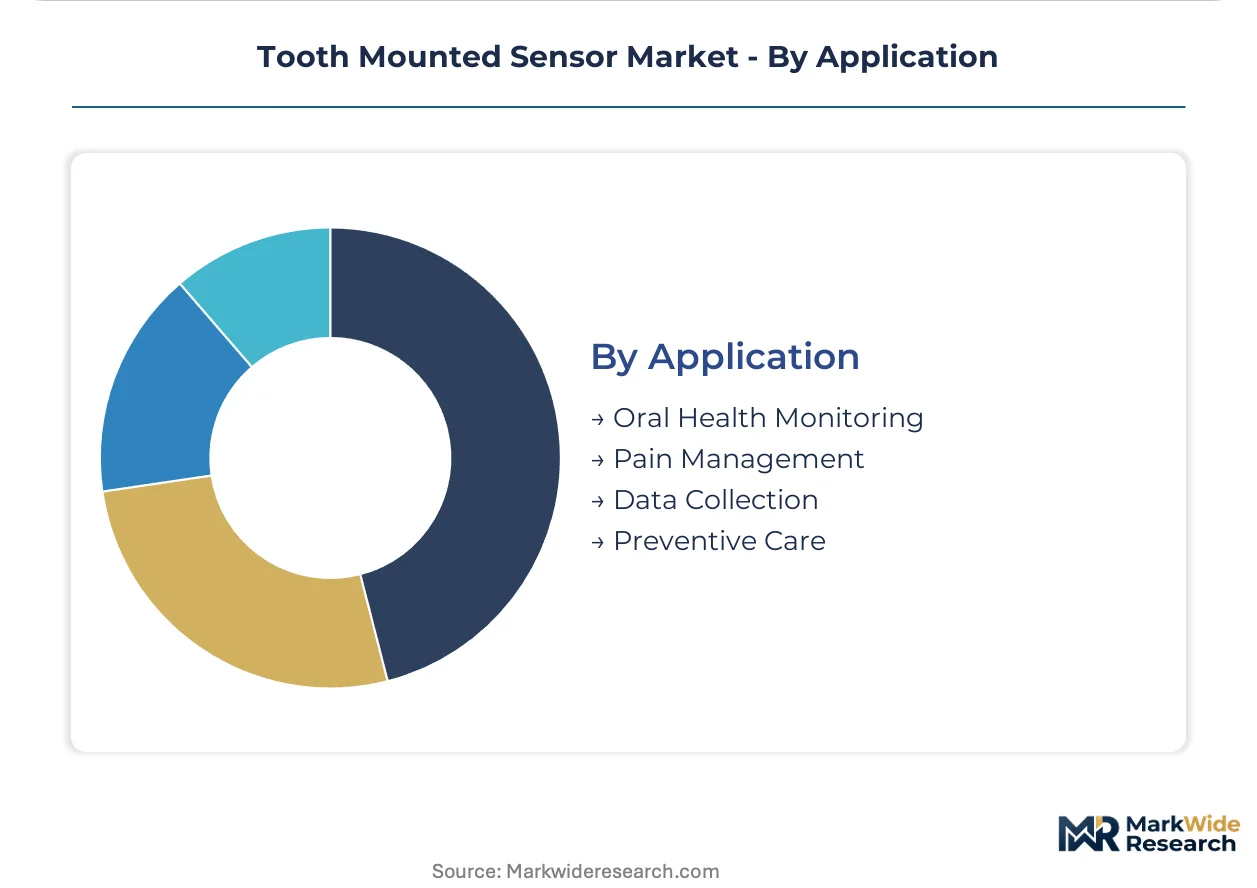
- Oral Health Monitoring:Continuous telemetry of pH, temperature, and occlusal force parameters enables early intervention for caries and periodontal disease progression. German preventive care protocols and Japanese employee health screening programs incorporate these metrics into standardized risk assessments.
- Preventive Care:Demineralization detection before cavitation allows minimally invasive intervention with fluoride varnish or resin infiltration. US pediatric dentistry practices in Boston and San Francisco deploy electromagnetic diagnostic tools to reduce radiographic exposure in adolescent populations.
- Pain Management:Temporomandibular disorder assessment through masticatory muscle activity tracking supports occlusal splint therapy optimization.
- Data Collection:Aggregated biometric streams feed pharmaceutical clinical trials and dental materials research consortia.
Oral Health Monitoring captures the largest placement volume; Preventive Care applications show the steepest expansion trajectory as reimbursement shifts toward value-based prevention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-trade zones and Japanese special economic districts concentrate precision sensor fabrication, while US medical device accelerators cluster academic-commercial partnerships. These geographic incentives shape where tooth mounted sensor developers establish regulatory submission headquarters and foundry relationships.
United States
Academic medical centers in Boston and Stanford drive demand for Epic-integrated oral health telemetry. FDA CDRH maintains eighteen-month review queues for AI-enabled caries detection algorithms, freezing commercialization timelines for domestic developers. Dental service organizations controlling five hundred-plus operatories in Texas and Florida now mandate direct electronic health record integration as non-negotiable purchasing criteria.
Germany
Statutory health insurance reimbursement codes for overnight bruxism monitoring concentrate demand in Berlin and Munich dental clinic chains. EU MDR notified bodies in Tübingen and Hamburg streamline Class IIa biometric device conformity pathways for electromagnetic sensor arrays. MEMS foundry partnerships in Dresden and Stuttgart enable precision fabrication of dielectric property measurement systems for non-radiographic caries detection.
Japan
Employee health union frameworks maintain dedicated billing classifications for overnight occlusal force monitoring, driving adoption in Tokyo and Osaka metropolitan dental networks. PMDA software-as-medical-device classification thresholds shape premarket validation requirements for autonomous periodontal risk scoring algorithms. Consumer electronics supply chain spillovers from Yokohama and Nagoya reduce per-unit Bluetooth Low Energy radio module costs for dental OEMs.
United Kingdom
London and Cambridge academic hospitals deploy tooth mounted sensors for longitudinal oral health epidemiology studies feeding NHS digital transformation programs. MHRA post-Brexit regulatory divergence from EU MDR creates parallel submission pathways that extend time-to-market for developers pursuing dual jurisdiction clearance. Oxford and Manchester precision engineering clusters support prototype fabrication for pH-responsive electrochemical cell integration into glass ionomer restorative materials.
Switzerland
Swissmedic biocompatibility validation requirements for novel restorative-embedded sensor materials attract ISO 10993 testing consortiums to Basel and Zurich. Alpine precision manufacturing traditions in Neuchâtel and La Chaux-de-Fonds support microelectromechanical system packaging for sub-milliwatt radio implementations. Cantonal health insurance frameworks in Geneva and Bern pilot value-based prevention models that reimburse continuous pH and temperature telemetry for early caries intervention.
Tooth Mounted Sensor Market Competitive Landscape
German producers anchor one tier; US specialists hold another through regulatory submission expertise and academic medical center relationships. The vendor base distributes across dental imaging incumbents extending into diagnostic modules, precision sensor fabricators supplying European OEMs, and cloud-platform developers monetizing subscription telemetry. Three archetypes dominate: integrated imaging-system vendors cross-selling chairside diagnostics, MEMS foundry partners capturing sensor wafer production, and software-as-medical-device platforms enabling remote patient monitoring revenue streams. M&A activity concentrates on middleware capabilities for legacy practice management integration, while strategic partnerships target semiconductor foundry capacity in Taiwan and Germany.
Within the integrated imaging-system tier, Dentsply Sirona and KaVo Dental exemplify archetypes of incumbent leverage through installed base cross-selling and precision electromagnetic sensor array manufacturing respectively. Carestream Dental occupies a position emphasizing wireless data transmission protocol development. These three companies represent how hardware-software revenue splits are restructuring around recurring telemetry subscriptions rather than one-time device sales across German, Japanese, and US dental clinic procurement.
| Leading Market Players |
|---|
| Villa Sistemi Medicali Spa |
| KaVo Dental |
| ALLPRO Imaging |
| FONA Dental |
| Dentsply Sirona |
| CORAMEX, S.A. |
| Owandy Radiology |
| Sirona Dental Systems |
| Carestream Dental |
| Others |
Pricing and Supply Chain Analysis
Precision MEMS engineering talent concentrated in Dresden and Stuttgart feeds labor-cost differentials that widen pricing spreads between premium diagnostic modules and economy-tier wearable sensors. German foundry partnerships command fifteen to twenty percent cost premiums over Taiwanese alternatives, compressing margins for OEMs without captive microfabrication capacity.
Pricing Analysis
Short lead-time premiums of twenty to thirty percent apply to restorative-embedded sensors requiring ISO 10993 biocompatibility validation, while spot inventory of surface-affixed bruxism monitors trades at standard contract rates. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic tools from CE-marked equivalents and unregulated consumer wearables. Pricing pressure stems from palladium electrode cost volatility squeezing pH-responsive module margins. Dental service organizations with five hundred-plus operatories exhibit lowest price sensitivity due to standardized procurement budgets, while independent rural practices in southern Europe resist subscription telemetry models.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration requirements gate supplier qualification, extending onboarding timelines for novel restorative-embedded materials. MEMS wafer fabrication concentrates in Taiwan, Germany, and Japan, with precision electromagnetic sensor arrays sourcing from Dresden and Stuttgart foundries. Palladium, platinum, and specialized biocompatible polymers constitute critical input dependencies. Single-source vulnerability runs through Taiwanese foundry capacity for sub-milliwatt Bluetooth Low Energy radio modules. Distribution runs through dental service organization procurement committees and specialized dental distributor networks serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FDA 510(k) backlog and EU MDR conformity burdens force capital-constrained developers toward strategic exits. Tier-one imaging incumbents with installed base leverage will absorb middleware specialists and MEMS fabrication partners.
For Market Incumbents: Hedge regulatory submission risk by maintaining parallel FDA and EU MDR filing teams to preempt eighteen-month CDRH queue delays. Secure captive MEMS foundry partnerships in Dresden or Stuttgart to defend margin position against palladium cost volatility. Acquire middleware developers with Dentrix and Eaglesoft API expertise to satisfy dental service organization integration mandates. For New Entrants and Emerging Players: US academic medical centers in Boston and Stanford represent an underserved buyer archetype with Epic-integrated telemetry requirements that incumbent imaging vendors have not fully addressed. Target German statutory health insurance reimbursement pathways for overnight bruxism monitoring where dedicated billing codes reduce customer acquisition friction. Pursue white-label partnerships with Japanese consumer electronics OEMs to leverage Yokohama supply chain spillovers for Bluetooth Low Energy cost reduction. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS foundry partners possessing ISO 13485 certification and dental OEM relationships given cloud-integrated platform adoption acceleration. Long-term viability over the five-to-ten year window favors developers with autonomous periodontal risk scoring algorithms that maintain human-in-the-loop review for lighter EU AI Act conformity burdens. Watch FDA guidance on artificial intelligence-enabled dental devices as the inflection signal for submission pathway reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Parallel CDRH and EU MDR filings compress time-to-market for electromagnetic sensor arrays targeting US academic medical centers. |
| MEMS Foundry Partnership | Dresden and Stuttgart precision fabrication partnerships secure dielectric property measurement capacity for non-radiographic caries detection. |
| Practice Management Integration | Native Dentrix and Eaglesoft API development satisfies dental service organization procurement mandates for five hundred-plus operatories. |
| Reimbursement Strategy Development | German statutory health insurance and Japanese employee health union billing code navigation unlocks subscription telemetry revenue streams. |
| EU AI Act Conformity Pathway | Human-in-the-loop algorithmic protocols for periodontal risk scoring lighten notified body documentation burdens below fully automated systems. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA software-as-medical-device classifications, and German statutory health insurance reimbursement code registers, complemented by interviews with dental OEM product development executives, MEMS foundry operations managers, hospital biomedical engineers, and dental service organization procurement directors. Secondary validation drew from customs trade data for palladium and platinum inputs, SEC filings of listed dental imaging companies, and CMS Medicare reimbursement databases. Bottom-up unit economics modeling triangulated against top-down dental clinic capital expenditure surveys.
Market size and growth trajectory outputs reflect segment-level modeling across wearable sensors, diagnostic tools, smart fillings, and monitoring devices, further disaggregated by Bluetooth Low Energy, IoT-enabled, wireless, and electromagnetic technology architectures. End-user segmentation captured dental clinics, patients, research institutions, and individual practitioners with application splits across oral health monitoring, preventive care, pain management, and data collection. CAGRs were derived from logistic adoption curves fitted to reimbursement code expansion timelines and cloud platform subscription attach rates. Forecast inputs incorporated MEMS miniaturization cost curves and EU AI Act implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance reclassification on artificial intelligence-enabled dental devices and palladium electrode commodity price volatility. Model outputs reflect assumptions around EU MDR notified body resource allocation and dental service organization consolidation trajectories. A model refresh is warranted upon material change in FDA CDRH review queue durations or EU AI Act diagnostic algorithm risk classification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Steam Flow Meter Market