
 Photography Light Box Market | 2026-2036
Photography Light Box Market Size, Share, and Industry Trends Forecast 2026-2036
Photography Light Box Market Analytics
Chinese LED component manufacturing is consolidating as the dominant supply base for photography light box assemblies worldwide. Godox leverages its Shenzhen production footprint to control cost structures across portable and studio-grade units. Neewer competes aggressively through direct-to-consumer channel dominance on North American e-commerce platforms. Westcott anchors its position in professional tabletop segments through sustained relationships with commercial photography studios.
A photography light box is an enclosed illumination chamber with diffused LED or fluorescent panels, typically rated at 5500K–6500K color temperature and 90+ CRI, designed to eliminate shadows and provide uniform background lighting for product and macro photography. The portable segment leads volume sales due to collapsible fabric construction and USB power compatibility for field use, while studio-grade metal-framed units with AC power and dimmable output command the largest margin pools. Fabric and plastic materials dominate unit economics, though metal chassis variants sustain pricing power in professional applications where durability requirements exceed consumer thresholds.
FCC electromagnetic emissions standards in the United States and CE marking requirements under EU RoHS and REACH frameworks govern AC-powered and battery-operated unit market access, with California's Title 20 appliance efficiency regulations adding compliance layers for products sold into that state. China's GB standards for LED lighting components and Japan's METI energy efficiency labeling create additional certification pathways for manufacturers serving Asian markets. Stakeholders must monitor evolving right-to-repair legislation and extended producer responsibility mandates that could reshape material selection and modular design priorities across all major selling regions.
Market Dynamics
LED diffusion technology is compressing replacement cycles across e-commerce product photography studios, while Chinese component manufacturing consolidates supply control and North American platform sellers tighten image quality specifications.
Growth Catalysts
- E-commerce image standards:Amazon seller ecosystems and independent creator economies in the United States demand color-accurate CRI 90+ equipment, forcing upgrade waves across portable and studio-grade segments.
- California Title 20 efficiency mandates:Appliance efficiency regulations for products sold into California accelerate LED panel replacement of fluorescent legacy systems.
- USB power compatibility:Field-deployable collapsible fabric construction enables mobile content creation workflows, expanding addressable use cases beyond fixed studio environments.
Market Restraints
- LED driver component concentration:Shenzhen-based manufacturing clusters control critical semiconductor supply, exposing price volatility and logistics disruption risk.
- REACH substance restrictions:EU RoHS and ECHA frameworks limit certain plasticizers and flame retardants in fabric diffuser materials, complicating material sourcing.
- Smartphone computational photography:AI-powered shadow removal and background replacement apps reduce entry-level hardware dependency for casual sellers.
Strategic Opportunities
- Right-to-repair legislation:Extended producer responsibility mandates in European markets create first-mover advantage for modular, field-serviceable LED panel designs.
- Live commerce streaming:Real-time product demonstration requirements in Chinese and Southeast Asian digital retail open dedicated lighting hardware categories.
- Subscription equipment access:Creator economy platforms pilot rental-to-own models for premium studio-grade units, lowering capital barriers for emerging sellers.
Industry Challenges
- Color science expertise gaps:Small-scale e-commerce operators lack calibration competency for 5500K–6500K temperature consistency, driving return rates and reputation damage.
- Multi-jurisdiction certification timelines:Simultaneous FCC, CE, and GB standard compliance extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photography Light Box Market |
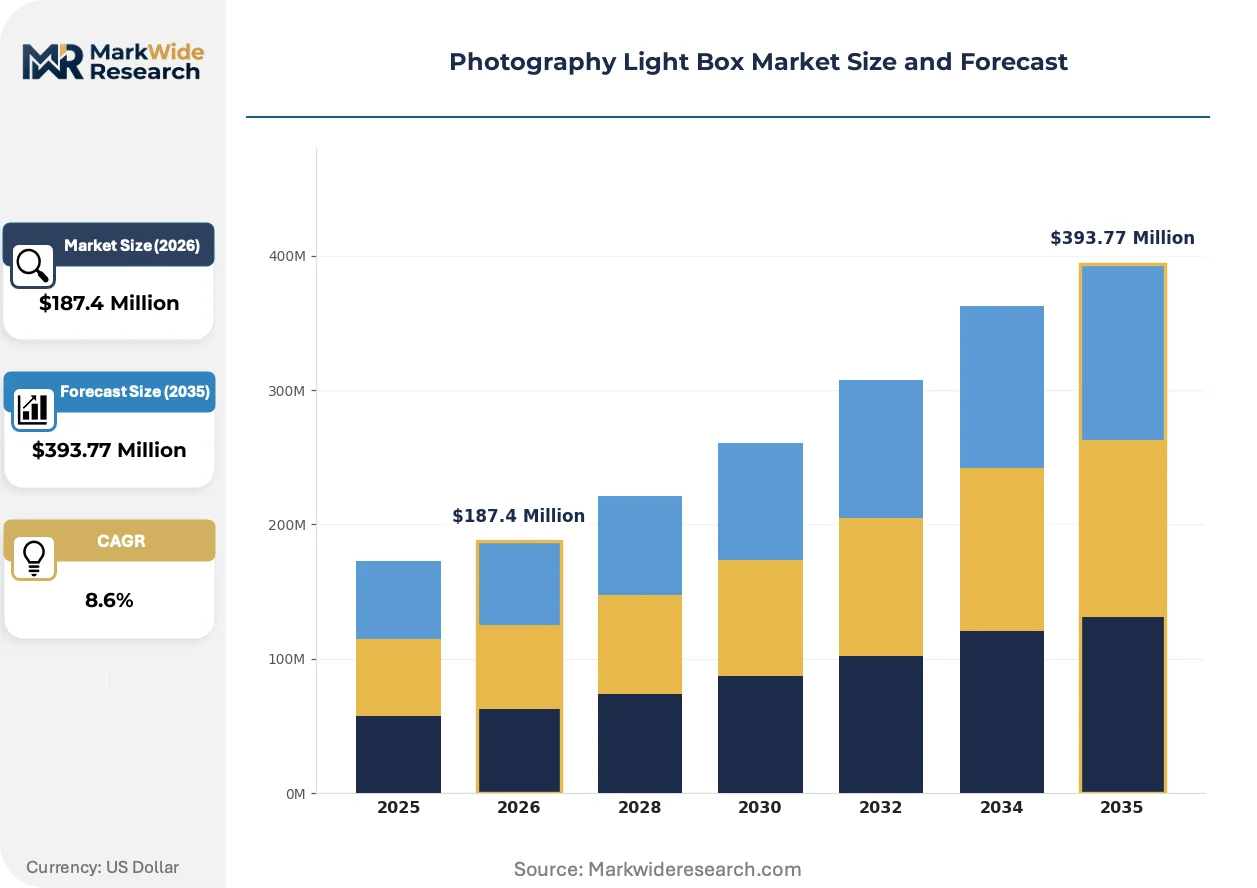
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Tabletop, Foldable, Studio Material: Plastic, Fabric, Metal, Glass Size: Small, Medium, Large, Extra Large Power Source: Battery-operated, AC-powered, USB, Solar |
| Companies Covered | Godox, Neewer, Fovitec, LimoStudio, Savage Universal, Foldio, ESDDI, Westcott, Profoto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photography Light Box Market Evolving Landscape
Active matrix dimming and tunable white LED arrays are reshaping equipment specifications, while regulatory pressure on material composition accelerates design overhaul across major selling regions.
Chip-on-board LED arrays with integrated diffusion films are electrifying professional tabletop segments. Commercial photography studios in Germany and the United States adopt these systems within eighteen-month refresh cycles. The technology is electrifying margin pools previously captured by fluorescent tube maintenance and replacement services.
EU REACH substance candidate list expansion is forcing reformulation of polycarbonate diffuser panels and adhesive compounds. Manufacturers serving European markets now pre-qualify alternative thermoplastics to avoid authorization bottlenecks. Studio-grade metal-framed units with certified material traceability command price premiums of fifteen to twenty percent over uncertified alternatives.
Direct platform integration is compressing traditional distributor roles. Amazon seller central and Shopify merchant ecosystems now surface lighting equipment through algorithmic procurement recommendations tied to photography service add-ons. This pattern concentrates most visibly in United States and United Kingdom digital retail corridors where platform-native sellers dominate volume.
Photography Light Box Market Segmentation
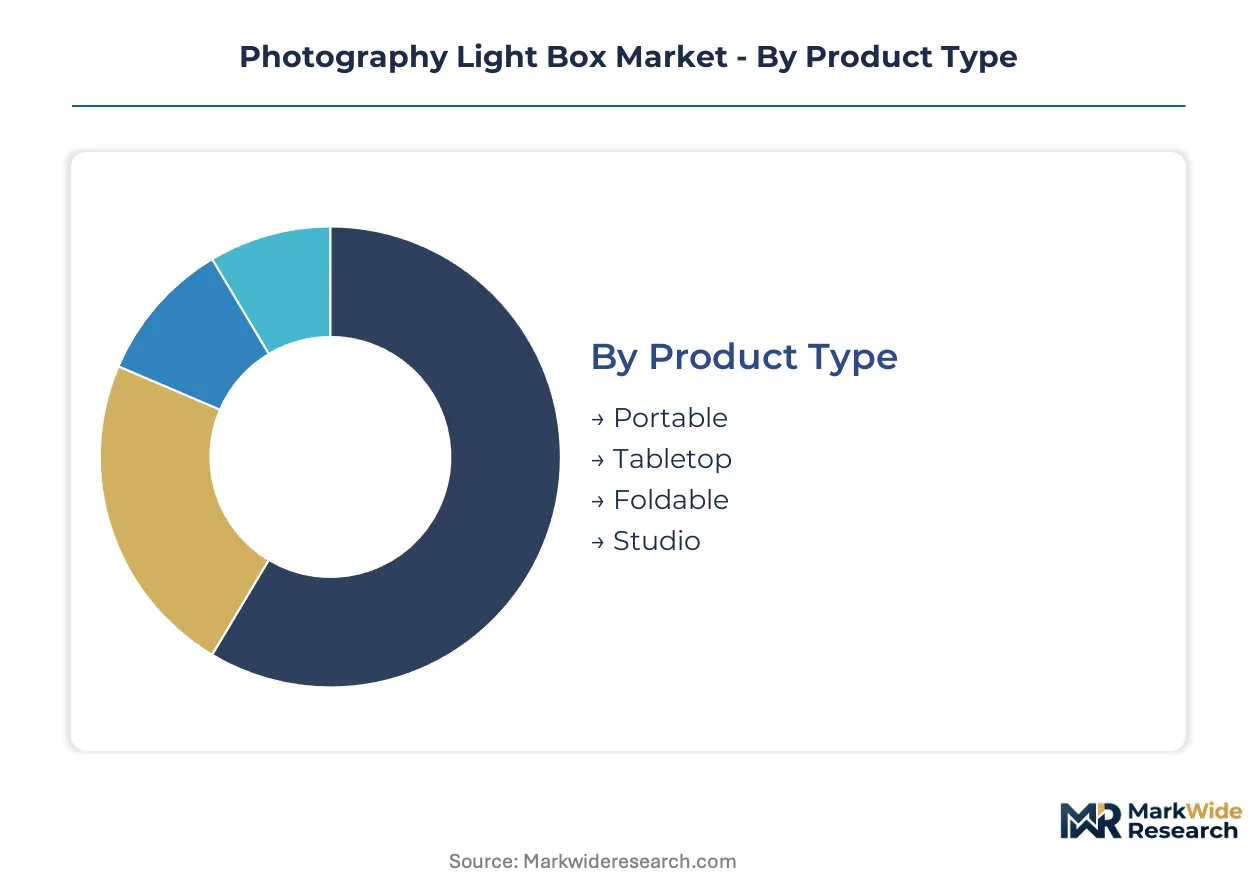
Photography light box segmentation separates casual content creators from commercial studios through mobility requirements, durability thresholds, and power infrastructure dependencies. Each category reflects distinct procurement patterns across Amazon seller ecosystems, professional tabletop operations, and field-deployable mobile workflows.
Product Type:
Buyers in this category separate by deployment mobility versus fixed installation requirements, with collapsible construction enabling remote content creation and metal framing serving permanent studio infrastructure.
- Portable:Collapsible fabric construction with USB power compatibility supports field-deployable mobile workflows. Amazon seller ecosystems in the United States drive replacement cycles as independent creators upgrade from smartphone-only setups to dedicated lighting chambers.
- Studio:Metal-framed units with AC power and dimmable output command premium positioning through durability specifications exceeding consumer thresholds. Commercial photography studios in Germany and the United States refresh these systems within eighteen-month cycles as chip-on-board LED arrays displace fluorescent legacy systems.
- Tabletop:Compact fixed-position units serve small-scale e-commerce operators with limited spatial footprints.
- Foldable:Hybrid construction balances portability with structural rigidity for semi-permanent installations.
Volume sits with portable configurations; growth tilts toward studio-grade systems as professional segments accelerate LED diffusion upgrades.
Material:
Cost tier and application durability separate buyers, with fabric dominating unit economics and metal sustaining pricing power in professional environments where equipment longevity determines total cost of ownership.
- Fabric:Lightweight diffuser panels enable collapsible construction for mobile deployment. EU REACH substance restrictions complicate sourcing as ECHA candidate list expansion forces reformulation of certain plasticizers and flame retardants.
- Metal:Chassis construction provides structural integrity for high-frequency commercial use. Certified material traceability commands price premiums of fifteen to twenty percent over uncertified alternatives in European markets.
- Plastic:Polycarbonate and ABS components reduce manufacturing costs for entry-level consumer segments.
- Glass:Tempered diffuser panels serve specialized macro photography requiring maximum light transmission clarity.
Economics favor fabric and plastic; durability premiums accrue to metal and glass in professional application tiers.
Size:
Subject scale and workspace constraints drive selection, with small formats serving jewelry and electronics while extra-large chambers accommodate furniture and industrial equipment photography.
- Small:Compact chambers rated for jewelry, watches, and consumer electronics components. Amazon marketplace sellers in the United States concentrate demand here for standardized product listing imagery.
- Large:Extended dimensions accommodate furniture, sporting goods, and industrial equipment. Live commerce streaming requirements in Chinese digital retail open dedicated hardware categories for real-time product demonstration.
- Medium:General-purpose dimensions serve apparel and home goods photography.
- Extra Large:Custom installations for automotive parts and commercial machinery documentation.
Transaction volume clusters in small and medium formats; expansion rates are steepest in large configurations as live commerce infrastructure scales.
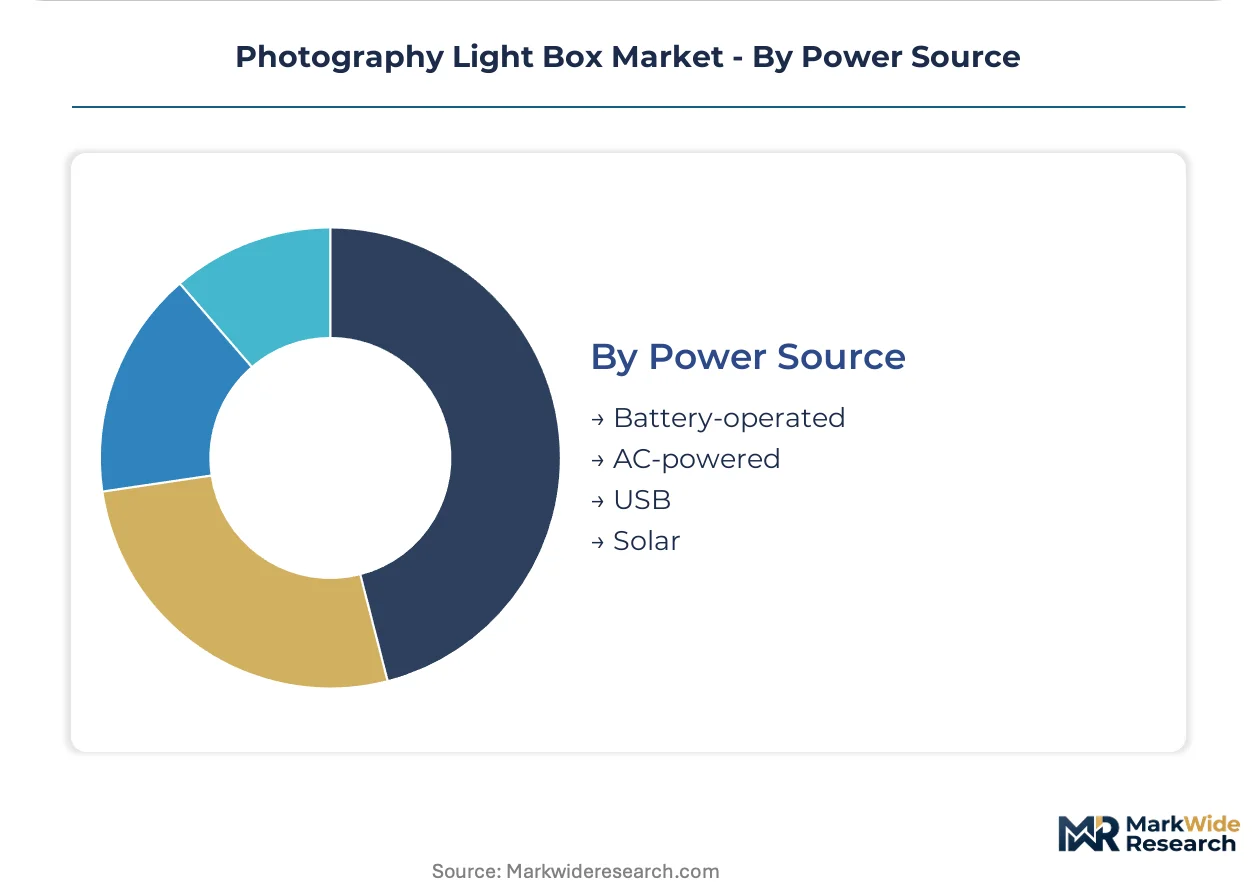
Power Source:
Energy infrastructure availability and field deployment requirements differentiate buyers, with USB compatibility enabling creator economy mobility and AC-powered systems serving fixed studio environments.
- USB:Low-voltage DC power compatibility supports laptop and power bank operation for location-independent workflows. California's Title 20 appliance efficiency regulations accelerate LED panel adoption against fluorescent alternatives in products sold into that state.
- AC-powered:Mains electricity connection delivers consistent output for professional studio environments. FCC electromagnetic emissions standards govern market access for units sold in the United States.
- Battery-operated:Integrated lithium-ion cells enable completely untethered operation for remote field deployment.
- Solar:Photovoltaic compatibility serves specialized applications in off-grid or sustainability-focused operations.
USB and AC sources dominate installed base; battery configurations are expanding most quickly as mobile content creation workflows proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen LED component manufacturing anchors supply-side concentration for photography light box assemblies worldwide, while demand fragmentation pulls finished equipment toward distinct regulatory and procurement environments across major consuming economies.
United States
Amazon seller ecosystems and independent creator economies in California and Texas drive replacement cycles for portable USB-powered units. FCC electromagnetic emissions standards govern AC-powered equipment market access, with California's Title 20 appliance efficiency regulations adding compliance layers for products sold into that state. Los Angeles commercial photography studios refresh studio-grade metal-framed systems within compressed eighteen-month cycles.
Germany
Commercial tabletop photography operations in Bavaria and North Rhine-Westphalia sustain premium positioning for chip-on-board LED arrays with certified material traceability. EU REACH substance restrictions under ECHA frameworks limit certain plasticizers in fabric diffuser materials, forcing reformulation of polycarbonate components. Berlin-based equipment distributors pre-qualify alternative thermoplastics to avoid authorization bottlenecks.
China
Live commerce streaming requirements in Shanghai and Hangzhou digital retail corridors open dedicated lighting hardware categories for real-time product demonstration. GB standards for LED lighting components create certification pathways for manufacturers serving domestic and export markets. Shenzhen manufacturing clusters control critical semiconductor supply for LED driver assemblies worldwide.
Japan
METI energy efficiency labeling requirements shape procurement specifications for professional studio operators in Tokyo and Osaka. Compact small-format chambers serve consumer electronics documentation needs for domestic e-commerce platforms. Nagoya industrial photography specialists demand tempered glass diffuser panels for specialized macro applications requiring maximum light transmission clarity.
United Kingdom
Shopify merchant ecosystems in London and Manchester concentrate demand for algorithmic procurement recommendations tied to photography service add-ons. CE marking requirements under RoHS frameworks govern battery-operated and AC-powered unit market access. Birmingham commercial studios adopt foldable hybrid construction for semi-permanent installations balancing portability with structural rigidity.
Photography Light Box Market Competitive Landscape
Global majors compete with regional champions across certification compliance and channel access dimensions, producing a tiered structure where scale-driven manufacturers face specialist challengers. Shenzhen-based production footprints control cost structures for volume segments, while European and North American players anchor premium positioning through material certification and studio relationships. Three archetypes dominate: integrated LED component manufacturers with captive supply chains, direct-to-consumer platform specialists, and professional-grade equipment houses serving commercial photography operations. Competitive moves concentrate on geographic expansion through e-commerce platform partnerships and portfolio diversification into adjacent lighting categories.
Within the integrated manufacturing tier, Godox leverages its Shenzhen production base to exemplify cost-structured competition across portable and studio-grade segments. Neewer occupies a position as the direct-to-consumer platform specialist, anchoring channel dominance on North American e-commerce marketplaces. Westcott represents the professional-grade archetype, sitting within sustained relationships with commercial photography studios in Germany and the United States.
| Leading Market Players |
|---|
| Godox |
| Neewer |
| Fovitec |
| LimoStudio |
| Savage Universal |
| Foldio |
| ESDDI |
| Westcott |
| Profoto |
| Others |
Value Network & Pricing Analysis
EU REACH substance candidate list expansion gates qualified supply for photography light box manufacturers serving European markets, with certified material traceability commanding fifteen to twenty percent premiums over uncertified alternatives and compressing margin pools for non-compliant producers.
Pricing Analysis
Warranty and calibration service bundling separates professional-grade studio equipment from unbundled portable consumer units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-marked metal-framed systems with material traceability anchor the top tier, while uncertified fabric collapsible units populate the entry level. Price differentiation hinges on after-sales service inclusion and calibration competency support. Cost compression in the portable segment intensifies as Shenzhen-based manufacturers flood direct-to-consumer channels, while commercial studios show lowest price sensitivity due to eighteen-month replacement cycles and durability requirements.
Supply Chain Analysis
CE marking and FCC electromagnetic emissions certification gate market access for finished units, with pre-qualification timelines extending product launches by four to six months. LED driver semiconductor supply concentrates in China, with Shenzhen manufacturing clusters controlling critical component flows for assemblies worldwide. Raw material dependencies span polycarbonate diffuser panels, aluminum chassis extrusions, and chip-on-board LED arrays. Single-source vulnerability in Chinese LED component manufacturing exposes price volatility and logistics disruption risk. Distribution runs through Amazon seller central and Shopify merchant ecosystems, with algorithmic procurement recommendations displacing traditional distributor roles in United States and United Kingdom corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where California Title 20 appliance efficiency regulations and EU REACH frameworks erect barrier-to-entry moats favoring producers with pre-qualified material pathways and multi-jurisdiction certification expertise.
For Market Incumbents: Cement channel control through exclusive algorithmic procurement partnerships with Amazon seller central and Shopify merchant ecosystems. Deepen backward integration into chip-on-board LED array production to capture margin pools previously diverted to fluorescent tube maintenance services. Threat response should prioritize modular, field-serviceable designs ahead of right-to-repair legislation expansion in European markets.
For New Entrants and Emerging Players: Live commerce streaming operators in Chinese and Southeast Asian digital retail represent an underserved buyer archetype with dedicated hardware requirements and limited incumbent penetration. White-space targets include subscription equipment access models for creator economy platforms and battery-operated configurations for completely untethered field deployment. Go-to-market execution should leverage direct platform integration bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Shenzhen manufacturing cluster consolidation announcements are the leading indicator that captive supply chain control is becoming the dominant competitive moat. Long-term viability across the analysis window favors integrated LED component manufacturers with in-house driver semiconductor sourcing over pure-play assemblers. Acquisition target archetype: mid-cap specialists with GB standard certification and established relationships with Hangzhou live commerce infrastructure providers. Signal to monitor: ECHA candidate list expansion velocity affecting polycarbonate diffuser panel reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver Manufacturing | Shenzhen semiconductor captive supply eliminates price volatility exposure from single-source clusters. |
| Multi-Jurisdiction Certification Pre-Qualification | Simultaneous FCC, CE, and GB compliance compresses launch windows against four-to-six-month timelines. |
| Platform-Native Distribution Partnership | Amazon seller central algorithmic placement displaces traditional distributor margin extraction. |
| Modular Field-Serviceable Design Transition | Right-to-repair legislation in European markets creates first-mover advantage for serviceable LED panels. |
| Live Commerce Hardware Category Development | Real-time streaming requirements in Shanghai digital retail open dedicated equipment procurement channels. |
Research Methodology
Document review covered SEC filings of lighting equipment manufacturers, customs and trade flow databases for LED component imports, and ECHA substance restriction notifications, complemented by interviews with commercial photography studio operators, Amazon seller ecosystem merchants, Shenzhen manufacturing cluster procurement leads, and EU regulatory compliance consultants. Secondary validation drew from FCC equipment authorization databases, CE marking registries, and platform seller central analytics disclosures. Bottom-up demand estimation across portable, studio, and tabletop segments was triangulated against top-down supply-side capacity assessments from Chinese LED component manufacturing clusters.
Cross-referencing historical refresh cycle patterns with panel input from studio equipment distributors established baseline assumptions across the projection horizon. Segmentation dimensions modeled include product type mobility tier, material durability grade, size format, and power source infrastructure dependency. CAGRs were derived from weighted scenario analysis incorporating e-commerce image standard tightening velocity and live commerce streaming infrastructure buildout rates. Industry-specific forecast inputs encompassed California Title 20 compliance adoption curves and EU REACH substance list expansion trajectories.
Revisions become necessary when LED driver semiconductor supply disruptions, REACH authorization bottlenecks, or platform algorithm changes materialize beyond baseline assumptions. Forecasts reflect documented assumptions regarding replacement cycle compression and regulatory compliance cost trajectories. A model refresh is warranted upon material change in Shenzhen manufacturing cluster consolidation patterns or right-to-repair legislation implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Gesture Control Light Market
Lighting
Plasma Lighting Market
Lighting
Display Light Control Film Market
Lighting
Solar Column Headlight Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Dimmer and Color Tunable Market
Lighting
Solar Lights Market
Lighting
Global Lighting Control System Market
Lighting
Industrial Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Battery Operated Lights Market
Lighting
Directional Luminaire Market
Lighting
Smart Street Lighting Systems Market
Lighting
Street Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Lighting Market