
 Graphic LCD Modules Market | 2026-2036
Graphic LCD Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Graphic LCD Modules Market Analytics
Software-defined brightness calibration and remote firmware update subscriptions are recalibrating how display module vendors monetize hardware deployments. Winstar Display leverages captive driver IC design to sustain margin control across industrial temperature-grade panels. Vishay anchors its position through stringent qualification protocols for avionics and military applications. Newhaven Display competes aggressively on small-batch customization velocity for medical instrument OEMs.
Graphic LCD modules are electro-optical display assemblies incorporating liquid crystal material sandwiched between glass substrates with patterned transparent electrodes, typically operating at voltages between 3.3V and 5V and requiring dedicated driver/controller integrated circuits to render pixel-mapped graphics. These modules serve as human-machine interfaces in equipment where alphanumeric readouts prove insufficient for complex data visualization. TFT active matrix technology dominates value capture due to superior response times and color fidelity, while passive matrix STN configurations retain cost advantages in monochrome utility metering. LED backlit variants command premium positioning as equipment OEMs phase out CCFL illumination to satisfy energy efficiency mandates.
RoHS and REACH frameworks in Europe restrict hazardous substance content in display assemblies, compelling reformulation of solder materials and backlight phosphors. The FCC in the United States enforces electromagnetic emission limits that shape PCB layout and shielding requirements for modules deployed in computing peripherals. ISO 13485 medical device quality management influences supplier qualification protocols for diagnostic equipment manufacturers. Stakeholders must monitor divergence between regional substance restrictions and emerging e-waste recovery obligations to avoid stranded inventory in international supply chains.
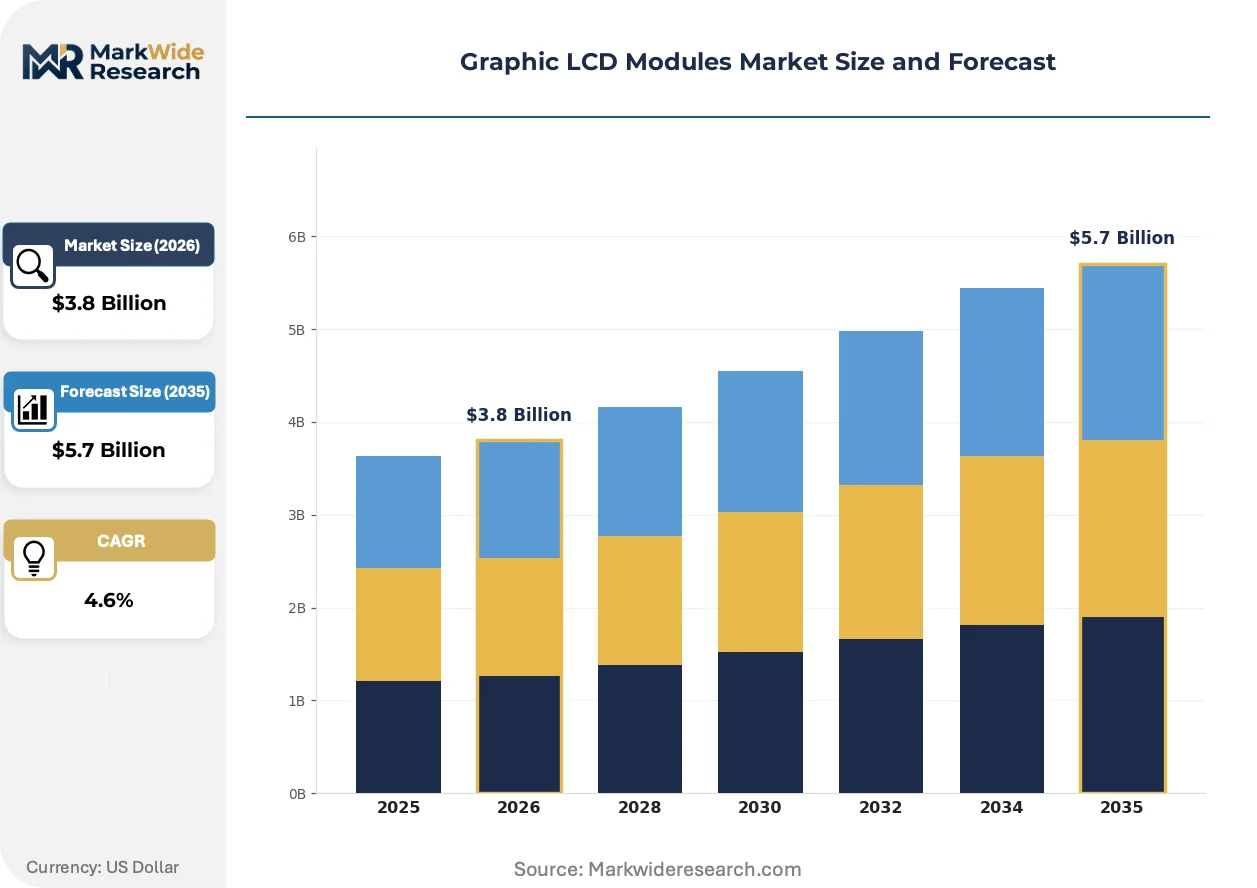
Market Dynamics
Mercury-free LED backlit designs are compressing CCFL supply chains as European REACH and RoHS enforcement hardens, forcing module assemblers in Shenzhen and Taipei to retool phosphor sourcing and solder formulations simultaneously.
Growth Catalysts
- Industrial automation controllers:German, Japanese, and American factory equipment OEMs are expanding procurement of medium-format TFT modules for operator interface panels.
- REACH and RoHS frameworks:European substance restrictions are accelerating the phase-out of mercury-containing backlight systems across display module imports.
- East Asian manufacturing clusters:Shenzhen and Taipei concentrate module assembly and driver IC integration at scale, reducing lead times for global equipment builders.
Market Restraints
- Driver IC supply concentration:Foundry capacity for industrial temperature-grade controller silicon concentrates among Taiwanese and South Korean semiconductor fabricators.
- Indium tin oxide cost volatility:Transparent electrode material prices fluctuate with rare earth export quotas from Chinese mining operations.
- Passive matrix substitution ceiling:STN monochrome configurations face displacement limits in utility metering where color fidelity offers marginal operational value.
Strategic Opportunities
- Medical instrument OEMs:Diagnostic equipment manufacturers under ISO 13485 protocols seek qualified suppliers for small-batch customized panel configurations.
- Avionics qualification pathways:Stringent FAA and EASA certification requirements create defensive moats for vendors willing to absorb extended validation timelines.
- Software-defined brightness calibration:Remote firmware update subscriptions enable recurring revenue attachment to hardware deployments in distributed industrial settings.
Industry Challenges
- Industrial temperature-grade validation:Extended thermal cycling certification for -40°C to +85°C operation stretches product development timelines.
- Legacy interface compatibility:New TFT modules must maintain signal compatibility with existing 8080 and 6800 parallel bus architectures in deployed equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphic LCD Modules Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded, TFT, STN, FSTN End User: Consumer Electronics, Automotive, Industrial Equipment, Medical Devices Technology: Passive Matrix, Active Matrix, LED Backlit, Touch Screen Size: Small, Medium, Large, Extra Large |
| Companies Covered | Winstar Display, Newhaven Display, Shen Zhen Raylid Electronic, Lumex, Microtips Technology, Varitronix, Displaytech, Vishay, Hantronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphic LCD Modules Market Evolving Landscape
Active matrix addressing architectures are compressing response time specifications across industrial display procurement, while regulatory substance bans and service model unbundling reshape how vendors capture lifetime value from hardware deployments.
Mercury-free LED backlighting is overtaking CCFL illumination in medium-format industrial panels. Equipment OEMs serving European markets are specifying LED backlit variants exclusively to preempt REACH enforcement actions. This transition is compressing phosphor supply chains and eliminating ballast component requirements from module bill-of-materials.
REACH substance restrictions are forcing reformulation of solder materials and backlight phosphors across display assemblies imported into European customs territories. The ECHA authorization list now captures several legacy phosphor compounds previously standard in CCFL manufacturing. Module assemblers in East Asia are responding by qualifying alternative rare-earth dopants and lead-free solder alloys for European-bound production lines.
Remote firmware update subscriptions are displacing one-time hardware transactions in industrial display procurement. Equipment builders in Germany and the United States are negotiating service attachments that bundle brightness calibration and driver updates over multi-year contracts. This behavioral shift concentrates vendor selection around software capability rather than unit manufacturing cost alone.
Graphic LCD Modules Market Segmentation
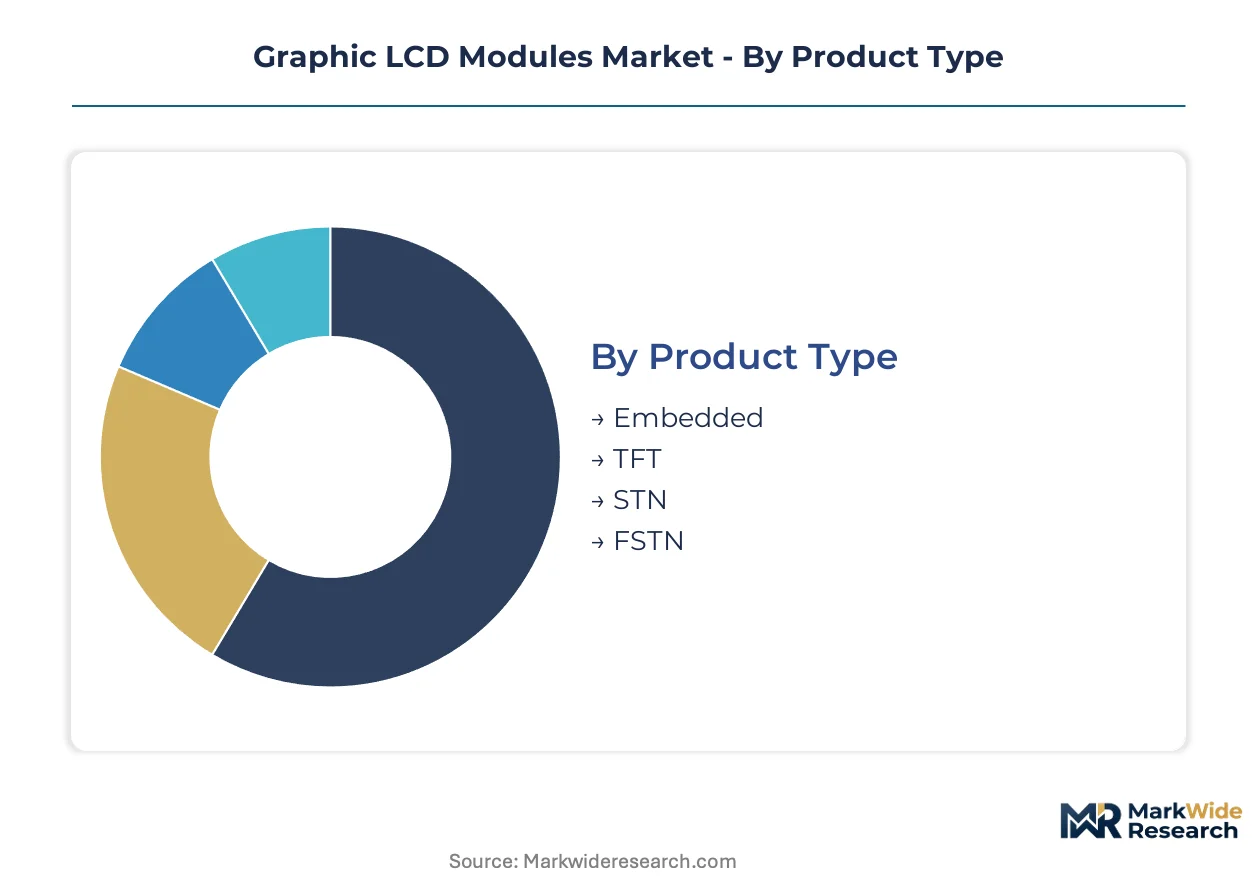
Graphic LCD module procurement patterns diverge sharply across certification regimes, with industrial and medical applications demanding ISO 13485 and extended temperature validation that consumer-grade deployments bypass entirely. Understanding which segments carry which compliance burdens allows suppliers to align R&D spend with margin-protected niches.
Product Type:
TFT and embedded configurations face the steepest certification requirements, with avionics and military applications demanding DO-160G environmental testing that STN and FSTN variants rarely encounter.
- TFT:Active matrix thin-film transistor technology delivers superior response times and color fidelity through individual pixel addressing. German and Japanese factory automation OEMs concentrate procurement of medium-format TFT modules for operator interface panels, driven by REACH-mandated mercury-free LED backlighting transitions.
- Embedded:Integrated controller-driver architectures reduce host processor overhead in resource-constrained equipment designs. Medical device manufacturers under FDA and EMA jurisdictions specify embedded variants for diagnostic equipment, prioritizing ISO 13485-qualified supply chains over unit cost minimization.
- STN:Super-twisted nematic passive matrix configurations retain cost advantages in monochrome utility metering applications with limited color requirements.
- FSTN:Film-compensated super-twisted nematic technology improves contrast ratio and viewing angle performance for industrial handheld terminals.
TFT sits at the top of the volume ranking, with embedded climbing the fastest as equipment OEMs consolidate display and control electronics.
End User:
Cost tier stratification separates military-aerospace qualification pathways from high-volume consumer electronics procurement, with medical and industrial segments occupying intermediate price-performance positions.
- Industrial Equipment:Factory automation controllers, process instrumentation, and HMI terminals demand -40°C to +85°C operating ranges with extended thermal cycling certification. Shenzhen and Taipei assemblers concentrate module production for this segment, leveraging proximity to driver IC foundries in Taiwan and South Korea.
- Medical Devices:Diagnostic imaging equipment, patient monitors, and surgical displays require ISO 13485 quality management and biocompatibility assessments. Small-batch customization velocity distinguishes qualified suppliers, with FDA 510(k) and EMA MDR submissions stretching supplier validation timelines.
- Automotive:Dashboard displays and center-stack modules face AEC-Q100 component qualification and EMC suppression requirements under NHTSA and UNECE regulations.
- Consumer Electronics:High-volume, short-lifecycle applications prioritize unit manufacturing cost over extended temperature specifications or decade-long supply guarantees.
Industrial Equipment commands the highest average selling prices, with Medical Devices gaining share fastest as diagnostic equipment OEMs reshore critical display supply chains.
Technology:
Manufacturing maturity separates legacy passive matrix architectures from emerging touch-integrated designs, with LED backlit variants displacing CCFL illumination across all volume tiers.
- Active Matrix:Individual thin-film transistor switching at each pixel enables high-resolution, fast-refresh displays for complex data visualization. FCC electromagnetic emission limits in the United States shape PCB layout and shielding requirements for active matrix modules deployed in computing peripherals.
- LED Backlit:Mercury-free illumination architectures satisfy European REACH and RoHS enforcement, eliminating ballast components from module bill-of-materials. ECHA authorization list restrictions on legacy phosphor compounds force East Asian assemblers to qualify alternative rare-earth dopants.
- Passive Matrix:Multiplexed row-column addressing suffices for static alphanumeric and simple graphic content in cost-sensitive utility applications.
- Touch Screen:Projected capacitive and resistive overlay integration adds human-machine interface functionality without separate input device procurement.
LED Backlit dominates shipment volumes, with Touch Screen expanding most quickly as equipment OEMs consolidate input and display functions.
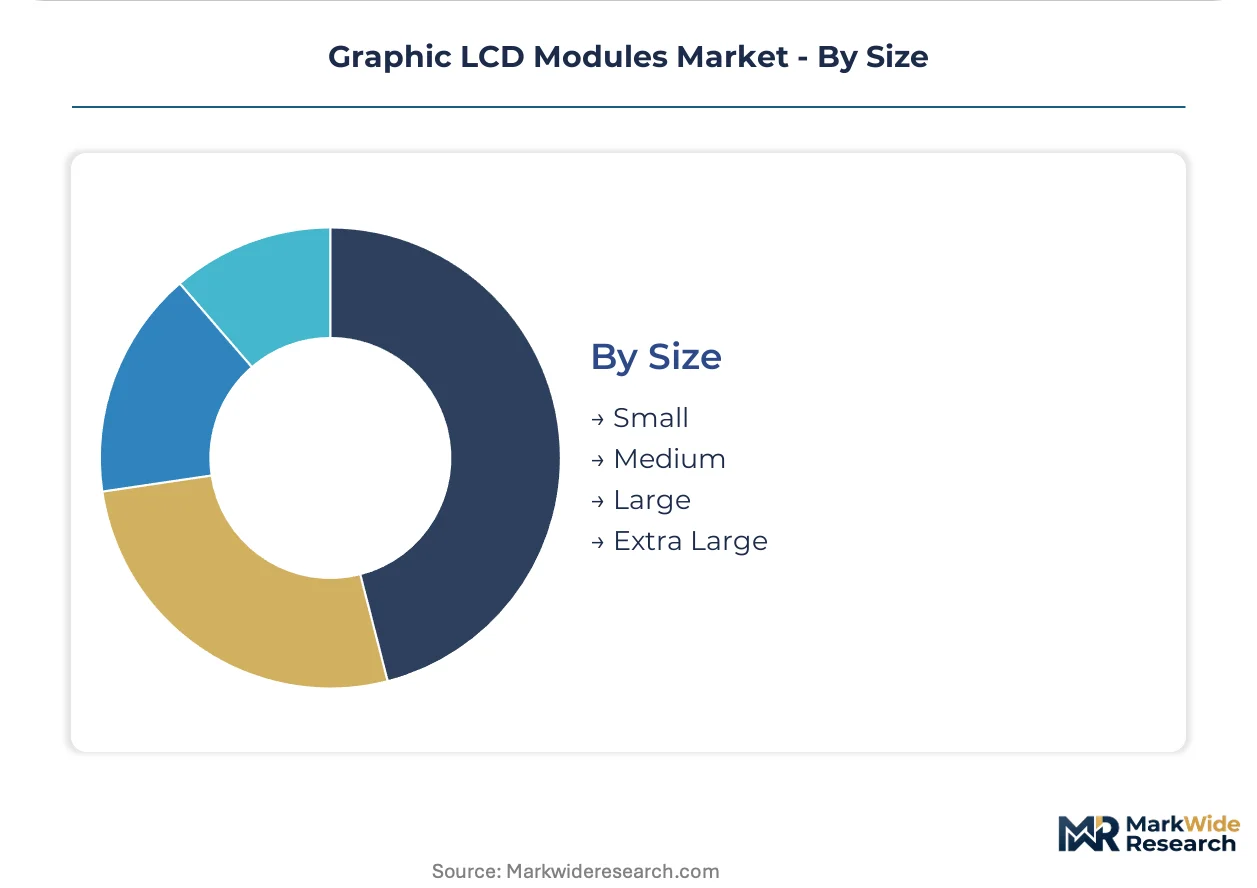
Size:
Supply chain concentration varies with format scale, with small and medium modules assembling in high-mix Shenzhen facilities while extra-large formats require specialized glass substrate handling.
- Medium:5-inch to 10-inch diagonal formats balance information density with panel cost in industrial HMI and medical monitor applications. German automation OEMs specify medium-format TFT modules exclusively for new operator interface designs, phasing out smaller legacy formats.
- Small:Sub-5-inch configurations serve handheld instrumentation, portable medical devices, and compact automotive clusters where physical envelope constraints dominate specification.
- Large:10-inch to 15-inch diagonal panels address process control stations and bedside monitoring equipment requiring simultaneous multi-parameter display.
- Extra Large:Above-15-inch formats concentrate in specialized medical imaging and industrial SCADA applications with limited volume but premium pricing.
Medium formats lead unit shipments, with Large gaining traction fastest as diagnostic equipment manufacturers specify bigger panels for image-intensive modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing Graphic LCD module assembly toward jurisdictions where REACH and RoHS compliance costs least to implement, while end-user demand concentrates in German factory automation, American medical devices, and Japanese precision instruments.
United States
Medical device OEMs in Minnesota and California drive procurement of ISO 13485-qualified embedded modules for diagnostic imaging equipment. FDA 510(k) submission requirements stretch supplier validation timelines, favoring vendors with established quality management systems. Boston and San Diego clusters concentrate design-in activity for surgical displays and patient monitoring systems.
Germany
Factory automation controllers in Bavaria and North Rhine-Westphalia specify medium-format TFT modules exclusively for new HMI terminal designs. REACH enforcement through ECHA authorization lists accelerates mercury-free LED backlight transitions. Stuttgart and Munich engineering centers coordinate specification standards across Siemens, Bosch, and Festo supply chains.
Japan
Precision instrument manufacturers in Tokyo and Osaka demand extended temperature-grade validation for industrial handheld terminals. METI energy efficiency guidelines shape backlight power specifications. Nagoya automotive clusters integrate graphic modules into dashboard displays under AEC-Q100 component qualification protocols.
China
Shenzhen and Taipei concentrate module assembly and driver IC integration at scale, leveraging proximity to Taiwanese foundry capacity. GB standards and emerging dual carbon goals from MEE push domestic OEMs toward LED backlit variants. Dongguan facilities retool phosphor sourcing to satisfy European import requirements.
South Korea
Display driver IC foundries in Gyeonggi-do supply industrial temperature-grade silicon to module assemblers across East Asia. MFDS medical device regulations create parallel qualification pathways for diagnostic equipment exports. Seoul-based electronics conglomerates backward-integrate into captive module production for internal consumption.
Graphic LCD Modules Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive driver IC design conferring margin protection in industrial temperature-grade panels. The vendor base organizes around three strategic archetypes: integrated semiconductor-display houses, pure-play module assemblers, and qualification-heavy avionics specialists. Consolidation pressure operates through foundry capacity allocation rather than horizontal merger activity, while geographic proximity to driver IC supply emerges as the dominant competitive variable.
Among Taiwan and China-based fabricators, Winstar Display and Shen Zhen Raylid Electronic occupy positions emphasizing scale and customization velocity respectively. Vishay sits within the qualification-intensive tier, representing vendors who absorb extended validation timelines for defensive positioning in aerospace and medical segments. Newhaven Display exemplifies the small-batch specialization archetype serving diagnostic instrument OEMs with rapid configuration turnaround.
| Leading Market Players |
|---|
| Winstar Display |
| Newhaven Display |
| Shen Zhen Raylid Electronic |
| Lumex |
| Microtips Technology |
| Varitronix |
| Displaytech |
| Vishay |
| Hantronix |
| Others |
Value Network & Pricing Analysis
Captive driver IC design anchors both supply position and pricing power for industrial-grade panel vendors. Winstar Display and Taiwan-based competitors leverage in-house semiconductor capabilities to defend margin structures against Shenzhen assemblers competing on customization velocity alone.
Pricing Analysis
Distributor margins compress as direct-to-OEM contracts expand across German and Japanese factory automation procurement. Three-tier pricing structure across industrial-temperature, medical-grade, and commercial-grade certifications separates qualified suppliers from commodity assemblers. Cost compression in medium-format TFT modules intensifies as REACH-mandated LED backlight transitions eliminate ballast component differentiation. Medical device OEMs exhibit lowest price sensitivity, prioritizing ISO 13485 qualification and FDA submission support over unit cost minimization.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given the embedded nature of industrial display deployments, with end-of-life management concentrated in e-waste recovery obligations under emerging European frameworks. Manufacturing concentrates in China, Taiwan, and South Korea, with Shenzhen module assembly drawing from Taiwanese foundry capacity for industrial temperature-grade driver silicon. Indium tin oxide for transparent electrodes and rare-earth phosphors for LED backlights anchor raw material dependencies. Single-source vulnerability in driver IC foundry allocation represents the dominant supply risk. Distribution runs through direct OEM contracts for qualified medical and industrial segments, with distributor channels serving lower-volume instrumentation buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as diagnostic equipment OEMs reshore critical display supply chains toward ISO 13485-qualified vendors with proven FDA submission track records.
For Market Incumbents: Lock in driver IC foundry allocation through multi-year wafer agreements before capacity tightens further. Deepen certification moats by accelerating DO-160G environmental testing investment for avionics qualification pathways. Threat of emerging Chinese assemblers with state-backed capital requires defensive positioning through captive semiconductor design rather than cost-matching. For New Entrants and Emerging Players: Small-batch medical instrument OEMs represent the most penetrable buyer archetype currently underserved by volume-focused Taiwan fabricators. Target diagnostic equipment manufacturers requiring rapid customization turnaround for FDA 510(k) submissions. Geographic white space exists in European-bound production with qualified REACH-compliant solder and phosphor formulations. Go-to-market leverage centers on software-defined brightness calibration subscriptions bundled with hardware. For Investors and Strategic Acquirers: Roll-up economics work for qualification-heavy avionics specialists because FAA and EASA certification timelines create defensive barriers that scale across acquired customer relationships. Long-term viability favors vendors with backward integration into driver IC design and established medical device quality management systems. Signal to watch is foundry capacity reallocation toward automotive-grade silicon squeezing industrial temperature-grade availability.| Strategic Initiative | Industry Significance |
|---|---|
| Driver IC Foundry Capacity Lock-in | Wafer agreements with TSMC or UMC secure industrial temperature-grade silicon allocation against automotive competition. |
| REACH-Compliant Phosphor Qualification | Alternative rare-earth dopant sourcing satisfies ECHA authorization requirements for European-bound production lines. |
| ISO 13485 Quality System Investment | FDA submission support capabilities attract diagnostic equipment OEMs reshoring critical display supply chains. |
| Remote Firmware Subscription Launch | Brightness calibration service attachments transform one-time hardware transactions into recurring revenue streams. |
| Avionics DO-160G Certification Pathway | Environmental testing investment creates defensive positioning in aerospace and military procurement with extended validation timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from display module procurement managers at German automation OEMs, biomedical engineers at diagnostic equipment manufacturers, Taiwanese foundry planning officers, and Shenzhen assembly facility operations heads. Secondary validation drew from SEC 10-K filings of listed semiconductor houses, ECHA substance restriction updates, FDA 510(k) submission databases, and customs trade records for display module imports. Bottom-up build of segment volumes triangulated against top-down industry value estimates.
Segment-weighting across the projection horizon applied differential growth assumptions by technology architecture, certification tier, and end-use concentration. Modeling dimensions included product type, end user vertical, backlight technology, and size format. CAGRs derived from historical shipment trajectories adjusted for regulatory transition timelines and foundry capacity expansion schedules. Forecast inputs incorporated REACH enforcement intensity scenarios and medical device reshoring momentum indicators.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time foundry utilization data introduce uncertainty bands around industrial temperature-grade supply assumptions. Forecasts reflect documented assumptions regarding LED backlight transition velocity and driver IC allocation priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Touch Screen Display Market
Display Technologies
Smart Screen Market
Display Technologies
Low Power Display Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Industrial Display Market
Display Technologies
Head Up Display Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Mono LCD Displays Market
Display Technologies
Global OLED Market