
 Smartphone Display Market | 2026-2036
Smartphone Display Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Display Market Intelligence
The capital-intensity divergence between Gen-8.6 OLED fab operators and legacy LCD panel producers is reorganizing competitive tiers in smartphone display supply. Samsung Display sustains technology leadership through captive LTPO and foldable OLED pipelines. BOE Technology Group leverages state-backed financing to expand Gen-6 flexible OLED capacity for Apple and domestic Android OEMs. Tianma specializes in LTPS LCD and rigid OLED segments for mid-tier handset brands.
A smartphone display is an optoelectronic output device comprising thin-film transistor backplanes, organic or liquid-crystal emissive layers, polarizers, and cover glass, manufactured through photolithography, chemical vapor deposition, and encapsulation processes to render visual interfaces for handheld computing devices. AMOLED panels command premium pricing in flagship tiers due to self-emissive architecture enabling always-on functionality and under-display biometric integration. The 6-7 inch screen size bracket anchors volume shipments as OEMs standardize phablet form factors across mid-range and premium portfolios. LCD retains cost-sensitive segments where procurement from mobile OEMs prioritizes bill-of-material compression over contrast ratio performance.
REACH restrictions on hazardous substances in electronics, EU Ecodesign energy-efficiency requirements, and China's GB standards for display power consumption collectively tighten material specifications and drive low-temperature polysilicon adoption. South Korea's METI-aligned industrial policy and China's MIIT domestic substitution mandates are accelerating regional supply chain decoupling. Stakeholders must monitor LTPO penetration rates and Gen-8.6 OLED yield trajectories to calibrate capacity commitments against OEM refresh cycle timing.
Market Dynamics
LTPO backplane technology and EU Ecodesign energy-efficiency mandates are compressing refresh cycles and forcing mobile OEMs to consolidate supplier relationships around Gen-6 and Gen-8.6 OLED clusters in South Korea and China.
Growth Catalysts
- EU Ecodesign Framework:Power-efficiency mandates are accelerating low-temperature polysilicon adoption across flagship smartphone portfolios.
- Flexible OLED Architecture:Self-emissive layers enable always-on displays and under-display biometric integration for premium handset differentiation.
- Gen-8.6 OLED Fabs:Capacity expansion near component ecosystems in South Korea and China is shortening procurement lead times for mobile OEMs.
Market Restraints
- Input Cost Volatility:Indium tin oxide and rare-earth phosphor prices swing with mining output from concentrated geographies.
- Supply Concentration Risk:Gen-6 and Gen-8.6 OLED capacity clusters in South Korea and China expose procurement to regional trade policy shifts.
- Technical Yield Limitations:Foldable OLED panel manufacturing suffers higher defect rates than rigid substrates, constraining volume economics.
Strategic Opportunities
- Underpenetrated India Market:Domestic smartphone assembly growth creates demand for mid-tier AMOLED panels as local brands upgrade from LTPS LCD.
- Automotive Display Convergence:LTPO backplane expertise transfers to curved cockpit displays, opening adjacent revenue for panel specialists.
- China MIIT Substitution Mandates:Domestic procurement quotas for government and state-enterprise handsets favor local OLED suppliers.
Industry Challenges
- Capex Intensity:Gen-8.6 OLED fabs require multi-billion-dollar photolithography and chemical vapor deposition equipment commitments.
- Skill Gap in Encapsulation:Thin-film barrier deposition for flexible substrates demands specialized cleanroom technicians scarce outside established clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Display Market |
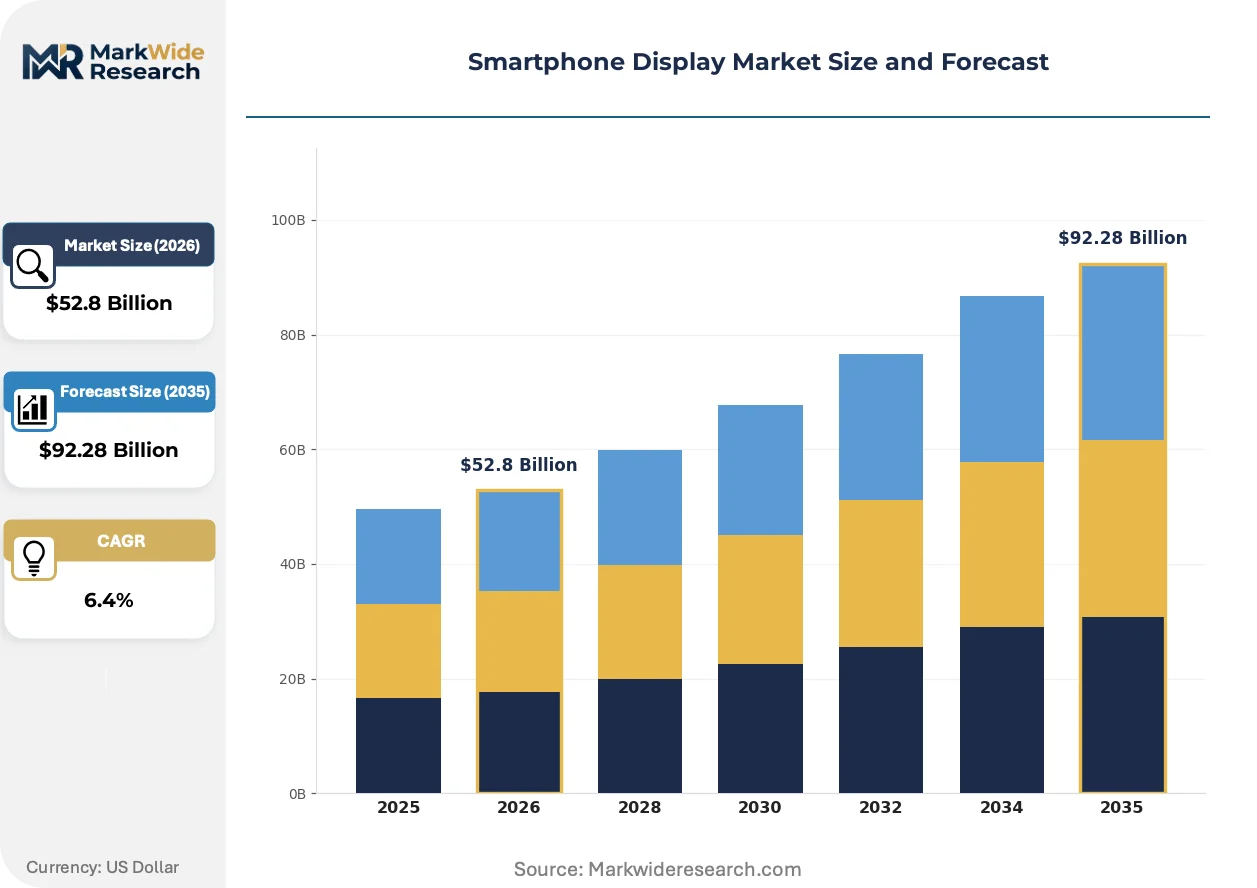
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Display Technology: LCD, OLED, AMOLED, IPS, TFT, E Ink Screen Size: Below 5 inches, 5-6 inches, 6-7 inches, Above 7 inches Resolution: HD, Full HD, Quad HD, 4K, WXGA End User Type: Mobile OEMs, Tier-1 Suppliers, Refurbishers, Aftermarket Providers |
| Companies Covered | CSOT (China Star Optoelectronics Technology), Visionox Technology, BOE Technology Group, Sharp Corporation, Japan Display Inc., Samsung Display, Tianma, TCL Technology, LG Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Display Market Strategic Shifts & Innovations
Display technology roadmaps are diverging between premium flexible OLED stacks and cost-optimized LTPS LCD alternatives, with regulatory pressure and form-factor innovation pulling development in opposing directions.
LTPO backplane technology is fragmenting the flagship smartphone segment between power-optimized premium tiers and standard LTPS-equipped mid-range devices. Apple and Samsung Electronics have integrated LTPO into their highest-end product lines, while domestic Chinese OEMs adopt the technology selectively. This divergence is compressing margins for panel suppliers caught between efficiency mandates and volume demands.
REACH restrictions on hazardous substances in electronics are tightening material specifications for polarizers, substrates, and encapsulation layers across European-bound smartphone shipments. ECHA substance-of-very-high-concern listings now cover several legacy flame retardants and plasticizers common in display laminates. Panel suppliers are reformulating chemistries and accelerating qualification timelines to maintain CE marking compliance.
Mobile OEM procurement departments are consolidating supplier panels from six-plus vendors to three preferred partners per technology category. This concentration is displacing spot-market purchasing with multi-year capacity reservation agreements tied to yield guarantees. The shift is most visible among Chinese handset brands sourcing from domestic Gen-6 flexible OLED fabs.
Smartphone Display Market Segmentation
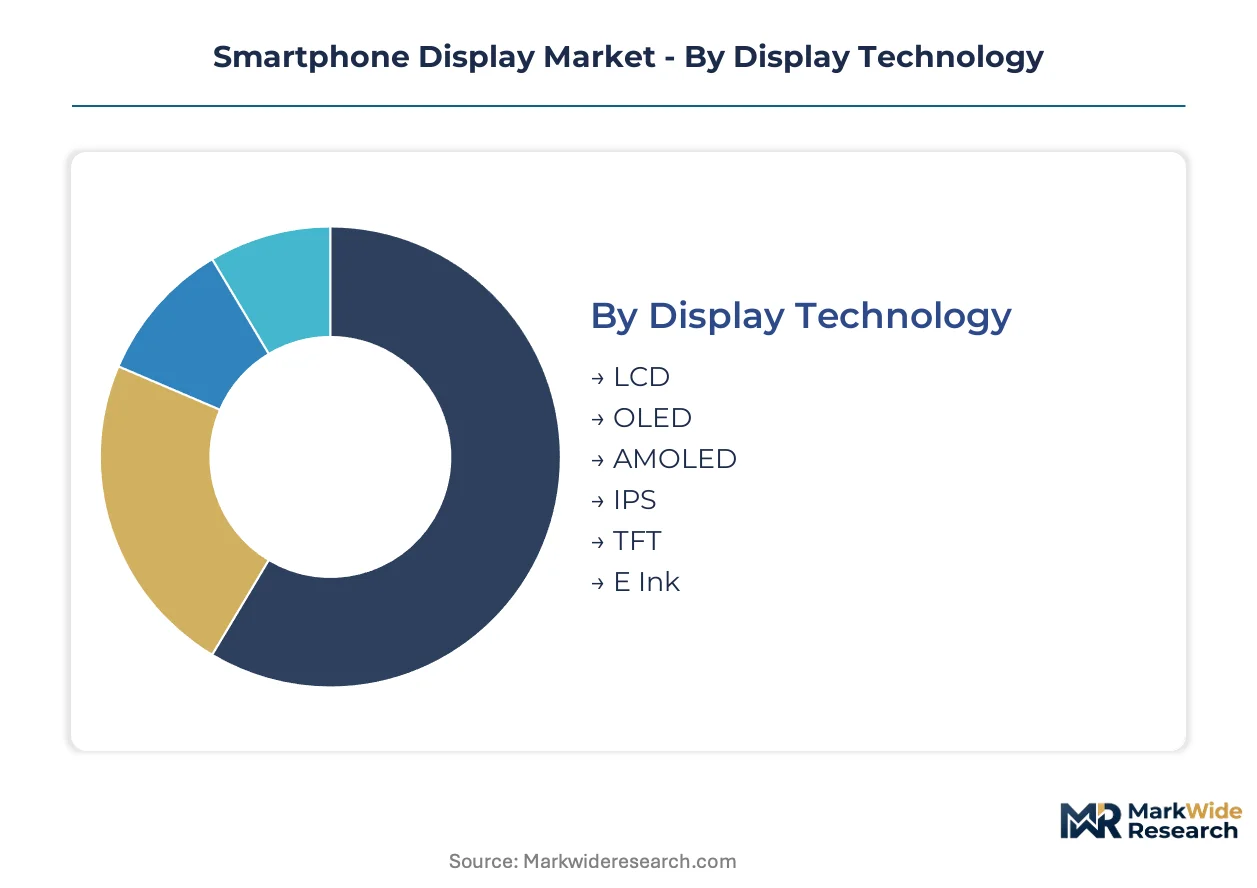
Smartphone display segmentation reveals how procurement power concentrates around specific technology-performance combinations. Panel suppliers calibrate fab output across these dimensions to match OEM refresh cycles and regional regulatory requirements.
Display Technology:
Margin pools concentrate in self-emissive architectures where power efficiency commands premium pricing from flagship OEMs.
- AMOLED:Active-matrix organic light-emitting diode stacks integrate thin-film transistor backplanes with self-emissive organic layers for always-on functionality. Samsung Electronics and Apple source AMOLED exclusively for flagship tiers where EU Ecodesign power mandates drive specification upgrades. Samsung Display and BOE Technology Group dominate capacity allocation.
- OLED:Organic light-emitting diode panels without active-matrix addressing serve mid-premium segments where cost-performance balance matters. Chinese domestic brands source OLED from local Gen-6 fabs near Shenzhen and Chengdu component clusters. MIIT domestic substitution quotas accelerate local procurement.
- LCD:Liquid-crystal display panels with external backlighting retain volume in cost-sensitive emerging markets. India domestic assembly operations source LCD for sub-premium handsets where bill-of-material compression outweighs contrast ratio demands.
- IPS:In-plane switching LCD variants deliver wider viewing angles for mid-tier devices prioritizing color accuracy over refresh rates.
- TFT:Thin-film transistor LCD backplanes serve entry-level smartphones with basic display requirements across African and Southeast Asian markets.
- E Ink:Bistable electrophoretic displays occupy niche auxiliary screen applications in experimental dual-screen form factors.
AMOLED holds installed capacity. OLED is rotating up the share rankings.
Screen Size:
Volume concentration follows OEM standardization on phablet form factors that maximize display area within hand-ergonomic limits.
- 6-7 inches:The dominant bracket where Samsung Electronics, Apple, and Xiaomi have converged flagship and mid-range portfolios. This diagonal range optimizes content consumption and battery housing while maintaining single-hand operability for most users. Gen-6 and Gen-8.6 OLED fabs target yield optimization at these dimensions.
- 5-6 inches:Legacy compact form factors retained by Apple for standard iPhone lines and select Android OEMs targeting ergonomic preferences. Panel suppliers maintain dedicated capacity lines for this shrinking volume segment.
- Below 5 inches:Diminishing category serving ruggedized industrial handsets and ultra-compact feature phones in price-sensitive geographies.
- Above 7 inches:Foldable and rollable experimental formats where Samsung Display and BOE Technology Group compete on mechanical durability. Technical yield limitations constrain volume economics.
6-7 inches anchors procurement volume. Above 7 inches is climbing the fastest as foldable adoption expands.
Resolution:
Specification differentiation tracks GPU capability advancement and streaming content availability across premium tiers.
- Full HD:1920x1080 pixel density serves as the practical standard for mid-range devices balancing clarity with power consumption. Chinese OEMs source Full HD AMOLED from domestic fabs for volume flagship lines.
- Quad HD:2560x1440 resolution dominates premium Android flagships where Samsung Electronics and OPPO compete on visual fidelity. LTPO backplane integration enables variable refresh rates at this pixel density.
- 4K:Ultra-high definition panels remain rare in smartphones due to power and cost constraints, appearing only in limited experimental devices.
- HD:1280x720 specification serves entry-tier devices in India and Southeast Asia where display cost dominates procurement decisions.
- WXGA:Wide extended graphics array format occupies niche tablet-phone hybrid devices with non-standard aspect ratios.
Full HD holds installed capacity. Quad HD is gaining share fastest as LTPO penetration deepens.
End User Type:
Procurement concentration reflects supply chain consolidation toward direct OEM relationships and away from spot-market intermediaries.
- Mobile OEMs:Brand manufacturers including Samsung Electronics, Apple, Xiaomi, and OPPO source directly through multi-year capacity reservation agreements. These stakeholders now consolidate supplier panels from six-plus vendors to three preferred partners per technology category.
- Tier-1 Suppliers:System integrators and module assemblers procure bare panels for integration with touch sensors and cover glass. South Korean and Chinese clusters near component ecosystems dominate this intermediary role.
- Refurbishers:Secondary market operators source replacement panels for device renewal programs, particularly active in European markets under circular economy directives.
- Aftermarket Providers:Independent repair networks and spare parts distributors serve out-of-warranty replacement demand with variable quality tiers.
Mobile OEMs hold installed capacity. Tier-1 Suppliers are rotating up the share rankings as vertical integration pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between South Korea and China is reshaping procurement patterns for mobile OEMs. South Korean suppliers command LTPO and foldable OLED premiums through captive technology pipelines. Chinese producers leverage state-backed financing to compress flexible OLED pricing for mid-tier volume segments.
South Korea
Samsung Electronics and domestic Android OEMs drive demand for LTPO AMOLED panels in flagship devices. METI-aligned industrial policy accelerates domestic substitution of Japanese component imports. Seoul-Suwong cluster concentrates Gen-6 and Gen-8.6 OLED fab capacity near component ecosystems.
China
Domestic brands Xiaomi, OPPO, and vivo source flexible OLED from local Gen-6 fabs for volume flagship lines. MIIT procurement quotas mandate domestic display sourcing for government and state-enterprise handsets. Shenzhen and Chengdu component clusters shorten procurement lead times for panel assemblers.
Japan
Sharp Corporation and Japan Display Inc. serve niche high-resolution LCD segments for industrial and automotive crossover applications. METI standards for display power consumption tighten material specifications for European-bound shipments. Chubu-Nagoya region maintains precision equipment supply chains for photolithography systems.
United States
Apple's procurement consolidation around three preferred panel partners per technology category drives multi-year capacity reservation agreements. FCC equipment authorization requirements shape display electromagnetic compatibility testing protocols. California design centers influence phablet form factor standardization across 6-7 inch screen sizes.
India
Domestic smartphone assembly growth creates demand for mid-tier AMOLED panels as local brands upgrade from LTPS LCD. BIS certification requirements for electronic components extend qualification timelines for new panel suppliers. Tamil Nadu and Karnataka manufacturing corridors attract display module integration facilities serving export markets.
Smartphone Display Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in the smartphone display supply base. The market structure concentrates around three to four dominant panel suppliers controlling LTPO and flexible OLED capacity, with tier-2 specialists occupying rigid OLED and high-specification LCD niches. Two strategic archetypes predominate: vertically integrated Korean conglomerates with captive semiconductor backplane capabilities, and Chinese state-supported enterprises scaling Gen-6 and Gen-8.6 fab output. Competitive moves center on multi-billion-dollar capacity expansion commitments and multi-year supply agreements tied to yield guarantees.
Within the technology-leadership tier, Samsung Display and BOE Technology Group anchor divergent geographic supply strategies. Samsung Display exemplifies the Korean conglomerate archetype with integrated LTPO and foldable OLED pipelines. BOE Technology Group represents Chinese state-backed scaling of flexible OLED capacity for Apple and domestic OEM procurement. Tianma occupies a specialist position in LTPS LCD and rigid OLED segments for mid-tier handset brands.
| Leading Market Players |
|---|
| CSOT (China Star Optoelectronics Technology) |
| Visionox Technology |
| BOE Technology Group |
| Sharp Corporation |
| Japan Display Inc. |
| Samsung Display |
| Tianma |
| TCL Technology |
| LG Display |
| Others |
Cost & Logistics Intelligence
Ninety-day procurement lead times for Gen-8.6 OLED panels concentrate pricing power with South Korean and Chinese suppliers, compressing margins for mobile OEMs locked into multi-year capacity agreements. This temporal rigidity reinforces cost premiums for LTPO backplane technology while state-backed financing in China undercuts flexible OLED pricing for mid-tier volume segments.
Pricing Analysis
The customization-premium spread between configured-to-order LTPO AMOLED and standard LTPS LCD panels spans three performance tiers. Contract-based long-term offtake agreements dominate flagship procurement, with price differentiation driven by backplane technology grade and EU Ecodesign certification compliance. Cost compression in mid-tier flexible OLED is intensifying because BOE Technology Group leverages state financing to expand Gen-6 capacity. Emerging market OEMs sourcing LCD panels exhibit highest price sensitivity, while Apple and Samsung Electronics accept premium positioning for foldable and LTPO-equipped flagships.
Supply Chain Analysis
South Korea and China anchor Gen-6 and Gen-8.6 OLED fabrication, with Taiwan supplying precision photolithography equipment and Japan providing polarizer substrates. The supply chain draws from indium tin oxide deposits concentrated in Chinese mining operations, rare-earth phosphor processing facilities in Inner Mongolia, and high-purity glass substrate manufacturing in Japan. Single-source vulnerability for LTPO backplane lithography systems creates chokepoint exposure. Distribution runs through direct OEM procurement departments consolidating supplier panels from six-plus vendors to three preferred partners per technology category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as LTPO penetration fragments procurement between power-optimized premium tiers and standard LTPS mid-range devices, creating specialist niches for rigid OLED and high-specification LCD suppliers.
For Market Incumbents: Secure LTPO yield guarantees through captive backplane semiconductor production, locking Apple and Samsung Electronics into exclusive multi-year agreements. Expand Gen-8.6 capacity near Seoul-Suwong component clusters to defend against Chinese state-subsidized pricing pressure. State-backed financing for BOE Technology Group expansion represents the primary margin threat requiring consolidation response.
For New Entrants and Emerging Players: CE marking fast-track qualification for REACH-compliant polarizer substrates opens procurement access to European-bound smartphone shipments. Target India domestic assembly corridors in Tamil Nadu and Karnataka where BIS certification requirements extend qualification timelines for established suppliers, creating entry windows for mid-tier AMOLED panel integration. Partner with local brands upgrading from LTPS LCD to capture volume flagship demand.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-concentration play because three to four dominant panel suppliers control LTPO and flexible OLED capacity with multi-billion-dollar fab commitments as moats. Acquisition targets should display specialist positioning in automotive display convergence or underpenetrated India module integration. Monitor Gen-8.6 OLED yield trajectories as the inflection signal for capacity commitment timing against OEM refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Gen-8.6 OLED Fab Capacity Expansion | Multi-billion-dollar photolithography commitments near Seoul-Suwong clusters shorten procurement lead times for Samsung Electronics and Apple. |
| LTPO Backplane Technology Licensing | Power-efficiency mandates from EU Ecodesign framework accelerate adoption across flagship tiers requiring variable refresh rate capability. |
| REACH-Compliant Material Reformulation | ECHA substance-of-very-high-concern listings drive chemistry qualification timelines for European-bound smartphone display shipments. |
| India Module Integration Facility Buildout | Tamil Nadu and Karnataka manufacturing corridors attract display assembly serving domestic brands upgrading from LTPS LCD. |
| Automotive Display Convergence Partnership | LTPO expertise transfers to curved cockpit displays for adjacent revenue at panel specialists like Tianma and Visionox Technology. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, and OEM procurement disclosures, validated through bottom-up and top-down triangulation. Primary interviews engaged display technology executives, mobile OEM procurement leads, semiconductor backplane engineers, and polarizer substrate chemists. Secondary sources included Samsung Display and BOE Technology Group capacity announcements, EU Ecodesign directive documentation, and ECHA REACH substance listings. This dual-track approach cross-validated yield estimates and pricing assumptions across the supply base.
Segmentation dimensions modeled include display technology architecture, screen size brackets, resolution tiers, and end-user procurement channels across the analysis window. CAGRs derive from capacity utilization trajectories at Gen-6 and Gen-8.6 OLED fabs, OEM refresh cycle timing, and regional regulatory adoption curves for power-efficiency mandates. Industry-specific inputs incorporate LTPO penetration rate assumptions and foldable OLED defect rate limitations affecting volume economics.
Underlying assumptions cover sustained EU Ecodesign enforcement, continued MIIT domestic substitution quotas in China, and stable indium tin oxide supply from concentrated mining geographies, with deviation risk concentrated in regional trade policy shifts and technical yield breakthroughs at Gen-8.6 facilities. Recalibration cycles align with material shifts in OEM procurement consolidation patterns and regulatory expansion of hazardous substance restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
Thin Display Technology Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Interactive Video Wall Market
Display Technologies
E-Paper Display Market
Display Technologies
Smartwatch Display Panel Market
Display Technologies
Display Control and Management System Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Electrochromic Window Market
Display Technologies
Automotive LCD Display Market