
 France Automotive OEM Coatings Market | 2026-2036
France Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive OEM Coatings Market Insights
Premium clear coat specifications is rotating toward higher solids and self-healing formulations as OEMs chase durability warranties. PPG Industries leverages its color-matching technology leadership to anchor major French assembly contracts. BASF SE sustains R&D intensity in waterborne base coat chemistry, while Axalta Coating Systems dominates the solvent-based segment through established OEM supply agreements.
France Automotive OEM Coatings are liquid or powder formulations applied to vehicle bodies during original manufacturing, typically comprising resin binders, pigments, and functional additives cured through thermal or ultraviolet processes to achieve corrosion resistance, aesthetic finish, and chip protection. The primary industrial purpose is to protect unibody and panel substrates while delivering brand-specific color and gloss consistency across high-volume production lines. Waterborne technology leads in new line installations due to regulatory pressure on solvent emissions, while powder coating occupies the fastest-growing niche in underbody and chassis applications where film-build efficiency matters most. Base coats command the deepest margin pools because color complexity drives formulation customization and technical service intensity.
REACH and the EU Green Deal constrain volatile organic compound thresholds across French automotive finishing, forcing reformulation investments and capital upgrades at coating operations. ANSM and CNIL oversight of chemical hazard classification intersects with ECHA substance authorization rules, creating layered compliance obligations for suppliers serving French OEM manufacturers. Stakeholders must monitor how the EU AI Act and emerging digital product passport requirements reshape traceability demands across coating supply chains.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's volatile organic compound restrictions are forcing simultaneous reformulation of base coat chemistry and capital upgrades across French OEM finishing lines, compressing supplier margins while accelerating waterborne technology substitution.
Growth Catalysts
- Electric vehicle production expansion:Stellantis plants in Hauts-de-France are commissioning dedicated coating lines for battery-electric platforms, creating demand for compatible primer and clear coat systems.
- REACH substance authorization:ECHA's tightening restrictions on chromium-based pretreatments are mandating zirconium and silane-based conversion coatings across French assembly operations.
- Film-build efficiency requirements:Powder coating technology is penetrating underbody and chassis applications where high-transfer efficiency and zero volatile organic compound emissions align with sustainability targets.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings constrain margin stability for white and pastel base coat formulations supplied to high-volume French OEM programs.
- Isocyanate supply concentration:Polyisocyanate hardener production clusters in German and Belgian chemical corridors, exposing French coaters to cross-border logistics disruptions and single-source risk.
- Self-healing clear coat technical limitation:Microcapsule-based scratch recovery formulations suffer from UV degradation and limited repair cycle durability, delaying warranty-backed OEM adoption.
Strategic Opportunities
- Occitanie region underpenetration:Sparse OEM assembly presence in southern France creates whitespace for supplier technical service centers targeting tier-1 component coaters.
- Digital product passport alignment:EU battery regulation traceability requirements are extending to coating chemistries, rewarding early movers with integrated supply chain data architectures.
- UV-cured powder convergence:Combination of ultraviolet cure speed with powder coating efficiency is opening energy-intensive clear coat operations to process redesign.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in waterborne resin synthesis and rheology control is concentrating at competitor R&D campuses in Germany and the Netherlands.
- Legacy solvent line stranding:Capital-intensive booth and oven infrastructure at older French plants resists retrofit for low-temperature waterborne cure cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive OEM Coatings Market |
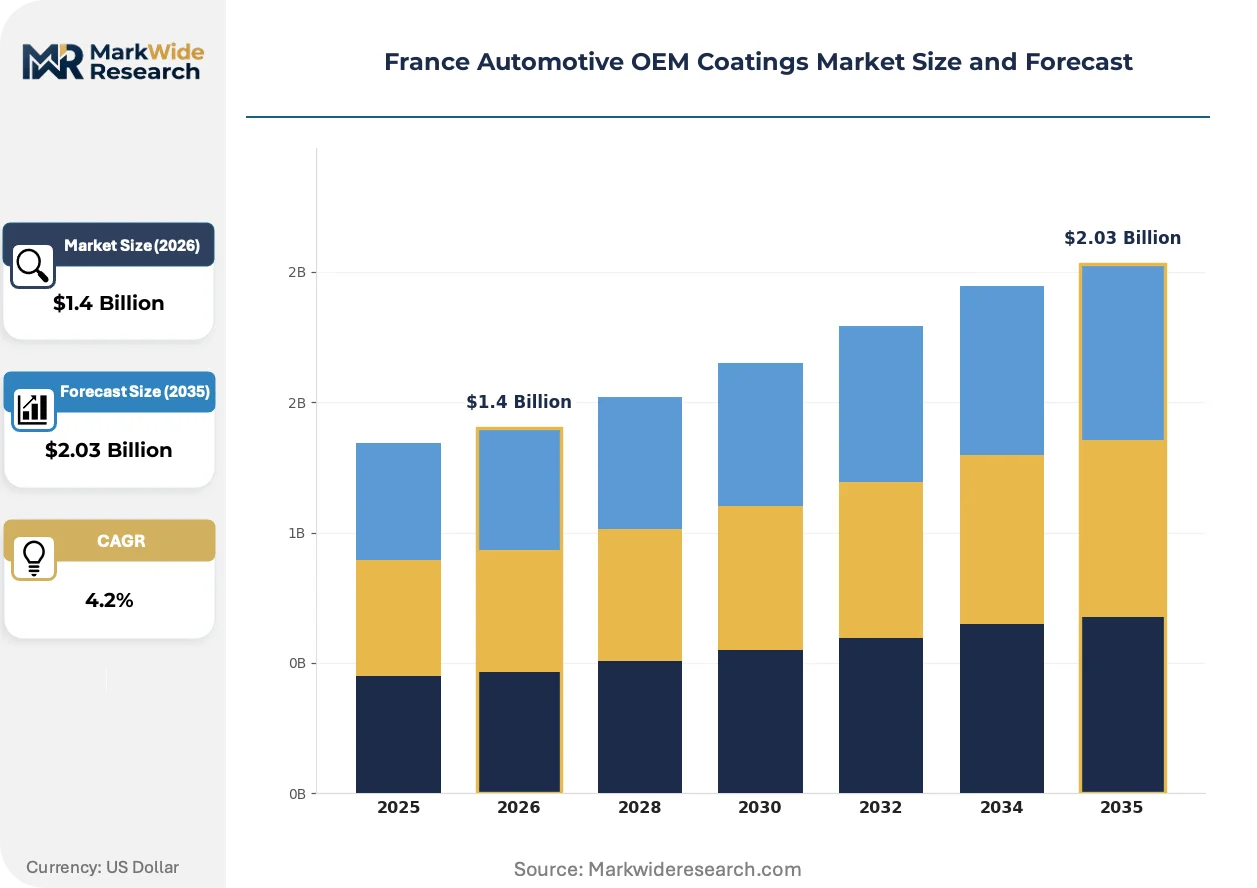
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primers, Base Coats, Clear Coats, Specialty Coatings Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Waterborne, Solvent-based, Powder Coating, UV-cured End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | AkzoNobel N.V., Axalta Coating Systems, BASF SE, PPG Industries, Inc., RPM International Inc., The Sherwin-Williams Company, Nippon Paint Holdings Co Ltd, Beckers Group, Mankiewicz Gebr. & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive OEM Coatings Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and procurement specifications are converging to redefine competitive advantage in French automotive finishing, with technology leadership separating contract winners from commodity suppliers.
Waterborne base coat systems are displacing solvent-borne alternatives across new line installations at Stellantis and Renault assembly plants. French OEM technical teams are specifying higher solids content and integrated primer-surfacer layers to reduce booth cycle times. This displacement is compressing demand for traditional solvent-based resin supply agreements while elevating formulation service intensity as a contract discriminator.
EU Green Deal carbon border adjustment mechanisms and REACH authorization timelines are tightening substance restrictions faster than reformulation cycles. French coaters face overlapping obligations from ECHA substance evaluation, ANSM workplace exposure limits, and emerging digital product passport traceability mandates. The base coat segment bears the heaviest compliance burden due to pigment diversity and complex supply chain documentation requirements.
OEM technical service specifications now embed sustainability scoring alongside performance metrics, altering how French purchasing teams evaluate supplier proposals. Coatings procurement at major French assemblers weights volatile organic compound footprint and recycled content verification equally with color match precision and chip resistance. This specification evolution is most visible in Hauts-de-France contract renewals, where incumbent suppliers face requalification against environmental criteria absent from prior agreements.
France Automotive OEM Coatings Market Segmentation
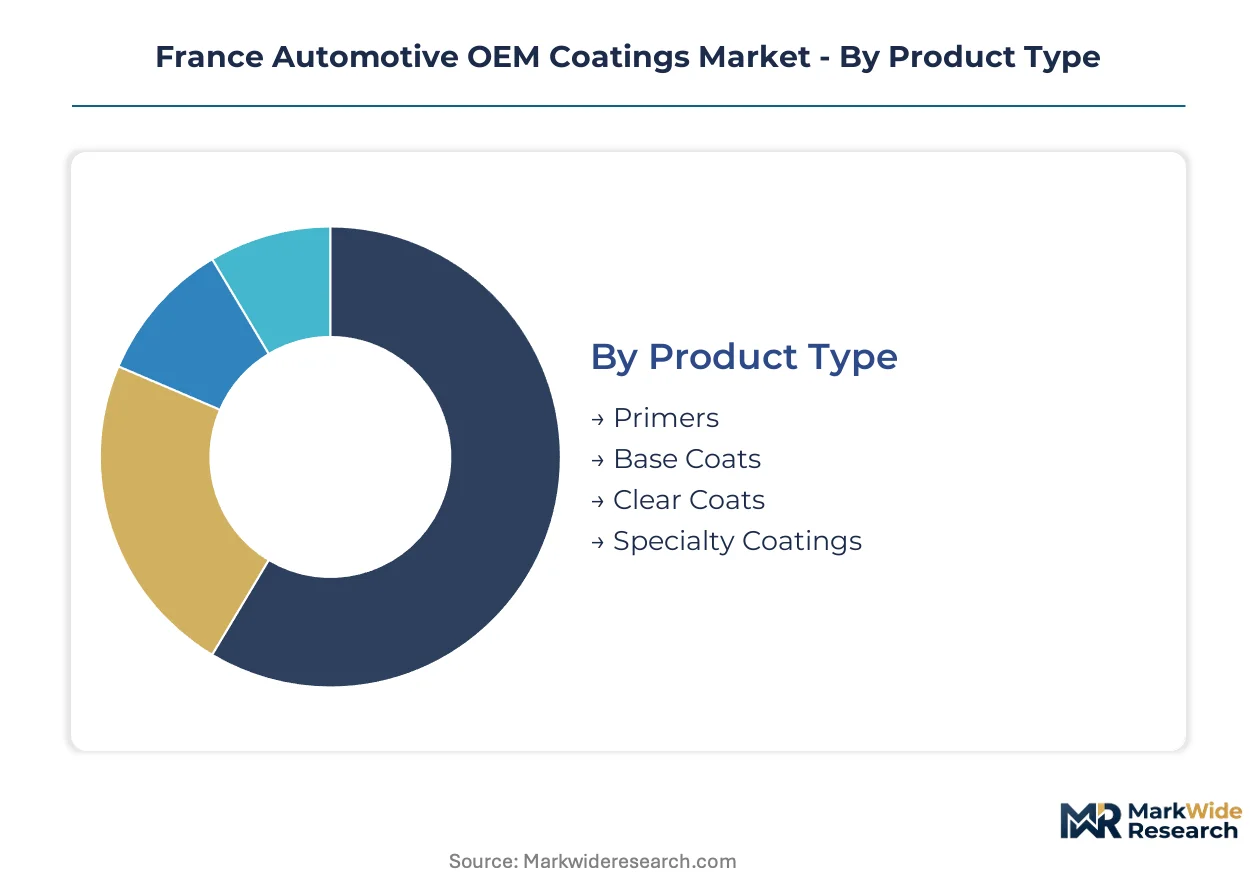
Segmentation in French automotive OEM coatings reveals how regulatory pressure and OEM technical specifications fragment demand across incompatible formulation platforms. Each category exposes different margin vulnerabilities and technology transition timelines that suppliers must navigate to maintain contract positioning.
Product Type:
Base coats and clear coats command the deepest margin pools due to formulation complexity and technical service intensity, while primers and specialty coatings operate on thinner spreads with higher volume throughput.
- Primers:Electrodeposition and surfacer formulations provide corrosion protection and substrate leveling for unibody construction. Demand concentrates at Stellantis plants in Hauts-de-France, where integrated primer-surfacer layers are reducing booth cycle times and coating mass per vehicle.
- Base Coats:Pigmented layers delivering color, metallic effects, and hiding power through waterborne or solvent-borne resin systems. Pigment diversity and supply chain documentation requirements concentrate margin pressure here, with white and pastel formulations exposed to titanium dioxide feedstock volatility.
- Clear Coats:Transparent protective layers providing gloss, UV resistance, and chip protection through polyurethane or acrylic chemistry.
- Specialty Coatings:Functional formulations including anti-chip, sound-deadening, and thermal management coatings for specific vehicle zones.
Base coats hold installed capacity. Clear coats are rotating up the share rankings.
Application:
Electric vehicle coating specifications diverge most sharply from legacy platforms, creating the steepest technology transition costs and qualification timelines for suppliers.
- Passenger Vehicles:High-volume compact and mid-size platforms requiring standardized color palettes and rapid color-change capability. Demand concentrates at Renault and Stellantis assembly lines in northern France, where waterborne base coat conversion is now complete on newer installations.
- Electric Vehicles:Battery-electric platforms with specialized primer requirements for thermal management and electromagnetic shielding. Stellantis plants in Hauts-de-France are commissioning dedicated coating lines for these platforms, driving demand for compatible primer and clear coat systems with modified cure profiles.
- Commercial Vehicles:Light and heavy-duty trucks with durability-focused specifications and extended warranty requirements.
- Luxury Vehicles:Low-volume, high-customization segments with premium effect finishes and manual inspection protocols.
Passenger vehicles hold installed capacity. Electric vehicles are climbing the fastest.
Technology:
Technology selection now determines regulatory compliance trajectory, with waterborne platforms capturing new line investments while legacy solvent infrastructure faces stranded asset risk.
- Waterborne:Resin systems dispersed in water rather than organic solvents, achieving low volatile organic compound emissions through formulation design rather than end-of-pipe controls. REACH and EU Green Deal restrictions are mandating this technology across new French OEM line installations.
- Powder Coating:Thermoset or thermoplastic powders applied electrostatically and cured through thermal or ultraviolet processes. Underbody and chassis applications in French plants are adopting this technology for zero volatile organic compound emissions and high-transfer efficiency.
- Solvent-based:Traditional resin systems using organic solvents for application viscosity and film formation.
- UV-cured:Radiation-curable formulations polymerizing instantly under ultraviolet light exposure.
Solvent-based holds installed capacity. Powder coating is gaining share fastest.
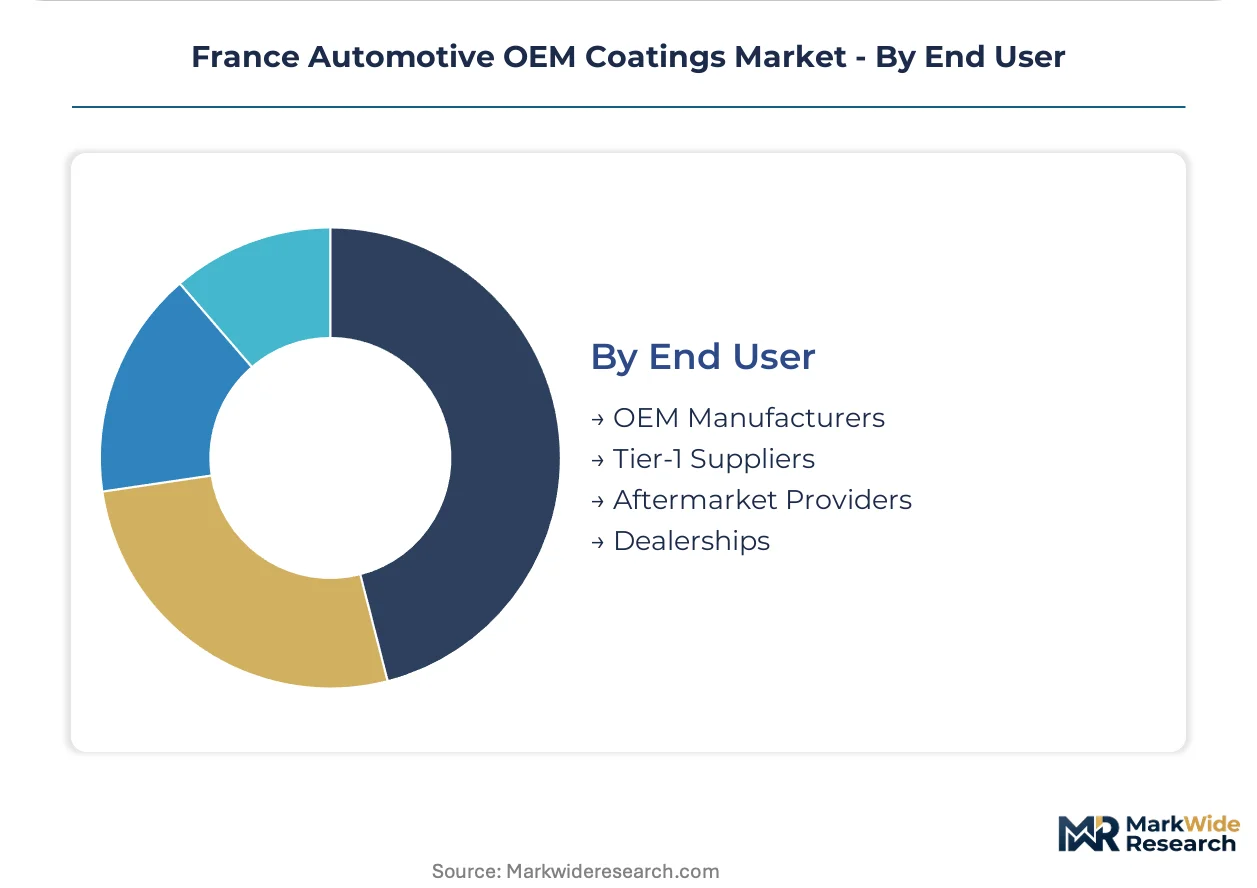
End User:
OEM direct procurement concentrates volume and technical specification power, while tier-1 suppliers represent the contested middle ground where coating suppliers compete for component-level contracts.
- OEM Manufacturers:Vehicle assemblers including Stellantis and Renault operating integrated paint shops with direct coating procurement. Sustainability scoring and digital product passport requirements are reshaping supplier qualification at these accounts.
- Tier-1 Suppliers:Component manufacturers coating bumpers, fascias, and body panels prior to final assembly. The Occitanie region's sparse OEM presence creates whitespace for technical service centers targeting these accounts.
- Aftermarket Providers:Refinish coating distributors serving collision repair and restoration demand.
- Dealerships:Authorized repair facilities with captive refinish supply agreements.
OEM manufacturers hold installed capacity. Tier-1 suppliers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's automotive OEM coatings trade balance tilts toward net import reliance for specialized resin intermediates and pigment precursors, while finished coating formulations flow outward to assembly plants in neighboring EU markets. This exchange pattern concentrates strategic value in formulation chemistry rather than commodity feedstock production.
Germany
Isocyanate hardener production clusters along the Rhine chemical corridor, supplying cross-border feedstock to French clear coat operations. KBA vehicle type approval rules and ECHA substance authorization timelines shape reformulation investments at German resin producers serving French OEM accounts. The Ludwigshafen-Basel axis anchors polyisocyanate capacity critical to polyurethane chemistry.
Belgium
Antwerp's petrochemical complex feeds aromatic solvent and acrylic monomer demand across northern French paint shops. REACH compliance documentation for imported intermediates concentrates at Belgian logistics hubs before cross-border transfer. The Port of Antwerp-Bruges handles titanium dioxide pigment shipments destined for Hauts-de-France coating plants.
Spain
Renault's Spanish assembly network sources compatible waterborne base coat systems from French formulation plants, creating reciprocal trade in finished coatings. Spanish SEPI industrial policy and EU Green Deal implementation timelines align with French VOC reduction trajectories. The Barcelona-Tarragona chemical corridor provides alternative resin supply routes.
Italy
Luxury vehicle effect finish demand from Italian OEMs pulls specialty metallic and pearlescent base coat exports from French suppliers. Italian MISE industrial transition funding supports comparable waterborne technology conversion timelines. The Turin-Milan automotive belt maintains technical service coordination with French formulation labs.
Netherlands
Rotterdam's bulk chemical handling infrastructure arbitrages titanium dioxide and specialty additive flows into French coating operations. Dutch environmental permitting under EU Industrial Emissions Directive precedents inform French plant upgrade specifications. The Chemelot campus in Limburg hosts rheology control additive production relevant to waterborne resin systems.
France Automotive OEM Coatings Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D scale dimensions, producing a tiered structure where publicly traded coating majors anchor high-volume OEM contracts while family-owned specialists capture niche specification segments. Three archetypes dominate: integrated chemical conglomerates with captive resin supply, standalone coating formulators with technical service intensity, and regional specialists with logistics proximity advantages. Competitive moves concentrate on waterborne technology licensing partnerships and powder coating capacity expansion near EV assembly clusters.
Within the integrated chemical conglomerate tier, BASF SE and PPG Industries exemplify archetypes combining resin backward integration with formulation expertise. Axalta Coating Systems occupies a position representing standalone coating specialists with established OEM supply agreements. These three anchors demonstrate how technology leadership in color matching and waterborne chemistry separates contract winners from commodity suppliers in French automotive finishing procurement.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Axalta Coating Systems |
| BASF SE |
| PPG Industries, Inc. |
| RPM International Inc. |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co Ltd |
| Beckers Group |
| Mankiewicz Gebr. & Co. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between French OEM procurement teams and coating formulators lock in both resin supply security and price visibility across multi-year vehicle platform cycles, insulating Stellantis and Renault plants from titanium dioxide feedstock volatility while compressing margin flexibility for suppliers facing REACH compliance costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures that stratify across premium effect finishes, standard solid colors, and economy fleet whites. Price differentiation rests on color complexity and technical service intensity, with metallic and pearlescent base coats commanding wider spreads than solid formulations. Cost compression in white and pastel tiers is intensifying because titanium dioxide sourcing concentrates in Chinese and Belgian chemical corridors. Tier-1 component coaters exhibit the highest price sensitivity due to thinner margin pools and limited formulation customization budgets.
Supply Chain Analysis
Inventory buffers for isocyanate hardeners and acrylic monomers stretch to eight-to-twelve weeks across northern French paint shops, reflecting just-in-time constraints at Stellantis assembly lines. Feedstock production clusters in Germany, Belgium, and the Netherlands, with the Ludwigshafen-Basel axis anchoring polyisocyanate capacity critical to polyurethane clear coat chemistry. Raw material dependencies center on aromatic solvents from Antwerp, titanium dioxide pigment via Rotterdam, and rheology additives from the Chemelot campus. Single-source vulnerability in cross-border isocyanate logistics exposes French coaters to Rhine corridor disruption risk. Distribution runs through integrated OEM paint shops and tier-1 component coating facilities serving bumper and fascia programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates formidable barriers. REACH authorization timelines and ECHA substance restrictions embed switching costs that protect qualified suppliers from commoditization.
For Market Incumbents: Shield contract positioning at Hauts-de-France OEM accounts by accelerating waterborne R&D investment ahead of EU Green Deal VOC deadline acceleration. Deepen backward integration into zirconium-based pretreatment chemistry to offset chromium substitution mandates. Lock in tier-1 technical service coverage across the Occitanie whitespace before emerging specialists establish beachheads.
For New Entrants and Emerging Players: Technical service underinvestment in southern France creates entry opportunity for coating specialists willing to deploy mobile color-matching labs and on-site formulation support. Target tier-1 component coaters in the Occitanie region where OEM assembly absence has suppressed incumbent service intensity. Lead with powder coating expertise for underbody applications where transfer efficiency advantages resonate with sustainability procurement scoring.
For Investors and Strategic Acquirers: Capital is best deployed toward standalone formulators with captive waterborne resin synthesis and established French OEM technical service relationships. Long-term viability hinges on regulatory compliance architecture rather than commodity scale. Monitor ECHA substance authorization timelines as the inflection signal for reformulation-driven contract churn.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Technology Licensing | PPG Industries leverages color-matching IP to anchor Stellantis contract renewals under stricter VOC limits. |
| Powder Coating Capacity Expansion | Axalta positions zero-emission underbody systems to capture EV platform thermal management specifications. |
| Backward Integration into Resin Synthesis | BASF SE secures supply chain control over waterborne acrylic dispersions for base coat formulations. |
| Digital Product Passport Alignment | Early movers integrate coating chemistry traceability to meet EU battery regulation documentation requirements. |
| Regional Technical Service Buildout | Southern France coverage gaps create whitespace for specialists targeting tier-1 component coaters. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 procurement leads, coating R&D directors, and aftermarket distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with formulation chemists and paint shop operations managers across Stellantis and Renault facilities. Secondary validation drew from ECHA substance authorization databases, French customs trade records, SEC filings of listed coating majors, and vehicle production data from industry associations. Bottom-up segment sizing triangulated against top-down market value estimates.
Segmentation dimensions modeled span product type, application platform, technology chemistry, and end-user procurement tier across the projection horizon. CAGRs derive from trend-line extrapolation of coating content per vehicle, technology substitution curves, and regulatory compliance investment cycles. Forecast inputs incorporate EV platform coating specifications, REACH substance restriction timelines, and powder coating penetration rates for underbody applications.
Underlying assumptions cover sustained OEM production volumes in Hauts-de-France, with deviation risk concentrated in titanium dioxide feedstock disruptions and cross-border logistics interruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Self-Healing Coatings Market
Coatings
Batters and Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Global Antiviral Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Trim Coatings Market
Coatings
Dispersion Coating Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Stain Resistant Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Glazes Market
Coatings
Shipping Container Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Graphene Coatings Market