
 Consumer Appliance Coatings Market | 2026-2036
Consumer Appliance Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Appliance Coatings Market Analysis
Asset-light leasing models for coating lines are reshaping competitive dynamics among appliance OEMs and their suppliers. AkzoNobel leverages its integrated powder coating resin operations to sustain margin control across refrigerator and oven applications. PPG Industries anchors its position through geographic dominance in North American appliance manufacturing corridors. Tiger Drylac specializes in compact batch powder systems that compete effectively for mid-volume dishwasher and washing machine producers.
Consumer appliance coatings are protective and decorative finishes applied to metal, polymer, or composite substrates, typically formulated with epoxy-polyester hybrids or fluoropolymer resins to achieve corrosion resistance, thermal stability, and surface hardness between 2H and 4H pencil hardness. These coatings serve primarily to extend product lifespan, enable color customization, and meet hygiene standards in food-contact and moisture-exposed environments. Powder coating dominates the coating type dimension due to its near-zero VOC profile and overspray recyclability, while liquid coating retains structural share in premium refrigerator segments requiring metallic and pearlescent effects. Among end users, residential appliances generate the largest volume base, though consumer electronics coatings command higher per-kilogram value due to precision thickness requirements and fingerprint-resistant nanocoatings.
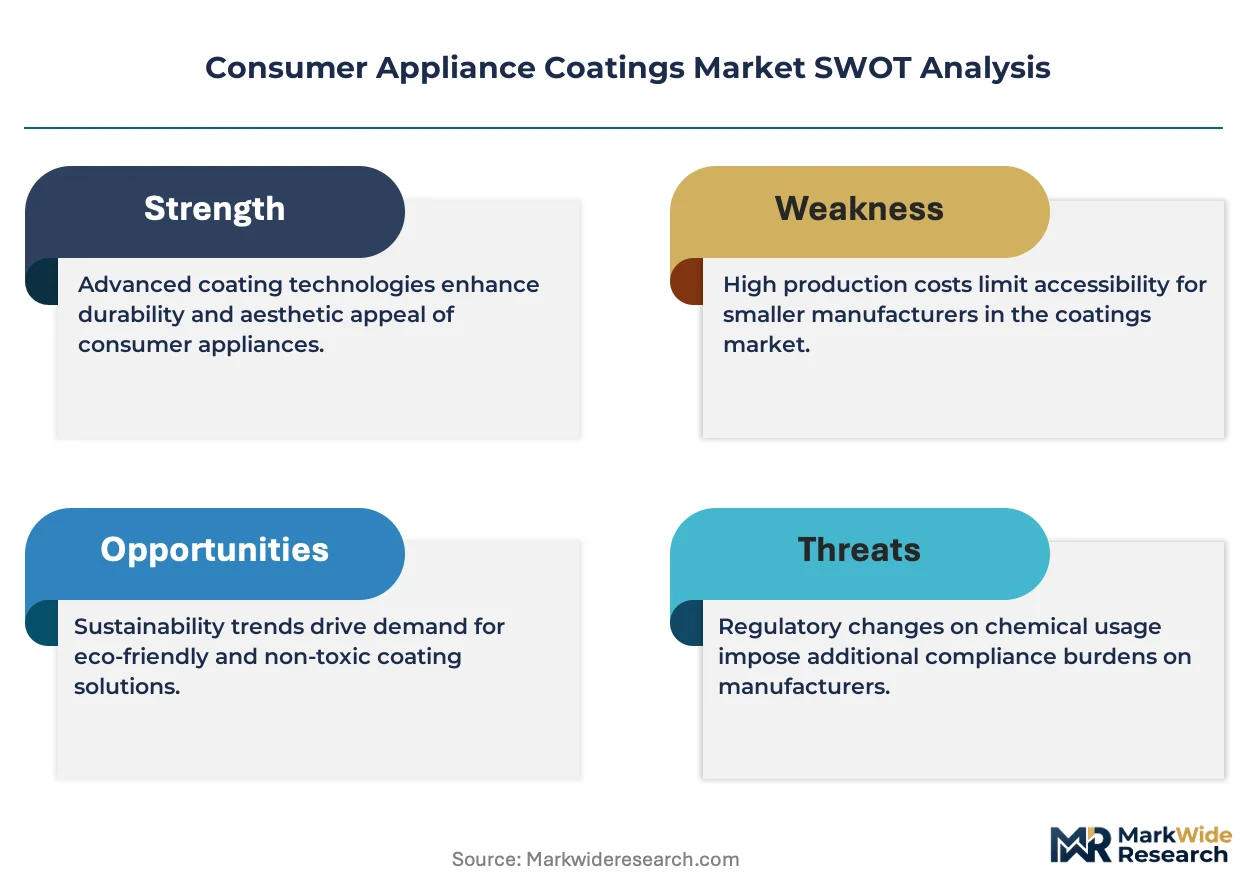
EPA regulations on hazardous air pollutants from surface coating operations and REACH restrictions on chromium VI and certain isocyanates are forcing reformulation across solvent-borne product lines. China's GB standards for volatile organic compound emissions in appliance manufacturing, enforced by MEE, are accelerating waterborne and powder system conversions among domestic producers. India's BIS certification for coating durability in tropical climates adds a compliance layer for exporters targeting South Asian appliance assembly plants. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure multi-region product registrations.
Market Dynamics
China's MIIT emission standards for appliance manufacturing are compressing solvent-borne coating demand while accelerating powder system conversions across Guangdong province production clusters.
Growth Catalysts
- REACH chromium VI restrictions:European appliance OEMs are reformulating exterior finishes toward epoxy-polyester hybrids, expanding addressable market for compliant coating suppliers.
- India BIS tropical durability certification:Exporters targeting South Asian assembly plants must upgrade coating performance specifications, creating specification-driven replacement cycles.
- Waterborne system technology maturation:Metallic effect capabilities in waterborne acrylic-urethane platforms now match liquid coating aesthetics for premium refrigerator segments.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin predictability for coating formulators serving price-sensitive washing machine OEMs.
- Guangdong province supply concentration:Haier, Midea, and Gree coating facilities cluster within 200 kilometers, creating geographic dependency risk for regional logistics disruptions.
- Fluoropolymer resin technical limitation:Curing temperature requirements above 200°C restrict application to metal substrates, excluding polymer appliance components from high-performance finishes.
Strategic Opportunities
- India domestic appliance production expansion:PLI scheme incentives for refrigerator and air conditioner manufacturing are attracting coating line investments toward Gujarat and Tamil Nadu industrial corridors.
- UV-cured powder technology convergence:Near-infrared curing combined with powder application enables heat-sensitive substrate coating for smart appliance touch panels and control interfaces.
- Asset-light coating line leasing:Mid-volume dishwasher producers in Turkey and Mexico are accessing Tiger Drylac batch systems without capital ownership, lowering entry barriers for regional appliance brands.
Industry Challenges
- ISO 9001 and IATF 16949 certification timeline:Automotive-qualified coating suppliers entering appliance markets face 18-24 month quality system audits before qualifying for refrigerator OEM approved vendor lists.
- Legacy liquid line retrofit complexity:Converting solvent-borne spray booths to powder recovery systems requires production downtime coordination with just-in-time appliance assembly schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Appliance Coatings Market |
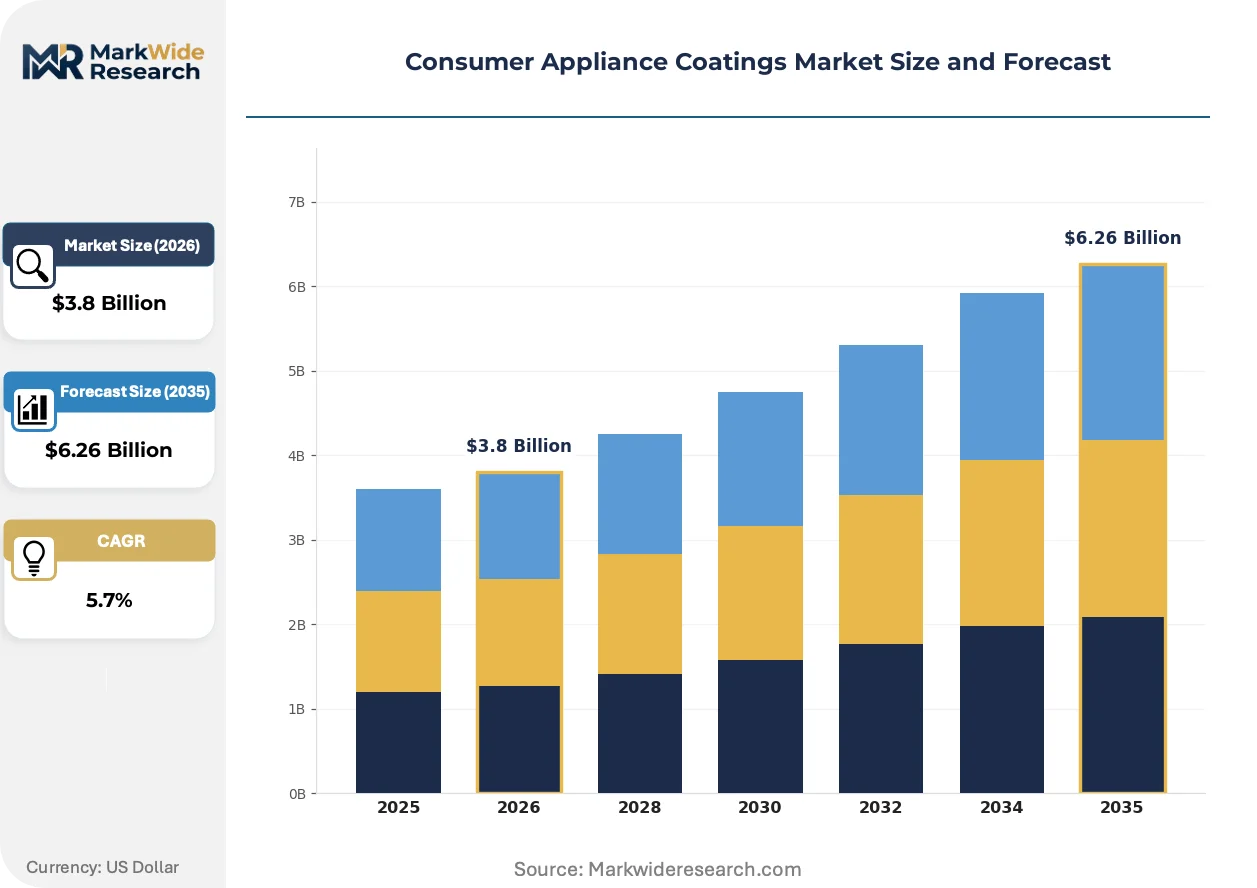
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
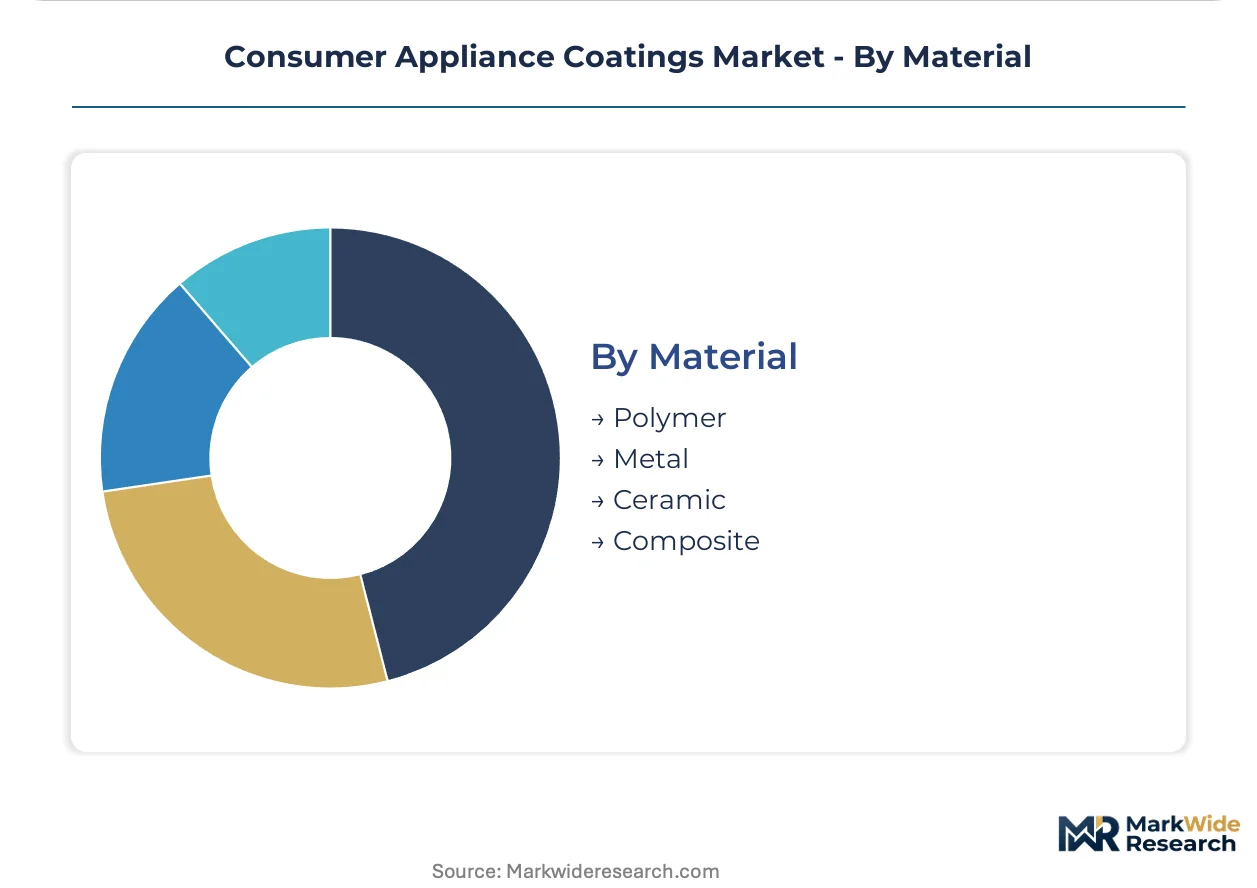
| Segmentation | Coating Type: Powder Coating, Liquid Coating, Electrocoat, Nanocoatings End User: Residential Appliances, Commercial Appliances, Industrial Equipment, Consumer Electronics Application: Washing Machines, Refrigerators, Ovens, Dishwashers Material: Polymer, Metal, Ceramic, Composite |
| Companies Covered | AkzoNobel N.V, Axalta Coating Systems, PPG Industries, The Sherwin-Williams Company, Henkel AG & Co. KGaA, Tiger Drylac, Jotun, Valspar, Nippon Paint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Appliance Coatings Market Emerging Trajectories
Active innovation fronts center on curing technology acceleration, regulatory compliance automation, and procurement model restructuring among residential appliance manufacturers.
UV-cured powder coating systems are rendering obsolete conventional thermal curing for heat-sensitive polymer appliance components. Mid-volume washing machine and dishwasher producers in Mexico and Turkey are piloting near-infrared powder lines to coat control panels and trim pieces previously excluded from powder applications. This thermal reduction is rendering obsolete the historical metal-substrate limitation that restricted powder coating to refrigerator and oven shells.
China's GB standards for volatile organic compound emissions, enforced by MEE, are mandating real-time monitoring systems at coating facility exhaust points. Appliance manufacturers in Guangdong province must install continuous emission measurement equipment and report hourly VOC discharge data to provincial environmental databases. Premium refrigerator segments requiring metallic and pearlescent liquid finishes face the steepest compliance cost escalation, accelerating waterborne metallic development programs.
Appliance OEMs are consolidating coating procurement toward specification-based supplier partnerships rather than transactional material purchasing. Haier and Midea have shifted refrigerator exterior finishing contracts toward multi-year coating service agreements incorporating application equipment, technical support, and regulatory compliance management. This bundled sourcing model concentrates supplier relationships in China's coastal manufacturing corridors while marginalizing smaller regional coating distributors.
Consumer Appliance Coatings Market Segmentation
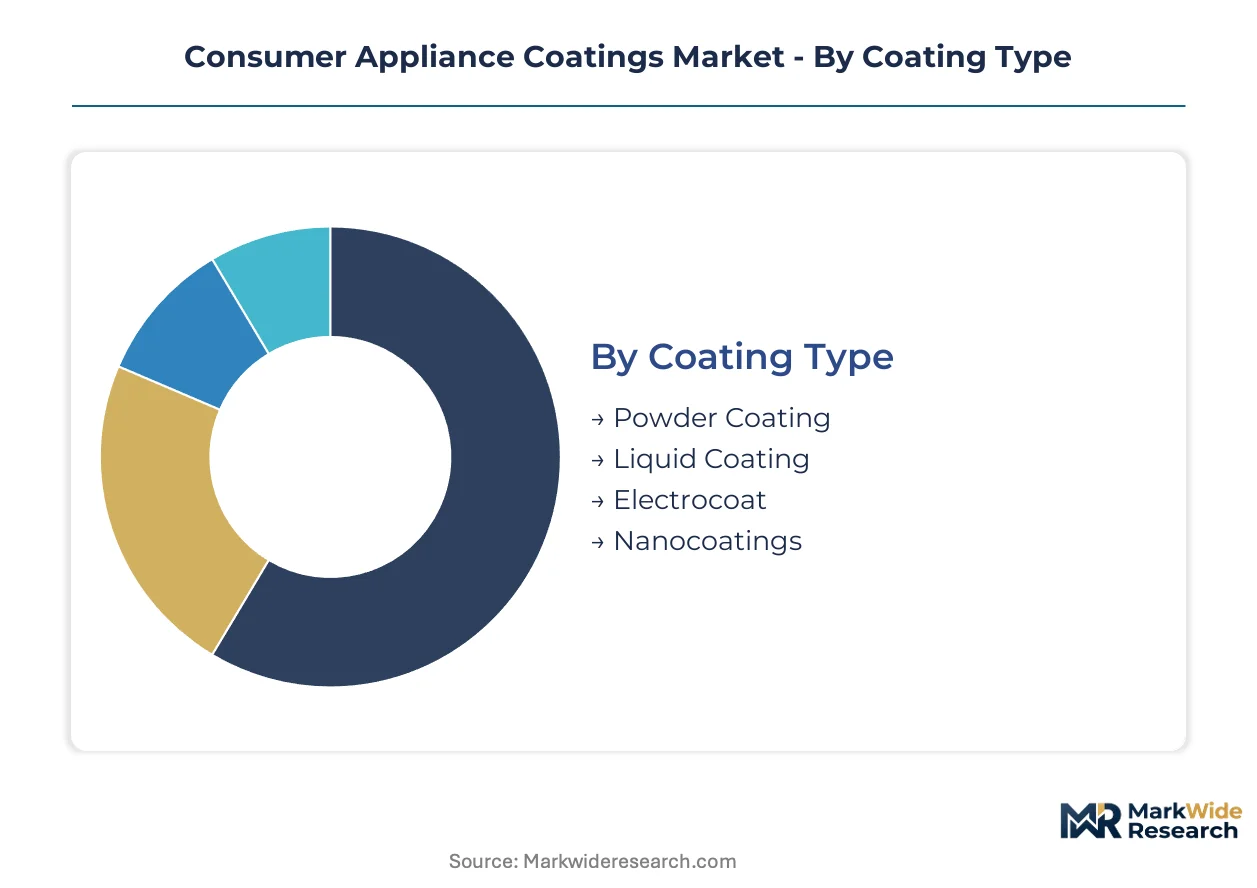
Coating specifications diverge sharply across appliance categories, with thermal cycles, moisture exposure, and aesthetic requirements dictating formulation choices. Procurement cycles vary from quarterly batch orders for high-volume washing machine lines to annual contracts for premium refrigerator finishes requiring metallic effect validation.
Coating Type:
Powder coating turns over fastest in procurement cycles due to overspray recyclability and near-zero waste profiles, while nanocoatings operate on extended development timelines for fingerprint-resistant formulations.
- Powder Coating:Epoxy-polyester hybrid formulations dominate refrigerator and oven exteriors, achieving 2H-4H pencil hardness with VOC emissions below regulatory thresholds. Demand concentrates in China's Guangdong province where Haier, Midea, and Gree operate consolidated coating facilities under tightening MIIT emission standards.
- Liquid Coating:Solvent-borne and waterborne acrylic-urethane systems retain structural position in premium refrigerator segments requiring metallic and pearlescent effects. REACH chromium VI restrictions are forcing European appliance OEMs toward compliant reformulations, expanding specification-driven replacement cycles for exterior finishes.
- Electrocoat:Cathodic epoxy systems provide uniform edge coverage for complex metal appliance frames and washing machine drums.
- Nanocoatings:Thin-film formulations enable fingerprint resistance and antimicrobial surfaces for consumer electronics and smart appliance touch panels.
Powder coating anchors the volume base while nanocoatings gain share at the steepest rate.
End User:
Cost tiers separate segments, with residential appliances driving bulk volume through standardized specifications and consumer electronics commanding premium pricing for precision thickness control.
- Residential Appliances:Refrigerators, washing machines, and dishwashers generate the largest coating volume base, with procurement concentrated among China's coastal manufacturing clusters. EPA regulations on hazardous air pollutants and China's GB standards enforced by MEE are accelerating waterborne and powder system conversions among domestic producers.
- Consumer Electronics:Smart displays, control panels, and touch interfaces require sub-10-micron precision coatings with optical clarity and fingerprint resistance. India's BIS certification for coating durability in tropical climates adds compliance complexity for exporters targeting South Asian assembly plants.
- Commercial Appliances:Restaurant equipment and institutional laundry systems prioritize chemical resistance and thermal stability over aesthetic variety.
- Industrial Equipment:Heavy-duty machinery coatings emphasize corrosion protection and extended service intervals in harsh operating environments.
Residential appliances generate the dominant procurement volume while consumer electronics coatings climb the fastest on per-kilogram value expansion.
Application:
Volume concentration varies by production geography, with washing machine and refrigerator output clustering in distinct regional corridors that shape coating logistics and supplier proximity requirements.
- Refrigerators:Exterior panels and interior liners require food-contact compliant finishes with thermal stability across temperature cycling. Waterborne metallic development programs are accelerating as premium segments face steepest compliance cost escalation under China's real-time VOC monitoring requirements.
- Washing Machines:Drum coatings must withstand detergent exposure and mechanical abrasion while exterior panels prioritize scratch resistance and color retention. Titanium dioxide feedstock volatility compresses margin predictability for formulators serving price-sensitive OEM procurement.
- Ovens:High-temperature enamel and powder systems resist thermal degradation up to 250°C on interior cavity surfaces.
- Dishwashers:Moisture-exposed interiors demand corrosion-resistant electrocoats and powder finishes with hydrophobic surface properties.
Washing machines anchor the volume base while refrigerator coatings expand most quickly on premium finish specification upgrades.
Material:
Substrate thermal tolerance determines coating compatibility, with metal surfaces accommodating high-cure fluoropolymer systems and polymer components restricted to UV or low-temperature powder alternatives.
- Metal:Cold-rolled steel and aluminum substrates dominate refrigerator cabinets, oven bodies, and washing machine drums, enabling full range of thermal and UV curing options. Fluoropolymer resin curing requirements above 200°C restrict these high-performance finishes to metal components exclusively.
- Polymer:ABS, polycarbonate, and thermoplastic elastomers in control panels and trim pieces require near-infrared or UV-cured powder systems to avoid substrate deformation. UV-cured powder technology convergence is rendering obsolete the historical metal-substrate limitation for smart appliance interfaces.
- Ceramic:Glass-ceramic cooktop surfaces utilize specialized high-temperature enamels with thermal shock resistance.
- Composite:Fiber-reinforced polymer structural components in premium appliance architectures demand compatible primer and topcoat systems.
Metal substrates anchor the volume base while polymer-compatible coating systems gain share at the steepest rate on smart appliance design proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appliance OEM procurement concentrates in manufacturing corridors where emission regulations and coating infrastructure have co-evolved. Buyers cluster near coastal industrial zones with established powder coating supply chains and real-time compliance monitoring capabilities.
China
Guangdong province hosts concentrated refrigerator and washing machine coating operations for Haier, Midea, and Gree. MIIT emission standards enforced by MEE mandate real-time VOC monitoring at facility exhaust points. Manufacturers in the Pearl River Delta cluster are converting solvent-borne lines to powder recovery systems under tightening GB standards.
United States
North American appliance manufacturing corridors in the Midwest and Southeast generate steady demand for compliant exterior finishes. EPA regulations on hazardous air pollutants from surface coating operations force reformulation across solvent-borne product lines. PPG Industries anchors supply relationships with major OEMs across Ohio, Kentucky, and Tennessee production facilities.
Germany
European appliance OEMs source REACH-compliant epoxy-polyester hybrid coatings for exterior refrigerator finishes. ECHA restrictions on chromium VI and certain isocyanates are accelerating specification-driven replacement cycles. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate coating R&D and application equipment manufacturing.
India
Domestic refrigerator and air conditioner production expansion under the PLI scheme is attracting coating line investments toward Gujarat and Tamil Nadu. BIS certification for coating durability in tropical climates adds compliance complexity for exporters targeting South Asian assembly plants. Mumbai-Pune and Chennai-Bengaluru industrial corridors are emerging as procurement hubs.
Japan
Precision coating demand for smart appliance touch panels and control interfaces drives nanocoating development programs. METI efficiency standards and JIS quality certifications shape supplier qualification requirements. Kanto and Kansai manufacturing belts concentrate consumer electronics coating applications with sub-10-micron thickness specifications.
Consumer Appliance Coatings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. The vendor base organizes around three strategic archetypes: integrated resin-to-coating operators, geographic corridor dominators, and compact batch system specialists. Consolidation pressures favor multi-year service agreements bundling application equipment with technical support. Competitive moves center on specification-based supplier partnerships and asset-light coating line leasing models.
Among integrated coating operators, AkzoNobel N.V and PPG Industries exemplify the resin-backward archetype with captive supply chain control over powder formulation inputs. Tiger Drylac occupies a specialist position serving mid-volume dishwasher and washing machine producers through compact batch powder systems. These three anchors demonstrate how scale, integration depth, and application-specific focus segment competitive positioning across refrigerator, oven, and smart appliance interface coatings.
| Leading Market Players |
|---|
| AkzoNobel N.V |
| Axalta Coating Systems |
| PPG Industries |
| The Sherwin-Williams Company |
| Henkel AG & Co. KGaA |
| Tiger Drylac |
| Jotun |
| Valspar |
| Nippon Paint |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Guangdong province powder coating facilities is compressing supplier pricing power while forcing asset-light leasing models that reshape procurement economics for refrigerator and washing machine OEMs.
Pricing Analysis
Certification level creates the primary spread between coating tiers, with ISO 9001 and IATF 16949-qualified suppliers commanding premiums over uncertified regional distributors. Contract-based long-term offtake agreements dominate procurement, bundling application equipment with technical support and regulatory compliance management. Price differentiation hinges on volume scale and after-sales service bundling, with mid-volume dishwasher producers in Turkey and Mexico exhibiting highest price sensitivity while premium refrigerator OEMs prioritize metallic effect validation over unit cost.
Supply Chain Analysis
Upstream titanium dioxide and fluoropolymer resin production concentrates in China, Germany, and Japan, with pigment cost swings feeding directly into coating formulator margins. Raw material dependencies center on epoxy-polyester hybrid resins, cathodic epoxy electrocoat systems, and UV-curable powder formulations. Single-source vulnerability in Guangdong province coating facilities clusters within 200 kilometers of Haier, Midea, and Gree operations. Distribution runs through specification-based supplier partnerships rather than transactional material purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating procurement is consolidating toward platform-economics models where bundled service agreements replace spot material buying, enabled by real-time VOC monitoring infrastructure and multi-year equipment leasing contracts.
For Market Incumbents: Insulate margin structures through backward integration into powder coating resin operations, mirroring AkzoNobel's captive supply chain control. Prioritize certification investment in ISO 9001 and IATF 16949 quality systems to defend against automotive-qualified coating suppliers entering appliance markets. Channel control through multi-year service agreements incorporating application equipment and regulatory compliance management creates switching costs that marginalize smaller regional distributors.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial corridors offer underpenetrated coating line investment opportunities as PLI scheme incentives attract refrigerator and air conditioner manufacturing capacity. Target mid-volume dishwasher producers in Turkey and Mexico with compact batch powder systems accessible through asset-light leasing without capital ownership. Go-to-market positioning should emphasize near-infrared curing technology for heat-sensitive polymer appliance components previously excluded from powder applications.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin-to-coating operators with captive supply chain control over powder formulation inputs. Long-term viability across the projection horizon favors suppliers with backward integration into resin production and established geographic corridor dominance. Acquisition target archetype: compact batch system specialists serving mid-volume producers in emerging manufacturing clusters. The signal to watch is conversion rates from solvent-borne to powder and waterborne systems under tightening MIIT and EPA emission standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | AkzoNobel's captive powder coating resin operations sustain margin control across refrigerator applications. |
| UV-Cured Powder Technology Deployment | Near-infrared curing enables coating of heat-sensitive polymer components for smart appliance touch panels. |
| Asset-Light Coating Line Leasing | Tiger Drylac batch systems lower entry barriers for mid-volume dishwasher producers in Turkey and Mexico. |
| Multi-Year Service Agreement Consolidation | Haier and Midea bundled contracts marginalize regional distributors through equipment-plus-compliance bundling. |
| Real-Time VOC Monitoring Infrastructure | Guangdong province manufacturers meet MEE GB standards through continuous emission measurement equipment installation. |
Methodological Framework
Desk research of SEC filings, customs and trade data, chemical industry association reports, and regulatory submission databases preceded structured interviews with coating plant managers, appliance OEM procurement leads, distribution channel partners, and technical R&D directors. Primary fieldwork combined with secondary validation across EPA enforcement actions, ECHA restriction proposals, and MIIT emission standard drafts. Bottom-up volume modeling and top-down value triangulation anchored market sizing across coating type, end user, application, and material segmentation dimensions.
Assumptions held fixed include regulatory enforcement timelines for China's GB standards and REACH chromium VI restrictions, while raw material cost trajectories and UV-cured powder adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass coating chemistry, appliance category, substrate material compatibility, and regional production cluster regulatory framework. CAGRs were derived from regression analysis of historical procurement cycles and projected conversion rates from solvent-borne to compliant systems across the analysis window. Industry-specific inputs included titanium dioxide feedstock volatility patterns and appliance OEM capital expenditure plans for coating line retrofits.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated resin operators or accelerated UV-cured powder technology deployment by specialist suppliers would shift outcomes beyond modeled ranges. Quarterly review of MIIT emission standard enforcement intensity, BIS certification timeline announcements, and PLI scheme coating line investment disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
China Protective Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Global Polyurea Coating Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Coating Pigments Market
Coatings
Sol Gel Nanocoating Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Coated Casing Market
Coatings
Canada Floor Coatings Market
Coatings
Global Conformal Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Polyester Coatings Market
Coatings
UV Coatings Market