
 Camouflage Coatings Market | 2026-2036
Camouflage Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Camouflage Coatings Market Insights
REACH is realigning the cost-of-entry calculus for European suppliers by mandating extensive substance registration and toxicity documentation for imported resin precursors. PPG Industries leverages its integrated pigment manufacturing network to control raw material qualification timelines. AkzoNobel sustains competitive positioning through specialized marine camouflage systems that meet NATO naval reflectance standards. Huntsman Corporation anchors its portfolio in aliphatic polyurethane chemistries that balance infrared suppression with exterior durability.
Camouflage coatings are engineered film-forming systems containing near-infrared reflective pigments, conductive fillers, and adaptive chromic compounds designed to reduce detection across visible, near-infrared, and thermal spectral bands. These formulations typically achieve solar reflectance values below 0.30 and emissivity modulation between 0.50 and 0.90 to defeat thermal imaging sensors. Liquid coatings dominate current military procurement due to field-repair compatibility and established application infrastructure, while nano coatings represent the fastest-expanding technology segment as graphene-enhanced and metamaterial-infused formulations demonstrate adaptive bandwidth performance. Spray coatings occupy the largest share of aerospace component finishing, where robotic application ensures uniform thickness on complex geometries.
EPA regulations in the United States restrict hazardous air pollutant emissions from coating operations, while ECHA oversees substance restrictions under REACH Annex XVII in Europe. ISO 14024 environmental labeling and military specifications such as MIL-DTL-53039 govern product qualification pathways, creating differentiated compliance burdens across export markets. Stakeholders must monitor evolving multispectral threat environments and corresponding specification updates to align R&D investment with procurement cycles.
Market Dynamics
Multispectral threat detection capabilities are forcing coating formulators to engineer simultaneous suppression across visible, near-infrared, and thermal bands, compressing development cycles and raising qualification barriers for military procurement programs.
Growth Catalysts
- NATO naval modernization:Member states are retrofitting surface combatants with advanced marine camouflage systems that meet strict reflectance standards for littoral operations.
- REACH substance restrictions:ECHA mandates on volatile organic compounds are accelerating water-based and UV-curable formulation adoption across European defense supply chains.
- Graphene-enhanced nano coatings:Adaptive bandwidth performance in metamaterial-infused systems is opening new procurement categories for next-generation armored vehicle fleets.
Market Restraints
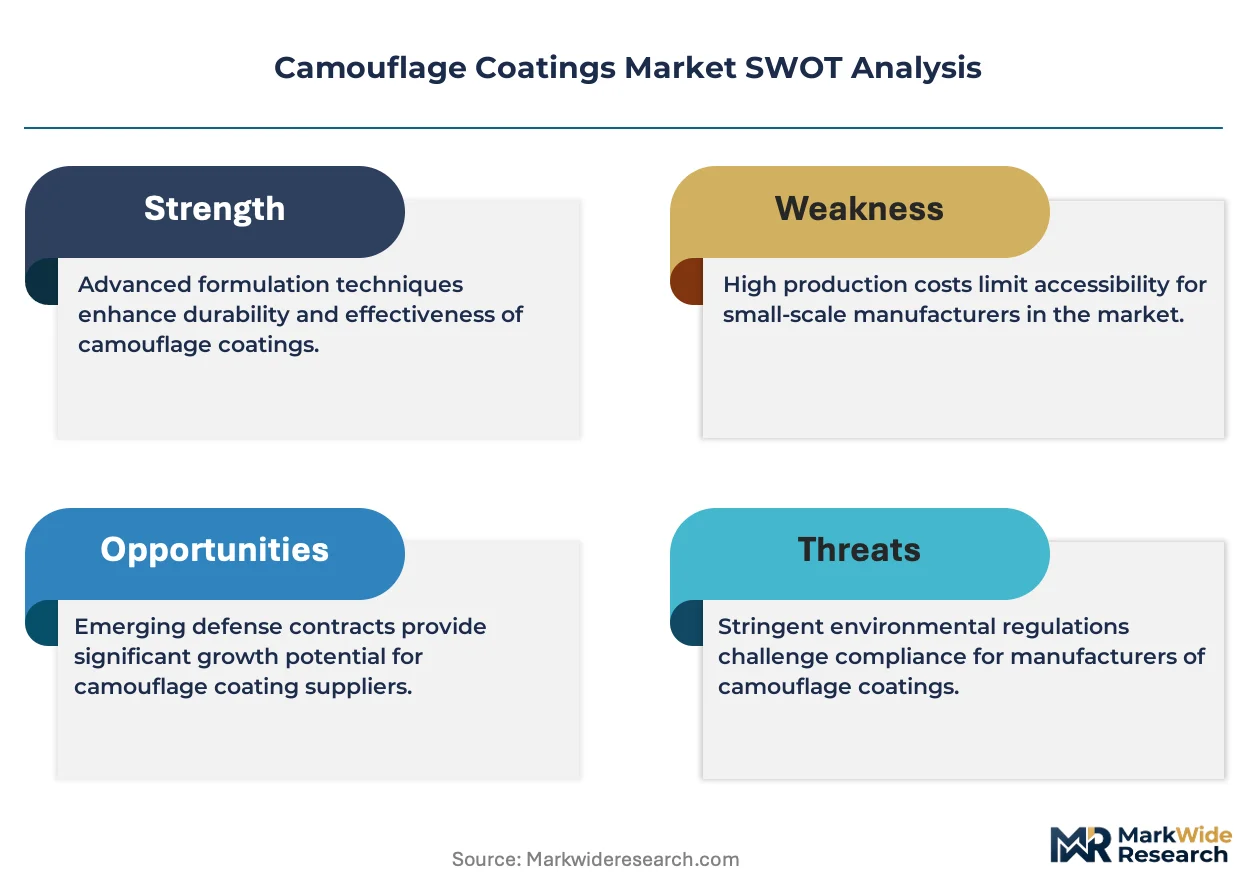
- Pigment precursor concentration:Specialized near-infrared reflective pigment supply concentrates among limited chemical manufacturers, creating input cost volatility.
- Aliphatic polyurethane feedstock exposure:Isocyanate and polyol pricing fluctuates with crude oil derivatives, squeezing margin stability for coating producers.
- Dual-use export controls:International Traffic in Arms Regulations and EU dual-use regulations restrict technology transfer for multispectral suppression formulations.
Strategic Opportunities
- Unmanned platform integration:Autonomous surface vessels and unmanned ground vehicles require standardized coating application protocols that legacy suppliers have not addressed.
- Field-repair service networks:Aftermarket touch-up and localized recoating infrastructure remains underdeveloped outside major military maintenance depots.
- Swiss defense procurement:Swiss Federal Office for Defence Procurement specifications for alpine terrain camouflage create niche demand for high-elevation thermal signature management.
Industry Challenges
- Multispectral testing infrastructure:Few independent laboratories possess simultaneous visible-NIR-thermal measurement capability, extending product validation timelines.
- Cross-certification complexity:MIL-DTL-53039 qualification does not automatically transfer to NATO STANAG equivalents, forcing redundant testing for export contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camouflage Coatings Market |
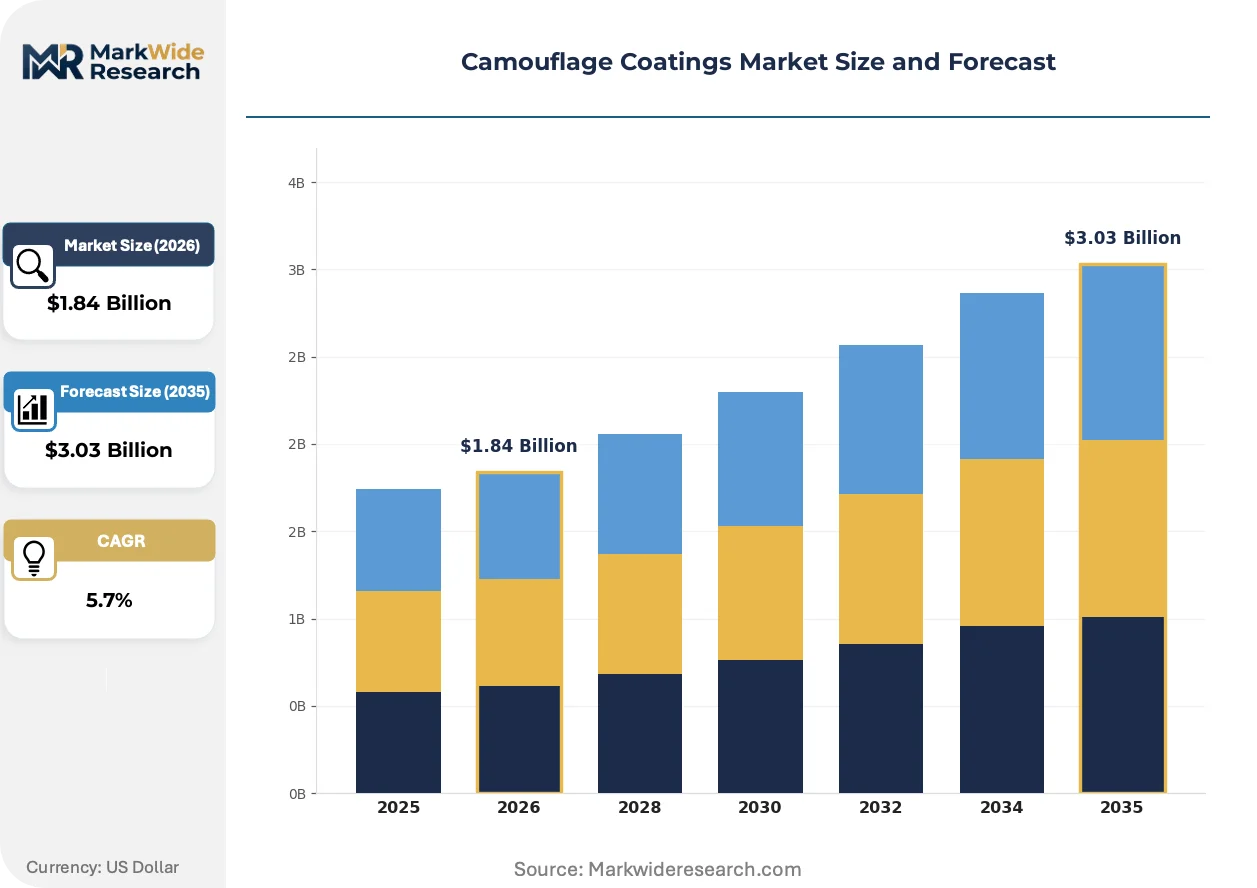
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.03 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coatings, Spray Coatings, Paste Coatings, Powder Coatings Application: Military Equipment, Aerospace Components, Consumer Goods, Industrial Machinery End User: Defense Forces, Aerospace Manufacturers, Outdoor Recreation Brands, Automotive Sector Technology: Water-Based Coatings, Solvent-Based Coatings, UV-Curable Coatings, Nano Coatings |
| Companies Covered | PPG Industries, Sherwin-Williams, AkzoNobel, Huntsman Corporation, Axalta Coating Systems, BASF SE, Hangzhou Epsilon Chemical, Nippon Paint Holdings, Spectrum Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camouflage Coatings Market Trends and Innovations
Adaptive signature management is displacing static camouflage across advanced military platforms, with chromic compounds and metamaterials enabling real-time spectral response to environmental conditions.
Electrochromic and thermochromic pigment systems are converging with conductive polymer substrates to create coatings that modulate emissivity in response to ambient temperature and illumination. Defense research agencies in the United States and United Kingdom are funding pilot programs for vehicle-scale demonstration. This convergence is compressing the development window for next-generation multispectral concealment from decade-long programs to five-year qualification cycles.
EPA hazardous air pollutant standards for coating operations are tightening permissible emission thresholds for solvent-based application processes. Military contractors operating fixed-site depots face capital expenditure requirements for abatement equipment or process conversion to water-based alternatives. Aerospace finishing facilities in California and Texas are disproportionately affected due to concentrated manufacturing presence and state-level air quality mandates.
Specification-driven procurement is consolidating buyer decision authority within centralized defense material agencies. Individual base-level maintenance units are losing autonomous sourcing power as NATO member states harmonize qualification requirements through STANAG frameworks. This concentration is most visible in Germany and France, where federal procurement offices now manage coating selection for all armored vehicle programs.
Camouflage Coatings Market Segmentation
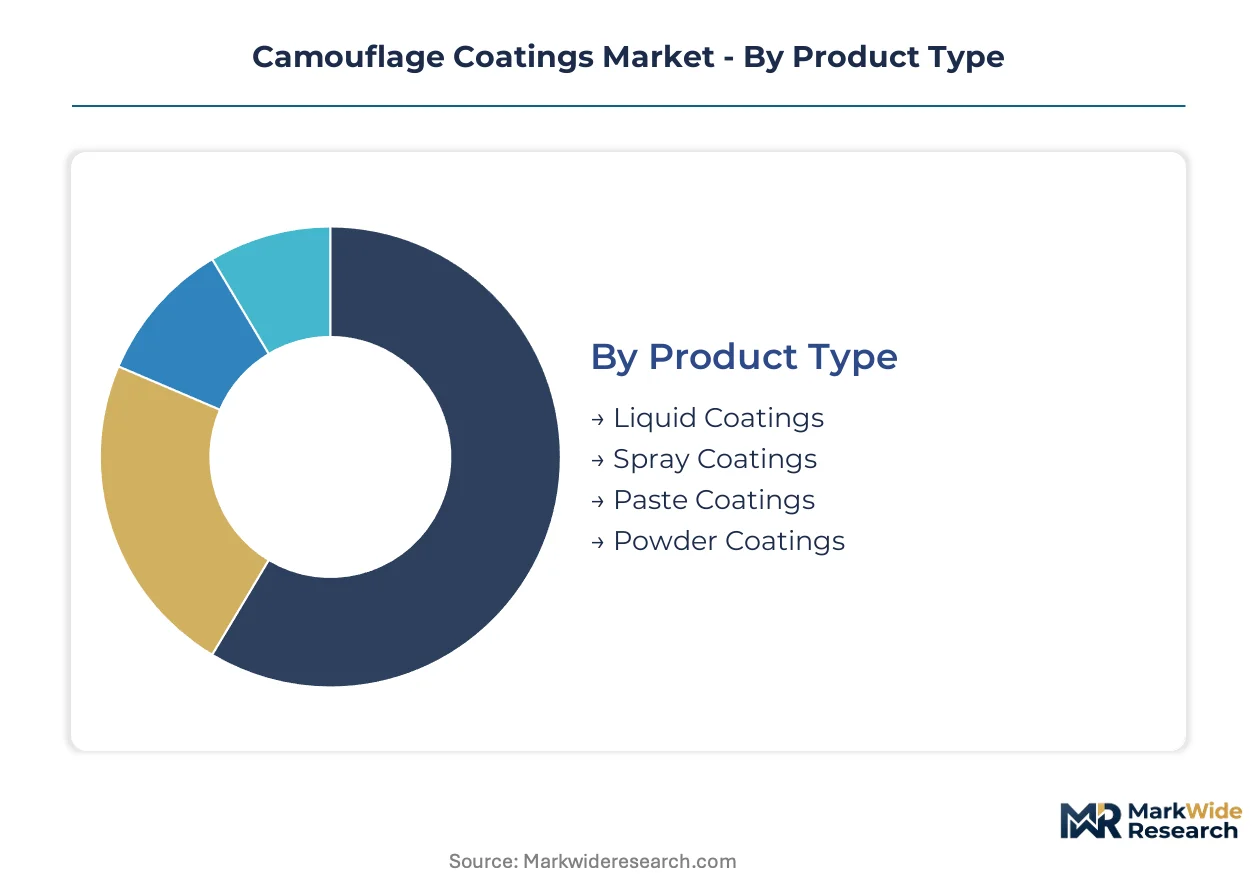
Segmentation in camouflage coatings reveals how formulation chemistry, application method, and end-use specifications create distinct procurement channels. Military buyers prioritize multispectral performance and field-repair compatibility, while commercial segments emphasize cost efficiency and aesthetic flexibility.
Product Type:
Customization intensity varies sharply across this category, from standardized bulk liquids to engineered spray systems requiring robotic calibration.
- Liquid Coatings:These formulations incorporate near-infrared reflective pigments and conductive fillers in solvent or water carriers, achieving solar reflectance below 0.30. Demand concentrates in United States Department of Defense armored vehicle programs, where field-repair compatibility and established depot infrastructure sustain procurement volume. EPA hazardous air pollutant standards are forcing conversion to water-based alternatives at fixed-site military depots.
- Spray Coatings:Atomized application systems deliver uniform thickness on complex aerospace geometries, with robotic platforms ensuring consistent emissivity modulation between 0.50 and 0.90. NATO naval modernization programs in Germany and France specify spray-applied marine systems meeting strict reflectance standards for littoral operations.
- Paste Coatings:High-viscosity formulations enable brush or trowel application in remote maintenance conditions without specialized equipment.
- Powder Coatings:Thermoset polymer systems offer zero volatile organic compound emissions and durability for industrial machinery in outdoor environments.
Most installed capacity flows through Liquid Coatings. Expansion is steepest in Spray Coatings.
Application:
Cost tier differentiation separates premium military specifications from commoditized consumer alternatives, with certification requirements creating order-of-magnitude price spreads.
- Military Equipment:Armored vehicles, naval vessels, and infantry systems require simultaneous suppression across visible, near-infrared, and thermal bands. United States defense modernization programs sustain premium consumption, while NATO STANAG harmonization is consolidating qualification pathways across member states.
- Aerospace Components:Fixed-wing and rotary platforms demand precise thickness control on radar-absorbent structures and engine nacelles. REACH substance restrictions are accelerating reformulation toward UV-curable alternatives in European supply chains.
- Consumer Goods:Hunting apparel and recreational equipment utilize simplified visible-spectrum camouflage without thermal management requirements.
- Industrial Machinery:Construction and agricultural equipment employs durable coatings for aesthetic branding and minimal signature reduction.
Military Equipment absorbs the majority of qualified supplier capacity. Aerospace Components are climbing the fastest as unmanned platform proliferation creates new specification categories.
End User:
Procurement authority concentration distinguishes centralized defense material agencies from fragmented commercial buyers with autonomous sourcing power.
- Defense Forces:Federal procurement offices in Germany and France now manage coating selection for all armored vehicle programs, eliminating base-level autonomy. Swiss Federal Office for Defence Procurement specifications for alpine terrain create niche demand for high-elevation thermal signature management.
- Aerospace Manufacturers:Tier-1 contractors in California and Texas face disproportionate EPA compliance burdens due to concentrated manufacturing presence and state-level air quality mandates.
- Outdoor Recreation Brands:Price-sensitive buyers prioritize visible-spectrum pattern variety over multispectral performance.
- Automotive Sector:Limited adoption for specialty vehicle wraps and concept demonstration platforms.
Defense Forces command the dominant share of qualified production. Aerospace Manufacturers are gaining share fastest as unmanned system integration creates standardized protocol demand.
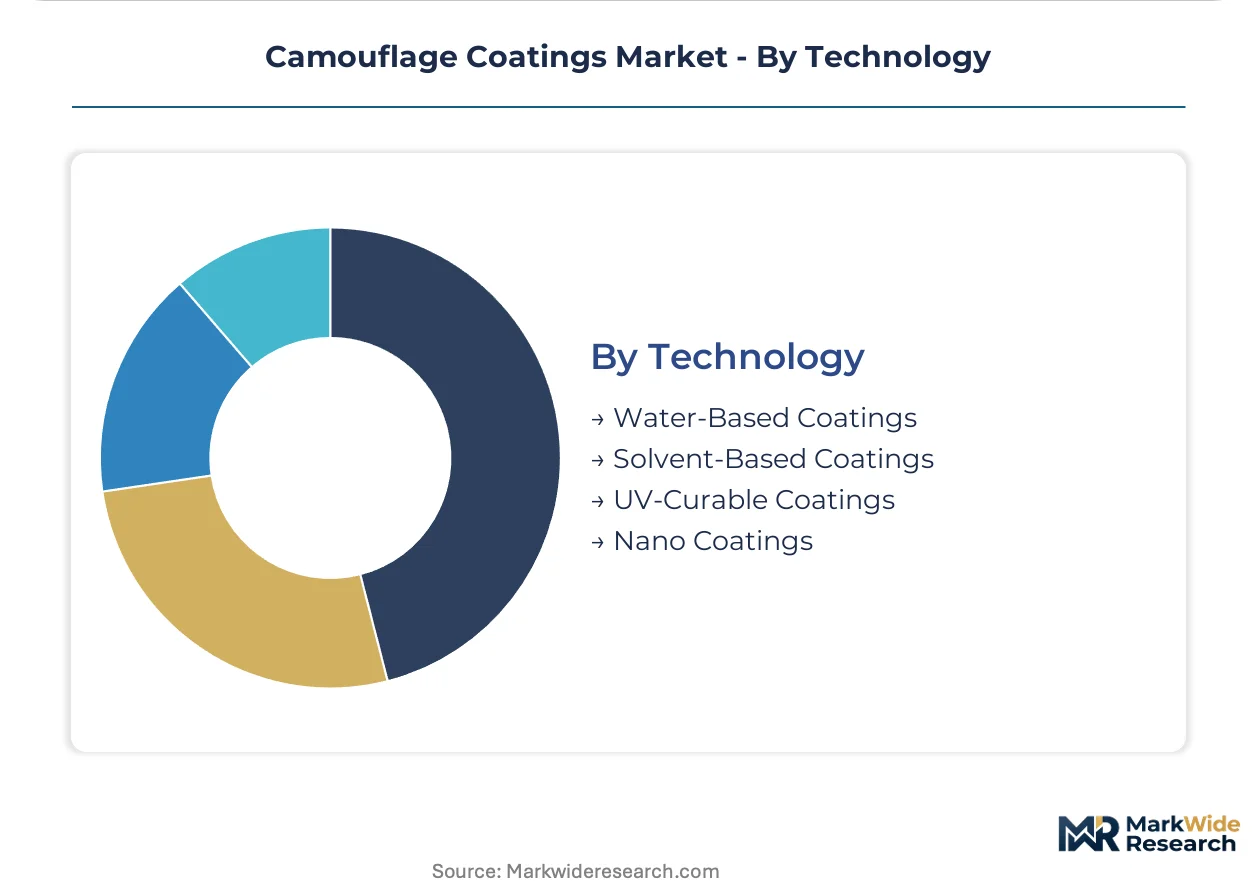
Technology:
Maturity gradients separate decades-old solvent systems from emerging nano-engineered platforms still navigating qualification barriers.
- Nano Coatings:Graphene-enhanced and metamaterial-infused formulations demonstrate adaptive bandwidth performance across environmental conditions. Defense research agencies in the United States and United Kingdom are funding vehicle-scale pilot programs, compressing development windows from decade-long cycles to five-year qualifications.
- Water-Based Coatings:Reformulated acrylic and polyurethane dispersions meet REACH Annex XVII restrictions while maintaining exterior durability. ECHA mandates on volatile organic compounds are accelerating adoption across European defense supply chains.
- Solvent-Based Coatings:Legacy aliphatic polyurethane systems face regulatory pressure but retain field-proven performance in extreme operational environments.
- UV-Curable Coatings:Rapid cure chemistry enables high-throughput aerospace finishing with minimal thermal exposure to sensitive substrates.
Solvent-Based systems retain the largest installed base. Nano Coatings are expanding most quickly as adaptive signature management displaces static camouflage across advanced platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement specialists and coating formulators cluster around established military-industrial corridors, with talent pools concentrated near major defense material agencies and aerospace finishing facilities.
United States
Department of Defense modernization programs and aftermarket refit cycles sustain premium coating consumption for armored vehicle fleets. EPA hazardous air pollutant standards tighten emission thresholds for solvent-based operations at fixed-site military depots. Aerospace finishing facilities in California and Texas face disproportionate compliance burdens due to concentrated manufacturing presence and state-level air quality mandates.
Germany
Federal procurement offices now manage coating selection for all armored vehicle programs, eliminating base-level autonomy in sourcing decisions. REACH substance restrictions mandate extensive toxicity documentation for imported resin precursors, realigning cost-of-entry for European suppliers. Industrial clusters in Bavaria and North Rhine-Westphalia host integrated pigment manufacturing networks that control raw material qualification timelines.
Switzerland
Federal Office for Defence Procurement specifications for alpine terrain camouflage create niche demand for high-elevation thermal signature management systems. National defense material standards exceed NATO baseline requirements for multispectral suppression in mountainous operational environments. Precision coating specialists in the Zurich-Bern corridor develop formulations for extreme altitude thermal contrast conditions.
United Kingdom
Defense research agencies fund pilot programs for vehicle-scale electrochromic and thermochromic coating demonstrations, compressing development windows from decade-long cycles to five-year qualifications. ECHA oversight of REACH Annex XVII restrictions affects cross-border supply chains for specialty pigment precursors. Aerospace and defense clusters in the Midlands and South East England coordinate with naval shipyards for marine camouflage system integration.
France
Centralized federal procurement offices harmonize coating selection across all armored vehicle programs under NATO STANAG frameworks. ECHA mandates on volatile organic compounds accelerate water-based and UV-curable formulation adoption across defense supply chains. Naval modernization programs at Atlantic and Mediterranean shipyards specify spray-applied marine systems meeting strict reflectance standards for littoral operations.
Camouflage Coatings Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive pigment supply and specialized coating formulators with military qualification expertise. Tier-1 suppliers with NATO STANAG certification capabilities occupy premium procurement channels, while regional specialists serve national defense material agencies with customized formulations. Two dominant archetypes emerge: integrated resin-pigment manufacturers controlling raw material timelines, and application-technology specialists with robotic aerospace finishing platforms. Competitive moves concentrate on backward integration into near-infrared reflective pigment production and strategic partnerships with unmanned platform integrators.
Among North American coating conglomerates, PPG Industries and Sherwin-Williams exemplify integrated manufacturing archetypes with established defense supply relationships. AkzoNobel represents the European specialist model with marine system expertise aligned to NATO naval standards. These three anchors demonstrate how geographic origin and corporate structure map to distinct qualification pathways in specification-driven procurement environments.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams |
| AkzoNobel |
| Huntsman Corporation |
| Axalta Coating Systems |
| BASF SE |
| Hangzhou Epsilon Chemical |
| Nippon Paint Holdings |
| Spectrum Coatings |
| Others |
Pricing and Supply Chain Analysis
NATO STANAG harmonization for multispectral coating qualification is compressing supplier approval timelines and forcing raw material standardization that elevates input costs for non-integrated formulators. Defense procurement offices in Germany and France now mandate unified pricing frameworks across armored vehicle programs, stripping base-level buyers of volume discount leverage and consolidating price-setting authority with tier-1 suppliers holding captive pigment production.
Pricing Analysis
Bundled coating-application service contracts dominate military procurement, separating premium integrators with robotic aerospace platforms from unbundled material suppliers competing on resin cost. Price differentiation rests on NATO STANAG certification tier and after-sales field-repair network coverage. Cost compression in water-based reformulations is intensifying because REACH-mandated VOC compliance requires capital-intensive abatement equipment. Commercial outdoor recreation buyers exhibit highest price sensitivity, while defense material agencies prioritize performance over unit cost.
Supply Chain Analysis
Near-infrared reflective pigment supply rests on German, Japanese, and United States specialty chemical producers with limited qualified alternative sources. Aliphatic polyurethane precursors draw from crude oil derivatives, while conductive fillers and chromic compounds hinge on rare earth processing concentrated in China. Single-source vulnerability for metamaterial inputs creates procurement risk for nano-coating developers. Distribution runs through defense material agencies and tier-1 aerospace contractors with qualified supplier status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in camouflage coatings rests on water-based formulation conversion lowering VOC compliance costs and premium-tier nano-coating adoption displacing legacy solvent systems. Cost-down drivers in raw material standardization and application automation support sustainable profitability improvement.
For Market Incumbents: Hedge against REACH regulatory escalation by accelerating captive production of near-infrared reflective pigments in European industrial clusters. Backward integration into conductive filler supply reduces exposure to Chinese rare earth export volatility. Certification investment in unmanned platform coating protocols defends positioning against emerging robotics specialists. For New Entrants and Emerging Players: Direct-to-defense-procurement digital platforms offer lowest-friction entry for qualified coating formulations bypassing legacy distributor networks. Swiss alpine terrain specifications and unmanned ground vehicle aftermarket touch-up services represent penetrable white-space segments. Target field-repair service networks with portable application systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing NATO STANAG certification and robotic aerospace finishing capabilities. Long-term viability over a multi-year horizon favors suppliers with integrated resin-pigment manufacturing and adaptive nano-coating pipelines. Watch for unmanned platform procurement volume inflection as the signal for next-generation coating demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Production | Captive supply of near-infrared reflective pigments compresses ECHA qualification timelines for European defense contracts. |
| Water-Based Formulation Conversion | REACH Annex XVII compliance eliminates solvent-based VOC exposure while maintaining MIL-DTL-53039 performance benchmarks. |
| Robotic Aerospace Finishing Platform Deployment | Automated spray systems ensure uniform emissivity modulation on complex engine nacelle geometries for NATO naval programs. |
| Unmanned Platform Coating Protocol Development | Standardized application specifications for autonomous vehicles address procurement gaps left by legacy military suppliers. |
| Field-Repair Service Network Expansion | Localized touch-up infrastructure outside major depots captures aftermarket revenue from expeditionary maintenance units. |
Research Methodology
Multiple input streams — defense procurement officer interviews, coating formulator technical assessments, and regulatory documentation analysis — were reconciled to construct segment-level demand estimates. Primary conversations with military material agency directors, aerospace finishing facility managers, specialty chemical procurement leads, and nano-coating R&D directors informed qualification pathway and technology adoption assumptions. Secondary validation drew from EPA hazardous air pollutant filings, ECHA REACH substance registrations, NATO STANAG specification databases, and Department of Defense modernization program disclosures. Bottom-up coating volume estimates by platform type and top-down defense budget allocation analysis were cross-referenced for convergence.
Historical procurement patterns were cross-referenced against expert panel input on electrochromic and thermochromic development timelines to anchor projection parameters across the analysis window. Segmentation modeling incorporated formulation chemistry, application method, end-use specification tier, and technology maturity gradients. CAGRs were derived from defense budget trajectory alignment and platform retrofit cycle phasing. Industry-specific inputs included multispectral threat environment evolution, unmanned system integration rates, and regulatory compliance cost curves for water-based alternatives.
The model assumes a particular technology adoption path; alternative pathways for graphene-enhanced adaptive coatings achieving faster vehicle-scale qualification would alter the outlook. Forecasts reflect documented assumptions regarding NATO procurement harmonization pace and REACH enforcement stringency. Regulatory reversal on VOC thresholds, breakthrough metamaterial cost reduction, or unmanned platform procurement acceleration constitute triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Protective and Marine Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Cold Gas Spray Coating Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Fillers and Coating Market
Coatings
Europe Thermal Spray Market
Coatings
Self-Cleaning Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
Anti-Microbial Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Global Flat Glass Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Europe Anti-Friction Coatings Market