
 North America Thermal Spray Market | 2026-2036
North America Thermal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermal Spray Market Analytics
High-performance ceramic coating specifications are rotating toward thicker, multi-layer thermal barrier systems capable of withstanding peak gas-path temperatures above 1,200°C in advanced turbine architectures. Oerlikon Metco leverages its integrated powder-manufacturing and coating-equipment portfolio to anchor supply security for aerospace OEM qualification programs. Praxair Surface Technologies sustains dominance in industrial gas turbine aftermarket services through its network of regional coating centers across the United States and Canada. Kennametal Stellite specializes in cobalt-based wear-resistant overlays for oilfield drilling components, competing on material formulation depth rather than equipment breadth.
Thermal spray encompasses the deposition of molten or semi-molten metallic, ceramic, or composite materials onto substrates via combustion flame, electric arc, or plasma jet, producing functional coatings typically 50 micrometers to several millimeters thick with bond strengths exceeding 40 MPa in optimized HVOF processes. The technology serves primarily to extend component life in extreme-service environments where bulk material replacement proves economically impractical. Powder feedstock commands the largest value share among product types, driven by the complexity of gas-atomized and sintered-and-crushed ceramic formulations required for aerospace thermal barriers. HVOF technology leads growth velocity among deposition methods, displacing conventional flame spraying in corrosion-sensitive applications due to its denser, lower-porosity coating structures. Wear resistance applications constitute the most mature segment, while thermal barrier coatings concentrate the highest margin pools through OEM qualification barriers and specialized powder requirements.
The FAA's Parts Manufacturer Approval process governs thermal spray coatings for commercial aviation engine and airframe components, creating multi-year qualification timelines that protect incumbent suppliers. EPA NESHAP regulations for chromium electroplating and surface coating operations continue to drive substrate-level substitution toward thermal spray alternatives, particularly for hard chrome replacement in landing gear and hydraulic rods. The Department of Energy's efficiency mandates for industrial gas turbines indirectly expand addressable coating surface area per unit. Stakeholders must monitor the trajectory of FAA certification reform initiatives and EPA hazardous air pollutant rulemakings to anticipate qualification cost shifts and process technology substitution timelines.
Market Dynamics
The US Gulf Coast industrial corridor concentrates petrochemical maintenance demand while EPA NESHAP emission thresholds tighten, forcing process technology substitution across surface coating operations.
Growth Catalysts
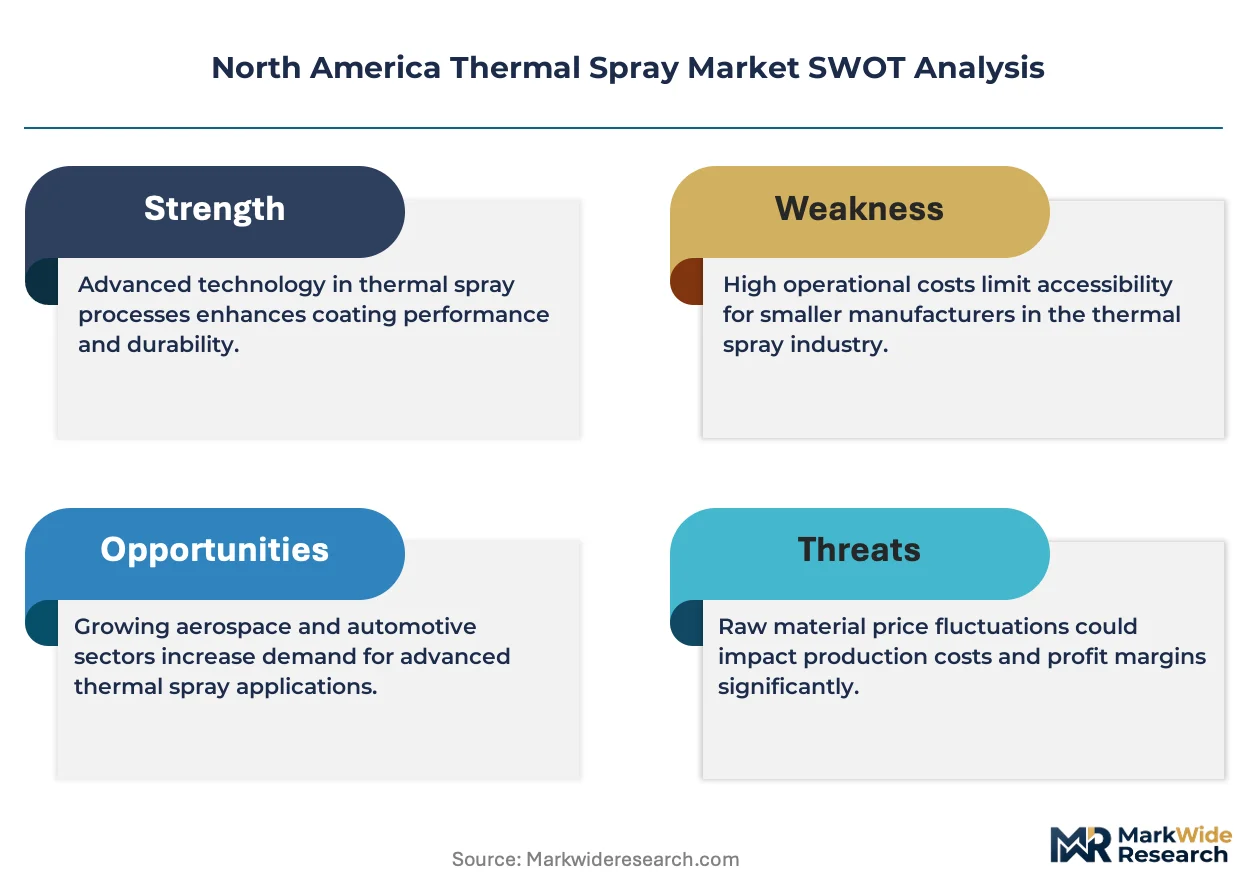
- Aerospace coating programs:Turbine blade and combustor specifications are expanding toward thicker multi-layer thermal barrier systems capable of withstanding peak gas-path temperatures above 1,200°C in advanced engine architectures.
- EPA NESHAP substitution mandate:The National Emission Standards for Hazardous Air Pollutants for chromium electroplating and surface coating operations drives substrate-level replacement of hard chrome with thermal spray alternatives in landing gear and hydraulic rods.
- HVOF technology advancement:High-velocity oxygen fuel deposition methods produce denser, lower-porosity coating structures that displace conventional flame spraying in corrosion-sensitive applications across energy sector capital projects.
Market Restraints
- Feedstock supply concentration:Gas-atomized and sintered-and-crushed ceramic formulations required for aerospace thermal barriers depend on a limited number of qualified powder manufacturers, creating qualification bottlenecks for new entrants.
- FAA certification timelines:The Parts Manufacturer Approval process for commercial aviation engine and airframe components imposes multi-year qualification periods that protect incumbent suppliers and delay revenue recognition for coating providers.
- Plasma spray equipment capex:Automated plasma deposition systems for thermal barrier coatings require substantial capital investment, restricting market participation to well-capitalized service providers with established OEM relationships.
Strategic Opportunities
- Texas-Louisiana petrochemical corridor:Maintenance cycles at refineries and chemical plants along the Gulf Coast generate recurring demand for wear-resistant overlays on pumps, valves, and processing equipment.
- Department of Energy efficiency mandates:Industrial gas turbine efficiency requirements indirectly expand addressable coating surface area per unit, creating volume pull for thermal barrier and corrosion protection services.
- Cold spray technology convergence:Solid-state deposition methods that avoid melting are emerging as complementary processes for temperature-sensitive substrates, opening repair applications previously excluded from thermal spray scope.
Industry Challenges
- Coating technician skill scarcity:Proficiency in parameter optimization for HVOF and plasma spray processes requires years of hands-on experience, constraining service capacity expansion regardless of equipment availability.
- Legacy system integration friction:Automated thermal spray cells must interface with existing manufacturing execution systems and quality databases, complicating deployment timelines at aerospace OEM facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermal Spray Market |
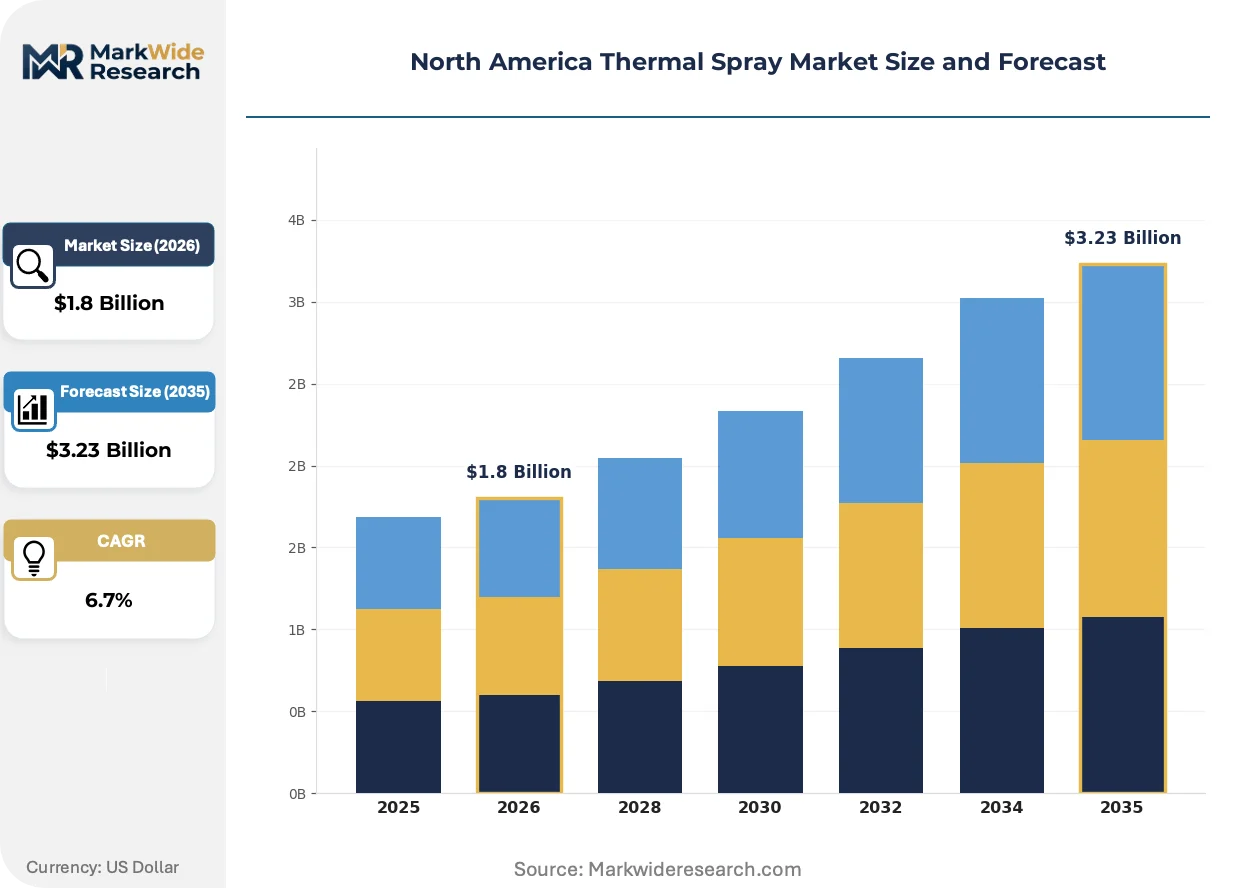
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire, Powder, Liquid, Tape Technology: Flame Spraying, Plasma Spraying, Arc Spraying, HVOF End User: Aerospace, Automotive, Energy, Medical Application: Wear Resistance, Thermal Barrier, Corrosion Protection, Electrical Conductivity |
| Companies Covered | Praxair Surface Technologies, Oerlikon Metco, Kennametal Stellite, H.C. Starck, Carpenter Technology Corporation, United Coatings Technologies, APS Materials, United Thermal Dynamics, Plasma-Tec, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermal Spray Market Evolving Landscape
Process automation and real-time monitoring systems are compressing coating variability while regulatory pressure accelerates technology substitution away from electroplating methods.
Cold spray deposition is displacing traditional thermal methods for repair of magnesium and aluminum aerospace components where heat input must be minimized. Airlines and MRO providers in the US Southwest are adopting these systems for on-site blade restoration. The structural consequence is fragmentation of the repair market into heat-limited and heat-tolerant application categories with different equipment requirements.
EPA NESHAP rulemakings for surface coating operations continue tightening permissible emission thresholds for spray processes. Industrial coating facilities across the Midwest and Southeast are retrofitting capture and control systems or migrating to lower-emission thermal spray alternatives. The affected segment is hard chrome replacement in hydraulic actuators and landing gear, where thermal spray now dominates new specification writing.
OEMs are consolidating supplier qualification lists to reduce audit burden and ensure supply security. Tier-one aerospace manufacturers now require coating providers to maintain captive powder manufacturing or exclusive feedstock partnerships. This concentration is most visible in the Pacific Northwest and Southern California aerospace clusters, where qualified thermal spray vendors have narrowed to a handful of integrated service providers.
North America Thermal Spray Market Segmentation
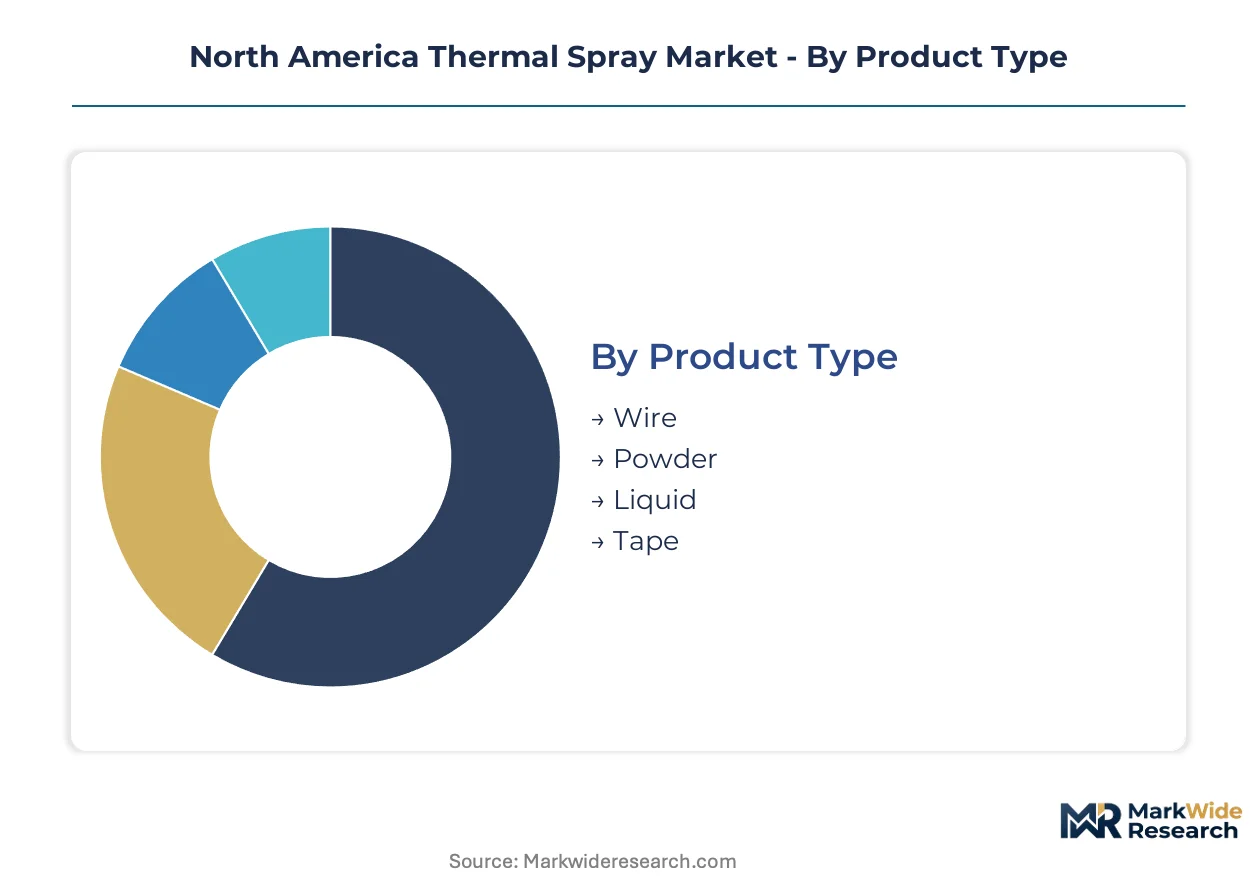
Segmentation in thermal spray reveals distinct supply chain pathways where powder feedstock flows through aerospace OEM qualification channels while wire products serve industrial maintenance through regional service centers. Channel configuration directly shapes margin capture and customer lock-in intensity across the value chain.
Product Type:
Powder commands premium positioning through aerospace channels, while wire and liquid products distribute through industrial maintenance networks with faster inventory turns.
- Powder:Gas-atomized and sintered-and-crushed ceramic formulations enable thermal barrier coatings for turbine blades. Demand clusters in Southern California and Pacific Northwest aerospace manufacturing corridors where OEM qualification programs require specialized feedstock chemistry.
- Wire:Solid and cored wire feedstocks support combustion flame and arc spraying for corrosion protection on petrochemical infrastructure. The US Gulf Coast industrial corridor generates recurring volume for nickel-based and zinc-aluminum wire products in refinery maintenance cycles.
- Liquid:Suspension and solution precursor feedstocks enable nanostructured coating architectures for medical device applications.
- Tape:Flexible composite tapes support automated deposition of abradable seal coatings in gas turbine compressors.
Powder dominates installed base. Wire is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive plasma systems serving aerospace from portable flame equipment deployed in field maintenance.
- HVOF:High-velocity oxygen fuel deposition produces dense, low-porosity metallic coatings with bond strengths exceeding 40 MPa. Landing gear and hydraulic rod applications across Midwest and Southeast manufacturing facilities are displacing hard chrome electroplating under EPA NESHAP pressure.
- Plasma Spraying:High-temperature plasma jets deposit ceramic thermal barrier coatings capable of withstanding peak gas-path temperatures above 1,200°C. Aerospace engine manufacturers in Connecticut and Ohio specify multi-layer plasma-sprayed systems for turbine blade hot sections.
- Flame Spraying:Combustion-driven deposition remains the lowest-cost entry point for corrosion protection on structural steel.
- Arc Spraying:Twin-wire electric arc systems offer high deposition rates for large-area industrial applications.
Flame spraying retains the broadest installed base. HVOF is climbing the fastest.
End User:
Application maturity varies sharply: aerospace demands qualification-intensive thermal barriers while automotive and energy sectors prioritize wear resistance and corrosion protection with faster specification cycles.
- Aerospace:Commercial aviation engine and airframe components require FAA Parts Manufacturer Approval for thermal spray coatings, creating multi-year qualification timelines. Turbine blade and combustor programs are expanding coating surface area per unit as engine architectures advance.
- Energy:Industrial gas turbines and oilfield drilling equipment drive demand for wear-resistant overlays. The Texas-Louisiana petrochemical corridor generates recurring maintenance cycles for pumps, valves, and processing equipment.
- Automotive:Powertrain and chassis components utilize thermal spray for cylinder bore coatings and suspension wear surfaces.
- Medical:Orthopedic implants and surgical instruments employ hydroxyapatite and biocompatible coatings for bone integration.
Aerospace concentrates the highest margin pools. Energy is where volume expansion accelerates.
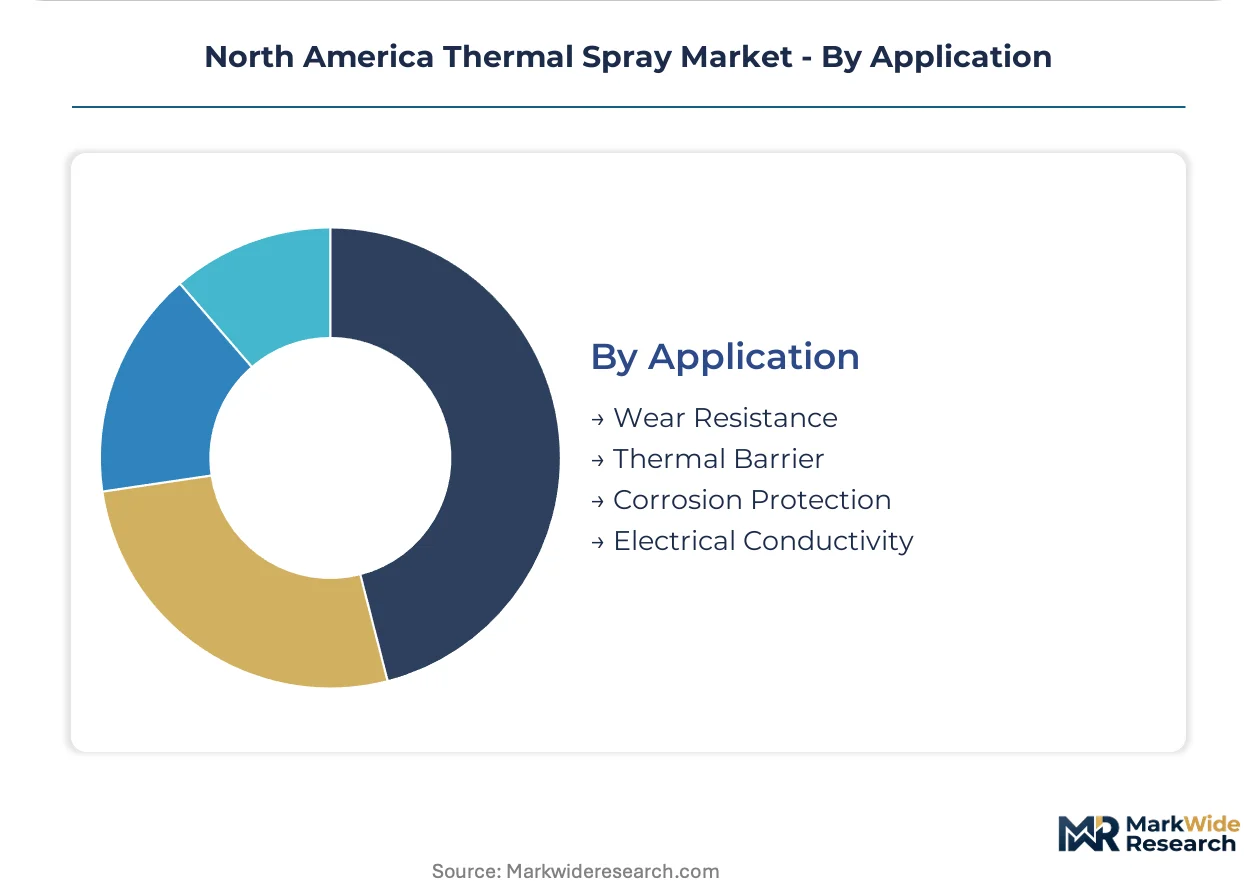
Application:
Margin structure inverts across applications: wear resistance operates as a mature, price-competitive segment while thermal barriers command qualification premiums.
- Thermal Barrier:Multi-layer ceramic coating systems insulate turbine components from extreme gas-path temperatures. OEM qualification barriers and specialized powder requirements protect incumbent suppliers in Pacific Northwest and Southern California aerospace clusters.
- Wear Resistance:Cobalt-based and tungsten carbide overlays extend component life in abrasive and erosive environments. Oilfield drilling components in Texas and Oklahoma represent a concentrated demand pocket where material formulation depth determines competitive position.
- Corrosion Protection:Zinc, aluminum, and alloy coatings protect steel substrates in marine and chemical environments.
- Electrical Conductivity:Copper and silver-based coatings provide EMI shielding and current-carrying surfaces.
Wear resistance holds the broadest installed base. Thermal barrier is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified powder manufacturers and coating service providers cluster along aerospace manufacturing corridors and petrochemical maintenance hubs. The United States dominates installed capacity while Canada and Mexico concentrate in niche feedstock and cross-border maintenance operations.
United States
Commercial aviation engine programs in Connecticut and Ohio drive demand for multi-layer thermal barrier systems. The FAA's Parts Manufacturer Approval process governs coating qualifications for turbine blades and airframe components. The US Gulf Coast industrial corridor generates recurring maintenance cycles for wear-resistant overlays on pumps and valves at refineries and chemical plants.
Canada
Oil sands extraction equipment in Alberta requires cobalt-based wear-resistant coatings for drilling and processing components. Environment and Climate Change Canada regulates air pollutant emissions from surface coating operations under the Canadian Environmental Protection Act. Ontario's manufacturing belt around Toronto hosts regional coating centers serving automotive and industrial gas turbine aftermarket demand.
Mexico
Automotive powertrain manufacturing in Querétaro and Guanajuato creates demand for cylinder bore and thermal spray coatings. The Secretariat of Environment and Natural Resources enforces emissions standards for industrial surface finishing operations. The northern border states concentrate maquiladora operations performing coating services for US aerospace and energy sector supply chains.
North America Thermal Spray Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Thermal Spray Market. Integrated powder-equipment portfolios and specialized coating service networks constitute distinct strategic positions. Three archetypes dominate: captive powder manufacturers with equipment integration, regional service providers with OEM qualification relationships, and material specialists competing on formulation depth. Competitive moves concentrate on supplier list consolidation by aerospace OEMs and geographic expansion of coating center networks along industrial corridors.
Within the integrated powder-equipment tier, Oerlikon Metco exemplifies supply security positioning for aerospace qualification programs. Praxair Surface Technologies occupies a scale-driven position through its regional coating center network across the United States and Canada. Kennametal Stellite represents material formulation depth in cobalt-based wear-resistant overlays for oilfield applications. These three anchors illustrate how qualification barriers, geographic coverage, and specialization depth create defensible market positions.
| Leading Market Players |
|---|
| Praxair Surface Technologies |
| Oerlikon Metco |
| Kennametal Stellite |
| H.C. Starck |
| Carpenter Technology Corporation |
| United Coatings Technologies |
| APS Materials |
| United Thermal Dynamics |
| Plasma-Tec |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between aerospace OEMs and qualified powder manufacturers lock in supply access while anchoring price visibility across multi-year qualification cycles. The EPA NESHAP emission thresholds reshape cost structures for coating service providers, forcing capital deployment into capture systems that compress margin flexibility.
Pricing Analysis
EPA NESHAP dictates the pricing tier structure across thermal spray service providers, separating qualified aerospace vendors from industrial maintenance operators. Pricing stratifies across FAA-certified premium tiers, EPA-compliant standard tiers, and non-certified economy tiers. Cost compression in standard tiers intensifies because hard chrome replacement volumes attract price-competitive entrants. Industrial energy and petrochemical segments exhibit highest price sensitivity, while aerospace engine programs demonstrate lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Port congestion at Long Beach and Houston anchors inbound logistics costs for gas-atomized ceramic powders sourced from European and Asian specialty manufacturers. Supply concentrates in the United States for aerospace-qualified coating services, Germany and Switzerland for precision powder manufacturing, and China for commodity wire feedstocks. Raw material dependencies rest on cobalt alloys for wear overlays, yttria-stabilized zirconia for thermal barriers, and nickel-chromium bond coats. Single-source vulnerability permeates aerospace-qualified powder formulations. Distribution runs through regional coating centers serving OEM direct accounts and industrial maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cold spray interoperability with existing thermal spray cells creates new repair ecosystem entry points. Equipment-software integration standards are fragmenting competitive moats between deposition technology providers.
For Market Incumbents: Secure captive powder manufacturing capacity or exclusive feedstock partnerships before OEM supplier list consolidation completes. HVOF equipment standardization threatens differentiation; defend through embedded process parameter libraries and technician certification programs. Cold spray entrants erode repair market share; counter with hybrid cell offerings. For New Entrants and Emerging Players: Anchor in the Texas-Louisiana petrochemical corridor where maintenance cycles generate recurring demand without FAA qualification barriers. The automotive cylinder bore segment offers fastest specification cycles and lowest incumbent lock-in. Lead with portable HVOF systems and rapid-response service contracts. For Investors and Strategic Acquirers: Regional coating center networks with established OEM relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory substitution tailwinds from EPA NESHAP and DOE efficiency mandates. Watch cold spray equipment adoption rates at US Southwest MRO facilities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Manufacturing | Captive supply of gas-atomized ceramics secures aerospace qualification timelines against feedstock bottlenecks. |
| Cold Spray Technology Deployment | Solid-state deposition opens magnesium and aluminum repair applications previously excluded from thermal spray scope. |
| Regional Coating Center Expansion | Proximity to US Gulf Coast petrochemical clusters captures recurring maintenance cycles on pumps and valves. |
| Automated Process Control Investment | Real-time parameter monitoring compresses coating variability for FAA Parts Manufacturer Approval compliance. |
| Hard Chrome Replacement Program | EPA NESHAP-driven substitution creates specification pull for HVOF coatings on landing gear and hydraulic rods. |
Research Methodology
Cross-validation between primary interviews with coating service technicians, powder manufacturing engineers, aerospace OEM procurement managers, and EPA compliance officers anchors the qualitative findings. Secondary validation draws from FAA Parts Manufacturer Approval databases, EPA NESHAP regulatory filings, Department of Energy efficiency mandate documents, and customs trade records for feedstock imports. Bottom-up demand modeling triangulates against top-down market sizing across technology and end-use dimensions.
Sensitivity analysis around EPA regulatory enforcement timelines and FAA certification reform initiatives stress-tests projection ranges across the analysis window. Segmentation dimensions modeled include deposition technology, feedstock product type, end-use industry, application function, and regional industrial corridor. CAGRs derive from installed base expansion rates and replacement cycle analysis. Forecast inputs incorporate aerospace engine program ramp schedules and petrochemical capital project pipelines.
Material uncertainties — EPA rulemaking acceleration, cold spray technology substitution rates, powder manufacturer qualification bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory substitution timelines and OEM supplier consolidation trajectories. Recalibration cycles align with material shifts in FAA certification reform and hazardous air pollutant threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Coating Market
Coatings
Global Waterborne Coatings Market
Coatings
Vietnam Architectural Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Dispersion Coating Market
Coatings
Anti Soiling Coating Market
Coatings
Japan Marine Coatings Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Emulsion Coatings Market