
 South Korea Commercial Vehicles Lubricants Market | 2026-2036
South Korea Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Commercial Vehicles Lubricants Market Analytics
A capital-intensity divergence between integrated refiners and independent blenders is reorganizing competitive dynamics in South Korea's commercial vehicle lubricants sector. GS Caltex leverages its Yeosu refinery complex to secure captive base oil supply for heavy-duty engine formulations. SK Lubricants Co. Ltd anchors its position through Group III synthetic capacity and OEM partnerships with domestic truck manufacturers.
Commercial vehicles lubricants are formulated lubricating fluids engineered to protect diesel and gasoline engines, transmissions, axles, and hydraulic systems operating under high load cycles, with viscosity grades typically spanning SAE 15W-40 to 5W-30 for modern low-emission engines. Engine oil commands the largest revenue pool due to high consumption frequency and OEM specification complexity, while synthetic and semi-synthetic formulations within this category capture expanding margin pools as fleet operators extend drain intervals. Gear oil and hydraulic fluid segments serve construction and freight applications where equipment uptime requirements drive premium product selection.
MFDS standards for chemical substance management, Ministry of Environment emission regulations under the Special Act on Fine Dust Reduction, and KSA quality certifications collectively mandate cleaner-burning, lower-ash lubricant formulations for commercial diesel fleets. These frameworks elevate compliance costs for smaller blenders while rewarding refiners with in-house additive development. Stakeholders must track how carbon-neutral fleet transition timelines reshape lubricant specification requirements and service bundling models.
Market Dynamics
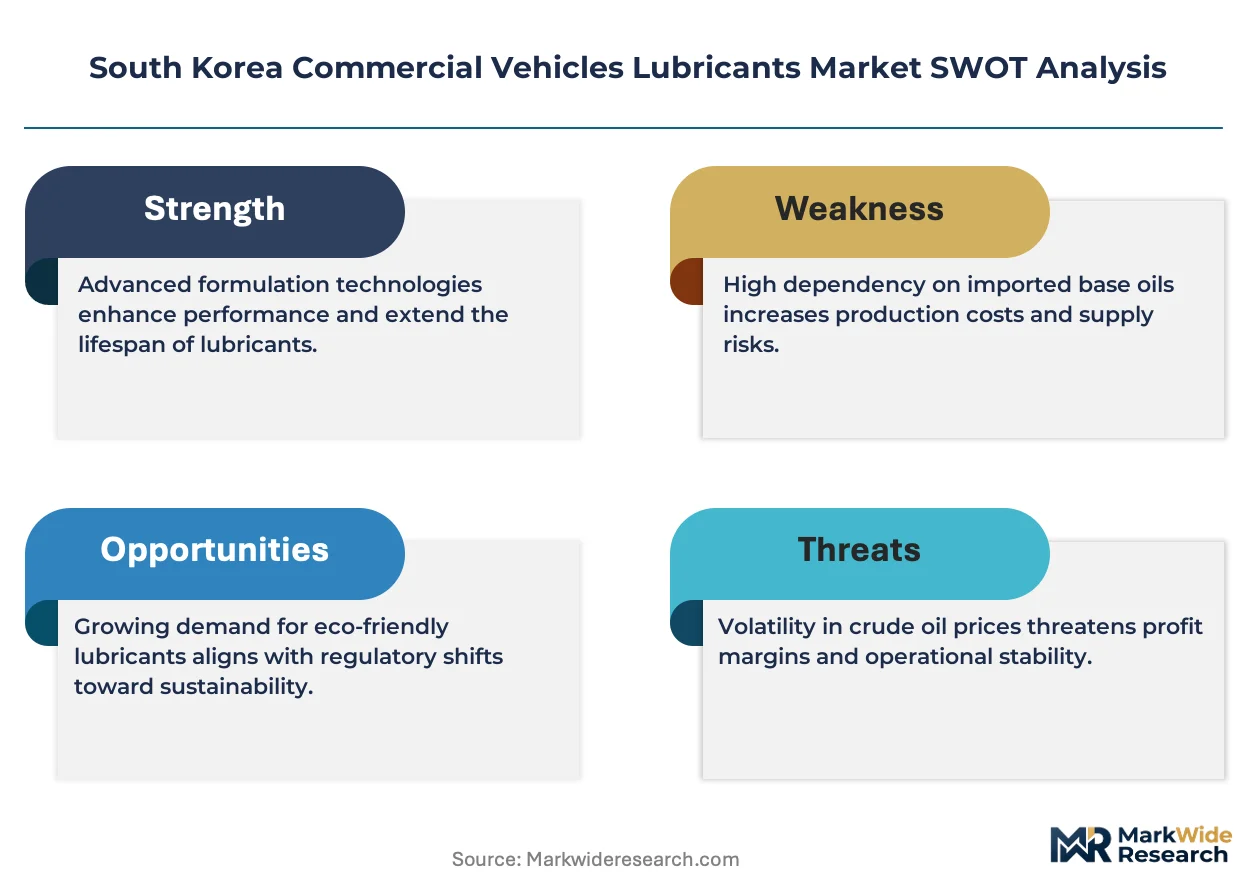
MFDS chemical substance mandates and the Ministry of Environment's Special Act on Fine Dust Reduction are forcing reformulation of commercial diesel lubricants toward lower-ash, cleaner-burning specifications. Integrated refiners with captive additive development capabilities capture margin from smaller blenders facing compliance cost escalation.
Growth Catalysts
- Seoul metropolitan fleet electrification timelines:Hybrid commercial vehicle penetration sustains demand for specialized transmission fluids and thermal management lubricants during the transition period.
- Construction equipment uptime requirements:Busan-Ulsan industrial corridor operators specify premium hydraulic fluids to minimize unscheduled maintenance on excavators and loaders.
- KSA quality certification expansion:Mandatory third-party testing for heavy-duty engine oils elevates barrier to entry for low-grade imports, protecting domestic formulation specialists.
Market Restraints
- Group II/III base oil import dependency:South Korea relies on regional supply chains for high-viscosity index feedstocks, exposing blenders to shipping cost volatility and currency fluctuation.
- Additive package concentration:Four multinational chemical suppliers control pour point depressant and anti-wear chemistry, limiting negotiating leverage for mid-size domestic blenders.
- Drain interval extension engineering:OEM-specified synthetic formulations now achieve 100,000-kilometer service cycles, compressing per-vehicle lubricant consumption volume.
Strategic Opportunities
- Gwangju-Daejeon logistics corridor expansion:E-commerce fulfillment center construction is generating fleet deployment outside the traditional Seoul-Busan axis, creating geographic white space for service bundling.
- Carbon-neutral fleet certification incentives:Ministry of Environment low-emission vehicle subsidies reward operators using bio-based hydraulic fluids, opening premium positioning for renewable formulation developers.
- Predictive maintenance platform integration:Telematics-enabled oil condition monitoring allows lubricant suppliers to embed fluid analytics within fleet management software, shifting revenue from product to service.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) diesel engine oils remains concentrated among retiring specialists at major refiners.
- OEM approval timeline compression:Accelerated vehicle model cycles demand faster lubricant certification against evolving ACEA and API specifications, straining R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Commercial Vehicles Lubricants Market |
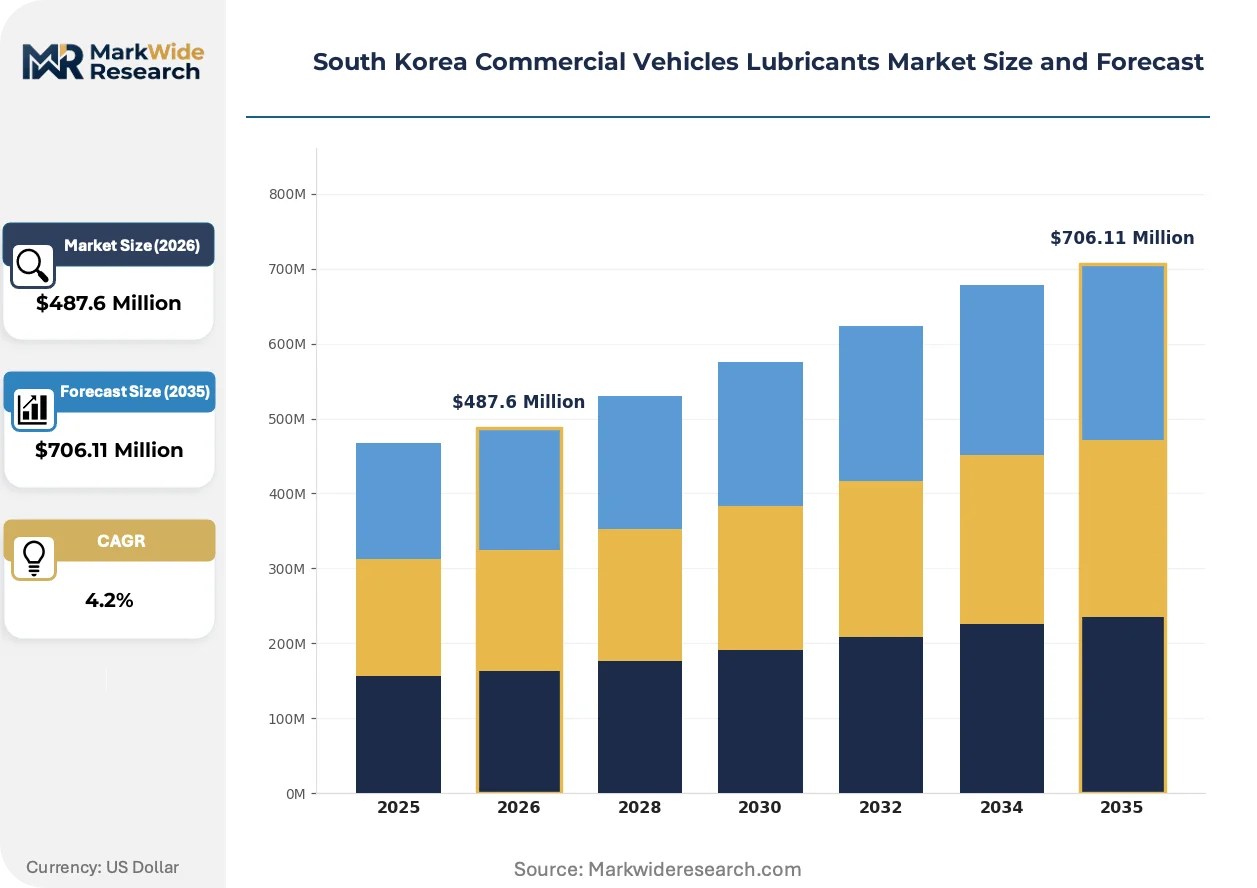
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $706.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Grease, Hydraulic Fluid End User: Logistics Companies, Freight Carriers, Public Transport, Construction Firms Distribution Channel: Retail, Wholesale, Online, Direct Sales Service Type: Maintenance, Repair, Engine Services, Diagnostic Services |
| Companies Covered | GS Caltex, SK Lubricants Co. Ltd, S-Oil Corporation, Hyundai Oilbank, ExxonMobil Corporation, BP PLC (Castrol), Royal Dutch Shell Plc, FUCHS, Valvoline Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic base oil technology and digital fleet management tools are restructuring how commercial vehicle lubricants are specified, procured, and consumed across South Korea's logistics and construction sectors.
Group III+ synthetic base stocks with enhanced oxidative stability are supplanting mineral-based formulations in long-haul diesel applications. Major freight operators in the Seoul-Incheon corridor now specify full-synthetic 5W-30 engine oils as standard, compressing demand for conventional 15W-40 products and enabling extended drain intervals that reduce total fluid consumption per vehicle.
The Ministry of Environment's Special Act on Fine Dust Reduction mandates particulate matter thresholds that diesel lubricants must support through reduced ash content. This regulatory pressure accelerates low-SAPS formulation adoption among urban delivery fleets, with compliance verification now required at vehicle inspection stations in Seoul, Busan, and Daegu metropolitan zones.
Fleet operators are consolidating lubricant procurement through integrated maintenance contracts rather than spot purchasing from distributors. Large logistics companies in the southeastern industrial belt now negotiate direct supply agreements with refiners, disintermediating traditional jobbers and capturing volume-based pricing advantages while securing guaranteed specification compliance across multi-brand vehicle pools.
South Korea Commercial Vehicles Lubricants Market Segmentation
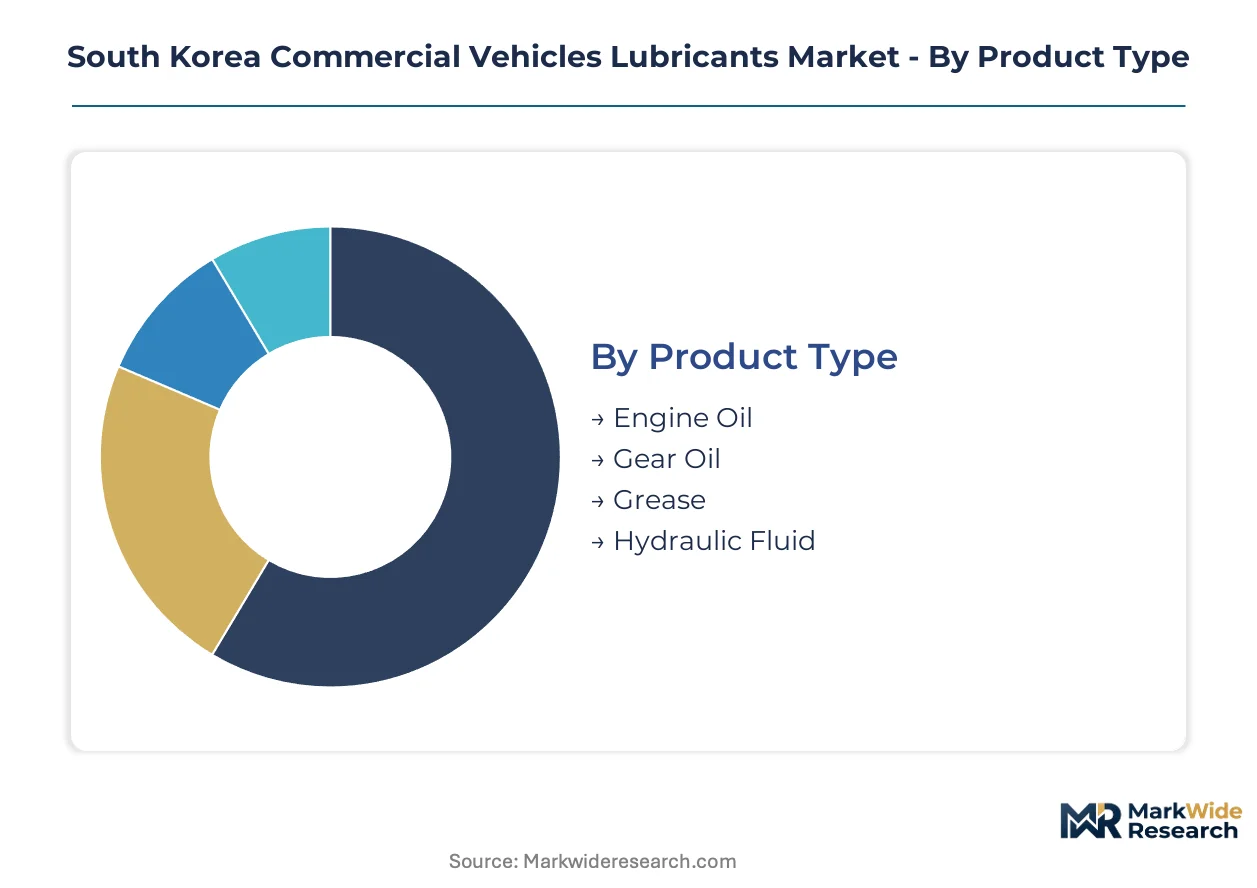
Segmentation in South Korea's commercial vehicle lubricants sector reveals how regulatory pressure and fleet modernization are fragmenting demand across product tiers and service models. Understanding these divisions exposes where margin pools are concentrating and which channels are disintermediating traditional supply relationships.
Product Type:
Engine oil faces the most acute substitution pressure as extended drain intervals and electrification compress per-vehicle consumption, while hydraulic fluids gain defensive positioning through construction equipment uptime requirements.
- Engine Oil:Formulated in SAE 15W-40 to 5W-30 viscosity grades with low-SAPS chemistry to meet Ministry of Environment particulate thresholds. Demand concentrates among Seoul metropolitan logistics fleets specifying full-synthetic formulations for 100,000-kilometer service cycles, though volume per vehicle declines as OEM drain intervals lengthen.
- Hydraulic Fluid:Anti-wear formulations with oxidation stability for excavator and loader systems operating in Busan-Ulsan industrial zones. Construction firms specify premium grades to minimize unscheduled downtime on high-utilization equipment, creating price-inelastic demand pockets.
- Gear Oil:Extreme-pressure lubricants for commercial vehicle axles and transmissions, specified by freight carriers for heavy-load corridor operations.
- Grease:Lithium-complex and calcium-sulfonate thickeners for chassis and bearing applications, serving maintenance-repair operations with lower specification complexity.
Engine oil anchors the volume base while hydraulic fluid gains share at the steepest rate as construction activity intensifies outside the Seoul corridor.
End User:
Cost tier stratification separates large fleet operators with direct refiner contracts from fragmented maintenance-repair channels serving smaller vehicle pools.
- Logistics Companies:E-commerce fulfillment fleets in the Gwangju-Daejeon corridor negotiate integrated supply agreements capturing volume pricing and guaranteed specification compliance across multi-brand vehicle pools. These operators consolidate procurement through predictive maintenance platforms that embed fluid analytics within fleet management systems.
- Freight Carriers:Long-haul diesel operators along the Seoul-Busan axis specify Group III+ synthetic engine oils as standard, with procurement shifting from spot distributor purchases to annual contracts with integrated refiners.
- Public Transport:Municipal bus fleets operating under Ministry of Environment low-emission subsidies, specifying bio-based and low-ash formulations to maintain vehicle inspection compliance in Seoul, Busan, and Daegu metropolitan zones.
- Construction Firms:Equipment-intensive operators in the southeastern industrial belt prioritizing hydraulic fluid performance over engine oil specifications due to excavator uptime economics.
Logistics companies command the steepest procurement leverage while construction firms deliver the most stable margin contribution through premium hydraulic fluid specifications.
Distribution Channel:
Geographic concentration in the Seoul metropolitan area and Busan-Ulsan corridor shapes channel viability, with direct sales penetrating dense fleet clusters while retail retains relevance in dispersed maintenance markets.
- Direct Sales:Refiner-to-fleet agreements disintermediating traditional jobbers, concentrated among logistics companies with 500-plus vehicle fleets in the Seoul-Incheon and Busan-Ulsan zones.
- Wholesale:Distributor networks serving independent repair shops and smaller freight operators across secondary cities, facing margin compression from direct sales expansion.
- Retail:Branded service stations and automotive parts retailers capturing emergency replenishment and owner-operator maintenance in regions outside major logistics corridors.
- Online:E-procurement platforms gaining traction among mid-size fleet managers seeking price transparency, though specification verification remains a friction point.
Direct sales is expanding most quickly in dense fleet clusters while wholesale retains relevance in geographically dispersed service territories.
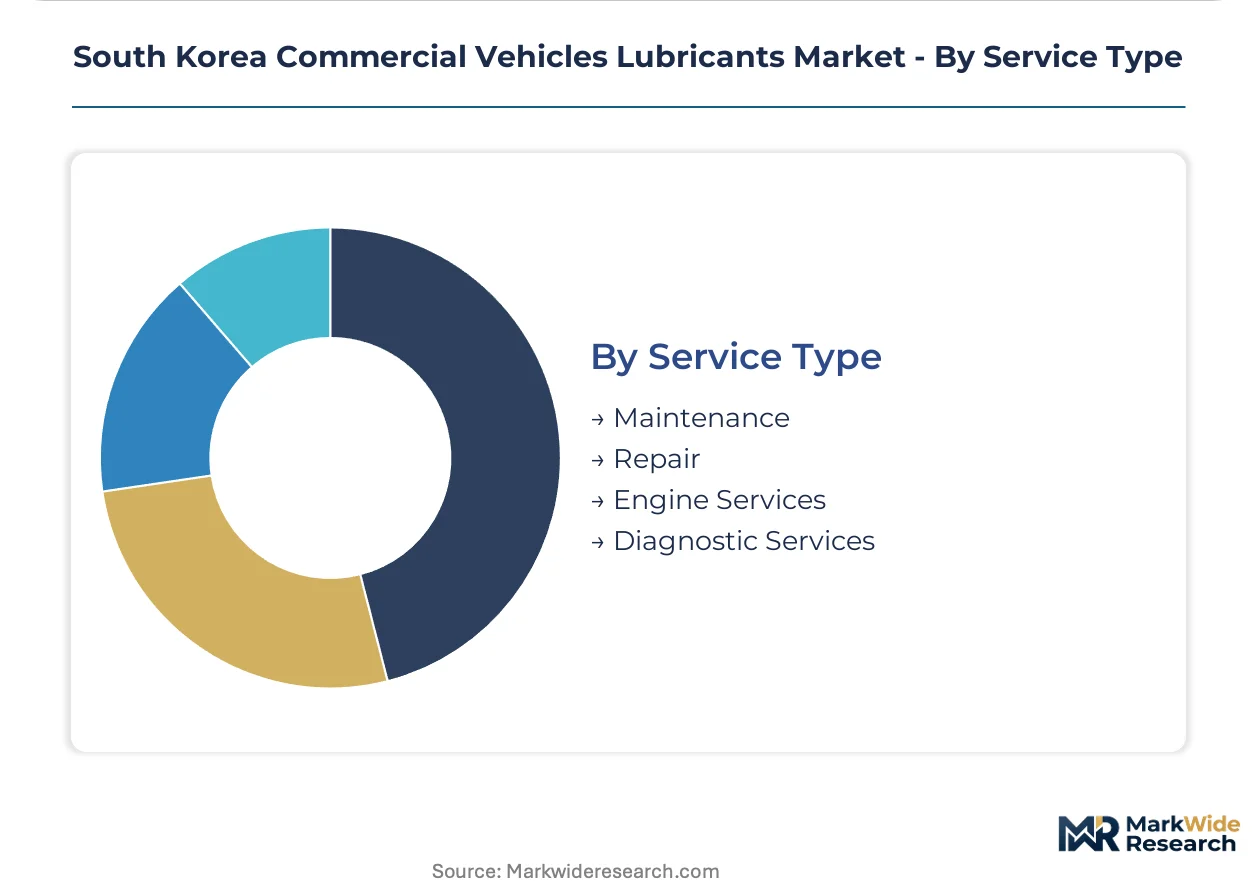
Service Type:
Customer type stratification separates integrated fleet maintenance programs from transactional repair services, with diagnostic capabilities becoming the critical differentiator for lubricant suppliers seeking service bundling opportunities.
- Maintenance:Scheduled fluid replacement programs tied to OEM service intervals, specified by logistics companies through integrated contracts with refiners offering guaranteed compliance documentation.
- Engine Services:Specialized low-SAPS formulation deployment and oil condition monitoring for diesel fleets operating under Ministry of Environment inspection regimes in metropolitan zones.
- Repair:Unscheduled fluid replacement following component failure, concentrated among construction equipment operators and older vehicle fleets in secondary markets.
- Diagnostic Services:Telematics-enabled oil analysis and predictive maintenance recommendations, emerging as the service layer where lubricant suppliers embed recurring revenue relationships.
Maintenance anchors the revenue base while diagnostic services climbs the fastest as fleet operators digitize asset management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Seoul Capital Area while logistics operators in the Busan-Ulsan corridor capture volume leverage through fleet scale. Regional demand fragmentation across South Korea's industrial geography creates distinct procurement dynamics in each metropolitan cluster.
Seoul Capital Area
E-commerce fulfillment fleets and municipal bus operators drive lubricant consumption in the Seoul-Incheon-Gyeonggi corridor. The Ministry of Environment enforces low-emission vehicle subsidies that mandate bio-based hydraulic fluids for fleet certification. Logistics companies in the Gwangmyeong and Songdo distribution hubs negotiate direct supply agreements with integrated refiners.
Busan-Ulsan
Construction equipment operators and heavy freight carriers dominate demand in the southeastern industrial belt. MFDS chemical substance management standards require reformulation of diesel lubricants toward lower-ash specifications. Shipbuilding and petrochemical facilities in the Ulsan industrial complex sustain premium hydraulic fluid consumption for excavator uptime.
Daegu-Gyeongbuk
Textile machinery logistics and regional freight distribution shape lubricant requirements in this manufacturing-heavy zone. KSA quality certification expansion elevates barriers for low-grade imports entering through Daegu metropolitan inspection stations. Fleet operators along the Nakdong River industrial corridor specify synthetic formulations for extended drain intervals.
Daejeon-Sejong
Government fleet procurement and research institution vehicle pools generate specialized demand in this administrative hub. The Ministry of Environment's Special Act on Fine Dust Reduction applies stringent particulate thresholds to public sector diesel fleets. Logistics companies serving the Sejong administrative city negotiate integrated maintenance contracts with predictive diagnostics.
Gwangju-Honam
Agricultural machinery distribution and regional construction activity sustain baseline lubricant consumption in southwestern South Korea. Smaller fleet operators here rely on wholesale distributor networks rather than direct refiner relationships. The Honam expressway freight corridor connects Gwangju-based carriers to national logistics networks with standardized specification requirements.
South Korea Commercial Vehicles Lubricants Market Competitive Landscape
Concentration sits with integrated petroleum refiners that command captive base oil supply and in-house additive development capabilities. Domestic refiners leverage Yeosu and Ulsan refinery complexes to secure feedstock advantages over independent blenders. Two strategic archetypes dominate: vertically integrated refiners with synthetic base stock capacity, and multinational lubricant specialists with OEM approval portfolios. Competitive moves center on direct fleet contract expansion and predictive maintenance platform integration.
Within the integrated refiner tier, GS Caltex and SK Lubricants Co. Ltd exemplify domestic players with refinery-linked supply chains, while S-Oil Corporation anchors a position among petroleum-derived lubricant specialists. Hyundai Oilbank represents the mid-scale refiner archetype competing through regional service bundling. Among multinational specialists, ExxonMobil Corporation, BP PLC (Castrol), and Royal Dutch Shell Plc occupy positions defined by global OEM certification networks and synthetic formulation portfolios. FUCHS and Valvoline Inc sit within the specialty lubricant tier serving construction equipment and aftermarket channels respectively.
| Leading Market Players |
|---|
| GS Caltex |
| SK Lubricants Co. Ltd |
| S-Oil Corporation |
| Hyundai Oilbank |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| FUCHS |
| Valvoline Inc |
| Others |
Value Network & Pricing Analysis
Sixty-day base oil inventory cycles at Yeosu refinery complexes concentrate pricing power among integrated refiners with captive feedstock supply, compressing margins for independent blenders sourcing Group II/III stocks through regional traders. This inventory-to-pricing linkage intensifies as MFDS chemical substance mandates escalate compliance costs for non-integrated operators.
Pricing Analysis
The customization-premium spread between OEM-certified synthetic formulations and standard mineral-based products spans three performance tiers: low-SAPS premium grades for Seoul metropolitan fleets, mid-tier semi-synthetics for regional freight carriers, and economy mineral oils for aging vehicle pools in secondary markets. Price differentiation hinges on ACEA/API certification tier and volume commitment scale, with annual contract volumes above ten thousand liters capturing fifteen to twenty percent standard discounts. Pricing pressure stems from drain interval extension engineering as OEM-specified synthetics achieve hundred-thousand-kilometer service cycles, compressing per-vehicle consumption. Logistics companies with five-hundred-plus fleet scale exhibit lowest price sensitivity due to uptime cost structures, while owner-operators in Gwangju-Honam demonstrate acute sensitivity to per-liter differentials.
Supply Chain Analysis
Just-in-time additive delivery from Singapore and Japan dominates formulation scheduling, though strategic stockpiling of Group III base oils occurs ahead of quarterly shipping cost volatility windows. Geographic supply concentration centers on South Korea's Yeosu and Ulsan refinery corridors for base stock, with pour point depressant and anti-wear chemistry drawing from Germany, Japan, and Singapore. Raw material dependencies include high-viscosity index base oils, polyalphaolefin synthetics, and low-ash additive packages. Single-source vulnerability concentrates in anti-wear chemistry where four multinational suppliers control formulation IP. Distribution runs through direct refiner-to-fleet agreements in Seoul-Incheon and Busan-Ulsan corridors, with wholesale networks retaining relevance in Daegu-Gyeongbuk and Gwangju-Honam secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's commercial vehicle lubricants sector sits in early-cycle expansion as carbon-neutral fleet certification incentives accelerate bio-based formulation adoption beyond regulatory baselines.
For Market Incumbents: Fortify captive base oil supply positions through Yeosu refinery complex capacity optimization and deepen OEM partnership portfolios to preempt multinational certification challenges. Integrated refiners should accelerate predictive maintenance platform integration to embed fluid analytics within fleet management systems, converting transactional product sales into recurring service revenue streams. Threat of drain interval extension engineering demands defensive specification complexity investments to maintain per-vehicle revenue capture. For New Entrants and Emerging Players: KSA quality certification fast-track programs offer the most penetrable entry vector for mid-scale blenders seeking to bypass incumbent distributor lock-in. Geographic white space concentrates in the Gwangju-Daejeon logistics corridor where e-commerce fulfillment center construction outpaces established refiner service coverage. Go-to-market execution should target construction equipment operators in Busan-Ulsan with premium hydraulic fluid bundles emphasizing excavator uptime guarantees rather than competing on engine oil volume. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates seeking to divest non-core lubricant blending assets amid Group II/III import dependency margin compression. Long-term viability favors operators with backward integration into synthetic base stock production or proprietary low-SAPS formulation IP. Acquisition archetype: mid-scale blenders with KSA certification infrastructure and established construction sector relationships. Signal to watch: Ministry of Environment enforcement intensity at Daegu and Busan metropolitan inspection stations as proxy for regulatory premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Synthetic Base Stock | Captive feedstock supply insulates GS Caltex and SK Lubricants from shipping cost volatility and currency fluctuation exposure. |
| Predictive Maintenance Platform Integration | Telematics-enabled oil condition monitoring shifts lubricant suppliers from product-centric to service-centric revenue models. |
| KSA Quality Certification Investment | Mandatory third-party testing elevates barrier to entry for low-grade imports, protecting domestic formulation specialists. |
| Bio-based Hydraulic Fluid Portfolio Expansion | Ministry of Environment low-emission vehicle subsidies reward operators using renewable formulations, opening premium positioning. |
| Direct Fleet Contract Expansion | Refiner-to-logistics company agreements disintermediate traditional jobbers and capture volume-based pricing advantages. |
Research Methodology
The analysis maps engine oil, hydraulic fluid, gear oil, and grease sub-sectors, each validated through lubricant formulation chemists, fleet procurement directors at logistics companies, construction equipment maintenance managers, and refinery supply chain executives. Primary interview intelligence combined with secondary validation from Korea Petroleum Association trade data, MFDS chemical substance registration filings, Ministry of Environment emission compliance records, and KSA quality certification databases. Bottom-up product volume estimates triangulated against top-down refinery output disclosures and customs import records for Group II/III base oil feedstocks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user segment, distribution channel, and service type dimensions alongside fleet electrification transition stage as industry-specific stratifier. CAGRs derived from regression analysis of historical consumption patterns against OEM drain interval extension timelines and construction equipment deployment cycles. Forecast inputs incorporated MFDS regulatory phase-in schedules and Ministry of Environment low-emission subsidy allocation trajectories.
Underlying assumptions cover stable Group III base oil import cost structures and continued ACEA/API specification convergence, with deviation risk concentrated in accelerated fleet electrification timelines and additive chemist talent scarcity at major refiners. Forecasts reflect documented assumptions with explicit scenario weighting for regulatory enforcement intensity variation. Revision becomes warranted when hybrid commercial vehicle penetration crosses thresholds that fundamentally alter transmission fluid and thermal management lubricant demand composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Synthetic Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Industrial Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
US Industrial Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Morocco Lubricants Market