
 Global Lubricant Anti Wear Agents Market | 2026-2036
Global Lubricant Anti Wear Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lubricant Anti Wear Agents Market Intelligence
Procurement power from large, consolidated automotive OEMs and Tier-1 suppliers is shifting the competitive landscape for agent producers. This consolidation among buyers demands greater R&D investment and supply chain reliability from vendors. The Lubrizol Corporation leverages its extensive portfolio to meet diverse OEM specifications across multiple geographies. Afton Chemical differentiates through its specialization in driveline and engine oil additive packages for high-performance applications.
Lubricant anti-wear agents are chemical additives that protect metal surfaces from damage caused by friction and high pressure. They function by forming a sacrificial film on metallic components, preventing direct metal-to-metal contact. Within the product mix, phosphate esters, particularly zinc dialkyldithiophosphates (ZDDP), continue to dominate due to their cost-effectiveness and proven performance. The engine oils application represents the largest segment, while demand for specialized agents in gear oils is expanding due to industrial automation and EV transmissions.
Regulatory frameworks from the EPA in the United States and ECHA in Europe under REACH are restricting the use of certain chemicals, such as phosphorus in ZDDP. These rules, alongside China's GB standards for fuel economy, compel formulators to develop ashless or low-SAPS (sulfated ash, phosphorus, and sulfur) alternatives. Consequently, supplier selection will increasingly hinge on the ability to provide compliant, high-performance chemistries that meet evolving OEM and environmental requirements.
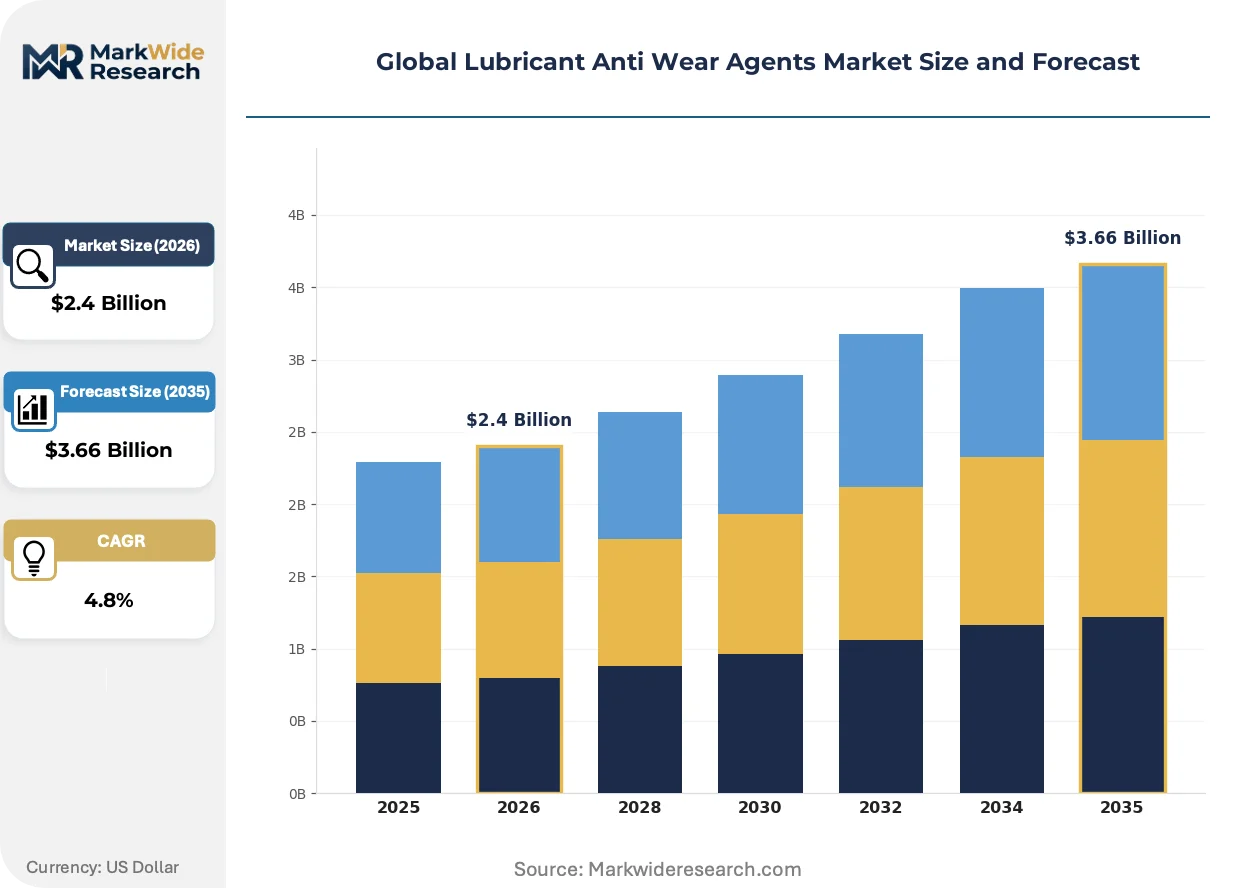
Market Dynamics
The central dynamic in the lubricant anti-wear agents market is the tension between escalating performance requirements from the automotive sector and stringent environmental regulations. This conflict forces chemical producers to innovate beyond traditional, cost-effective chemistries like ZDDP toward compliant alternatives.
Growth Catalysts
- Stricter Emissions Regulations:The EU Green Deal and similar global mandates for lower vehicle emissions compel the use of advanced engine oils, which in turn require sophisticated anti-wear agents to improve fuel efficiency and protect after-treatment systems.
- Industrial Automation:Expansion in automated manufacturing and robotics increases the operational demands on industrial gearboxes and hydraulic systems, necessitating higher-performance gear oils and hydraulic fluids formulated with specialized anti-wear additives.
- Electric Vehicle Drivetrains:The unique material composition and operating conditions of EV transmissions and e-axles create demand for novel anti-wear agents that provide protection without causing copper corrosion or electrical conductivity issues.
Market Restraints
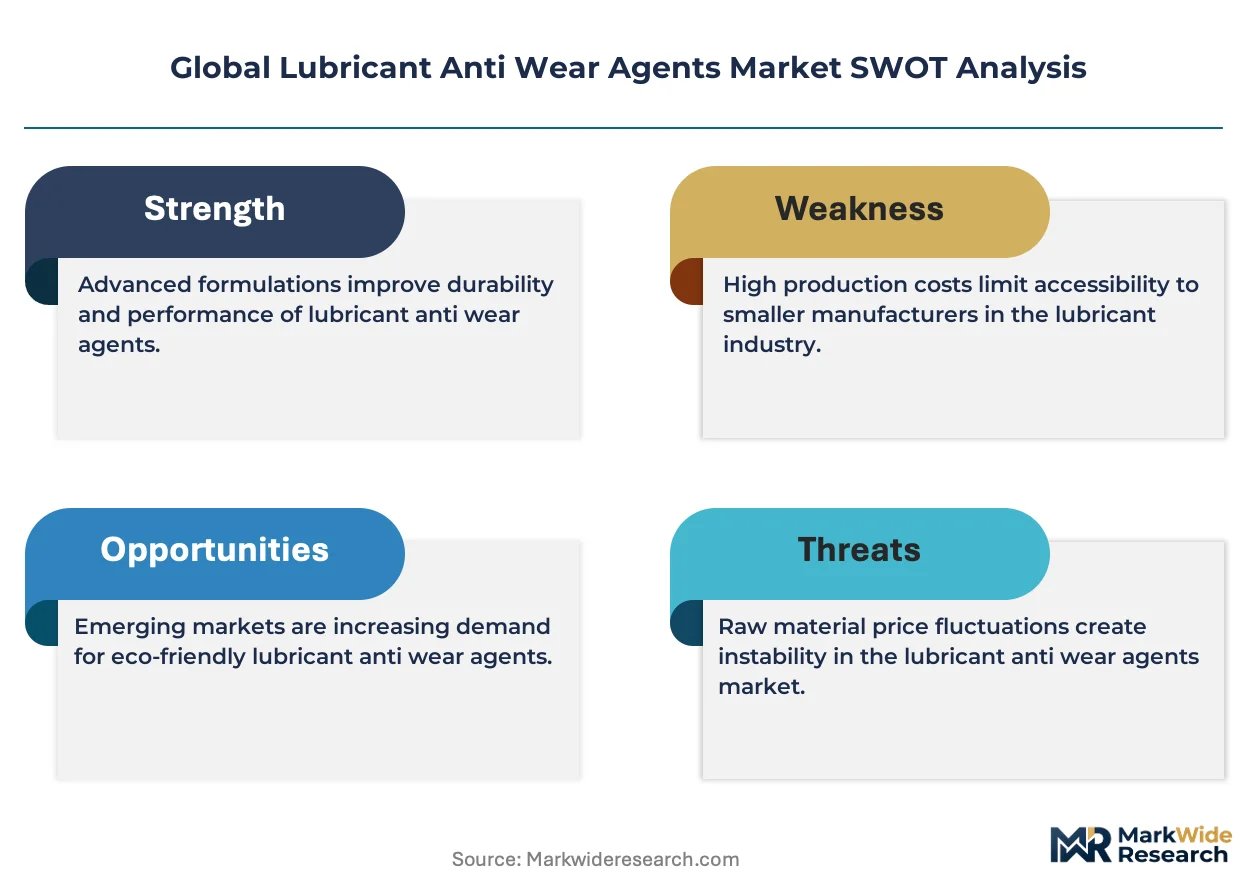
- Raw Material Price Volatility:Fluctuations in the cost of key precursors like phosphorus, zinc, and specialty amines create margin pressure for additive manufacturers and introduce price instability for lubricant blenders.
- Regulatory Restrictions on Phosphorus:Rules from the EPA and ECHA under REACH limit the amount of phosphorus and sulfur in engine oils to protect catalytic converters, constraining the use of highly effective ZDDP additives.
- High R&D Cost of Alternatives:Developing ashless or low-SAPS anti-wear agents that match the performance and cost-effectiveness of traditional chemistries requires significant investment in research, testing, and validation, posing a barrier to entry.
Strategic Opportunities
- Biodegradable Lubricant Additives:Formulating anti-wear agents for environmentally acceptable lubricants opens new markets in marine, agriculture, and forestry, where regulations restrict the use of mineral oil-based products.
- Emerging Automotive Hubs:As countries in Southeast Asia and Latin America tighten their vehicle emissions standards, a significant opportunity emerges to supply higher-performance additive packages that meet these new local requirements.
- Specialized EV Fluids:The development of additives for direct-contact immersion cooling fluids for EV batteries represents a high-value niche, combining thermal management with material protection in a single fluid.
Industry Challenges
- OEM and Industry Certification Cycles:The lengthy and costly process of securing approvals from automotive OEMs and certifications from bodies like API and ACEA for new additive formulations can significantly delay time-to-market.
- New Chemistry Supply Chain Development:Establishing reliable, scalable supply chains for the novel raw materials required for ashless and low-SAPS chemistries presents a logistical challenge compared to the mature supply base for traditional additives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lubricant Anti Wear Agents Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Amines, Phosphate Esters, Sulfurized Olefins, Ionic Liquids End User: Aerospace, Automotive, Manufacturing, Marine Application: Metalworking, Gear Oils, Hydraulic Fluids, Engine Oils Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Infineum, LANXESS, Lubrizol, Vanderbilt Chemicals, Evonik, Afton Chemical, BASF SE, Solvay, Chevron Oronite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lubricant Anti Wear Agents Market Strategic Shifts & Innovations
The evolution of lubricant anti-wear agents is being driven by a fundamental shift toward chemistries that balance wear protection with environmental sustainability. This trend is reshaping formulation strategies, compelling a move away from legacy additives toward multifunctional, compliant alternatives.
Ashless anti-wear agents, which often utilize nitrogen and boron compounds, deliver wear protection without producing sulfated ash that can harm vehicle exhaust after-treatment systems. Lubricant formulators supplying major automotive markets in Europe and North America are actively adopting these chemistries to meet low-SAPS specifications. This transition from phosphorus-based technology is rewriting the performance-to-cost framework for modern engine oil additive packages.
China's GB standards for fuel economy and emissions are becoming progressively more rigorous, aligning with international benchmarks set by the EU and US. This national policy forces lubricant manufacturers in the region to prioritize formulations that minimize friction and enhance engine efficiency. The passenger car engine oil segment is most affected, influencing the selection of anti-wear agents that can meet these demanding Chinese performance and environmental mandates.
A significant change in buying behavior is the consolidation of additive sourcing by large automotive OEMs. This move from purchasing individual components to procuring fully formulated, pre-certified additive packages streamlines the OEM's internal validation and simplifies supply chain management. This pattern is most visible within the highly integrated automotive manufacturing clusters of Germany, the United States, and Japan.
Global Lubricant Anti Wear Agents Market Segmentation
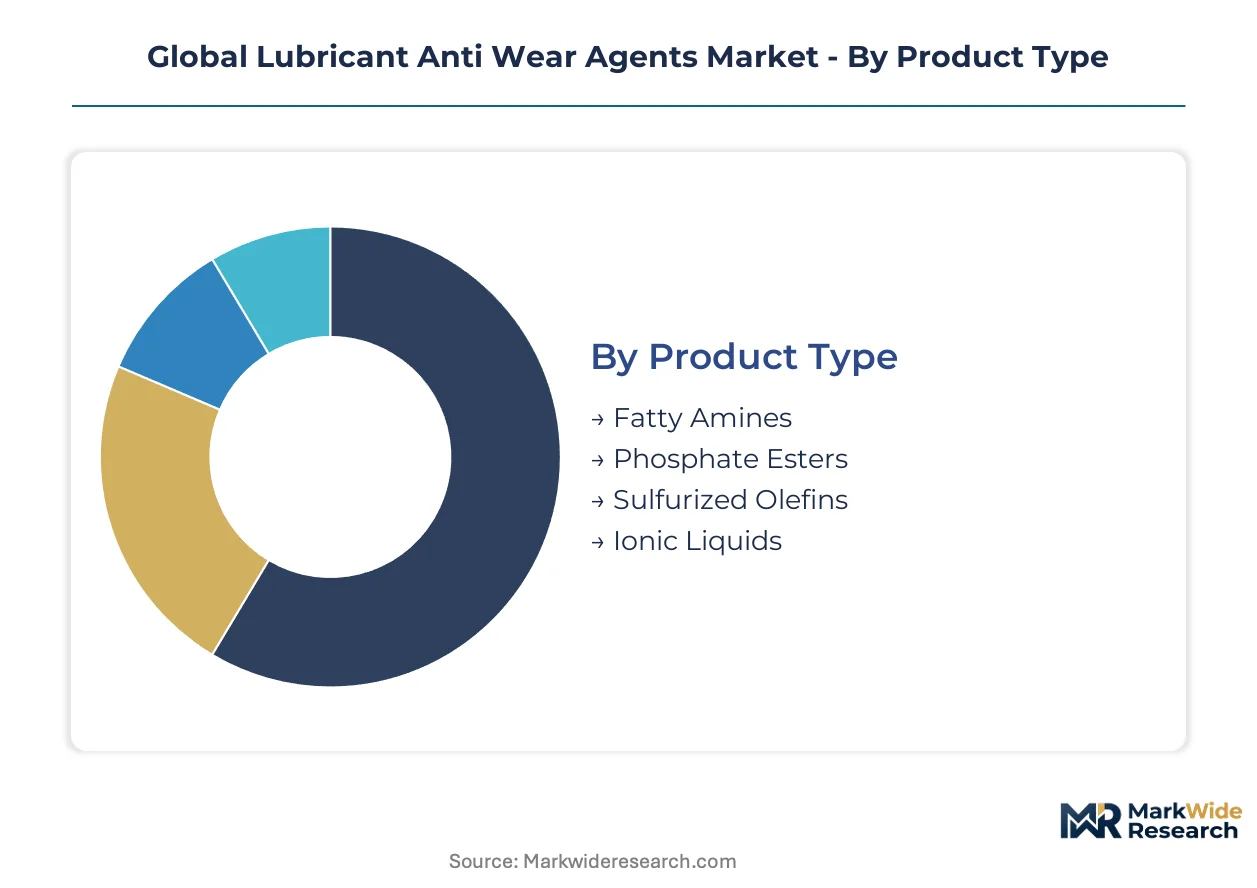
Understanding the distinct segments within the lubricant anti-wear agents market is essential for identifying strategic opportunities and navigating evolving regulatory landscapes. Each category reflects unique chemical compositions, end-user requirements, application demands, and supply chain dynamics. This granular view helps stakeholders align product development with specific market needs and compliance mandates.
Product Type:
The product type segmentation highlights the varying chemical structures and performance characteristics of anti-wear agents, ranging from established chemistries to novel formulations. Some agents serve as standalone additives, while others are integrated into complex additive packages.
- Fatty Amines:These nitrogen-containing compounds function as friction modifiers and corrosion inhibitors, often used in conjunction with other anti-wear additives. Their demand is stable in industrial lubricants and greases.
- Phosphate Esters:These phosphorus-based compounds, including zinc dialkyldithiophosphates (ZDDP), form protective films on metal surfaces under extreme pressure and high temperatures. ZDDP remains a cost-effective and high-performing solution, widely utilized in engine oils despite phosphorus restrictions.
- Sulfurized Olefins:These sulfur-containing additives provide extreme pressure protection, especially in gear oils and metalworking fluids, by reacting with metal surfaces to form a tenacious protective layer. Demand is consistent in heavy industrial applications.
- Ionic Liquids:These novel molten salts offer ashless anti-wear properties and reduced friction, presenting a promising alternative to traditional chemistries, particularly for electric vehicle fluids. Their unique properties are gaining traction in high-performance and specialty applications.
Volume placements concentrate in Phosphate Esters; the faster expansion belongs to Ionic Liquids.
End User:
The end-user segmentation reveals where the primary consumption of anti-wear agents occurs, reflecting the diverse operational environments and performance requirements across different industries. Certain end-users require highly specialized formulations due to unique operating conditions.
- Aerospace:This sector demands high-performance, temperature-stable anti-wear agents for hydraulic systems and turbine engines, ensuring reliability under extreme conditions. Stringent certification processes govern additive selection.
- Automotive:The automotive industry represents the largest consumer of anti-wear agents, primarily for engine oils, transmission fluids, and gear oils in passenger and commercial vehicles. Stricter emissions regulations in Europe and China drive demand for advanced, low-SAPS formulations.
- Manufacturing:Industrial automation and heavy machinery in manufacturing facilities require robust anti-wear additives for hydraulic systems, industrial gearboxes, and metalworking fluids. The expansion of automated production lines in Germany and the United States increases demand for specialized industrial lubricants.
- Marine:Marine applications involve large engines and hydraulic systems operating in harsh, corrosive environments, necessitating durable anti-wear protection. Regulatory shifts towards environmentally acceptable lubricants influence additive choices in this segment.
The Automotive sector commands the largest share of anti-wear agent consumption, while the Manufacturing segment exhibits significant expansion due to industrial automation.
Application:
This category delineates the specific functional areas where anti-wear agents are employed, highlighting the tailored performance characteristics required for each use case. Each application demands a precise balance of wear protection, friction modification, and compatibility.
- Metalworking:Anti-wear agents in metalworking fluids reduce tool wear and improve surface finish during machining and forming operations. Their performance directly impacts manufacturing efficiency.
- Gear Oils:These lubricants protect gears in transmissions and industrial machinery from scuffing and pitting under heavy loads, often requiring high-pressure anti-wear additives. Demand is escalating with the proliferation of electric vehicle drivetrains and industrial robotics.
- Hydraulic Fluids:Anti-wear agents prevent wear in hydraulic pumps and valves, ensuring system efficiency and longevity in industrial and mobile equipment. Their consistent performance is critical for reliable operation.
- Engine Oils:This application represents the largest segment for anti-wear agents, protecting critical engine components from friction and wear while managing deposits and emissions. Global fuel economy standards, including China's GB standards, accelerate the development of advanced engine oil formulations.
Engine Oils constitute the dominant application area, with Gear Oils demonstrating vigorous demand driven by new vehicle technologies.
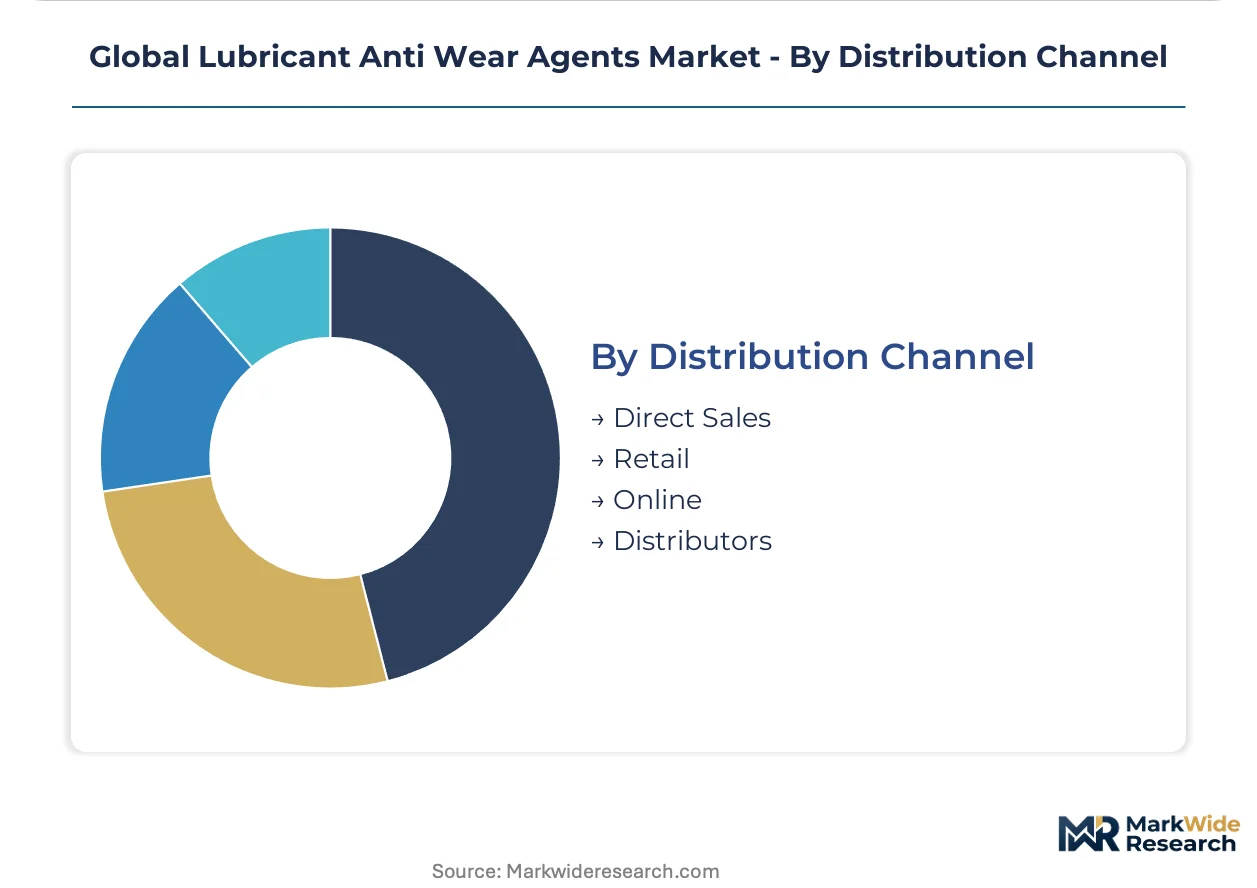
Distribution Channel:
The distribution channel segmentation illustrates the various routes through which anti-wear agents reach end-users, reflecting the structure of the supply chain. Channels range from direct engagement with large buyers to broader market access through intermediaries.
- Direct Sales:Major additive manufacturers often sell directly to large lubricant blenders and automotive OEMs, fostering close technical collaboration and customized solutions. This channel ensures direct control over product delivery and technical support.
- Retail:This channel includes sales through automotive parts stores, hypermarkets, and other consumer-facing outlets, primarily for packaged engine oils and consumer lubricants. Brand recognition and accessibility are key success factors.
- Online:E-commerce platforms facilitate the sale of lubricant additives and finished lubricants to a diverse customer base, including small businesses and individual consumers. Digital channels provide convenience and wider product selection.
- Distributors:Independent distributors play a crucial role in reaching smaller lubricant blenders, industrial end-users, and regional markets by providing logistical support and local inventory. They often offer a portfolio of products from multiple manufacturers.
Direct Sales are critical for large-volume OEM procurement, while Distributors extend market reach to a broader industrial customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for lubricant anti-wear agents significantly influences regional market dynamics. Automotive and industrial manufacturing hubs drive consumption, necessitating advanced formulations for engine oils and industrial lubricants. Stricter emissions regulations in these key geographies compel the development of high-performance, compliant chemistries.
United States
The United States automotive sector drives substantial demand for anti-wear agents in engine oils and transmission fluids. EPA regulations restrict phosphorus content, pushing formulators toward ashless alternatives. Industrial clusters in the Midwest focus on developing advanced lubricant solutions for both traditional and EV applications.
Germany
Germany's premium automotive manufacturing and sophisticated industrial machinery sectors create strong demand for advanced anti-wear agents. The EU Green Deal and ECHA's REACH regulations compel lubricant formulators to develop environmentally compliant chemistries. Automotive OEMs in Bavaria prioritize high-performance, low-SAPS solutions.
China
China's expanding automotive production and industrial automation initiatives significantly increase the consumption of anti-wear agents. GB standards for fuel economy and emissions mandate the use of friction-reducing and wear-protecting chemistries. Manufacturing centers in the Yangtze River Delta actively seek advanced engine oil formulations.
Japan
Japanese automotive and precision manufacturing industries require high-performance anti-wear agents for engine oils and specialized industrial lubricants. National emissions targets and JIS standards guide the development of ashless and low-SAPS chemistries. The Kanto region focuses on innovative additive packages for next-generation vehicles.
India
India's burgeoning automotive market and infrastructure development projects fuel demand for anti-wear agents across various applications. Bharat Stage emission norms push lubricant manufacturers to adopt higher-quality, more efficient engine oil additives. Industrial and automotive hubs in Maharashtra are key areas for the adoption of compliant anti-wear chemistries.
Global Lubricant Anti Wear Agents Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-performance chemistries for electric vehicles and industrial automation. The market exhibits a tiered structure, with a few large integrated chemical companies dominating the supply of base additives and complex additive packages. Strategic archetypes include diversified chemical giants, specialized additive formulators, and regional players focusing on specific application niches. Portfolio diversification, strategic partnerships, and significant R&D investment are dominant competitive moves among these participants.
Specialized additive formulators, like Lubrizol Corporation, leverage extensive portfolios to meet diverse OEM specifications across multiple geographies. Afton Chemical, another prominent player, differentiates through its specialization in driveline and engine oil additive packages for high-performance applications. German-based Evonik AG also sits within this tier, contributing to the development of advanced chemical solutions required for modern lubricant formulations. These entities anchor the market for complex, performance-driven anti-wear agents.
| Leading Market Players |
|---|
| Infineum |
| LANXESS |
| Lubrizol |
| Vanderbilt Chemicals |
| Evonik |
| Afton Chemical |
| BASF SE |
| Solvay |
| Chevron Oronite |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and similar environmental mandates gate access to qualified supply for anti-wear agents, driving premium pricing for compliant, high-performance chemistries.
Pricing Analysis
Volume-based pricing dominates the standard anti-wear agent segment, while higher margins are secured by specialized, high-performance formulations. Pricing stratifies across premium, standard, and economy tiers, differentiated by certification level for OEM approvals and performance grade for specific applications. Pricing softness reflects raw material cost volatility, particularly for phosphorus and zinc precursors. Large automotive OEMs are less price-sensitive for advanced solutions, whereas smaller industrial blenders prioritize cost-effectiveness.
Supply Chain Analysis
Certification and qualification processes gate entry into the anti-wear agent supply chain, demanding rigorous testing from producers. Supply concentrates in chemical manufacturing hubs within Germany, China, and the United States, drawing from key precursors like phosphorus, zinc, and specialty amines. Commodity price volatility for these raw materials presents a significant structural risk. Direct sales are critical for large lubricant blenders and automotive OEMs, while distributors extend market reach to smaller industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained narrative, particularly for ashless and low-SAPS anti-wear agents. Limited production capacity for novel chemistries props up premium pricing for compliant formulations.
For Market Incumbents: Anchor market share by expanding R&D investment into ashless and low-SAPS alternatives, mitigating the threat from phosphorus restrictions. Consolidate technical service and supply chain reliability to meet diverse OEM specifications across multiple geographies. Deepen vertical integration into key specialty amine precursors to manage raw material price volatility. Invest in faster OEM certification cycles for new additive packages.
For New Entrants and Emerging Players: The price-point gap between established ZDDP and novel ashless chemistries offers an entry point for specialized solutions. Target the expanding gear oils segment for EV drivetrains with unique, copper-compatible anti-wear agents. Focus on Southeast Asia's emerging automotive hubs with tailored, cost-effective additive packages. Differentiate through rapid OEM validation and flexible supply chain models.
For Investors and Strategic Acquirers: Increased OEM mandates for ashless formulations is the leading indicator that traditional chemistries will face accelerated displacement. Long-term viability for anti-wear agent producers hinges on early adoption of sustainable, high-performance alternatives over the next five to ten years. Target specialized additive formulators with strong IP in ionic liquids or boron-based chemistries. Watch for significant market share shifts in China's passenger car engine oil segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand R&D into Ashless Chemistries | Meets EU Green Deal and EPA phosphorus restrictions for advanced engine oils. |
| Secure Long-Term Raw Material Contracts | Mitigates commodity price volatility for phosphorus and specialty amines. |
| Invest in EV Fluid Additive Development | Captures demand from electric vehicle drivetrains and immersion cooling applications. |
| Accelerate OEM Certification Processes | Reduces time-to-market for new additive packages for automotive manufacturers. |
| Regional Production Capacity Expansion | Serves growing demand in China and Southeast Asia for compliant formulations. |
Research Approach
Multi-period observation of emissions regulations and OEM specifications anchored the trend analysis, supplemented by interviews with industry experts. Primary research involved discussions with R&D directors, procurement leads at lubricant blenders, and automotive OEM engineers. Secondary data sources included ECHA REACH filings, EPA environmental reports, and customs data for chemical precursors. This approach ensured bottom-up market insights triangulated with top-down industry trends.
An input-output matrix integrated historical data with projected market drivers across the analysis window. Segmentation dimensions modeled included product type, end-user, application, and regional regulatory compliance. Compound annual growth rates were derived from a multi-variable regression analysis. Key forecast inputs included global vehicle production forecasts and industrial automation investment trends.
Inputs from chemical producers and regulatory bodies were available through the study window; gaps in emerging EV fluid specifications introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. A model refresh is warranted upon material change in global emissions standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Brazil Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Italy Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Global Compressor Oil Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
ASEAN Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Neat Cutting Oil Market