
 Global Fusion Bonded Epoxy Coatings Market | 2026-2036
Global Fusion Bonded Epoxy Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fusion Bonded Epoxy Coatings Market Foresight
Polyethylene is hardening into a less competitive position against fusion bonded epoxy in subsea and buried pipeline specifications where cathodic protection compatibility matters. Akzo Nobel leverages its marine coatings heritage to anchor premium specification relationships with North Sea and Gulf of Mexico operators. PPG Industries competes through backward integration into resin synthesis, sustaining margin control across powder and liquid formulation lines. Jotun dominates Nordic and North Atlantic offshore markets where thermal shock resistance requirements exceed standard API specifications.
Fusion bonded epoxy coatings are thermosetting polymer systems applied as dry powders or liquid suspensions that cure at 180–250°C to form dense, chemically resistant barriers with typical dry-film thickness of 250–500 microns, engineered primarily to prevent corrosion on steel substrates in aggressive service environments. Powder coatings lead volume consumption in pipeline protection applications where automated electrostatic spray and fluidized bed deployment methods support high-throughput mill-applied specifications. Liquid coatings represent the fastest-growing format for field joint repairs and rebar coating applications where ambient-cure flexibility overrides factory-line efficiency. Dual coatings command premium positioning in deepwater riser and flowline segments where combined fusion bonded epoxy and abrasion-resistant overlays address multi-mechanism degradation.
API 5L2, ISO 21809-2, and NACE SP0394 govern fusion bonded epoxy performance benchmarks for pipeline operators, while EPA stormwater regulations and OSHA hexavalent chromium exposure limits shape shop-applied coating facility compliance investments. ECHA REACH substance restrictions on bisphenol-A derivatives and certain epoxy hardeners are forcing reformulation timelines across European supply chains. Stakeholders must monitor regulatory divergence between API corrosion prevention standards and emerging EU chemical hazard classifications that could fragment qualification protocols across Atlantic supply bases.
Market Dynamics
Pipeline operators are consolidating specifications around single-layer fusion bonded epoxy systems as cathodic protection compatibility becomes non-negotiable for subsea and high-pressure CO2 service, compressing qualification timelines and freezing out polyethylene alternatives.
Growth Catalysts
- API 5L2 specification tightening:Revised corrosion prevention benchmarks in North America are mandating enhanced cathodic disbondment resistance, forcing replacement of legacy three-layer polyethylene systems at mill-applied coating facilities.
- Offshore pipeline refurbishment cycles:Gulf of Mexico and North Sea operators are accelerating riser and flowline recoating programs as infrastructure ages beyond original design life.
- Shale gathering infrastructure expansion:Permian Basin and Bakken field development is driving specification volumes for fusion bonded epoxy on gathering lines and compressor station piping.
Market Restraints
- Epoxy resin supply concentration:Bisphenol-A and specialty hardener production clusters in China and Germany create input cost volatility and qualification risk for formulators.
- ECHA REACH substance restrictions:European reformulation mandates on bisphenol-A derivatives and certain amine hardeners are extending product development timelines by 18-24 months.
- Thermoset processing inflexibility:Factory-applied fusion bonded epoxy requires 180-250°C cure temperatures, excluding field deployment on ambient-temperature substrates without portable induction heating systems.
Strategic Opportunities
- Hydrogen pipeline compatibility testing:German and Dutch transmission operators are evaluating fusion bonded epoxy performance under high-pressure hydrogen permeation, opening qualification pathways for repurposed natural gas infrastructure.
- Liquid epoxy field joint coatings:Ambient-cure formulations are penetrating repair and tie-in applications where mill-applied powder systems cannot reach.
- Carbon capture transport lines:Dense phase CO2 service specifications in Norway and the United Kingdom are creating premium demand for dual-layer abrasion-resistant overlay systems.
Industry Challenges
- Hexavalent chromium exposure compliance:OSHA permissible exposure limits are forcing coating facility capital upgrades for ventilation and personal protective equipment across US Gulf Coast applicators.
- Cross-Atlantic qualification divergence:API corrosion prevention standards and emerging EU chemical hazard classifications under ECHA are fragmenting certification protocols, requiring dual-track testing for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fusion Bonded Epoxy Coatings Market |
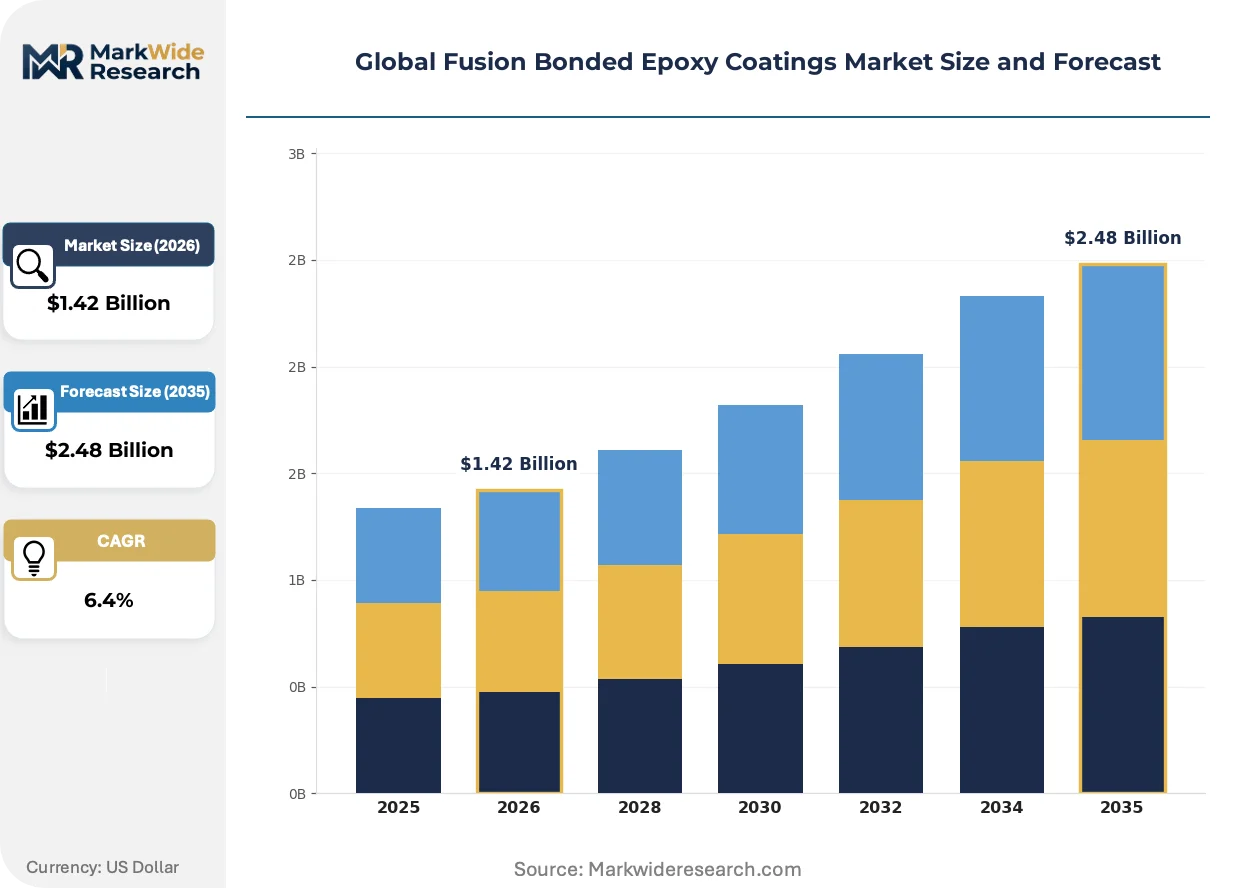
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder Coatings, Liquid Coatings, Dual Coatings, Custom Formulations Application: Pipeline Protection, Rebar Coating, Wire & Cable Coating, Industrial Machinery Covering, Corrosion Prevention End User Industry: Oilfield Equipment Manufacturers, Construction Companies, Electrical Component Makers, Heavy Equipment Producers, Marine Equipment Fabricators Deployment Method: Electrostatic Spray, Fluidized Bed, Powder Slurry, Vacuum Coating Technologies |
| Companies Covered | Jotun, Akzo Nobel, 3M, BASF, PPG Industries, Axalta Coating Systems, The Sherwin-Williams Company, Shawcor, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fusion Bonded Epoxy Coatings Market Shifts & Advancements
Formulation chemistry and application methodology are undergoing parallel evolution as regulatory pressure and service environment complexity outpace incremental performance gains from conventional epoxy systems.
Nano-modified epoxy resins incorporating graphene and clay platelet additives are converging with conventional fusion bonded epoxy matrices to enhance barrier properties and mechanical toughness. Subsea contractors in Brazil and Norway are specifying these hybrids for deepwater riser applications where thermal cycling and mechanical abrasion coincide. The technology is compressing the performance gap between standard fusion bonded epoxy and more expensive thermoplastic composite liners.
REACH authorization procedures for bisphenol-A and certain epoxy hardeners are forcing accelerated reformulation investment across European coating supply chains. ECHA substance restriction timelines are compressing product development cycles while maintaining qualification rigor under ISO 21809-2. German and Dutch formulators are responding with bio-based epoxy alternatives and non-bisphenol-A curing agents, though thermal resistance trade-offs remain unresolved.
Integrated coating-logistics contracts are displacing transactional procurement for mill-applied pipeline specifications. Major line pipe producers in Japan and South Korea are bundling fusion bonded epoxy application with steel production and ocean freight, compressing buyer decision cycles and locking out independent coating applicators. This consolidation is most visible in large-diameter transmission line awards where single-source accountability reduces interface risk.
Global Fusion Bonded Epoxy Coatings Market Segmentation
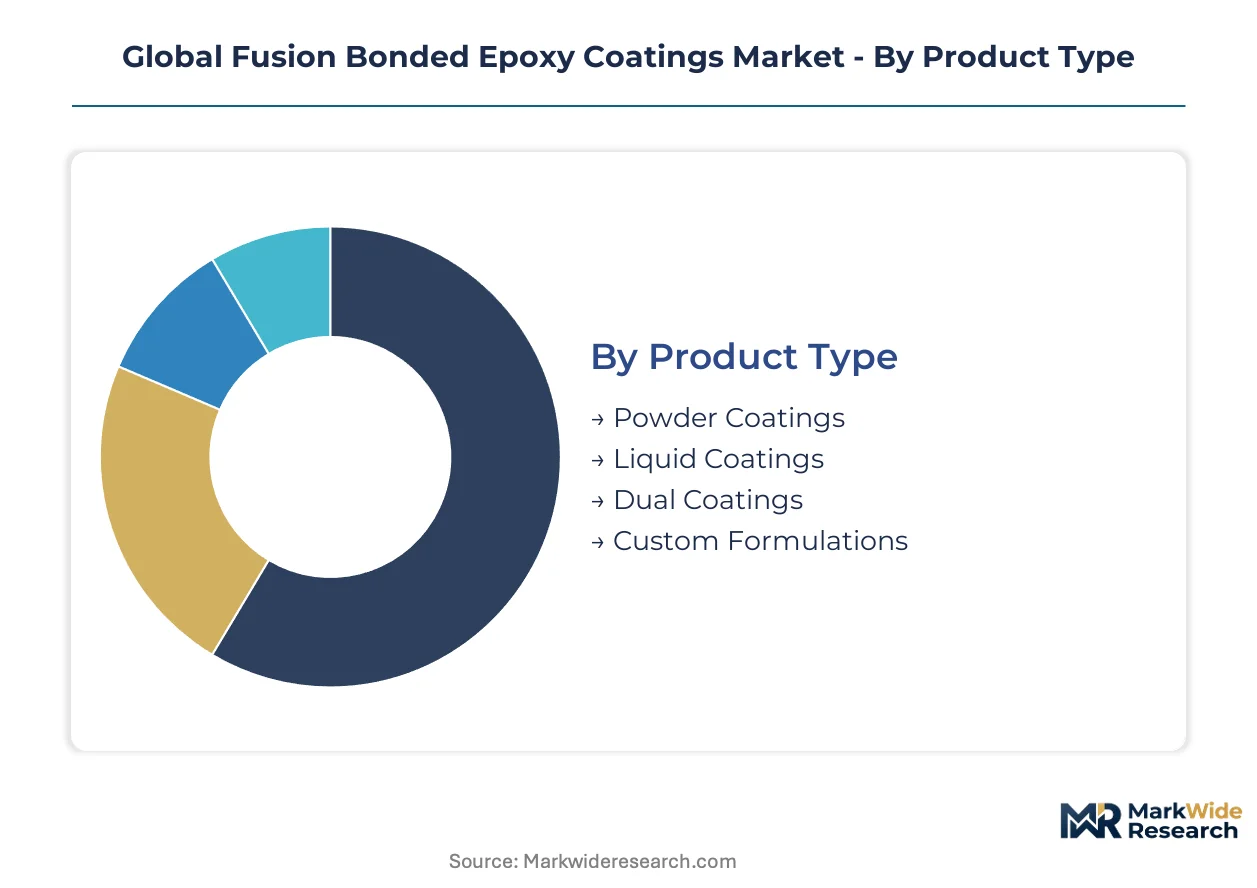
Segmentation in fusion bonded epoxy coatings reveals how specification requirements fragment across factory automation, field repair constraints, and multi-mechanism degradation environments. Product format and deployment method choices cascade through qualification timelines, capital intensity, and regulatory compliance burdens.
Product Type:
The customization-standardization spectrum runs from commodity powder systems to engineered dual-layer architectures, with liquid formats occupying a middle ground of application flexibility.
- Powder Coatings:Thermosetting polymer systems applied as dry particulates that cure at 180–250°C to form dense barriers with 250–500 micron dry-film thickness. Demand concentrates at mill-applied pipeline coating facilities on the United States Gulf Coast, where automated electrostatic spray lines support high-throughput API 5L2 specifications and cathodic disbondment resistance requirements are tightening.
- Liquid Coatings:Ambient-cure or low-temperature formulations deployed as liquid suspensions for field joint repairs and rebar coating applications. Norwegian and German contractors specify these for tie-in operations where portable induction heating is unavailable, though thermal resistance trade-offs persist against powder alternatives.
- Dual Coatings:Combined fusion bonded epoxy base layers with abrasion-resistant overlays for deepwater riser and flowline segments.
- Custom Formulations:Nano-modified epoxy resins incorporating graphene or clay platelet additives for thermal cycling resistance in Brazil's pre-salt fields.
Leading the category by volume: Powder Coatings. Growing fastest: Liquid Coatings.
Application:
Cost tier separation distinguishes capital-intensive pipeline infrastructure from lower-unit-value industrial maintenance cycles.
- Pipeline Protection:Buried and subsea steel pipe corrosion prevention governed by API 5L2, ISO 21809-2, and NACE SP0394. Gulf of Mexico and North Sea operators are accelerating riser recoating programs as infrastructure ages, with three-layer polyethylene systems losing share to fusion bonded epoxy for superior cathodic protection compatibility.
- Rebar Coating:Steel reinforcement corrosion barriers for concrete structures in aggressive environments. Japanese construction specifications favor liquid epoxy formats for precast concrete facilities where heat-cured powder application is impractical.
- Wire & Cable Coating:Electrical insulation and environmental sealing for power transmission and subsea umbilicals.
- Industrial Machinery Covering:Protective barriers for processing equipment in chemical and petrochemical plants.
- Corrosion Prevention:General-purpose protective coatings for structural steel across marine and industrial settings.
Highest capital deployment: Pipeline Protection. Steepest expansion trajectory: Rebar Coating.
End User Industry:
Customer type segmentation separates specification-integrated OEMs from fragmented maintenance contractors.
- Oilfield Equipment Manufacturers:Integrated line pipe producers in Japan and South Korea bundling fusion bonded epoxy application with steel production and ocean freight, compressing procurement cycles for large-diameter transmission awards.
- Construction Companies:Infrastructure contractors specifying rebar and structural steel coatings under EPA stormwater regulations and OSHA hexavalent chromium exposure limits.
- Electrical Component Makers:Wire and cable fabricators requiring insulation-grade epoxy formulations.
- Heavy Equipment Producers:Mining and earthmoving machinery manufacturers coating hydraulic cylinders and structural frames.
- Marine Equipment Fabricators:Shipyards and offshore platform builders applying corrosion barriers under thermal shock resistance requirements exceeding standard API specifications in Nordic and North Atlantic markets.
Specification volume leader: Oilfield Equipment Manufacturers. Procurement pattern shift: Construction Companies.
Deployment Method:
Supply concentration in automated coating equipment shapes method selection across volume tiers.
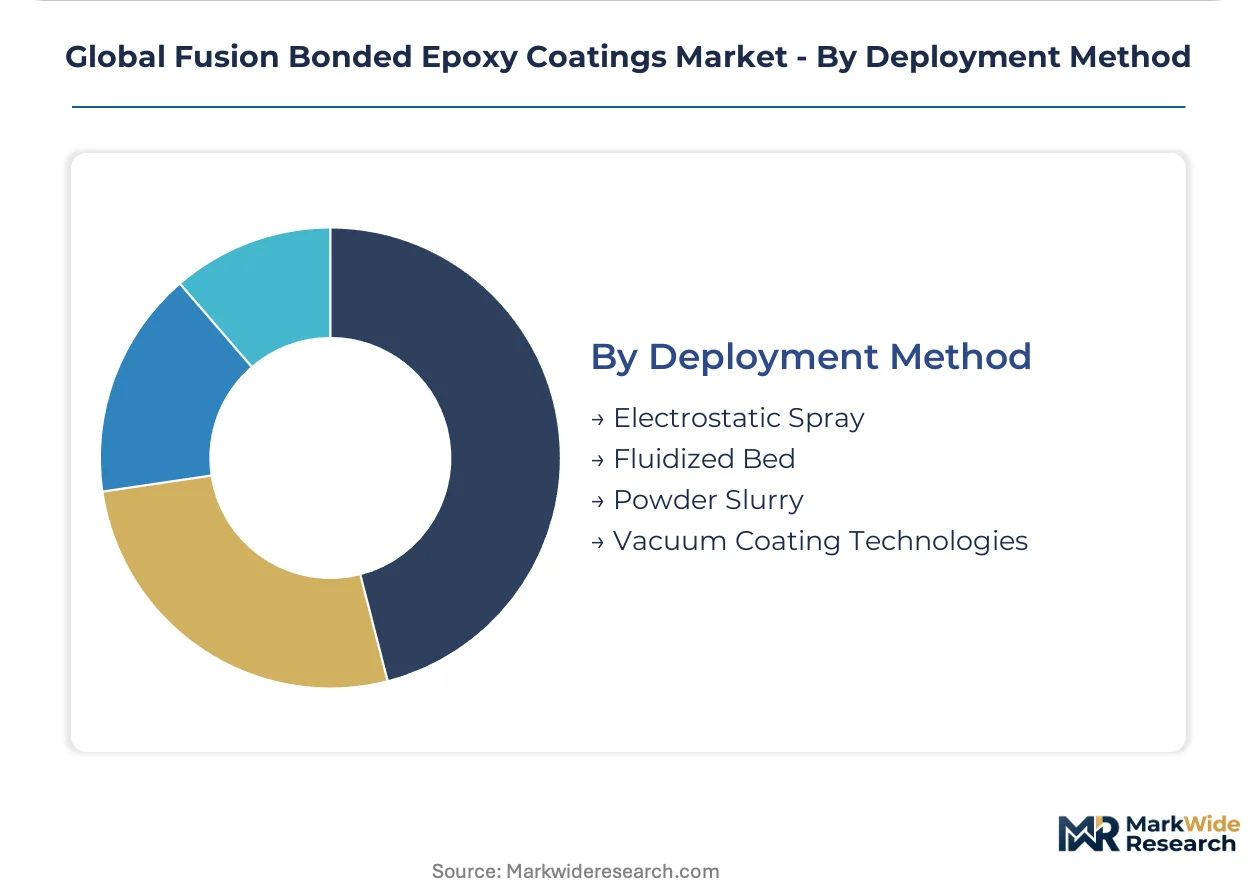
- Electrostatic Spray:Charged powder deposition onto grounded substrates with automated reciprocators achieving uniform coverage. Dominates mill-applied pipeline specifications where throughput and film thickness control are critical.
- Fluidized Bed:Preheated parts immersed in aerated powder beds for complex geometries. German and Dutch applicators favor this for valve fittings and short-radius elbows where spray line-of-sight is obstructed.
- Powder Slurry:Aqueous suspensions combining powder handling convenience with liquid application flexibility.
- Vacuum Coating Technologies:Reduced-pressure deposition for specialized electrical and electronic component applications.
Dominant method by installed capacity: Electrostatic Spray. Technology gaining specification share: Fluidized Bed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones along the United States Gulf Coast concentrate mill-applied coating capacity, drawing pipeline steel through Houston and Corpus Christi before export to Latin American and West African offshore projects.
United States
Permian Basin gathering lines and Gulf of Mexico riser refurbishment drive specification volumes at Port Arthur coating facilities. OSHA hexavalent chromium exposure limits are forcing ventilation upgrades across Texas and Louisiana applicators. Houston anchors the highest concentration of API 5L2-qualified electrostatic spray lines serving shale infrastructure developers.
Germany
Carbon capture transport line specifications for repurposed natural gas infrastructure are accelerating demand in the Rhine-Ruhr industrial corridor. ECHA REACH substance restrictions on bisphenol-A derivatives are extending reformulation timelines for domestic formulators. Dortmund and Duisburg host testing facilities evaluating fusion bonded epoxy performance under high-pressure hydrogen permeation.
Norway
Dual-layer abrasion-resistant overlay systems command premium positioning for dense phase CO2 service on the Norwegian Continental Shelf. The country's national petroleum regulator mandates enhanced cathodic disbondment resistance for subsea tiebacks. Stavanger and Bergen concentrate engineering contractors specifying nano-modified epoxy hybrids for deepwater pre-salt developments.
Brazil
Pre-salt field riser specifications are driving thermal cycling resistance requirements beyond standard API benchmarks. The national petroleum regulator ANP enforces ISO 21809-2 compliance for subsea production systems. Rio de Janeiro anchors the procurement decisions for integrated coating-logistics contracts bundling steel production with mill-applied specifications.
China
Offshore pipeline steel exports to Southeast Asian markets are pulling coating capacity toward coastal special economic zones. GB standards alignment with API corrosion prevention protocols is compressing qualification timelines for domestic applicators. Tianjin and Qingdao concentrate fluidized bed coating facilities serving valve and fitting manufacturers.
Global Fusion Bonded Epoxy Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated line pipe producers capturing bundled procurement decisions while independent formulators defend position in repair and maintenance niches. The structure tilts toward consolidation at the premium specification tier, where API qualification timelines and marine heritage create defensive moats. Three archetypes dominate: marine coatings specialists with offshore operator relationships, diversified chemical conglomerates with captive resin supply, and regional applicators with logistics integration. Competitive moves center on backward integration into resin synthesis and bundling coating application with steel production and ocean freight.
Within the marine heritage tier, Jotun and Akzo Nobel occupy positions anchored by North Sea and Gulf of Mexico operator specifications. PPG Industries exemplifies the diversified chemical archetype with in-house control over powder and liquid formulation inputs. Among integrated service providers, Shawcor represents the bundled procurement model combining coating application with pipeline integrity management. These three patterns illustrate how qualification rigor, supply chain configuration, and geographic proximity to offshore clusters determine competitive positioning across mill-applied and field-deployed segments.
| Leading Market Players |
|---|
| Jotun |
| Akzo Nobel |
| 3M |
| BASF |
| PPG Industries |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Shawcor |
| Arkema Group |
| Others |
Supply & Pricing Matrix
Backward integration into resin synthesis anchors both supply security and margin control for diversified chemical conglomerates competing against marine heritage specialists. PPG Industries exemplifies this pattern through captive bisphenol-A epoxy production, insulating formulation lines from Chinese and German feedstock volatility while sustaining premium positioning against transactional procurement models.
Pricing Analysis
Volume-margins split sharply between mill-applied powder specifications and field-deployed liquid formats. Three-tier pricing structure across premium, standard, and economy levels separates API 5L2-qualified dual-layer systems for deepwater risers from commodity single-layer powders for gathering lines. Price differentiation rests on certification grade and cathodic disbondment resistance metrics. Pricing pressure stems from ECHA REACH reformulation costs extending European product development timelines. Construction contractors show highest price sensitivity due to EPA stormwater compliance burdens, while offshore operators prioritize thermal shock performance over unit cost.
Supply Chain Analysis
Skilled applicator availability constrains capacity expansion in Port Arthur, Houston, and Corpus Christi despite electrostatic spray line investments. Bisphenol-A and specialty amine hardener production clusters in China and Germany feed formulation facilities across the United States Gulf Coast and European industrial corridors. Supply chain risk centers on single-source vulnerability for nano-modified resin additives from Brazilian and Norwegian deepwater contractors. Distribution runs through integrated coating-logistics contracts bundling steel production with mill-applied specifications, displacing independent applicators in large-diameter transmission awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase as nano-modified epoxy resins displace conventional fusion bonded epoxy matrices in deepwater pre-salt specifications. Graphene and clay platelet additives are compressing the performance gap against thermoplastic composite liners.
For Market Incumbents: Extend qualification relationships with North Sea and Gulf of Mexico operators by accelerating hydrogen pipeline compatibility testing at Dortmund and Duisburg facilities. Deepen backward integration into hardener synthesis to offset ECHA REACH substance restriction impacts on European formulation timelines. Defend against integrated line pipe producers from Japan and South Korea by locking in multi-year coating-logistics contracts with Permian Basin shale developers.
For New Entrants and Emerging Players: Enter via liquid epoxy field joint coatings for Norwegian and German tie-in operations where portable induction heating infrastructure remains underdeveloped. Target ambient-cure rebar specifications in Japanese precast concrete facilities where heat-cured powder application is impractical. Pursue carbon capture transport line qualifications in the Rhine-Ruhr corridor as German and Dutch operators evaluate repurposed natural gas infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in bundled procurement models combining coating application with pipeline integrity management services. Long-term viability favors specialists with API 5L2 qualification heritage and marine coatings expertise over commodity powder applicators. Monitor hydrogen permeation test results from German transmission operators as the critical inflection signal for repurposed infrastructure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive bisphenol-A supply insulates PPG Industries from Chinese feedstock volatility. |
| Hydrogen Pipeline Compatibility Testing | Dortmund facilities evaluate fusion bonded epoxy under high-pressure permeation for German transmission operators. |
| Integrated Coating-Logistics Contracts | Japanese line pipe producers bundle mill-applied specifications with steel production and ocean freight. |
| Nano-Modified Epoxy Formulation | Graphene additives enhance thermal cycling resistance for Brazil's pre-salt deepwater risers. |
| ECHA REACH Reformulation Investment | Bio-based epoxy alternatives address bisphenol-A derivative restrictions in European supply chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with coating facility plant managers, procurement leads at oilfield equipment manufacturers, distribution channel partners, and technical R&D directors at formulation houses combined with API 5L2 specification databases, ECHA substance restriction timelines, and SEC 10-K disclosures. Bottom-up volume modeling across powder, liquid, and dual coating formats triangulated against top-down pipeline infrastructure investment tracking.
Data-stream reconciliation connected electrostatic spray capacity utilization rates with Permian Basin gathering line deployment schedules. Segmentation dimensions modeled include product format, application method, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs derived from facility expansion announcements, qualification timeline compression, and replacement cycle analysis for three-layer polyethylene systems. Hydrogen permeation test protocols and dense phase CO2 service specifications provided industry-specific demand inflection inputs.
Revisions become necessary when ECHA accelerates bisphenol-A authorization timelines, OSHA tightens hexavalent chromium exposure limits, or API issues corrosion prevention benchmark updates. Forecasts reflect assumptions about shale infrastructure investment continuity and offshore refurbishment cycle pacing. Material deviation in regulatory trigger schedules or feedstock supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electrically Conductive Coating Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
High Performance Epoxy Coating Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Anti-Microbial Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Powder Coating Booth Market
Coatings
Global Low Friction Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Japan Architectural Coatings Market