
 Fluoropolymer Additives Market | 2026-2036
Fluoropolymer Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoropolymer Additives Market Analysis
REACH is repositioning the European cost-of-entry calculus for fluoropolymer additive suppliers, forcing reformulation investments that favor incumbents with dedicated regulatory affairs infrastructure. Solvay leverages its integrated fluorochemicals chain to sustain compliance leadership across PTFE and FEP additive grades. Daikin Industries anchors Asia-Pacific supply through captive fluoromonomer production and localized technical service centers.
Fluoropolymer additives are specialty chemicals incorporating polytetrafluoroethylene (PTFE), fluorinated ethylene propylene (FEP), perfluoroalkoxy (PFA), or ethylene tetrafluoroethylene (ETFE) structures, typically supplied as micronized powders with particle sizes below 20 micrometers to reduce friction, enhance chemical resistance, or improve thermal stability in host matrices. Their primary industrial purpose centers on imparting non-stick, low-friction, and dielectric properties to coatings, adhesives, sealants, and plastics without compromising bulk mechanical performance. The PTFE product category dominates current volume flows due to its cost-performance ratio in industrial coatings, while PFA additives command premium positioning in semiconductor and healthcare applications where extractable limits are stringent. Powder and granule forms attract the majority of formulation demand, though emulsion formats are gaining traction in waterborne coating systems seeking volatile organic compound reductions.
The EPA regulates perfluorooctanoic acid (PFOA) and perfluorooctanesulfonic acid (PFOS) residues under the Toxic Substances Control Act, directly constraining additive purity thresholds for US-market coatings and plastics. ECHA's persistent organic pollutant assessments and the EU F-Gas Regulation collectively reshape acceptable fluoropolymer chemistries, with downstream implications for aerospace and automotive qualification protocols. China's MEE enforces discharge standards for fluorochemical manufacturing that affect additive production economics in Shandong and Zhejiang provinces. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
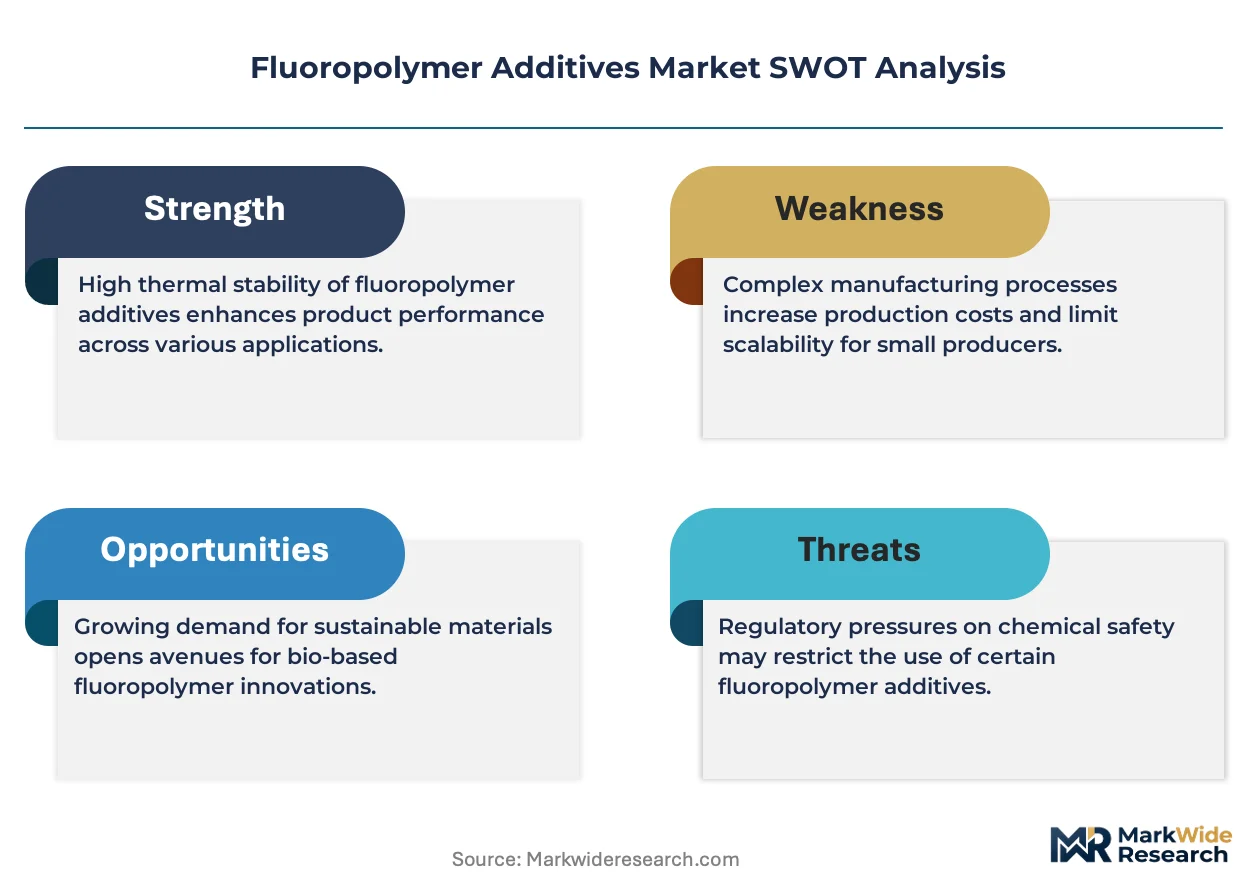
REACH restrictions on per- and polyfluoroalkyl substances are forcing wholesale reformulation across European coatings and plastics supply chains, redirecting capital toward short-chain fluoropolymer alternatives and compressing margins for non-compliant inventory.
Growth Catalysts
- EV battery thermal management:Automotive manufacturers are embedding PTFE and FEP additives into electric vehicle battery coatings to manage heat dissipation and dielectric isolation as pack densities rise.
- China's dual carbon goals:Domestic fluoropolymer additive production in Shandong and Zhejiang provinces is scaling to serve both local coatings producers and export-oriented plastics compounders.
- Waterborne coating transitions:Emulsion-format fluoropolymer additives are gaining formulation share as coatings producers seek volatile organic compound reductions under tightening environmental discharge standards.
Market Restraints
- Fluoromonomer supply concentration:Captive production of tetrafluoroethylene and hexafluoropropylene concentrates among integrated chemical majors, limiting independent additive producers' feedstock security.
- PFOA/PFOS residue thresholds:EPA Toxic Substances Control Act enforcement constrains additive purity for US-market coatings, requiring costly purification upgrades or reformulation.
- Silicone and ceramic substitute encroachment:Alternative low-friction and thermal barrier materials are capturing share in industrial coatings where fluoropolymer performance premiums cannot be justified.
Strategic Opportunities
- Semiconductor fabrication equipment:PFA additive demand is accelerating in wafer processing components where extractable limits are stringent and qualification cycles create incumbent advantage.
- Healthcare device coatings:Regulatory tailwinds from FDA device safety mandates are opening formulation opportunities for medical-grade fluoropolymer additives in catheter and implantable component coatings.
- Technical service localization:Regional compounding support centers in India and Southeast Asia can capture formulation development work currently concentrated in East Asian headquarters.
Industry Challenges
- Fluorochemical process engineering talent:Specialized expertise in controlled polymerization and micronization below 20 micrometers is concentrated among retiring cohorts at established producers.
- Cross-jurisdictional inventory stranding:Divergent purity standards between EPA, ECHA, and China's MEE enforcement create compliance complexity for multi-regional additive distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoropolymer Additives Market |
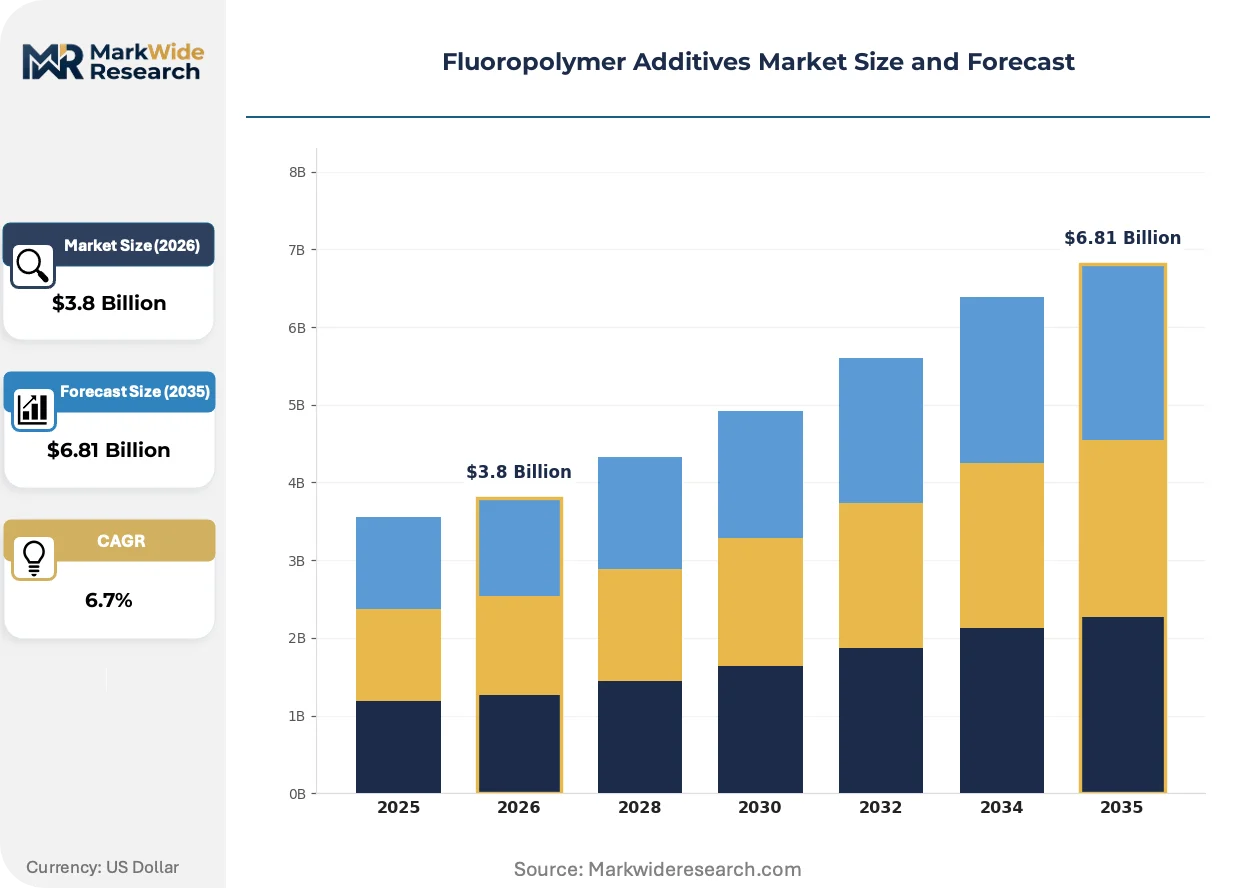
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE Application: Coatings, Adhesives, Sealants, Plastics End Use Industry: Aerospace, Automotive, Electronics, Healthcare Form: Powder, Granules, Emulsion, Suspension |
| Companies Covered | Solvay, Arkema, DuPont, Gujarat Fluorochemicals, Shamrock Technologies, Daikin Industries, The Chemours Company, Micro Powders, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoropolymer Additives Market Emerging Trajectories
Reformulation chemistry and particle engineering are converging to redefine competitive positioning in fluoropolymer additives, with regulatory compliance and end-use performance specifications driving simultaneous innovation across multiple technology fronts.
Nano-scale PTFE dispersions are absorbing volume from conventional micronized powders in high-performance coatings applications. Aerospace and automotive OEMs are qualifying these grades for friction reduction in fuel system components and landing gear assemblies. The technology is absorbing market share previously held by larger-particle additives by enabling thinner film builds without sacrificing wear resistance.
ECHA's persistent organic pollutant assessments are accelerating the phase-out of long-chain fluoropolymer chemistries across European industrial coatings. Downstream implications extend to aerospace qualification protocols, where OEMs must recertify supply chains under revised material specifications. Semiconductor and healthcare applications are responding fastest, given their pre-existing sensitivity to extractable contamination limits.
Compounders are consolidating procurement relationships around integrated suppliers offering captive fluoromonomer production and regional technical service. This behavior is displacing spot-market purchasing for standard PTFE additive grades. The shift is most visible in China, where domestic coatings producers are signing multi-year offtake agreements with Shandong-based integrated producers to secure volume and formulation support.
Fluoropolymer Additives Market Segmentation
Fluoropolymer additive purchasing decisions pivot on performance specifications versus regulatory compliance thresholds. Buyers segment procurement by chemistry purity, application processing requirements, and end-use qualification protocols. Form factor selection directly determines formulation compatibility and manufacturing integration costs.
Product Type:
Cost-performance positioning drives chemistry selection across industrial versus premium application tiers.
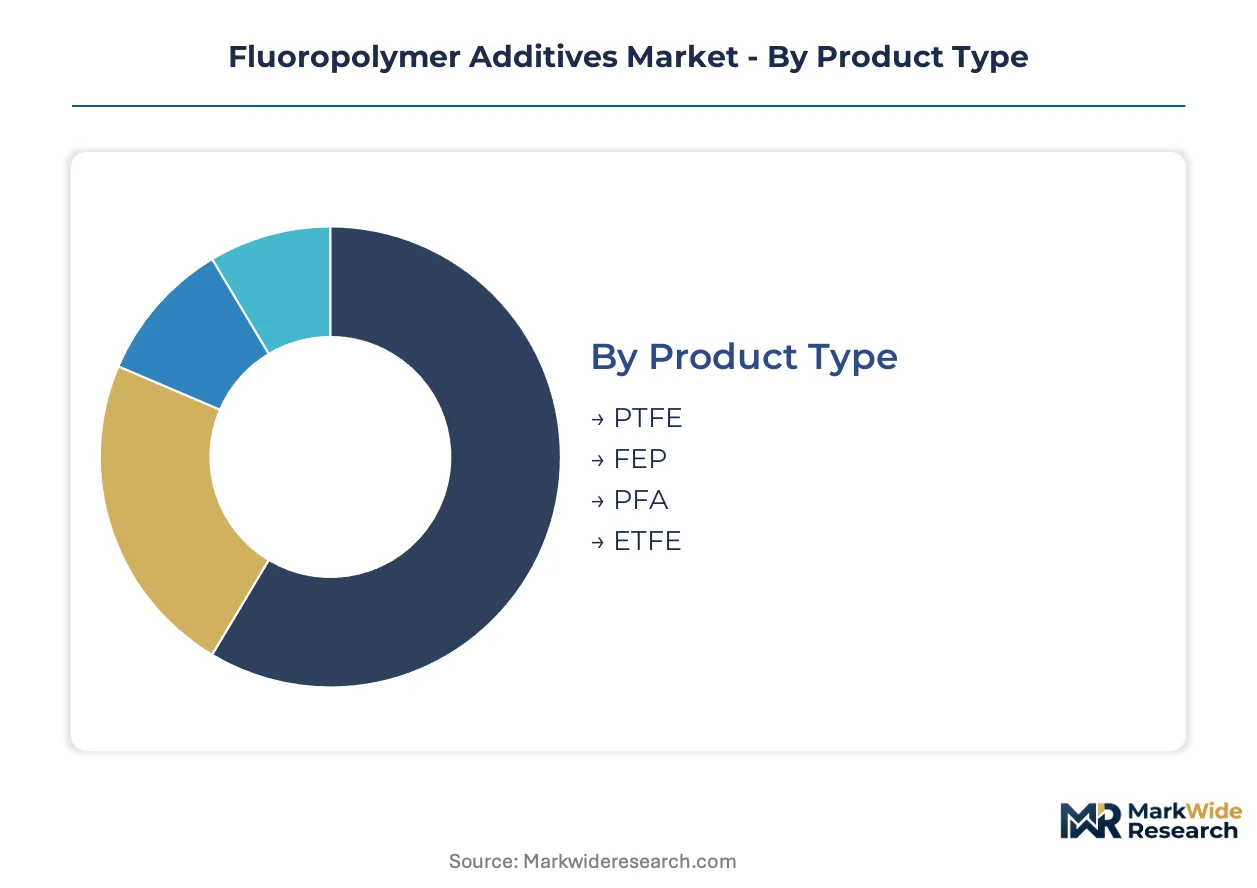
- PTFE:Micronized polytetrafluoroethylene powders dominate volume flows through superior cost-performance ratios in industrial coatings. Demand concentrates in China's Shandong and Zhejiang province coatings clusters serving both domestic producers and export compounders, constrained by REACH-driven reformulation investments toward short-chain alternatives.
- PFA:Perfluoroalkoxy additives command premium positioning through ultra-low extractable limits. Semiconductor fabrication equipment manufacturers in Japan and South Korea anchor demand as wafer processing component specifications tighten.
- FEP:Fluorinated ethylene propylene serves EV battery thermal management systems where dielectric isolation and heat dissipation converge.
- ETFE:Ethylene tetrafluoroethylene additives penetrate aerospace fuel system components requiring thin-film wear resistance.
PTFE leads on scale; PFA leads on momentum.
Application:
Processing method and substrate compatibility determine formulation selection across surface protection and bulk modification uses.
- Coatings:Industrial coatings absorb the majority of PTFE and FEP additive volume through non-stick and low-friction surface requirements. Waterborne coating transitions are accelerating emulsion-format adoption as producers seek volatile organic compound reductions under EPA and MEE discharge standards.
- Plastics:Compounding applications embed fluoropolymer additives to reduce friction and enhance chemical resistance without compromising bulk mechanical performance. Automotive manufacturers expanding electric vehicle battery coatings anchor demand growth in this segment.
- Adhesives:Specialty adhesive formulations leverage fluoropolymer additives for chemical inertness in harsh environment bonding.
- Sealants:High-performance sealing applications require thermal stability and low surface energy properties.
Coatings commands current volume; plastics is climbing the fastest.
End Use Industry:
Qualification cycle length and regulatory scrutiny intensity segment buyer priorities across industrial verticals.
- Automotive:Electric vehicle battery thermal management and fuel system friction reduction are embedding PTFE and FEP additives into qualification protocols. OEMs in Germany and Japan are recertifying supply chains under revised material specifications responding to ECHA persistent organic pollutant assessments.
- Healthcare:FDA device safety mandates are opening formulation opportunities for medical-grade fluoropolymer additives in catheter and implantable component coatings. Extractable limit sensitivity creates incumbent advantage through qualification cycle barriers.
- Aerospace:Landing gear assemblies and fuel system components are qualifying nano-scale PTFE dispersions for thinner film builds.
- Electronics:Semiconductor fabrication equipment demands PFA additives with stringent contamination controls.
Automotive leads on scale; healthcare is gaining share fastest.
Form:
Manufacturing integration and environmental compliance requirements determine physical format selection.
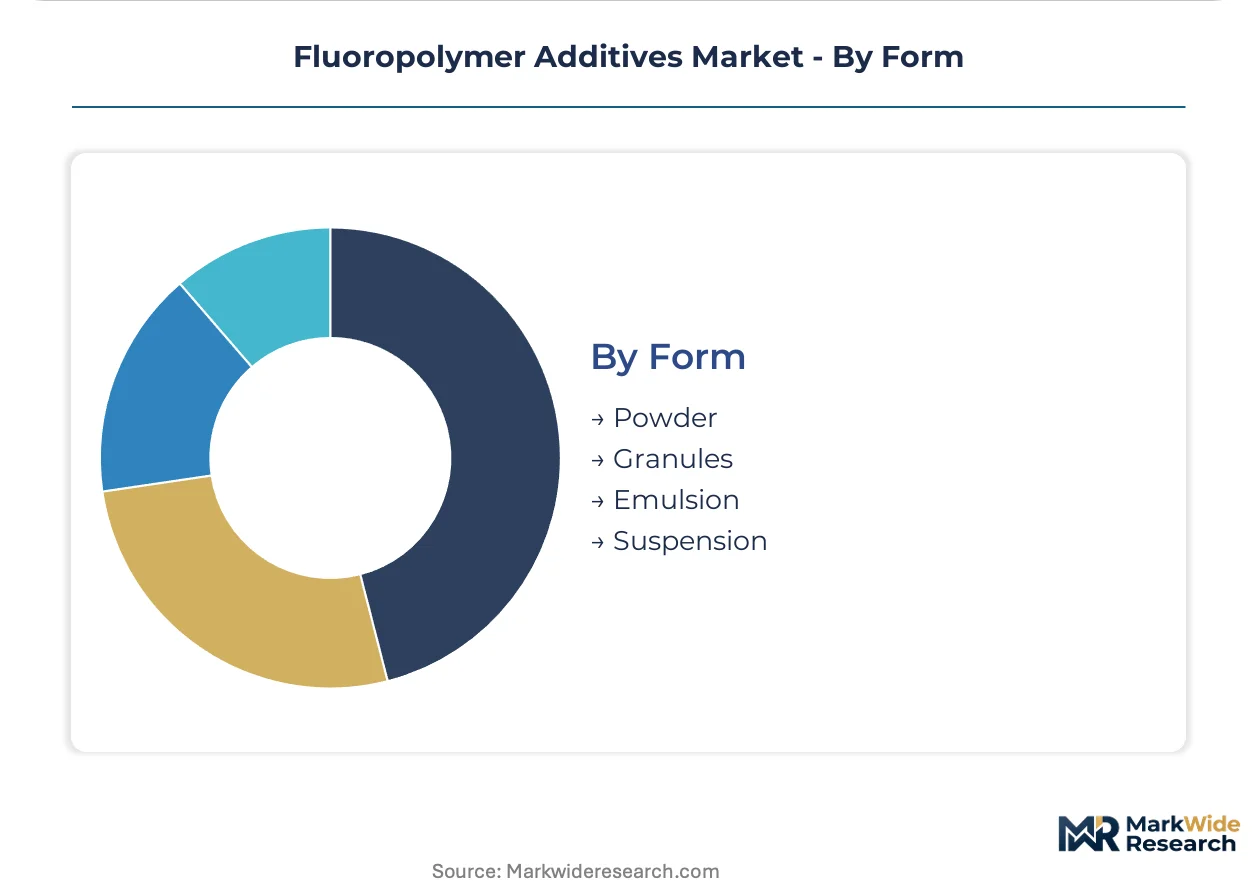
- Powder:Micronized powders below 20 micrometers attract majority formulation demand through established compounding infrastructure and processing familiarity. Dry handling systems dominate industrial coatings and plastics compounding workflows.
- Emulsion:Waterborne formats are gaining traction as coatings producers reformulate for volatile organic compound reductions. MEE discharge standards in China and EPA enforcement in the US are accelerating this transition.
- Granules:Free-flowing granular forms serve high-throughput extrusion and molding operations.
- Suspension:Liquid suspension formats enable precise dosing in continuous coating line applications.
Powder leads on scale; emulsion shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fluorochemical process engineers cluster in Germany's industrial belt, Japan's chemical corridor, and China's eastern manufacturing provinces, anchoring regional production capabilities and formulation expertise for fluoropolymer additive supply chains.
China
Shandong and Zhejiang province coatings clusters drive domestic PTFE additive consumption for both local producers and export compounders. MEE discharge standards enforce wastewater treatment investments that reshape production economics in fluorochemical manufacturing zones. Qingdao and Hangzhou-based integrated producers are signing multi-year offtake agreements to secure volume and technical service relationships.
United States
EPA Toxic Substances Control Act enforcement constrains PFOA and PFOS residue thresholds for coatings and plastics applications, forcing purification upgrades or reformulation investments. Automotive OEMs in Michigan and Ohio are embedding PTFE additives into EV battery thermal management qualification protocols. Gulf Coast fluoromonomer production supports captive additive manufacturing for industrial coatings producers.
Germany
ECHA persistent organic pollutant assessments and EU F-Gas Regulation reshape acceptable fluoropolymer chemistries across aerospace and automotive supply chains. REACH-driven reformulation investments favor incumbents with dedicated regulatory affairs infrastructure. Industrial coatings producers in North Rhine-Westphalia are recertifying supply chains under revised material specifications.
Japan
Semiconductor fabrication equipment manufacturers in Kyushu and the Kanto region anchor PFA additive demand through ultra-low extractable limit requirements. METI industrial policy supports domestic fluoromonomer production for specialty additive grades. Osaka-based technical service centers provide localized formulation support for regional coatings compounders.
South Korea
Wafer processing component specifications in Gyeonggi Province drive premium PFA additive consumption for contamination-sensitive semiconductor applications. MFDS regulatory alignment with international extractable standards accelerates healthcare device coating qualifications. Busan-Ulsan chemical complexes support integrated fluoropolymer additive production for export markets.
Fluoropolymer Additives Market Vendor Landscape
The competitive structure tilts toward integrated chemical majors with captive fluoromonomer production and dedicated regulatory compliance infrastructure. Three archetypes dominate: diversified fluorochemical conglomerates controlling upstream tetrafluoroethylene and hexafluoropropylene supply, specialized micronization houses focused on particle engineering below 20 micrometers, and regional compounders offering localized technical service. Capacity expansion and backward integration into fluoromonomer production represent the dominant competitive moves as feedstock security becomes a primary differentiator.
Among diversified fluorochemical conglomerates, Solvay and Daikin Industries exemplify the integrated archetype through their captive supply chains and multi-regional technical service networks. Gujarat Fluorochemicals occupies a position within the emerging integrated tier, representing the shift toward Asia-Pacific production gravity for standard PTFE additive grades. Shamrock Technologies sits within the specialized micronization segment, illustrating the independent additive producer model focused on particle engineering expertise rather than upstream chemical integration.
| Leading Market Players |
|---|
| Solvay |
| Arkema |
| DuPont |
| Gujarat Fluorochemicals |
| Shamrock Technologies |
| Daikin Industries |
| The Chemours Company |
| Micro Powders |
| 3M |
| Others |
Supply Flow & Price Mechanics
Automotive OEM recertification demands under ECHA persistent organic pollutant assessments are forcing additive suppliers to absorb reformulation costs while maintaining price competitiveness against silicone and ceramic substitutes. This demand-side pressure concentrates pricing power among integrated producers with captive fluoromonomer supply chains.
Pricing Analysis
Bundled technical service and qualification support versus unbundled commodity powder sales splits the market into two pricing models. Three-tier pricing structure across semiconductor-grade PFA, automotive-qualified FEP, and industrial PTFE separates premium contamination-controlled tiers from standard coating grades. Cost compression in industrial PTFE intensifies as China's Shandong-based integrated producers expand capacity. Commodity compounders in plastics applications exhibit highest price sensitivity; semiconductor fabricators accept premium positioning for extractable-limited grades.
Supply Chain Analysis
Certification and qualification gating through aerospace OEM protocols and FDA device safety mandates restricts supply chain participation to established producers with multi-year qualification histories. China, Japan, and Germany anchor global supply through integrated fluorochemical complexes in Shandong, Kyushu, and North Rhine-Westphalia. Tetrafluoroethylene monomer, hexafluoropropylene feedstock, and micronization equipment draw from concentrated chemical majors. Single-source vulnerability in fluoromonomer supply creates structural risk for independent additive producers. Distribution runs through regional compounding centers with localized formulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA-driven reformulation costs in Europe diverge from China's MEE discharge standard compliance economics, creating margin capture opportunities for producers with multi-regional regulatory infrastructure.
For Market Incumbents: Acquire micronization technology specialists below 20 micrometer particle engineering capability to consolidate particle engineering expertise before retiring cohorts exit. Backward integration into hexafluoropropylene production defends feedstock security against fluoromonomer supply concentration. Invest in regional technical service centers in India and Southeast Asia to preempt new entrant localization strategies. For New Entrants and Emerging Players: Regional compounders serving waterborne coating transitions in India's emerging industrial corridors offer the most penetrable channel partner type for emulsion-format additive distribution. Target healthcare device coating qualifications where FDA safety mandates create formulation openings and incumbent advantage remains incomplete. Pursue joint development agreements with domestic coatings producers in Shandong province to secure volume commitments before multi-year offtake agreements close. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized micronization houses possessing sub-20 micrometer particle engineering expertise and established aerospace qualification protocols. Long-term viability over a five-to-ten year window favors targets with semiconductor and healthcare certification moats rather than commodity PTFE exposure. Watch for ECHA persistent organic pollutant assessment acceleration as the inflection signal triggering consolidation among reformulation-lagged producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoromonomer Production | Captive tetrafluoroethylene supply insulates margin position against feedstock concentration risk. |
| Regional Technical Service Localization | Compounding support centers in India capture formulation development from East Asian headquarters. |
| Long-term Supply Agreement | Multi-year offtake contracts with Shandong producers secure volume amid MEE discharge investments. |
| Green Manufacturing Transition | Waterborne emulsion formats align with EPA and MEE volatile organic compound reduction mandates. |
| Joint Venture | Partnerships with semiconductor fabricators in Kyushu lock in PFA additive qualification cycles. |
Methodological Framework
Direct dialogue with fluoropolymer additive plant managers, procurement leads at automotive and semiconductor OEMs, distribution channel partners, and technical R&D directors grounded qualitative insights. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed fluorochemical producers, and EPA enforcement actions. Bottom-up volume modeling across chemistry grades and end-use industries triangulated against top-down macroeconomic indicators.
Bottom-up segment-level modeling across PTFE, PFA, FEP, and ETFE chemistries converged with top-down industrial coatings and plastics compounding demand projections. Segmentation dimensions included chemistry purity tier, end-use industry qualification protocol, physical form factor, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating EV battery thermal management adoption curves and semiconductor fabrication capacity expansion. Forecast inputs captured REACH reformulation timelines and China's dual carbon policy implementation intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA persistent organic pollutant assessment acceleration and fluoromonomer supply disruption scenarios. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and substitution elasticity between fluoropolymer and silicone alternatives. A model refresh is warranted upon material change in EPA PFOA residue threshold enforcement or MEE discharge standard revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Russia Sodium Reduction Ingredient Market
Additives
FD and C Lakes Market
Additives
Ammonium Phosphatide Market
Additives
Anti-Settling Agents Market
Additives
Grease Additives Market
Additives
Citric Acid Anhydrous Market
Additives
Global Feed Acidifiers Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Marine Fuel Additives Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Benzoates Market
Additives
Crosslinking Agents Market
Additives
Pearlizers Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Americas Coating Additives Market
Additives
Volatile Corrosion Inhibitors Market