
 Cool Roof Coatings Market | 2026-2036
Cool Roof Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Cool Roof Coatings Market Intelligence
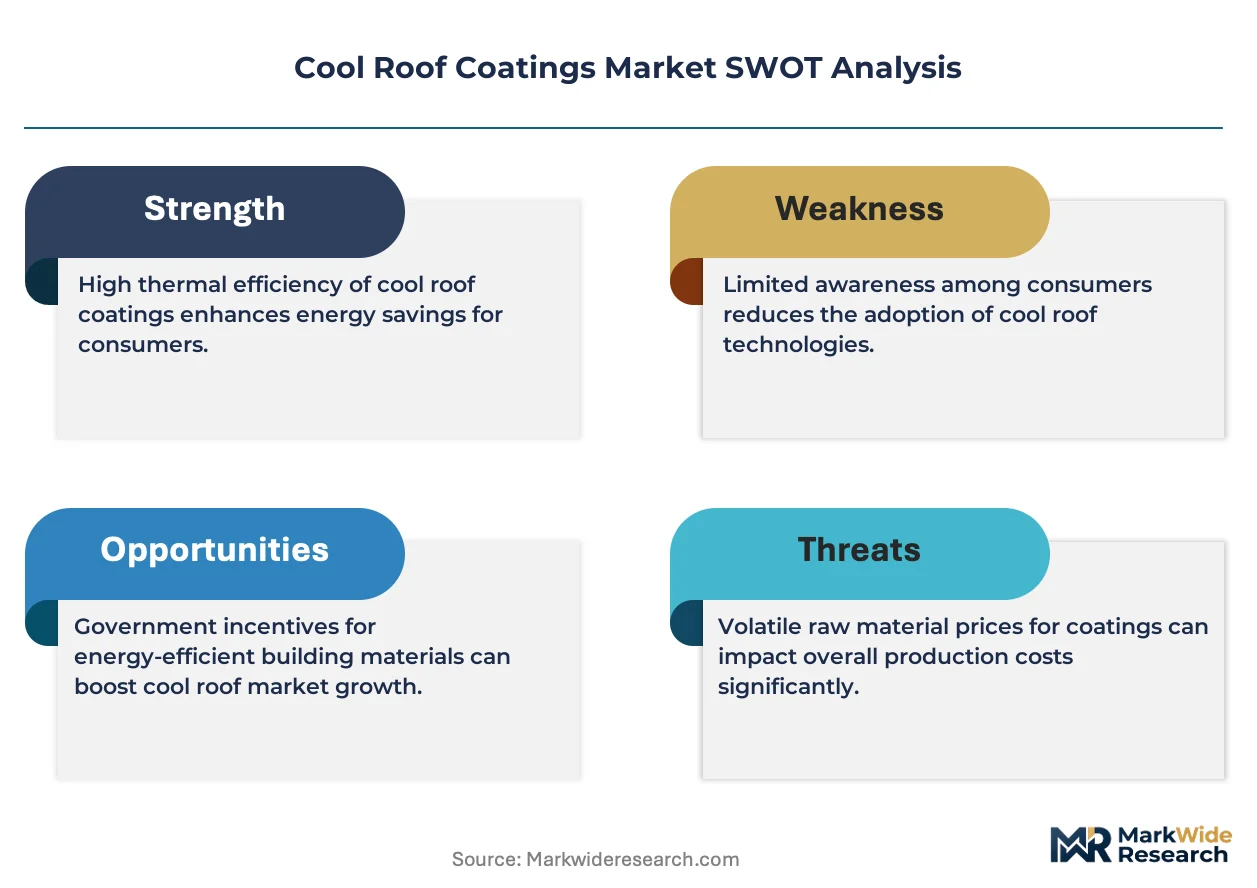
Project finance for large-scale commercial retrofit portfolios is fragmenting the competitive landscape, enabling smaller contractors to bid on previously capital-intensive installations. The Dow Chemical Company leverages its integrated silicone supply chain to sustain cost advantages in elastomeric formulations. Sherwin-Williams Company anchors distribution through its architectural coatings network, while Sika AG competes on specification relationships with European engineering firms.
Cool roof coatings are thin-film emulsions or membranes engineered with high solar reflectance index values, typically incorporating acrylic, silicone, or polyurethane binders with titanium dioxide or ceramic pigments to minimize thermal absorption. Their primary purpose is reducing building cooling loads by reflecting infrared and visible radiation. Reflective coatings dominate current specification volumes due to proven performance in hot-dry climates, while elastomeric coatings represent the fastest-expanding category because of their combined reflectance and waterproofing function. Foam coatings occupy a narrower niche where insulation-upgrade integration justifies material cost premiums.
US EPA Energy Star roofing standards and California Title 24 jointly establish product performance baselines that manufacturers must certify against for market access. The EU Green Deal renovation wave and REACH chemical compliance requirements are reshaping formulation chemistry across exported product lines. Stakeholders should monitor how emerging state-level stretch codes in jurisdictions like New York and Massachusetts tighten reflectance minimums ahead of federal benchmarks.
Market Dynamics
California's Title 24 Building Energy Efficiency Standards are compressing specification windows for conventional dark roofing materials, forcing reformulation cycles and recertification investments across the supply base.
Growth Catalysts
- Cooling-degree-day intensity:The American Southwest's extreme thermal loading creates lifecycle cost advantages that accelerate reflective envelope investments in Arizona, Nevada, and New Mexico commercial portfolios.
- EPA Energy Star roofing standards:Federal performance baselines expand addressable market access by establishing third-party validation protocols that reduce buyer due diligence friction.
- Elastomeric waterproofing integration:Silicone-acrylic hybrid chemistries consolidate roof maintenance budgets by combining reflectance and membrane repair functions in single-application systems.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin stability for acrylic and polyurethane formulation houses dependent on chloride-process TiO2.
- REACH chemical compliance:EU Green Deal renovation wave requirements force solvent system phase-outs that extend R&D timelines for exported product lines.
- Single-ply membrane substitution:TPO and PVC roofing systems with factory-applied reflective surfaces capture low-slope new construction specifications that bypass field-applied coatings.
Strategic Opportunities
- Massachusetts stretch code adoption:State-level reflectance minimums ahead of federal benchmarks create first-mover certification advantages for pre-qualified coating systems.
- Project finance fragmentation:Retrofit portfolio securitization enables smaller contractors to bid previously capital-intensive installations, expanding channel reach.
- Cool roof-as-a-service models:Energy savings performance contracting converts capital expenditure barriers into operational expenditure streams for municipal and institutional buyers.
Industry Challenges
- Applicator certification bottlenecks:Manufacturer warranty programs require trained installer networks that expand slower than specification demand, creating installation backlogs.
- Substrate compatibility testing:Legacy built-up roofing and modified bitumen surfaces demand adhesion validation protocols that extend project timelines and increase specification risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cool Roof Coatings Market |
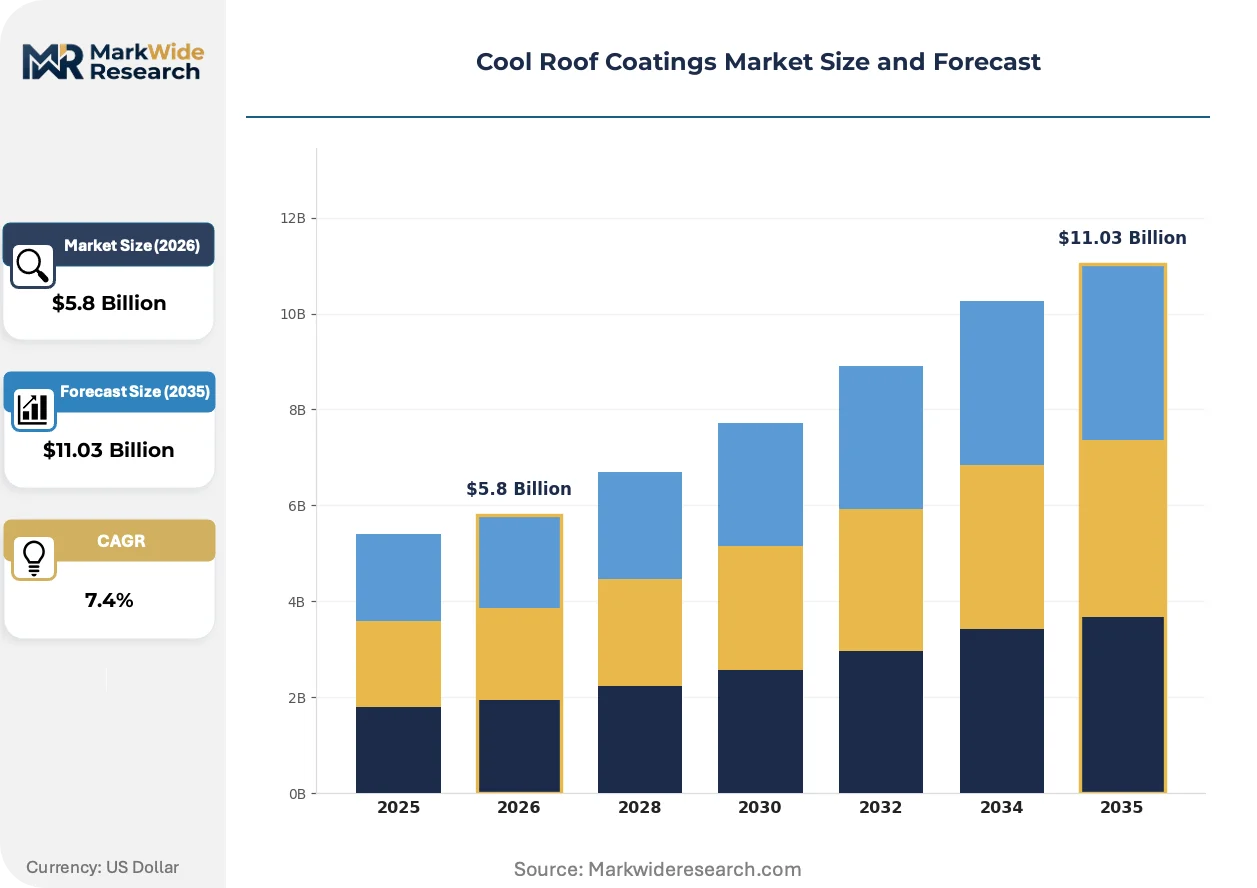
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reflective Coatings, Elastomeric Coatings, Foam Coatings, Bituminous Coatings End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions Technology: Spray Application, Roll-on Application, Brush Application, Dip Coating Installation: New Construction, Retrofitting, Maintenance, Repair |
| Companies Covered | The Dow Chemical Company, RPM International Inc., PPG Industries, Sika AG, Nippon Paint Holdings Co., Ltd., BASF SE, Sherwin-Williams Company, GAF Materials Corporation, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cool Roof Coatings Market Strategic Shifts & Innovations
Formulation chemistry and application methodology are converging to compress total installed cost while extending service life expectations beyond conventional maintenance cycles.
Ceramic microsphere additives are rendering obsolete traditional pigment-heavy formulations in high-solar-reflectance specifications. Military and data center portfolios in Texas and Florida are specifying these systems for thermal shock resistance. The technology is rendering obsolete specification preferences that prioritized titanium dioxide loading over infrared emissivity performance.
REACH chemical compliance requirements are forcing solventborne system phase-outs across European export lines. Manufacturers reformulate waterborne acrylics to match elastomeric durability benchmarks. The American Southwest retrofit segment absorbs premium pricing for compliant imports to maintain specification eligibility in federally funded projects.
Building owner procurement teams now require modeled energy savings guarantees backed by calibrated simulation software. Performance risk shifts from capital budget holders to coating applicators and their manufacturer partners. New York City commercial retrofits exhibit this pattern most acutely, with Local Law 97 carbon penalties driving guaranteed-outcome contracting structures.
Cool Roof Coatings Market Segmentation
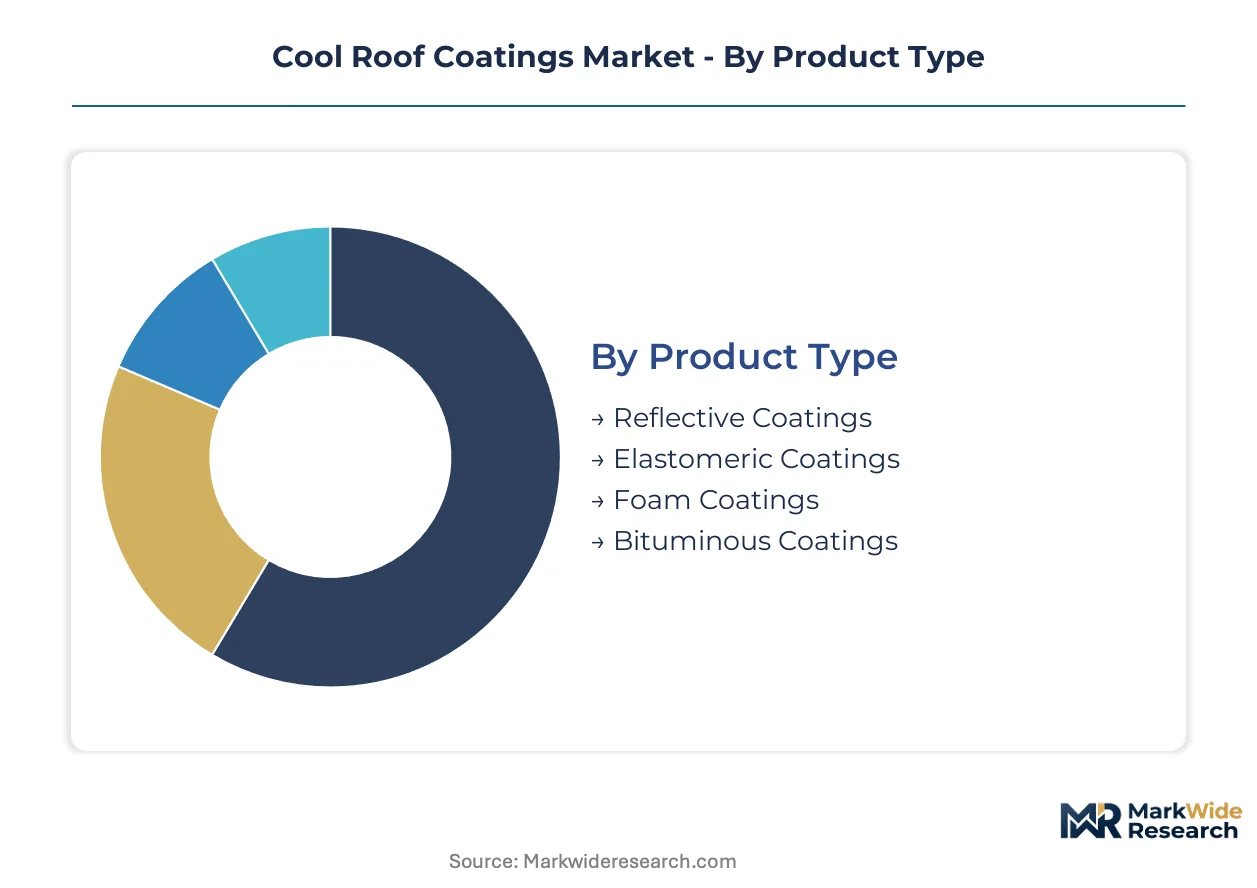
Cool roof coatings demand fragments across distinct technical specifications, building ownership models, and project lifecycle stages. Each segmentation dimension reveals divergent margin structures and specification authority patterns that reshape competitive positioning.
Product Type:
Cost tier stratification separates commodity formulations from premium elastomeric systems with integrated waterproofing.
- Reflective Coatings:Acrylic and silicone-based thin-film emulsions engineered with titanium dioxide or ceramic pigments for high solar reflectance index values. Commercial building portfolios across Arizona and Nevada specify these systems for lifecycle cooling cost reduction in extreme thermal loading environments.
- Elastomeric Coatings:Silicone-acrylic hybrid chemistries combining reflectance with membrane repair and waterproofing functions. The steepest expansion runs through this segment as building owners consolidate roof maintenance budgets into single-application systems.
- Foam Coatings:Spray polyurethane systems integrating insulation upgrade with reflective surface performance. Data center and cold storage facilities in Texas absorb material cost premiums where R-value enhancement justifies specification.
- Bituminous Coatings:Modified asphalt formulations with aluminum flake reflectance for legacy built-up roofing compatibility. Industrial facilities with aging substrate infrastructure drive residual demand.
Reflective coatings command the established base. The steepest expansion runs through elastomeric systems.
End User:
Application context determines specification authority—institutional procurement teams versus individual owner-operators.
- Commercial Buildings:Office and retail portfolios with professional facility management drive standardized specification across multi-site retrofits. California Title 24 compliance mandates concentrate demand in this segment.
- Residential Buildings:Single-family and low-rise multifamily applications where homeowner association aesthetics constraints limit specification flexibility. Southwestern US sunbelt markets absorb premium pricing for energy code compliance.
- Industrial Facilities:Manufacturing and warehouse operations with large roof surface-to-volume ratios. EPA Energy Star validation protocols reduce procurement friction for energy-intensive operations.
- Educational Institutions:K-12 and university campuses with municipal bond financing for capital improvements. Massachusetts stretch code adoption creates first-mover certification advantages for pre-qualified systems.
Commercial buildings anchor volume concentration. Educational institutions gain share fastest as municipal sustainability mandates tighten.
Technology:
Application methodology determines labor productivity, substrate compatibility, and total installed cost structures.
- Spray Application:Airless and plural-component systems for large-area coverage on low-slope commercial roofs. Contractor certification bottlenecks constrain deployment velocity despite specification demand.
- Roll-on Application:Conventional roller and squeegee methods for detail work and repair zones. Smaller contractors bid retrofit portfolios through project finance fragmentation.
- Brush Application:Manual precision application for flashing, penetrations, and complex geometries. Maintenance and repair segments absorb higher labor intensity.
- Dip Coating:Factory-applied systems for metal roofing components and pre-fabricated panels. Limited field relevance due to substrate size constraints.
Spray systems dominate commercial new construction. Roll-on methods climb fastest as retrofit securitization expands contractor access.
Installation:
Project lifecycle positioning separates capital expenditure decisions from operational maintenance budgets.
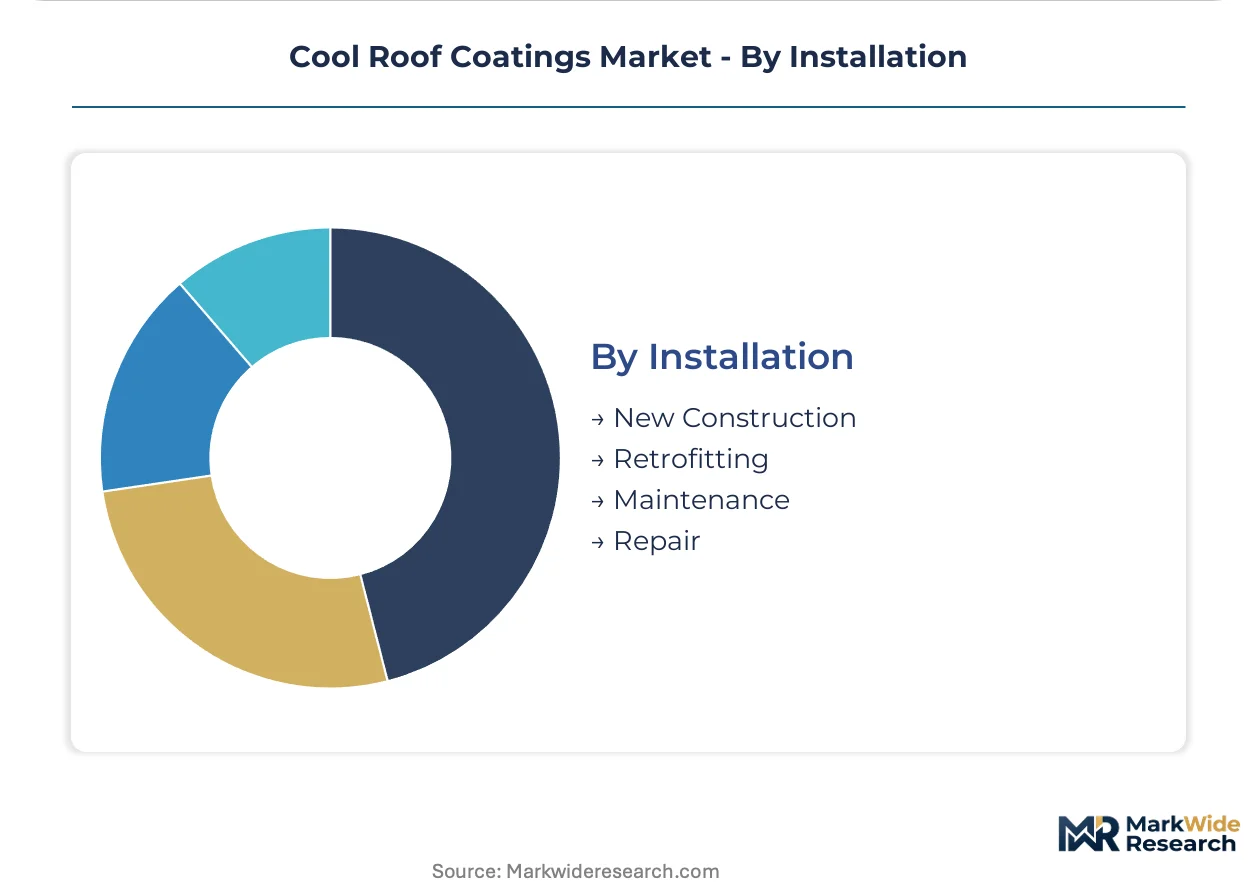
- New Construction:Architect and general contractor specification during envelope design. Single-ply membrane substitution with factory-applied reflective surfaces captures share in this segment.
- Retrofitting:Existing building energy upgrade projects driven by code compliance and carbon penalty avoidance. New York City Local Law 97 structures drive guaranteed-outcome contracting.
- Maintenance:Scheduled recoating cycles to preserve reflectance performance and warranty validity. Building owner procurement teams now require modeled energy savings guarantees.
- Repair:Reactive intervention for storm damage, membrane failure, or adhesion loss. Substrate compatibility testing extends project timelines and increases specification risk.
Retrofitting commands current investment flows. Maintenance contracts expand most quickly as performance risk shifts to applicator-manufacturer partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Japanese formulation houses service Middle Eastern retrofit demand, while Chinese manufacturers supply price-sensitive Southeast Asian projects. Import dependency for titanium dioxide feedstock shapes regional cost structures.
United States
Commercial building portfolios in Arizona and Nevada drive specification volumes for reflective envelope systems. EPA Energy Star roofing standards establish federal performance baselines that manufacturers must certify against. Dallas-Fort Worth data center clusters absorb premium elastomeric formulations for thermal shock resistance.
Germany
Engineering firm specification relationships anchor demand for high-durability silicone-acrylic hybrids. REACH chemical compliance requirements force solvent system phase-outs that extend R&D timelines for exported product lines. The Rhine-Ruhr industrial corridor concentrates retrofit activity for aging manufacturing facilities.
China
Rapid urban commercial construction in Yangtze River Delta cities creates specification volume for cost-optimized acrylic formulations. Dual carbon goals tighten building envelope efficiency mandates in municipal energy codes. Shenzhen technology campuses pilot ceramic microsphere additive systems for thermal performance validation.
Japan
Earthquake-resistant building standards drive demand for lightweight coating systems over conventional membrane replacements. METI efficiency programs subsidize reflective envelope retrofits in Tokyo commercial districts. Osaka-Kobe manufacturing zones specify integrated waterproofing-reflectance systems for large-span industrial roofs.
United Arab Emirates
Extreme cooling-degree-day intensity creates lifecycle cost advantages for high-reflectance specifications across Dubai commercial portfolios. MOHAP-adjacent building efficiency guidelines influence federal procurement standards for federally funded projects. Abu Dhabi government building retrofits absorb premium compliant imports to maintain specification eligibility.
Cool Roof Coatings Market Key Industry Players
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive silicone supply chains and specialized coating houses with specification-engineering relationships. Three archetypes dominate: diversified materials conglomerates with backward integration into resin production, architectural coatings specialists with distribution network density, and regional waterproofing contractors expanding into formulated products. Competitive moves concentrate on certification pre-qualification for emerging stretch codes and project finance partnerships that securitize retrofit portfolios.
Among diversified materials conglomerates, The Dow Chemical Company and BASF SE exemplify the integrated supply chain archetype, while Sherwin-Williams Company and PPG Industries represent distribution-anchored specialists with architectural coatings network density. Sika AG occupies a position bridging European engineering specification relationships with waterproofing system integration. These three groupings—integrated chemical producers, distribution-heavy coating houses, and specification-driven waterproofing specialists—capture distinct margin pools across project types.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| RPM International Inc. |
| PPG Industries |
| Sika AG |
| Nippon Paint Holdings Co., Ltd. |
| BASF SE |
| Sherwin-Williams Company |
| GAF Materials Corporation |
| AkzoNobel N.V. |
| Others |
Cost & Logistics Intelligence
The Gulf Coast petrochemical corridor from Houston to Baton Rouge concentrates silicone resin and acrylic monomer capacity, anchoring formulation cost structures for elastomeric coating producers serving the American Southwest retrofit segment. Downstream pricing power fragments across project-scale buyers and national distribution networks, compressing margin capture for non-integrated compounders.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across commercial building portfolios, with three-tier pricing stratification across premium silicone-acrylic hybrids, standard waterborne acrylics, and economy-grade bituminous formulations. Price differentiation hinges on Energy Star certification tier and solar reflectance index performance grade, with municipal procurement teams exhibiting lowest price sensitivity due to lifecycle cost modeling requirements. Cost compression in standard acrylic tiers intensifies as Chinese import volumes expand, while premium elastomeric segments sustain pricing resilience through waterproofing integration.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for regional waterproofing contractors bidding securitized retrofit portfolios. Raw material sourcing draws from domestic Gulf Coast petrochemical production, German silicone intermediate imports, and Chinese titanium dioxide pigment supply. Tariff exposure on chloride-process TiO2 imports from China constitutes the primary structural supply risk. Distribution runs through architectural coatings wholesalers and direct manufacturer relationships with large commercial roofing contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cool roof coatings market fragmentation creates niche opportunities as project finance securitization democratizes access to capital-intensive retrofit contracts, enabling specialized applicators to capture share from national roofing conglomerates.
For Market Incumbents: Insulate specification relationships through accelerated certification pre-qualification for Massachusetts and New York stretch codes ahead of federal benchmark adoption. Deepen backward integration into silicone intermediate production to offset titanium dioxide feedstock volatility, while expanding trained installer networks to resolve warranty-program bottlenecks constraining deployment velocity. For New Entrants and Emerging Players: Pursue educational institution procurement channels in Massachusetts and New York where municipal bond financing and stretch code compliance create first-mover advantages for pre-qualified systems. Target maintenance contract segments with performance-guarantee service models that shift energy savings risk from building owners to applicator-manufacturer partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating houses with ceramic microsphere formulation capabilities and established specification-engineering relationships with European engineering firms. Acquisition targets should demonstrate validated substrate compatibility protocols for legacy built-up roofing surfaces. The signal to monitor is REACH-compliant waterborne system adoption rates in federally funded Middle Eastern projects.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification | Massachusetts stretch code compliance secures first-mover specification advantages ahead of federal adoption. |
| Backward Integration into Silicone Intermediates | Gulf Coast resin capacity anchors cost stability for elastomeric hybrid formulations against TiO2 volatility. |
| Installer Network Expansion | Trained applicator certification resolves warranty-program bottlenecks constraining retrofit deployment velocity. |
| Ceramic Microsphere Formulation Investment | Texas data center thermal shock specifications validate next-generation pigment-light reflectance technology. |
| Performance Guarantee Service Models | New York Local Law 97 carbon penalties drive guaranteed-outcome contracting structures for municipal buyers. |
Research Approach
The analysis maps elastomeric, reflective, foam, and bituminous coating sub-sectors, each validated through facility management directors, commercial roofing contractors, formulation chemists, and architectural specification consultants. Primary interview findings triangulate against EPA Energy Star certification databases, California Title 24 compliance filings, ACC industry shipment reports, and customs trade data for titanium dioxide imports. Bottom-up project pipeline analysis and top-down construction spending allocation converge across product type, end user, application technology, and installation lifecycle segmentation dimensions.
Assumptions hold fixed current EPA Energy Star performance baselines and California Title 24 solar reflectance minimums, while varying cooling-degree-day intensity projections and stretch code adoption timelines across the analysis window. Modeled outputs reflect volume and value trajectories by product chemistry tier, building ownership model, and regional regulatory cluster. CAGRs derive from installed base depreciation curves and retrofit penetration elasticity to energy price movements. Key inputs include commercial building stock age distributions and municipal bond issuance patterns for institutional capital improvements.
Sensitivities concentrate around titanium dioxide feedstock price trajectories and REACH-compliant formulation transition costs for European export lines. Forecasts reflect documented assumptions regarding stretch code adoption sequencing and project finance market depth. Macroeconomic contraction, federal preemption of state energy codes, or ceramic microsphere technology cost breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
South Africa Automotive OEM Coatings Market
Coatings
United States Industrial Wood Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
United States Floor Coatings Market
Coatings
South Korea Protective Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Textile Coatings Market
Coatings
Stain Resistant Coatings Market
Coatings
Tablet Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Packaging Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Global Anti-Smudge Coatings Market