
 India Feed Additives Market | 2026-2036
India Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
India Feed Additives Market Foresight
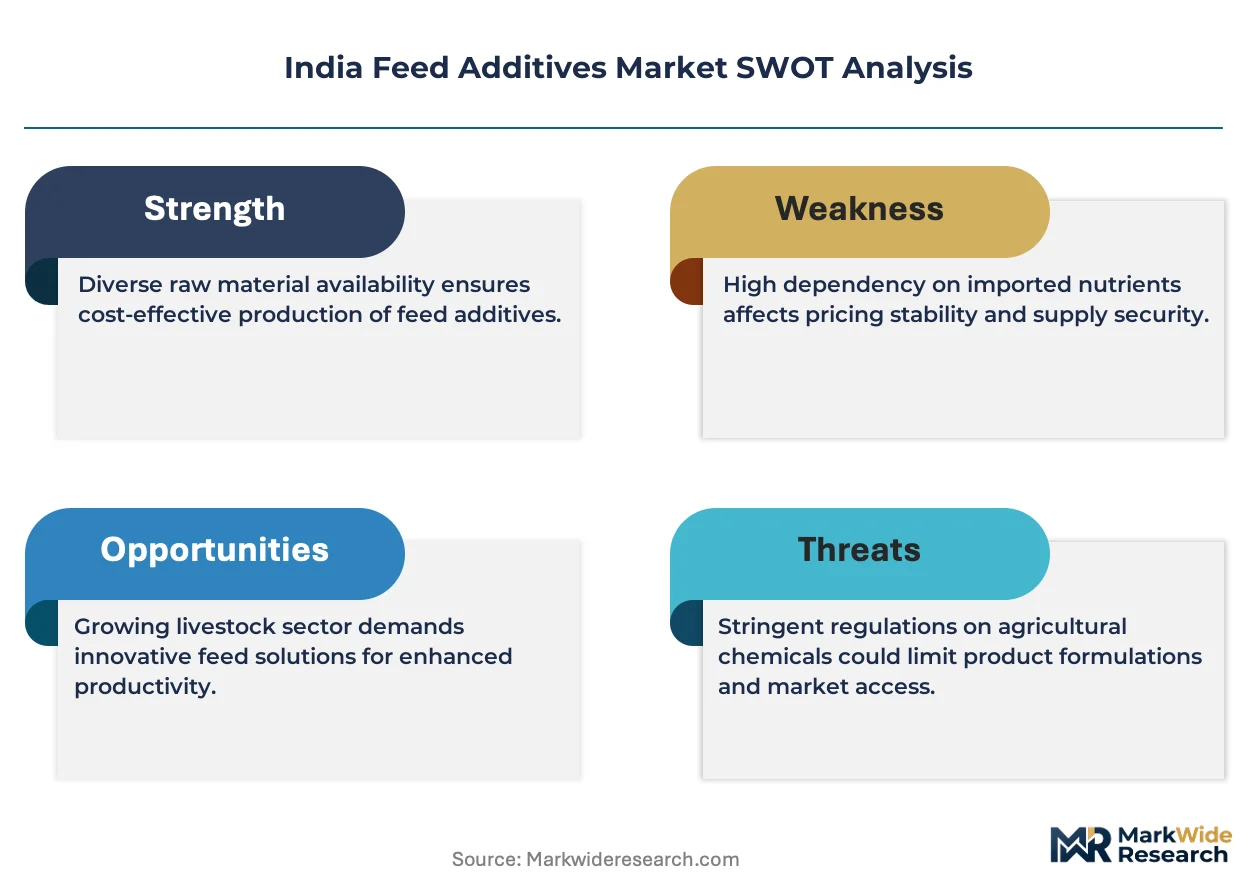
Phytogenic extracts is broadening the ingredient palette for antibiotic-free poultry and swine diets across Indian integrated operations. Cargill Incorporated leverages its captive oilseed processing infrastructure to secure consistent supply of lecithin and specialty lipids for rumen-protected formulations. BASF SE anchors its position through in-house production of synthetic vitamin A and E esters serving northern India's dairy cooperative network. Alltech, Inc. differentiates via yeast cell wall derivatives and solid-state fermentation platforms tailored to tropical heat stress conditions.
Feed additives comprise biologically active substances—including amino acids, enzymes, vitamins, minerals, and acidifiers—incorporated at sub-therapeutic levels to improve feed conversion ratios, nutrient bioavailability, and animal health outcomes. These inputs typically undergo spray-drying, microencapsulation, or granulation to ensure thermostability during pelleting at temperatures exceeding 80°C. Amino acids and enzymes command the deepest margin pools among product types due to precision-nutrition requirements in commercial broiler and aquaculture operations. Poultry dominates end-user consumption volumes, though aquaculture represents the fastest-expanding application as shrimp and freshwater fish intensification spreads across Andhra Pradesh and West Bengal.
The Food Safety and Standards Authority of India enforces contaminant thresholds and labeling mandates that push compound feed mills toward third-party certified premix suppliers. Bureau of Indian Standards specifications for mineral and vitamin premixes create compliance barriers for informal blenders, consolidating procurement relationships with organized manufacturers. The Central Drugs Standard Control Organization monitors veterinary drug residues, indirectly steering feed formulators away from growth-promoting antibiotics toward enzymatic and organic acid alternatives. Stakeholders must track state-level dairy development board procurement tenders and evolving FSSAI notification timelines to anticipate specification shifts before contract cycles reset.
Market Dynamics
FSSAI's antibiotic residue limits are compressing formulation choices across Indian compound feed mills, forcing rapid substitution toward enzymatic and botanical alternatives in poultry and dairy nutrition programs.
Growth Catalysts
- Antibiotic-free mandates:FSSAI's tightened maximum residue limits for veterinary drugs in feed are accelerating demand for phytogenic extracts and probiotic formulations in commercial broiler operations.
- Dairy cooperative expansion:State-led cattle nutrition programs across Gujarat, Punjab, and Haryana are prioritizing mineral and vitamin premix inclusion in ration formulations.
- Heat stress adaptation:Yeast cell wall derivatives and solid-state fermentation platforms are gaining traction as tropical climate conditions intensify productivity losses in layer and broiler houses.
Market Restraints
- Soybean meal price volatility:Domestic oilseed supply fluctuations constrain consistent lecithin and specialty lipid availability for rumen-protected formulations.
- Premix certification barriers:Bureau of Indian Standards specifications for mineral and vitamin premixes exclude informal blenders from organized procurement channels.
- Technical thermostability limits:Enzyme and probiotic viability degrades during pelleting above 80°C, requiring costly microencapsulation or spray-drying investments.
Strategic Opportunities
- Andhra Pradesh aquaculture intensification:Shrimp and freshwater fish farming expansion creates unmet demand for precision amino acid and enzyme supplementation.
- PLI scheme alignment:Production-linked incentive frameworks for animal husbandry inputs could subsidize domestic manufacturing of synthetic vitamin esters.
- Direct-to-farm digital channels:Cooperative procurement platforms and veterinary teleconsultation networks are bypassing traditional distributor tiers in Maharashtra and Telangana.
Industry Challenges
- Formulation chemistry expertise gap:Compound feed mills lack in-house capability to balance acidifier-enzyme interactions in antibiotic-free diets.
- CDSCO residue testing compliance:Veterinary drug monitoring protocols require feed mills to maintain batch traceability systems that strain legacy inventory management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Feed Additives Market |
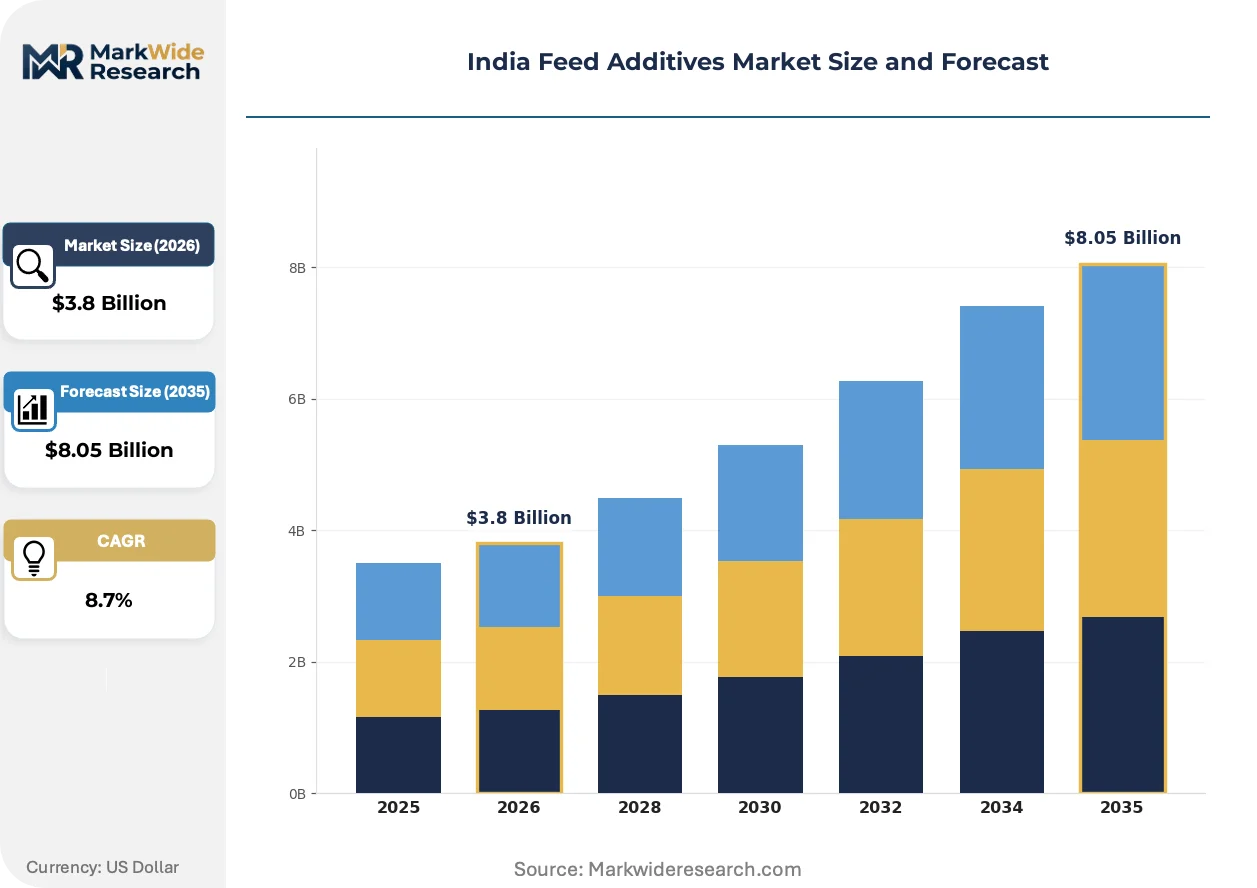
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Enzymes End User: Poultry, Ruminants, Swine, Aquaculture Formulation Type: Liquid, Powder, Granular, Premix Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Archer Daniels Midland Company, Elanco Animal Health Inc., Cargill Incorporated, Alltech, Inc., IFF (Danisco Animal Nutrition), BASF SE, Adisseo, Evonik Industries, DSM Nutritional Products AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Feed Additives Market Shifts & Advancements
Microencapsulation technologies and precision-delivery systems are redefining additive bioavailability standards, while regulatory pressure and buyer consolidation reshape competitive requirements across formulation tiers.
Solid-state fermentation platforms for yeast cell wall derivatives and postbiotic metabolites is consolidating production economics among tropical-adapted suppliers. Commercial poultry integrators in Telangana and Maharashtra are adopting these heat-stable alternatives at contract-cycle pace. The technology is consolidating margin structures around captive fermentation capacity versus imported freeze-dried concentrates.
FSSAI notification timelines for contaminant thresholds and labeling mandates are compressing reformulation lead times for compound feed mills. The regulator's push toward third-party certified premix suppliers is disqualifying informal blenders from organized procurement. Northern India's dairy cooperative network faces the steepest compliance curve as vitamin premix specifications tighten ahead of state tender cycles.
Buyer concentration among integrated poultry operations and cooperative dairy federations is shortening supplier qualification periods and unbundling technical service from product pricing. Maharashtra's broiler integrators now demand outcome-based feed conversion guarantees rather than ingredient specifications alone. This contractual shift is most visible in layer operations across the Mumbai-Pune corridor where volume commitments lock in multi-year enzyme supply agreements.
India Feed Additives Market Segmentation
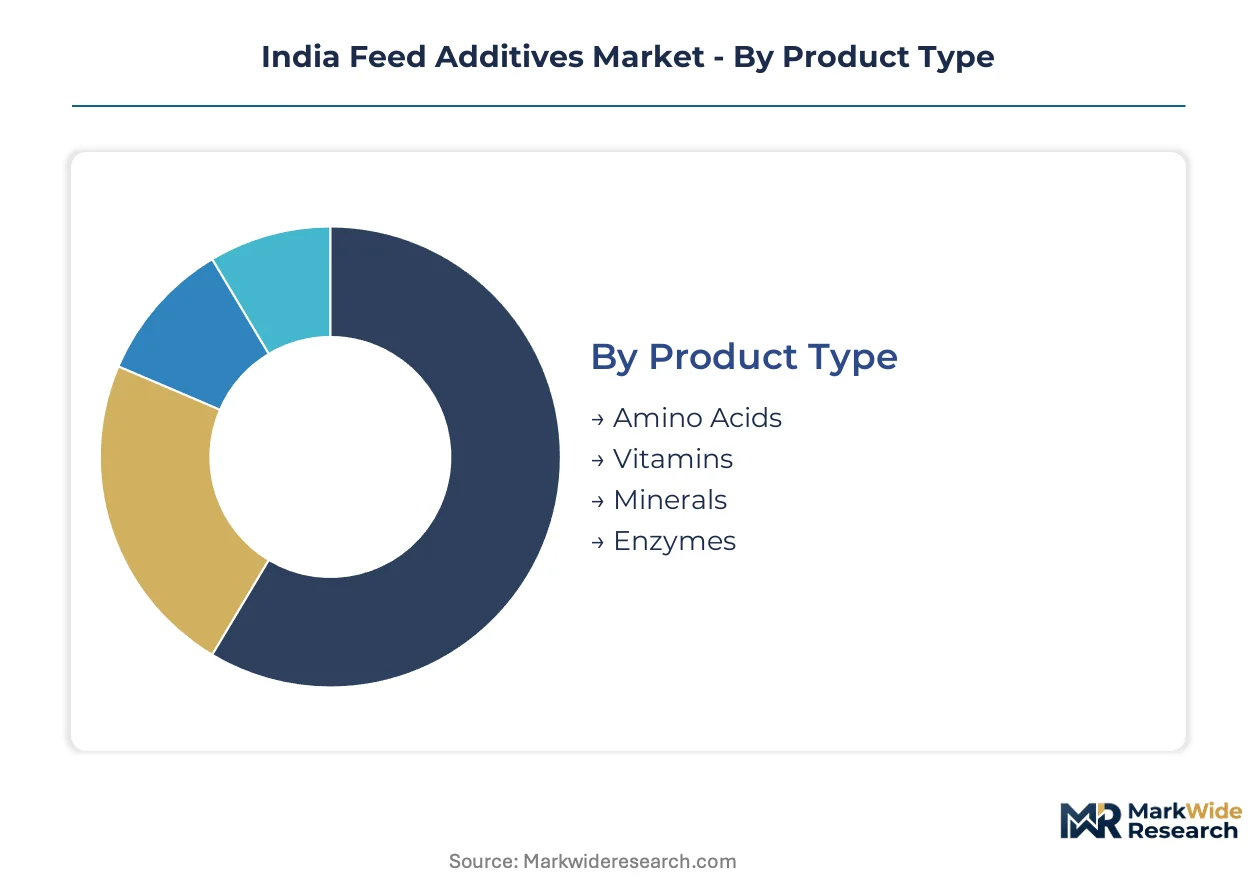
Feed additive procurement patterns in India diverge sharply across livestock systems, with poultry integrators prioritizing thermostable enzymes while dairy cooperatives emphasize mineral premix certification. Understanding these segment-level distinctions reveals where formulation margins concentrate and which compliance barriers reshape supplier relationships.
Product Type:
Cost tier separates precision-nutrition buyers from commodity premix purchasers in this category.
- Amino Acids:Lysine, methionine, and threonine formulations enable precise protein optimization in commercial broiler and aquaculture diets. Maharashtra and Telangana poultry operations drive bulk procurement of crystalline amino acids for least-cost ration formulation.
- Enzymes:Phytase, xylanase, and protease preparations degrade anti-nutritional factors and improve feed conversion ratios. Thermostability during pelleting above 80°C remains the critical specification for Andhra Pradesh shrimp feed mills adopting extruded diets.
- Vitamins:Synthetic A and E esters anchor dairy cooperative premix programs across Gujarat, Punjab, and Haryana.
- Minerals:Chelated trace elements and macro-mineral complexes support reproductive performance in state-led cattle nutrition schemes.
Volume sits with amino acids; growth tilts toward enzymes.
End User:
Application intensity determines additive specification sophistication across livestock species.
- Poultry:Layer and broiler operations in Maharashtra and Telangana deploy enzyme-acidifier combinations to maximize feed conversion in antibiotic-free programs. Contract farming structures enable volume commitments that lock in multi-year supply agreements.
- Aquaculture:Shrimp and freshwater fish intensification across Andhra Pradesh and West Bengal creates demand for precision amino acid supplementation. Extruded feed processing requires heat-stable enzyme formulations absent in legacy carp farming systems.
- Ruminants:Dairy cooperatives in Gujarat, Punjab, and Haryana prioritize rumen-protected lipids and mineral premixes.
- Swine:Northeastern commercial pig operations adopt phytogenic extracts as FSSAI antibiotic limits tighten.
Volume concentrates in poultry; aquaculture climbs the fastest.
Formulation Type:
Customer type dictates physical form preferences, with integrators favoring concentrated inputs and cooperatives accepting premix dilution.
- Powder:Spray-dried vitamin and mineral concentrates serve large compound feed mills with in-house blending capability. Northern India's dairy cooperative network sources powder premixes for ration formulation at federated processing facilities.
- Premix:BIS-certified vitamin-mineral complexes simplify procurement for mid-tier feed mills lacking analytical laboratories. FSSAI labeling mandates push compound feed operations toward third-party certified premix suppliers.
- Liquid:Acidifier and enzyme suspensions enable post-pelleting application in heat-sensitive formulations.
- Granular:Microencapsulated products protect viability during high-temperature pelleting.
Volume rests with powder; premix gains share fastest.
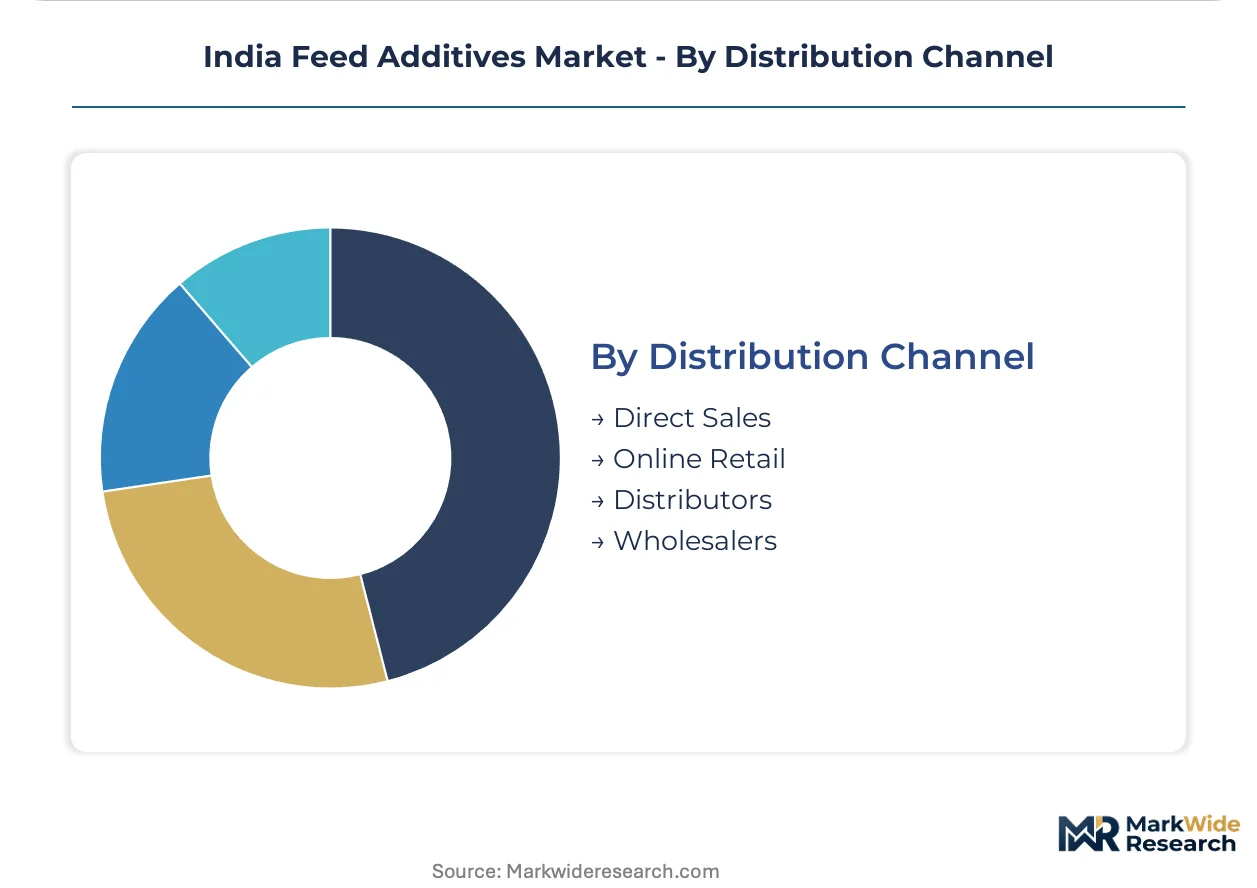
Distribution Channel:
Supply concentration shapes channel selection, with organized procurement bypassing traditional distributor tiers.
- Direct Sales:Integrated poultry operations and dairy federations negotiate volume contracts with manufacturers, unbundling technical service from product pricing. Maharashtra broiler integrators now demand outcome-based feed conversion guarantees rather than ingredient specifications alone.
- Distributors:Regional stocking points serve fragmented layer farms and independent feed mills in secondary markets. Telangana's poultry belt maintains distributor relationships for emergency enzyme replenishment during contract cycle peaks.
- Online Retail:Veterinary teleconsultation networks and cooperative procurement platforms expand in Maharashtra and Telangana.
- Wholesalers:Commodity amino acids and bulk minerals flow through agricultural supply mandis.
Volume flows through direct sales; online retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for feed additives concentrates in India's dairy belt and poultry corridors, with state-level procurement programs and cooperative structures dictating regional specification requirements. FSSAI antibiotic residue limits and BIS premix certification reshape supplier access across sub-markets.
Maharashtra
Commercial broiler and layer integrators in the Mumbai-Pune corridor drive enzyme and amino acid procurement for antibiotic-free programs. State animal husbandry department tenders prioritize FSSAI-compliant premix suppliers for cooperative feed mills. Nashik and Sangli districts host concentrated contract farming operations that lock in multi-year supply agreements.
Gujarat
Dairy cooperatives in Anand and Mehsana anchor national demand for rumen-protected lipids and vitamin A-E premixes. Gujarat State Cooperative Milk Marketing Federation procurement specifications exceed national BIS standards for mineral fortification. The Banaskantha dairy cluster sources chelated trace elements through direct manufacturer contracts.
Andhra Pradesh
Shrimp and freshwater fish intensification across Nellore and Krishna districts creates unmet demand for heat-stable enzymes in extruded aquafeed. State aquaculture mission subsidies accelerate extrusion plant investments that require thermostable phytase formulations. Visakhapatnam feed mills import precision amino acid concentrates for marine protein optimization.
Telangana
Integrated poultry operations around Hyderabad deploy yeast cell wall derivatives for tropical heat stress mitigation. State veterinary university extension programs validate solid-state fermentation platforms for layer productivity trials. Medak and Rangareddy districts concentrate contract grower networks that bypass distributor tiers for direct enzyme procurement.
Punjab and Haryana
Milk shed cooperatives in Ludhiana and Karnal prioritize mineral premix certification for crossbred cattle nutrition programs. Punjab State Dairy Development Board tenders enforce third-party laboratory verification of vitamin stability claims. The Ambala feed manufacturing corridor serves Haryana's state-led cattle nutrition schemes with BIS-certified inputs.
India Feed Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with organized premix suppliers consolidating procurement relationships as FSSAI compliance barriers exclude informal blenders. The market structures around three tiers: global nutrition majors with captive vitamin synthesis, regional compounders with BIS-certified blending capacity, and tropical-adapted fermentation specialists. M&A activity targets certification-accretive premix facilities, while strategic partnerships secure oilseed processing infrastructure for lipid supply security.
Among global nutrition majors, Cargill Incorporated and BASF SE exemplify divergent supply chain anchoring strategies. Cargill leverages captive oilseed processing for lecithin and specialty lipid consistency in rumen-protected formulations. BASF anchors through in-house synthetic vitamin A and E ester production serving northern India's dairy cooperative network. Alltech, Inc. occupies a distinct position with yeast cell wall derivatives and solid-state fermentation platforms engineered for tropical heat stress conditions.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Elanco Animal Health Inc. |
| Cargill Incorporated |
| Alltech, Inc. |
| IFF (Danisco Animal Nutrition) |
| BASF SE |
| Adisseo |
| Evonik Industries |
| DSM Nutritional Products AG |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap compounders across Gujarat and Punjab anchor supply behavior through federated procurement structures, translating cooperative volume concentration into pricing discipline that resists spot-market volatility. Their captive blending capacity insulates dairy nutrition programs from imported premix premiums while compressing margins for informal suppliers lacking Bureau of Indian Standards certification.
Pricing Analysis
Volume concentrates in commodity amino acids where lysine and methionine procurement by Maharashtra poultry integrators operates on contract-based long-term offtake; margins pool in thermostable enzymes where microencapsulation costs justify premium positioning. Price differentiation hinges on FSSAI certification tier and volume scale, with BIS-certified premix suppliers commanding 15-20% premiums over informal blenders. Pricing pressure stems from soybean meal volatility constraining lecithin availability for rumen-protected formulations. Dairy cooperatives exhibit lowest price sensitivity due to subsidized state procurement; independent layer farms in secondary markets show highest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements mandated by Gujarat State Cooperative Milk Marketing Federation and Maharashtra broiler integrators force qualification of at least two BIS-certified premix suppliers per procurement cycle. Geographic supply concentrates in India for oilseed-derived lipids, China for crystalline amino acid intermediates, and Germany for synthetic vitamin ester precursors. Raw material dependencies include soybean meal, corn gluten, and chelated trace element substrates. Supply chain risk centers on single-source vulnerability for thermostable enzyme concentrates. Distribution runs through direct manufacturer contracts with dairy federations and poultry integrators, bypassing traditional distributor tiers in organized procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's feed additives market operates as a supply-constrained environment where captive fermentation capacity for tropical-adapted yeast derivatives props pricing power among qualified suppliers. Thermostability certification bottlenecks exclude informal blenders from organized procurement, consolidating margin pools.
For Market Incumbents: Deploy backward integration into oilseed processing to secure lecithin supply consistency against price volatility. Cargill's captive infrastructure model demonstrates how upstream control over specialty lipids defends margin position against substitute entrants. Incumbents must accelerate BIS certification investments ahead of FSSAI notification timelines to disqualify emerging regional compounders from cooperative tenders. For New Entrants and Emerging Players: Capture Andhra Pradesh aquaculture intensification as the most penetrable segment, where heat-stable enzyme demand outpaces qualified domestic supply. Nellore and Krishna district extrusion plants require phytase formulations absent in legacy supply chains. A go-to-market angle anchored through state aquaculture mission subsidy alignment bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor BIS-certified premix facilities in Punjab and Haryana where dairy cooperative expansion strains legacy blending capacity. Long-term viability hinges on tropical fermentation platform acquisition rather than imported concentrate distribution. Watch FSSAI antibiotic residue limit enforcement timelines as the inflection signal; accelerated notification schedules compress reformulation windows and privilege certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's captive infrastructure secures lecithin supply for rumen-protected formulations against price volatility. |
| BIS Certification Investment | Third-party laboratory verification of vitamin stability claims qualifies suppliers for Gujarat cooperative tenders. |
| Tropical Fermentation Platform Deployment | Alltech's solid-state systems address heat stress productivity losses in Telangana layer operations. |
| Direct-to-Farm Digital Channel Expansion | Cooperative procurement platforms in Maharashtra bypass distributor tiers and unbundle technical service pricing. |
| Aquaculture-Focused Enzyme Development | Heat-stable phytase formulations serve Nellore extrusion plants where legacy carp farming systems fail. |
Research Methodology
Multi-period observation of FSSAI notification timelines, BIS certification issuance rates, and state cooperative procurement tender awards anchored the trend analysis, supplemented by interviews with compound feed mill procurement directors, dairy cooperative nutrition officers, BIS laboratory certification leads, and FSSAI regulatory affairs specialists. Secondary validation drew from FSSAI contaminant threshold notifications, Bureau of Indian Standards premix specifications, state dairy development board tender documents, and Central Drugs Standard Control Organization residue monitoring protocols. Bottom-up volume estimates from individual feed mill capacity utilization triangulated against top-down state-level livestock population projections.
Input-output matrix modeling connected amino acid inclusion rates to broiler feed conversion ratios across Maharashtra and Telangana operations, enzyme thermostability specifications to Andhra Pradesh aquafeed extrusion temperatures, and mineral premix fortification levels to Punjab crossbred cattle milk yield benchmarks. Segmentation dimensions spanned product type, livestock species, formulation physical form, and distribution channel structure. CAGRs derived from logistic growth curve fitting to historical procurement volumes, adjusted for regulatory inflection points. Industry-specific forecast inputs included PLI scheme disbursement schedules for animal husbandry inputs and state aquaculture mission subsidy allocation patterns.
The model holds under stable FSSAI enforcement intensity and continued cooperative procurement centralization; deviation in antibiotic residue limit notification timing or state subsidy disbursement delays would shift volume trajectories materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Inorganic Rheology Modifiers Market
Additives
Global UV Stabilizers Market
Additives
Amino Acids Premixes Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Alkyl Acetates Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Sodium Potassium Tartrate Market
Additives
Global PVC Stabilizer Market
Additives
Global Asphalt Additives Market
Additives
Calcium Stearate Market
Additives
Propyl Gallate Market
Additives
Pectin Market
Additives
Additives for Metalworking Fluids Market
Additives
Marine Fuel Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market