
 Middle East and Africa Super Hydrophobic Coatings Market | 2026-2036
Middle East and Africa Super Hydrophobic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Super Hydrophobic Coatings Market Foresight
South Africa is narrowing its supply gap for advanced nanocoating precursors through partnerships with specialty chemical distributors. P2i Ltd leverages its plasma-based application technology to serve electronics manufacturers in the region. BASF SE anchors industrial coating formulations through its Johannesburg technical center, while UltraTech International Inc. competes in marine protection segments along the Red Sea coastline.
Super hydrophobic coatings are thin-film surface treatments engineered with contact angles exceeding 150 degrees and roll-off angles below 10 degrees, typically incorporating fluoropolymers or silica nanoparticles to achieve water-repellent functionality. These coatings primarily protect substrates from corrosion, ice accumulation, and contaminant adhesion in harsh operational environments. Industrial coatings dominate volume demand from oil and gas infrastructure across the Gulf, while marine coatings represent the fastest-growing category as Red Sea and Mediterranean port expansions accelerate. Spray coating technology leads installation practice due to field applicability, though chemical vapor deposition commands premium positioning in electronics applications.
Saudi Arabia's SFDA and the UAE's MOHAP enforce chemical safety standards that constrain fluorinated compound imports, pushing formulators toward PFAS-free alternatives. South Africa's NRCS alignment with REACH principles adds compliance complexity for European-origin suppliers entering Sub-Saharan markets. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and national certification requirements to optimize product registration strategies.
Market Dynamics
Desert climate durability requirements and fluorinated compound restrictions are forcing simultaneous reformulation and supply chain reconfiguration across Middle East and Africa coating producers.
Growth Catalysts
- Red Sea port expansions:Marine coating procurement from Egyptian and Saudi Arabian terminal operators is accelerating as container throughput capacity doubles.
- SFDA chemical safety standards:Saudi Arabia's tightening import protocols for fluorinated precursors are redirecting procurement toward PFAS-free alternatives with equivalent performance profiles.
- Plasma-based application systems:Electronics manufacturers in South Africa are adopting vapor-phase deposition for smartphone and wearable device protection.
Market Restraints
- Silica nanoparticle supply concentration:Precursor sourcing depends on concentrated Asian supply routes vulnerable to shipping disruptions through Suez Canal corridors.
- REACH-aligned NRCS certification:South Africa's national regulator imposes extended compliance timelines that delay European supplier market entry by 18-24 months.
- Epoxy-polyurethane hybrid substitutes:Lower-cost conventional marine coatings capture budget-constrained procurement in North African fishing and coastal transport fleets.
Strategic Opportunities
- Kenya and Ethiopia infrastructure corridors:Underpenetrated East African construction markets present first-mover positioning for hydrophobic concrete protection as Chinese-funded rail and port projects advance.
- MOHAP fast-track registration:UAE's streamlined chemical approval pathway rewards early PFAS-free formulation submissions with 90-day review cycles versus standard 180-day windows.
- Spray-CVD hybrid systems:Converging field-application and precision-deposition technologies enable on-site electronics protection for oilfield instrumentation.
Industry Challenges
- Nanocoating formulation chemists:Gulf producers face acute talent scarcity for silica-fluoropolymer interface engineering.
- Multi-jurisdiction registration costs:Separate SFDA, MOHAP, and NRCS dossier requirements fragment compliance budgets for regional suppliers.
- Legacy solvent-based infrastructure:Existing spray application equipment requires capital retrofit for waterborne and low-VOC hydrophobic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Super Hydrophobic Coatings Market |
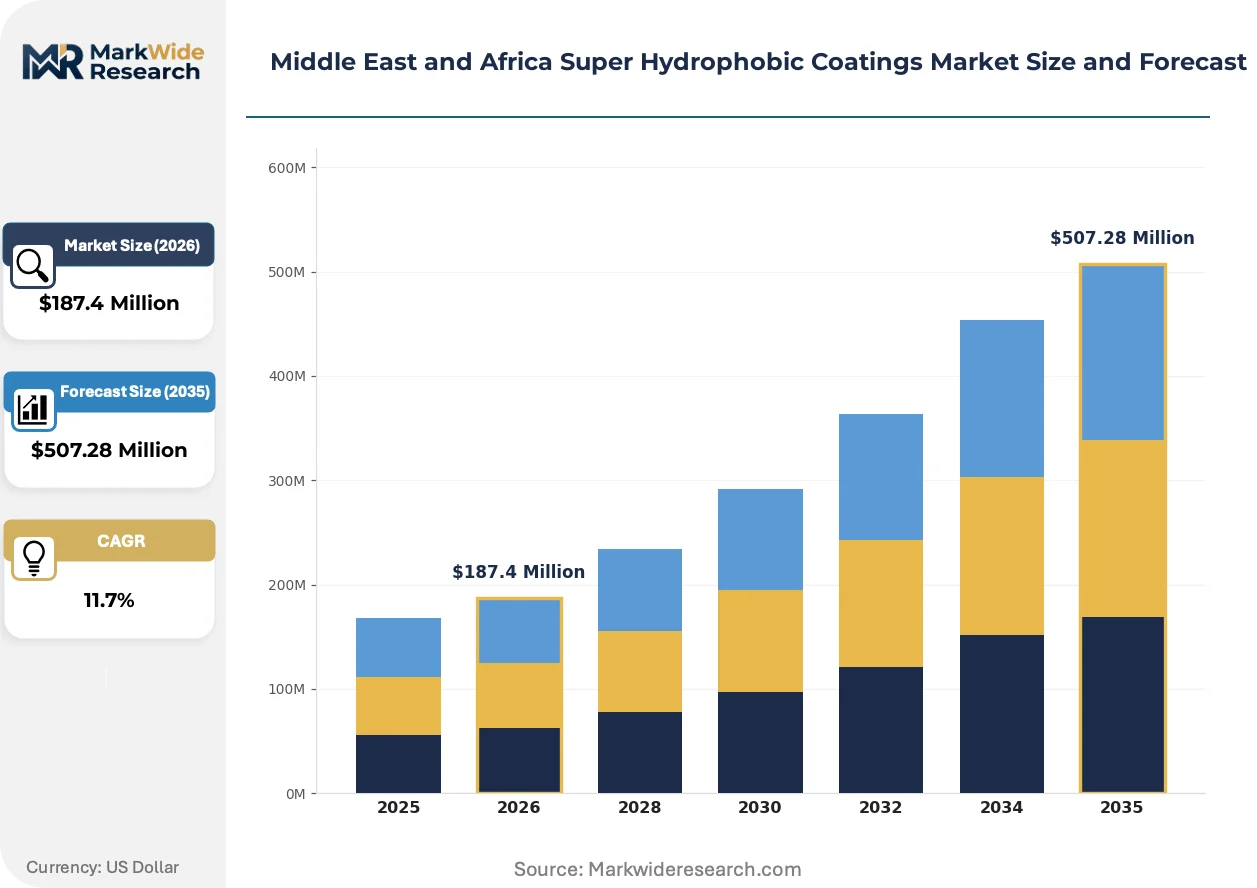
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Coatings, Marine Coatings, Automotive Coatings, Architectural Coatings Application: Textiles, Electronics, Construction, Healthcare Technology: Spray Coating, Dip Coating, Chemical Vapor Deposition, Electrodeposition End User: Manufacturing, Consumer Goods, Automotive, Aerospace |
| Companies Covered | Rust-Oleum (NeverWet), P2i Ltd, UltraTech International Inc., NEI Corporation, Aculon Inc., 3M Company, BASF SE, The Sherwin-Williams Company, PPG Industries Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Super Hydrophobic Coatings Market Shifts & Advancements
Formulation chemistry and application methodology are diverging sharply between Gulf state industrial demand and Sub-Saharan African import-dependent supply chains.
Silica-fluoropolymer hybrid coatings is collapsing the performance gap between premium vapor-deposited films and field-applied spray systems. Oilfield service contractors in Saudi Arabia's Eastern Province are piloting these materials for pipeline exteriors. The technology is collapsing equipment downtime requirements by enabling touch-up application without surface re-preparation.
MOHAP's 2024 technical guidance on per- and polyfluoroalkyl substance labeling is forcing Gulf formulators toward explicit chain-of-custody documentation. Industrial buyers in Dubai's Jebel Ali free zone now require supplier attestation letters for coating constituent disclosure. Marine coating tenders from Abu Dhabi Ports are weighting PFAS-free formulations at 15% above technical score thresholds.
Specification-driven procurement consolidation is compressing supplier qualification cycles across UAE construction conglomerates. Master service agreements with 36-month coating supply commitments are displacing project-by-project tendering for Dubai Expo legacy district developments. Saudi Aramco's contractor pre-qualification system now mandates hydrophobic coating applicator certification for maintenance contract eligibility.
Middle East and Africa Super Hydrophobic Coatings Market Segmentation
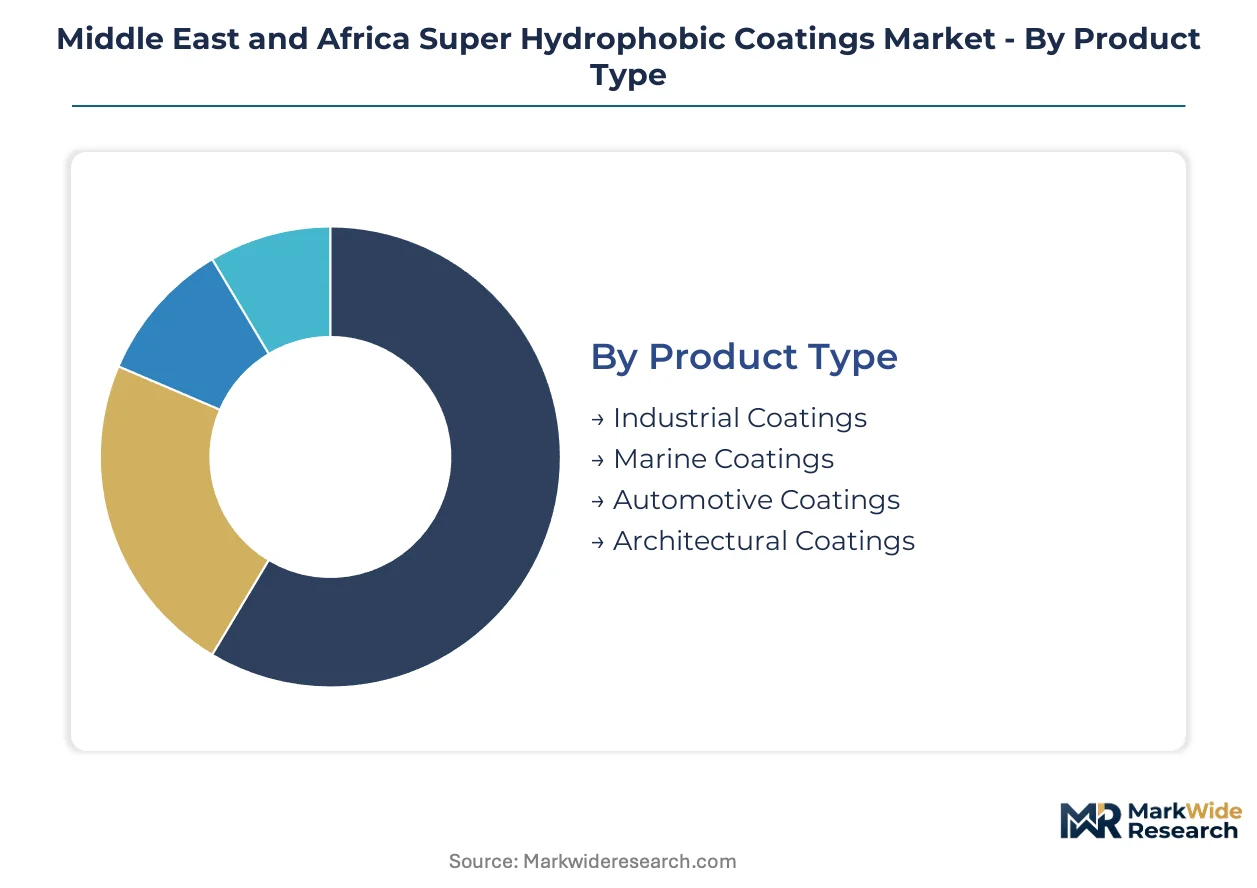
Segmentation in the Middle East and Africa super hydrophobic coatings market reveals distinct procurement patterns across industrial infrastructure, marine terminals, and emerging electronics manufacturing. Each dimension—product type, application, technology, and end user—carries unique regulatory and climate-driven constraints that reshape supplier positioning.
Product Type:
Use-case spectrum spans heavy-asset protection in oilfield environments through consumer-facing surface treatments, with performance specifications diverging sharply between Gulf industrial demand and Sub-Saharan import substitution.
- Industrial Coatings:Silica-fluoropolymer formulations engineered for contact angles exceeding 150 degrees protect pipeline exteriors and processing equipment across Saudi Arabia's Eastern Province oilfields. Procurement concentrates with Aramco contractor pre-qualification systems that mandate applicator certification. Desert thermal cycling and sand abrasion drive reformulation toward enhanced durability binders.
- Marine Coatings:Fouling-resistant hydrophobic layers reduce drag coefficients on hull surfaces and port infrastructure across Red Sea and Mediterranean expansions. Egyptian and Saudi Arabian terminal operators are accelerating procurement as container throughput capacity doubles. Salt spray corrosion resistance specifications exceed 5,000 hours in Abu Dhabi Ports tenders.
- Automotive Coatings:Hydrophobic clear coats and underbody treatments serve premium vehicle assembly in South Africa and aftermarket protection across Gulf luxury vehicle fleets.
- Architectural Coatings:Self-cleaning facade treatments address dust accumulation on Dubai high-rises and Riyadh commercial developments, with waterborne formulations gaining preference for low-VOC compliance.
The dominant share belongs to Industrial Coatings, while Marine Coatings is closing the gap fastest.
Application:
Cost tier stratification separates high-value precision deposition for electronics from field-applied construction treatments, with healthcare emerging as a premium niche.
- Construction:Concrete and steel protection dominates volume across Gulf megaprojects, with hydrophobic treatments specified for Dubai Expo legacy district developments and Riyadh infrastructure corridors. Chinese-funded rail and port projects in East Africa are opening first-mover positioning for concrete protection specifications.
- Electronics:Smartphone and wearable device protection drives plasma-based vapor deposition adoption among South African electronics manufacturers. P2i Ltd's plasma technology serves regional OEMs with nanometer-scale film precision.
- Textiles:Performance apparel and technical fabrics utilize spray-applied fluoropolymer treatments for oilfield workwear and military applications across Gulf defense procurement.
- Healthcare:Antimicrobial hydrophobic surfaces address medical device and facility hygiene requirements, with MOHAP registration pathways creating 90-day fast-track opportunities for PFAS-free formulations.
Construction commands the volume lead, though Electronics is expanding most quickly through manufacturing investment in South Africa.
Technology:
Application methodology determines capital intensity and field feasibility, with hybrid systems emerging to bridge precision and scalability.
- Spray Coating:Airless and electrostatic spray systems dominate field application for oilfield infrastructure and construction projects, enabling touch-up without surface re-preparation. Existing solvent-based spray equipment requires capital retrofit for waterborne formulation compatibility.
- Chemical Vapor Deposition:Vapor-phase deposition commands premium positioning in electronics and precision instrumentation, with Saudi Aramco piloting on-site CVD systems for oilfield instrumentation protection. Equipment portability constraints limit deployment to fixed manufacturing facilities.
- Dip Coating:Batch immersion processes serve textile and small-component treatment, with lower capital barriers suited to Sub-Saharan African import-dependent supply chains.
- Electrodeposition:Electrophoretic application ensures uniform coverage on complex metal geometries for automotive and industrial components, with Johannesburg technical centers supporting regional formulation adaptation.
Spray Coating retains the widest deployment base, yet Chemical Vapor Deposition is gaining share fastest through electronics manufacturing expansion.
End User:
Customer type dictates specification stringency, with manufacturing and aerospace demanding certified performance against consumer goods' price sensitivity.
- Manufacturing:Oil and gas infrastructure, chemical processing, and industrial equipment operators specify coatings for corrosion protection and process efficiency. SFDA chemical safety standards redirect procurement toward PFAS-free alternatives with equivalent performance profiles.
- Automotive:Assembly plants and aftermarket service networks in South Africa and Gulf states drive coating demand for exterior protection and interior surface treatments.
- Consumer Goods:Electronics OEMs and apparel brands prioritize cost-competitive hydrophobic treatments, with specification consolidation compressing supplier qualification cycles across UAE procurement.
- Aerospace:MRO facilities and defense contractors require certified formulations meeting stringent flame resistance and outgassing specifications, with limited regional supply capacity creating import dependence.
Manufacturing holds the dominant position, while Aerospace presents the steepest expansion trajectory through defense procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdullah Port expansion underwrites Saudi Arabia's centrality, while Jebel Ali's container throughput anchors UAE procurement volumes across the Middle East and Africa super hydrophobic coatings market.
Saudi Arabia
Aramco's Eastern Province pipeline networks and NEOM construction corridors drive industrial coating specifications. SFDA chemical safety standards restrict fluorinated precursor imports, pushing formulators toward PFAS-free alternatives. Riyadh's industrial zones host reformulation labs targeting desert thermal cycling durability.
United Arab Emirates
Dubai Expo legacy district developments and Abu Dhabi port expansions concentrate marine and architectural coating demand. MOHAP's fast-track registration pathway rewards early PFAS-free submissions with 90-day review cycles. Jebel Ali free zone buyers now mandate supplier attestation letters for constituent disclosure.
South Africa
Johannesburg electronics manufacturers and Cape Town marine services generate precision coating demand. NRCS alignment with REACH principles extends European supplier compliance timelines by 18-24 months. The Durban-Gauteng industrial corridor anchors BASF SE's regional technical center operations.
Egypt
Suez Canal Economic Zone port expansions and Red Sea terminal upgrades accelerate marine coating procurement. The country's national chemical regulator enforces import documentation standards that favor established regional suppliers. Alexandria's ship repair clusters specify hydrophobic hull treatments for Mediterranean fleet operators.
Kenya
Chinese-funded Lamu Port-South Sudan-Ethiopia Transport corridor projects create first-mover openings for concrete protection specifications. Kenya Bureau of Standards adoption of construction material codes lags Gulf harmonization by several years. Nairobi's emerging industrial zones attract distributor partnerships for nanocoating precursor supply.
Middle East and Africa Super Hydrophobic Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation IP. The vendor base spans multinational chemical conglomerates, regional application-technology providers, and niche nanomaterial suppliers. Three archetypes dominate: fluoropolymer formulators with regulatory compliance capabilities, plasma-deposition technology licensors, and construction-sector distributors with project-specification relationships. Competitive moves concentrate on PFAS-free reformulation races and MOHAP/SFDA pre-registration positioning.
Among specialty application-technology providers, P2i Ltd and UltraTech International Inc. exemplify divergent market positioning. P2i Ltd anchors the electronics protection segment through plasma-based vapor deposition licensing. UltraTech International Inc. occupies marine and industrial field-application terrain. BASF SE represents the integrated chemical conglomerate archetype, leveraging Johannesburg technical infrastructure for regional formulation adaptation.
| Leading Market Players |
|---|
| Rust-Oleum (NeverWet) |
| P2i Ltd |
| UltraTech International Inc. |
| NEI Corporation |
| Aculon Inc. |
| 3M Company |
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in silica nanoparticle precursor manufacturing across the Gulf states drives aggressive spot purchasing from Saudi and UAE formulators, compressing margins while elevating pricing power for Asian suppliers with secured offtake agreements.
Pricing Analysis
Volume-discount tiering separates Aramco-qualified contractors purchasing industrial coatings at scale from project-specific marine coating procurement by Egyptian and Saudi terminal operators. Price differentiation rests on MOHAP registration status and PFAS-free certification grade, with fast-track approved formulations commanding substantial premia over standard-review alternatives. Pricing pressure stems from epoxy-polyurethane hybrid substitutes capturing budget-constrained North African fleet procurement. Construction conglomerates in Dubai's Jebel Ali free zone exhibit lowest price sensitivity due to master service agreement structures, while Kenyan infrastructure contractors face acute cost compression from Chinese EPC pricing norms.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement contracts for South African electronics manufacturers, reflecting distributor financing strain amid NRCS compliance delays. Silica nanoparticle supply concentrates in China, South Korea, and Japan, with fluoropolymer resins sourcing from Germany and the United States. Raw material dependencies include fumed silica, fluorinated acrylates, and plasma deposition precursors. Single-source vulnerability through Suez Canal corridors elevates disruption risk for Gulf formulators. Distribution runs through Johannesburg technical centers for Sub-Saharan markets and Jebel Ali free zone distributors for Gulf state project procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specification-driven procurement consolidation across UAE construction conglomerates, compressing supplier qualification cycles and mandating 36-month coating supply commitments for master service agreement eligibility.
For Market Incumbents: Build regulatory compliance moats through early PFAS-free formulation pre-registration with SFDA and MOHAP ahead of competitor submissions. Anchor positioning via backward integration into silica nanoparticle precursor supply through partnerships with Asian suppliers securing dedicated capacity. Defend against epoxy-polyurethane hybrid substitution by demonstrating total cost of ownership advantages in desert thermal cycling applications. Prioritize applicator certification programs within Saudi Aramco's contractor pre-qualification system to lock out unqualified competitors. For New Entrants and Emerging Players: East African infrastructure corridors present first-mover positioning for hydrophobic concrete protection specifications as Chinese-funded Lamu Port-South Sudan-Ethiopia Transport projects advance. Kenya's lagging construction material codes relative to Gulf harmonization create regulatory arbitrage opportunities for PFAS-free formulations. Target electronics manufacturing in South Africa through plasma-based application technology licensing rather than capital-intensive formulation production. Secure distributor partnerships in Nairobi's emerging industrial zones to establish nanocoating precursor supply relationships ahead of competitor entry. For Investors and Strategic Acquirers: Capital is best deployed toward specialty application-technology providers with plasma-deposition IP and established MOHAP registration dossiers rather than commodity formulation assets. Long-term viability across the analysis window favors platform integrators consolidating fragmented Gulf state applicator networks. Acquisition targets should demonstrate proven desert climate durability testing and SFDA pre-registration positioning. Watch for inflection signals in Abu Dhabi Ports tender weighting shifts toward PFAS-free technical score thresholds exceeding current 15% premia.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Pre-Registration | MOHAP fast-track approval compresses competitor entry timelines to 90-day windows versus standard 180-day reviews. |
| Applicator Certification Program | Saudi Aramco contractor pre-qualification mandates create exclusive maintenance contract eligibility for certified suppliers. |
| Silica Nanoparticle Supply Partnership | Secured precursor offtake from Asian manufacturers insulates Gulf formulators against Suez Canal disruption risk. |
| Plasma Deposition Technology Licensing | Electronics manufacturing expansion in Johannesburg favors vapor-phase deposition providers over spray-application competitors. |
| East African Distributor Acquisition | Nairobi industrial zone positioning captures first-mover advantage in Chinese-funded infrastructure corridor specifications. |
Research Methodology
A standing panel of coating formulators, oilfield procurement managers, marine terminal operators, and electronics manufacturing engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from SFDA and MOHAP regulatory filings, customs and trade data for fluorinated precursor imports, SEC disclosures from multinational chemical conglomerates, and construction tender databases for UAE megaprojects. Bottom-up demand modeling triangulated against top-down market sizing from industrial coating volume estimates and electronics manufacturing capacity announcements.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated adoption pathways for PFAS-free formulation penetration. Segmentation dimensions spanned product type, application methodology, end-use industry, and regional regulatory cluster. CAGRs derived from weighted average of segment-specific growth trajectories calibrated to infrastructure investment pipelines and manufacturing FDI announcements. Industry-specific inputs included Aramco maintenance contract award schedules and Red Sea port expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed coating producers or accelerated EU PFAS bans would shift outcomes. Macroeconomic deviation in Gulf state infrastructure spending, regulatory divergence between SFDA and MOHAP chemical safety standards, or breakthroughs in bio-based hydrophobic chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Canada Floor Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Electron Beam Curable Coating Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Graphene Coatings Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Topcoat Market
Coatings
Glazes Market
Coatings
France Protective Coatings Market
Coatings
OEM Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Hydrophilic Coatings Market