
 South Africa Protective Coatings Market | 2026-2036
South Africa Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Protective Coatings Market Insights
Market Overview
South African chemical manufacturing is consolidating around fewer large-scale formulation sites serving the subcontinent. Akzo Nobel N.V. leverages its global R&D network to sustain technical service capabilities across Johannesburg and Cape Town. PPG Industries, Inc. anchors its regional position through specialized marine and industrial distribution partnerships. Jotun A/S competes aggressively in the oil and gas segment with high-performance epoxy systems engineered for offshore platforms.
Segmentation Analysis
Protective coatings are engineered film-forming systems comprising resins, pigments, solvents, and functional additives that cure to create barrier layers against corrosion, chemical attack, and environmental degradation on metal, concrete, and composite substrates. Epoxy formulations dominate heavy industrial maintenance due to their superior adhesion and chemical resistance in South Africa's mining and petrochemical infrastructure. Powder coatings are gaining share in automotive and manufacturing applications where zero-VOC compliance and durable factory-applied finishes reduce environmental remediation costs.
Regulatory Environment
South Africa's Department of Employment and Labour enforces Hazardous Chemical Substances regulations that mandate VOC thresholds and worker exposure limits in coating application environments. The South African Bureau of Standards (SIS) maintains SANS codes for corrosion protection in structural steel, while ISO 12944 provides the international benchmark for protective paint systems in atmospheric and immersion service categories. Stakeholders must monitor alignment between evolving carbon pricing mechanisms and coating lifecycle assessments to preserve competitive positioning in public infrastructure tenders.
Market Dynamics
South Africa's revised Hazardous Chemical Substances regulations are compressing formulation timelines while mining maintenance schedules pull demand toward high-performance epoxies. This regulatory tightening intersects with concentrated supply from Durban and Johannesburg production clusters.
Growth Catalysts
- Mining sector maintenance cycles:Expanded procurement from Durban-based applicators is driving volume for heavy-duty corrosion protection in extraction infrastructure.
- VOC compliance mandates:South Africa's Department of Employment and Labour enforcement is accelerating reformulation toward low-solvent epoxy and polyurethane systems.
- Port infrastructure renewal:Western Cape marine coating demand is concentrating around Cape Town harbor expansion and shipyard maintenance contracts.
Market Restraints
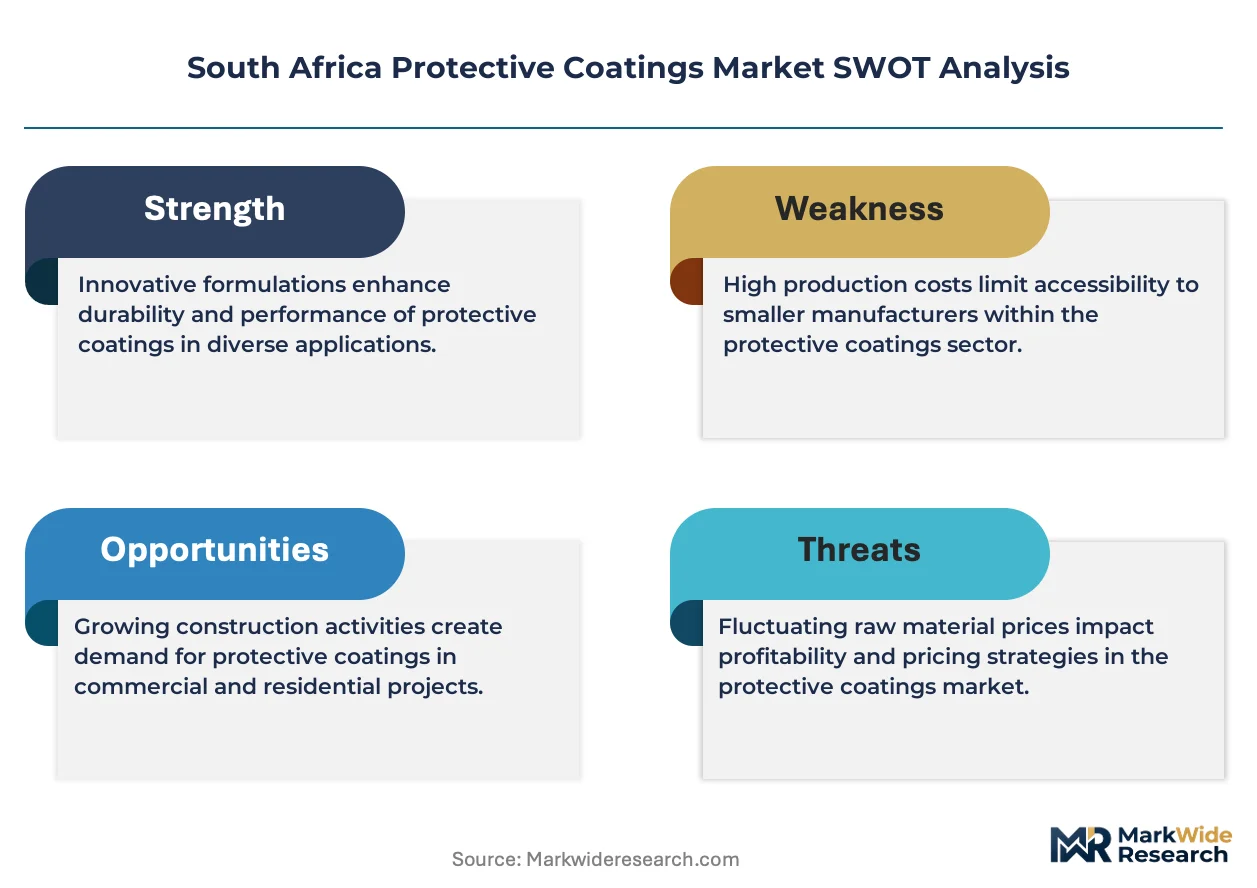
- Import dependency for specialty resins:Bisphenol-A and isocyanate feedstock concentration in Asian supply chains exposes formulators to currency volatility and shipping disruptions.
- Skilled applicator shortages:Certified coating inspector scarcity in Gauteng and KwaZulu-Natal extends project timelines and raises warranty risk.
- Substitution by thermal spray metallization:Offshore platform operators in Mossel Bay are piloting arc-sprayed aluminum as an alternative to conventional three-coat epoxy systems.
Strategic Opportunities
- Eastern Cape industrial corridor:Coega Special Economic Zone manufacturing investments are creating greenfield demand for factory-applied powder coatings on automotive components.
- Water treatment infrastructure:Municipal wastewater plant upgrades across Free State and Northern Cape are specifying NSF-certified epoxy linings for concrete tanks.
- Carbon border adjustment alignment:South African Bureau of Standards lifecycle assessment protocols are enabling coating exporters to preserve EU market access under evolving carbon pricing mechanisms.
Industry Challenges
- ISO 12944 certification bottlenecks:Third-party corrosion protection system validation delays are extending tender qualification timelines for infrastructure projects.
- Legacy solvent-based inventory stranding:Formulators face write-downs on non-compliant stock as VOC thresholds tighten, compressing working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Protective Coatings Market |
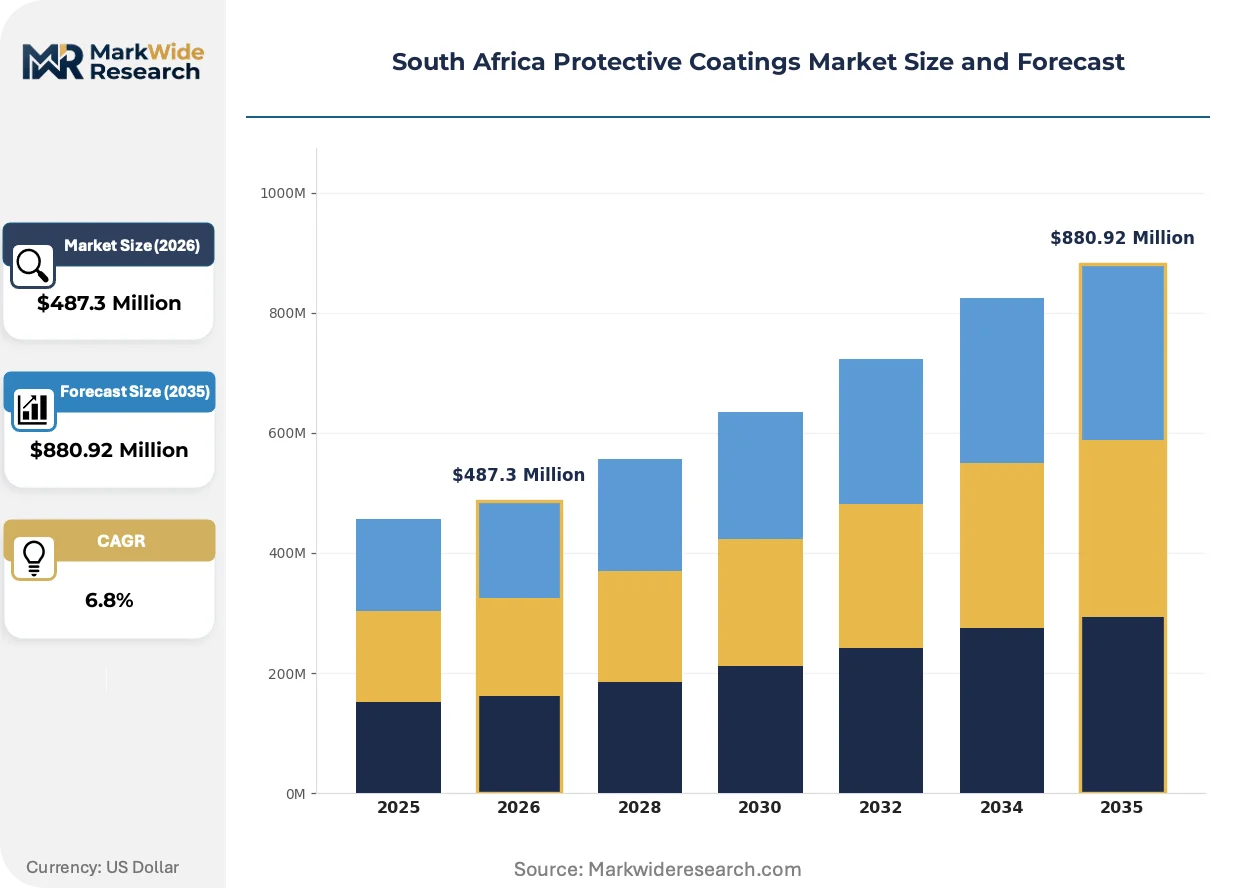
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyester Application: Industrial Equipment, Marine, Aerospace, Automotive End User: Construction, Oil & Gas, Manufacturing, Transportation Form: Liquid, Powder, Paste, Spray |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun A/S, Nippon Paint Holdings Co., Ltd., BASF SE, Axalta Coating Systems, Dekro Paints, Duram Smart Paints, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Protective Coatings Market Trends and Innovations
Formulation chemistry and application methodology are evolving in response to environmental compliance pressures and asset-owner lifecycle cost requirements. Three developments are restructuring competitive positioning in South African protective coatings.
High-solids epoxy technology is converging with ambient-cure polyurethane topcoats to deliver extended maintenance intervals for mining infrastructure in Mpumalanga's coal belt. Anglo American Platinum and Sibanye-Stillwater maintenance teams are specifying these hybrid systems for conveyor structures and processing vessels. This convergence is compressing demand for traditional alkyd-based maintenance paints in heavy industrial applications.
South Africa's Department of Employment and Labour is enforcing Hazardous Chemical Substances exposure limits that mandate respiratory protection and ventilation upgrades in coating application environments. Industrial facilities in Johannesburg's manufacturing corridor are retrofitting spray booths to meet these worker safety requirements. Marine and offshore segments are responding fastest, integrating compliant application protocols into existing ISO 12944 quality management systems.
Asset owners in the petrochemical and power generation sectors are unbundling coating specification from general construction contracts, creating direct procurement relationships with certified applicators. This disintermediation is displacing general contractor markup structures in Sasolburg and Secunda industrial complexes. The shift is most visible in scheduled turnaround maintenance, where owner-operators now retain independent coating inspectors and warranty providers.
South Africa Protective Coatings Market Segmentation
Protective coating selection in South Africa tracks directly to asset lifecycle stages and regulatory compliance windows. Mining operators and port authorities specify formulations based on corrosion severity, VOC exposure limits, and maintenance interval targets rather than upfront cost alone.
Product Type:
Upgrade cycles in Mpumalanga's coal belt and Western Cape marine terminals are driving specification shifts toward longer-lasting film-forming systems with reduced solvent content.
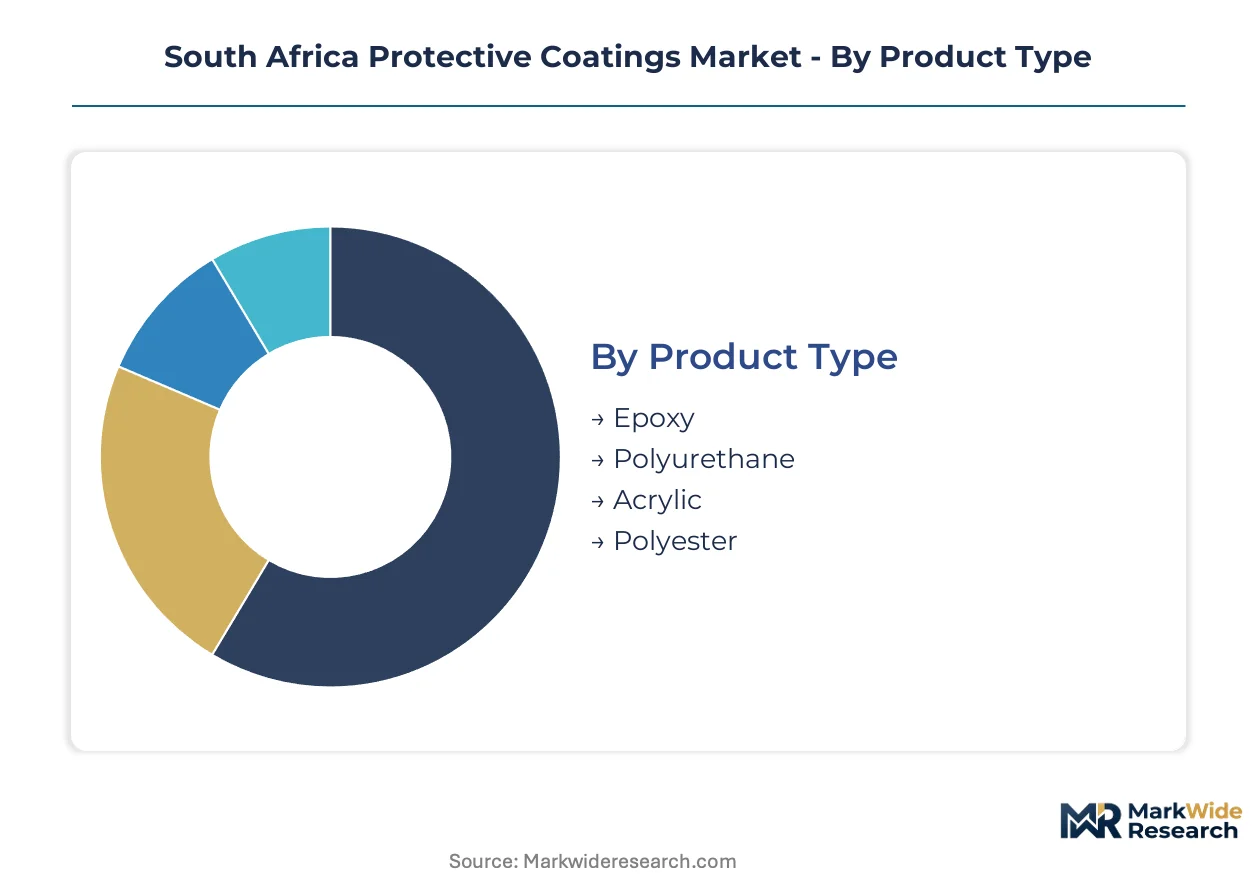
- Epoxy:Two-component thermosetting systems built from bisphenol-A resins and polyamine hardeners deliver superior adhesion to blasted steel and concrete. Demand concentrates in Sasolburg petrochemical complexes and Rustenburg platinum concentrators where chemical resistance and immersion service life justify premium formulation costs.
- Polyurethane:Aliphatic and aromatic isocyanate-cured topcoats provide UV stability and color retention for exterior architectural and marine applications. Durban shipyards and Cape Town harbor infrastructure projects are specifying these for weathering resistance in coastal atmospheric zones.
- Acrylic:Water-borne and solvent-borne thermoplastic resins serve decorative and light industrial protection in Gauteng manufacturing facilities.
- Polyester:Unsaturated resin systems dominate powder coating formulations for automotive and appliance factory lines in the Eastern Cape.
Epoxy sits at the top of the volume ranking, with polyurethane climbing the fastest as marine maintenance schedules accelerate.
Application:
Application-specific demand correlates to South Africa's industrial geography and export infrastructure positioning.
- Industrial Equipment:Heavy machinery, processing vessels, and conveyor systems in mining and metals extraction require high-build epoxy systems with abrasion resistance. Anglo American Platinum and Sibanye-Stillwater maintenance teams specify these for scheduled turnaround intervals in Rustenburg and Marikana.
- Marine:Immersion-grade epoxy and antifouling coatings protect hulls, ballast tanks, and offshore platforms. Cape Town harbor expansion and Mossel Bay gas platform maintenance are pulling volume toward certified applicators with ISO 12944 compliance.
- Aerospace:Chromate-free primers and polyurethane topcoats serve commercial aviation MRO facilities in Johannesburg and Cape Town.
- Automotive:Electrocoat primers and clearcoats support OEM assembly and refinish operations in Rosslyn and Uitenhage manufacturing zones.
Industrial equipment commands the largest application share, while marine coatings are expanding most quickly on port renewal investment.
End User:
End-user procurement patterns reflect capital expenditure cycles and regulatory inspection regimes across South Africa's core industrial sectors.
- Construction:Structural steel fireproofing and corrosion protection for commercial and infrastructure projects. Gauteng's manufacturing corridor and Durban port back-of-port developments are specifying SANS-compliant zinc-rich primers and intumescent systems.
- Oil & Gas:Pipeline coatings, tank linings, and offshore platform protection. Secunda synthetic fuels complexes and Mossel Bay offshore operations demand high-performance epoxies with NORSOK and ISO 12944 certification.
- Manufacturing:Factory-applied powder coatings and liquid systems for metal fabrication and assembly operations.
- Transportation:Rail rolling stock, shipbuilding, and vehicle refinish coatings serving Transnet and private logistics operators.
Construction leads end-user demand by volume, with oil and gas posting the steepest expansion trajectory on upstream maintenance deferrals.
Form:
Form selection in South African protective coatings follows application methodology constraints and VOC compliance enforcement intensity.
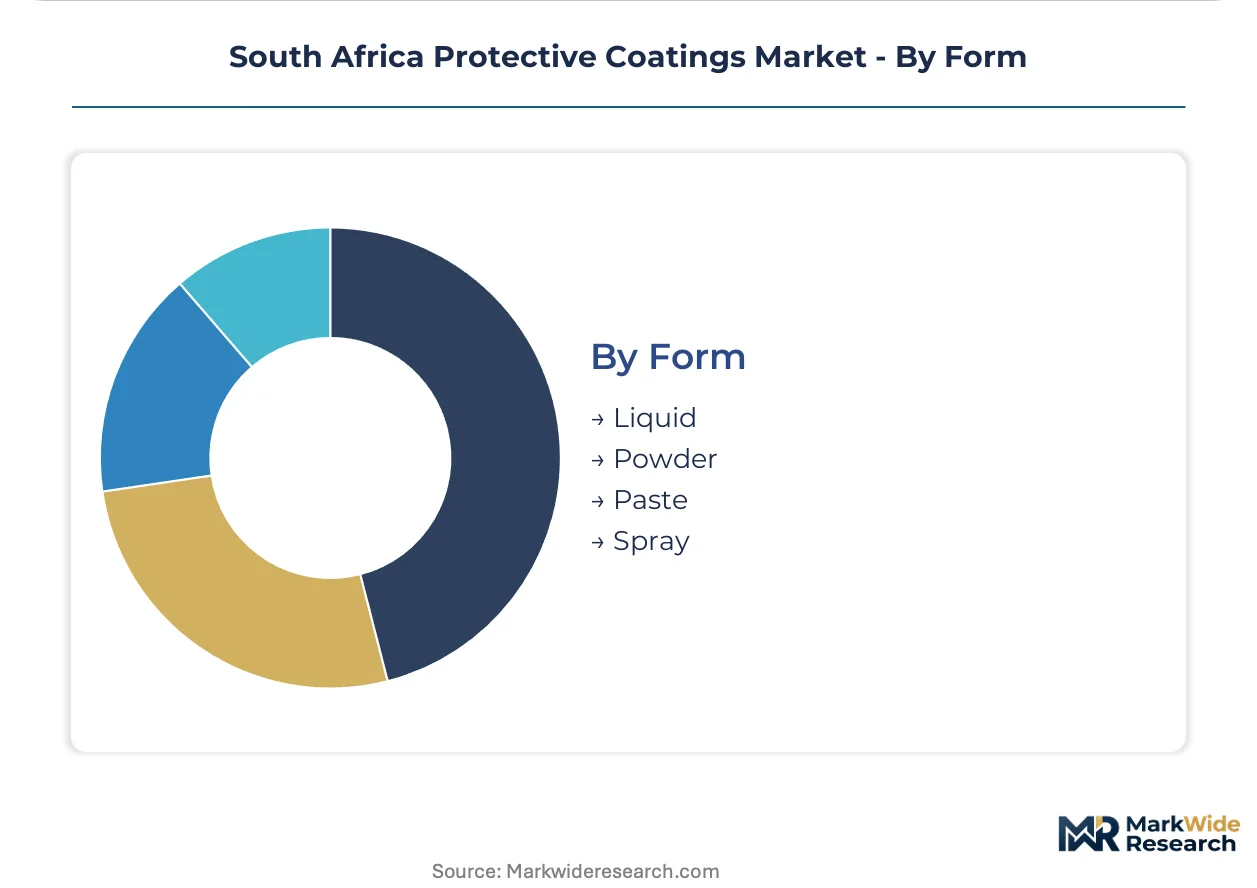
- Liquid:Solvent-borne and water-borne formulations applied by brush, roller, or conventional spray dominate field maintenance. Johannesburg industrial facilities continue specifying these for touch-up and repair work despite Department of Employment and Labour ventilation requirements.
- Powder:Thermosetting epoxy, polyester, and hybrid powders applied electrostatically and oven-cured deliver zero-VOC compliance. Coega Special Economic Zone automotive investments are driving new powder line installations for component finishing.
- Paste:High-build trowel-applied compounds for concrete repair and tank lining applications.
- Spray:Plural-component airless spray systems for high-volume industrial and marine projects requiring rapid film build.
Liquid coatings retain dominant volume position, with powder systems gaining share fastest on factory-applied automotive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as formulators migrate toward jurisdictions with narrower compliance cost differentials. South Africa's Department of Employment and Labour enforcement creates localized pressure, while neighboring territories with looser VOC thresholds attract blending operations for export backhaul.
Gauteng
Johannesburg's manufacturing corridor concentrates powder coating demand from automotive component plants in Rosslyn and metal fabrication clusters in Germiston. The Department of Employment and Labour inspects spray booth ventilation systems quarterly, accelerating capital expenditure on emission controls. Sasolburg petrochemical complexes anchor heavy-duty epoxy procurement for processing vessel maintenance.
Western Cape
Cape Town harbor expansion and Mossel Bay offshore platform maintenance are pulling marine coating volume toward certified applicators with ISO 12944 compliance. The South African Bureau of Standards enforces SANS corrosion protection codes for structural steel in port infrastructure. Bellville industrial zones host distribution nodes serving shipyard contractors with high-solids polyurethane systems.
KwaZulu-Natal
Durban-based applicators supply mining maintenance schedules across Mpumalanga's coal belt and platinum concentrators in Rustenburg. Hazardous Chemical Substances regulations mandate respiratory protection upgrades in spray application environments. Pinetown formulation plants serve as the primary import gateway for bisphenol-A resins arriving through Durban Container Terminal.
Eastern Cape
Coega Special Economic Zone manufacturing investments are creating greenfield demand for factory-applied powder coatings on automotive components. Provincial economic development incentives support electrocoat primer line installations for export-oriented component suppliers. Port Elizabeth automotive assembly zones drive specification alignment with EU carbon border adjustment protocols.
Free State and Northern Cape
Municipal wastewater plant upgrades are specifying NSF-certified epoxy linings for concrete tanks in Bloemfontein and Kimberley. The Department of Water and Sanitation procurement guidelines favor coating systems with documented lifecycle assessments. Kuruman manganese mining infrastructure extends maintenance intervals through high-build epoxy specifications for slurry handling equipment.
South Africa Protective Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized industrial niches with certified application capabilities. The market structures around three archetypes: global formulation houses with regional technical service networks, domestic blenders serving cost-sensitive maintenance segments, and certified applicator-coordinators who bundle specification compliance with installation warranty. Competitive moves concentrate on strategic partnerships with asset owners for direct procurement relationships and portfolio diversification into water-borne and high-solids formulations.
Among global formulation houses, Akzo Nobel N.V., PPG Industries, Inc., and Jotun A/S exemplify distinct positioning archetypes. Akzo Nobel N.V. represents the integrated technical service model with Johannesburg and Cape Town capabilities. PPG Industries, Inc. occupies a position emphasizing marine and industrial distribution partnerships. Jotun A/S anchors the high-performance epoxy specialization for offshore and petrochemical immersion service. These three names from the raw data illustrate how multinational presence stratifies against domestic specialists like Dekro Paints and Duram Smart Paints.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun A/S |
| Nippon Paint Holdings Co., Ltd. |
| BASF SE |
| Axalta Coating Systems |
| Dekro Paints |
| Duram Smart Paints |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ISO 12944-compliant systems and uncertified maintenance coatings manifests in divergent margin structures and procurement channel configurations across South Africa's industrial corridors. Premium formulations command direct applicator relationships with asset owners, while commodity-grade products flow through distributor networks serving cost-sensitive maintenance contractors in Gauteng and KwaZulu-Natal.
Pricing Analysis
Distributor margin layers absorb 15-25 percent of landed cost for small-batch field maintenance purchases, while direct-to-OEM channels offer volume-scaled discounts for powder coating lines in the Eastern Cape. Price differentiation hinges on SANS corrosion protection certification tier and after-sales warranty bundling. Cost compression in solvent-borne alkyd segments is intensifying because legacy inventory stranding accelerates discounting. General contractor procurement teams exhibit highest price sensitivity; petrochemical asset owners prioritize lifecycle cost over unit price.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Coega automotive plants, while project-based applicators serve marine maintenance in the Western Cape. Raw material sourcing draws from China, South Korea, and Germany for bisphenol-A resins, isocyanate hardeners, and specialty pigments. Single-source vulnerability concentrates in Asian epoxy resin feedstock, exposing formulators to shipping disruption and currency fluctuation. Distribution runs through Durban Container Terminal import gateways and Johannesburg blending facilities serving subcontinental markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's protective coatings market represents a late-cycle quality story as mining operators and port authorities shift procurement toward extended-warranty, certified systems with documented lifecycle assessments.
For Market Incumbents: Anticipate thermal spray metallization substitution in Mossel Bay offshore platforms by accelerating high-solids epoxy R&D partnerships with Anglo American Platinum and Sibanye-Stillwater. Deepen backward integration into specialty resin sourcing through long-term offtake agreements with Asian suppliers. Certification investment in ISO 12944 Category C5-M systems anchors defensive positioning against emerging applicator-coordinators. For New Entrants and Emerging Players: Begin with NSF-certified epoxy linings for Free State and Northern Cape municipal wastewater infrastructure, where specification barriers remain lower than marine or petrochemical segments. Water treatment plant upgrades offer the most penetrable vertical, with procurement governed by Department of Water and Sanitation lifecycle assessment guidelines rather than NORSOK or ISO 12944 stringency. A go-to-market angle bundling coating supply with certified inspection services bypasses established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where certified applicator networks face working capital strain from VOC compliance retrofit costs and legacy inventory write-downs. Long-term viability favors formulators with captive technical service capabilities and direct asset owner relationships spanning the analysis window. Acquisition targets include Durban-based applicators with ISO 12944 inspection credentials and established mining maintenance contracts. The signal to watch is Department of Employment and Labour enforcement intensity accelerating smaller player exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive supply of bisphenol-A feedstock reduces exposure to Asian shipping disruptions and currency volatility. |
| ISO 12944 Certification Investment | Third-party validation unlocks tender qualification for Transnet port infrastructure and Sasolburg petrochemical maintenance. |
| Direct Procurement Relationship Development | Disintermediation of general contractors in Secunda turnaround maintenance preserves margin and warranty control. |
| High-Solids Formulation Transition | VOC compliance alignment with Department of Employment and Labour regulations prevents inventory stranding penalties. |
| Certified Applicator Network Acquisition | Technical service bundling with coating supply creates defensive moats against commodity price competition. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Johannesburg powder coating facilities, procurement leads at Durban-based mining applicators, distribution channel partners serving the Western Cape marine segment, and technical R&D directors at multinational formulation houses. Secondary validation drew from South African Bureau of Standards SANS code publications, Department of Employment and Labour enforcement records, customs and trade data through Durban Container Terminal, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up volume estimates from end-user maintenance schedules triangulated against top-down production capacity assessments across Gauteng, KwaZulu-Natal, and Western Cape formulation clusters.
Historical reference periods anchored volume and value projections across the modeling period, with growth trajectories derived from segment-level demand elasticity and regulatory compliance cost pass-through assumptions. Segmentation dimensions included resin chemistry tier, end-use industry vertical, application methodology, and regional production hub concentration. Forecast inputs incorporated mining maintenance cycle timing, port infrastructure capital expenditure pipelines, and automotive OEM capacity additions in the Eastern Cape.
Several conditions sit outside the modeled scope, including unforeseen shifts in carbon border adjustment mechanisms affecting EU export competitiveness, abrupt changes in Department of Employment and Labour enforcement intensity, and substitution acceleration by thermal spray metallization technologies. Forecasts reflect assumptions about regulatory continuity and raw material supply chain stability that warrant periodic reassessment. Periodic stress-testing of base assumptions against mining sector capital expenditure deferrals and currency fluctuation scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
South America Thermal Spray Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Water Based Enamel Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Hydrophilic Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
North America Coil Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Cladding Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Global Plastic Coatings Market