
 Composite Coatings Market | 2026-2036
Composite Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Coatings Market Analysis
Germany's industrial capacity build-out is tilting toward advanced ceramic and hybrid coating production for automotive and aerospace supply chains. PPG Industries leverages its European manufacturing network to sustain R&D intensity in thermal barrier coatings for turbine applications. Akzo Nobel N.V. anchors its position through waterborne polymeric formulations that meet tightening environmental standards. The Sherwin-Williams Company competes by extending its distributor channel control across Continental Europe's industrial equipment segment.
Composite coatings are engineered surface treatments combining polymeric, ceramic, metal, or hybrid matrices deposited via thermal spray, electroplating, chemical vapor deposition, or liquid coating processes, typically formulated to achieve thicknesses between 50 microns and 5 millimeters depending on substrate protection requirements. These coatings primarily protect structural components from corrosion, wear, thermal degradation, and chemical attack in demanding operational environments. Polymeric coatings dominate volume through broad applicability in industrial equipment and marine hull protection, while ceramic coatings command premium positioning in aerospace turbine blades where thermal resistance thresholds exceed 1,000 degrees Celsius. Hybrid coatings represent the fastest-expanding category as manufacturers blend ceramic durability with polymer flexibility to serve automotive underbody and exhaust system applications.
EMA's Medical Device Regulation and REACH chemical authorization requirements in Europe shape product formulation roadmaps by restricting chromium VI and certain solvent carriers in coating chemistries. ECHA's candidate list updates force reformulation cycles that favor waterborne and high-solids technologies over conventional solvent systems. OEM procurement teams and coating formulators must monitor evolving substance restrictions and align R&D pipelines with regulatory sunset dates to maintain market access across European manufacturing networks.
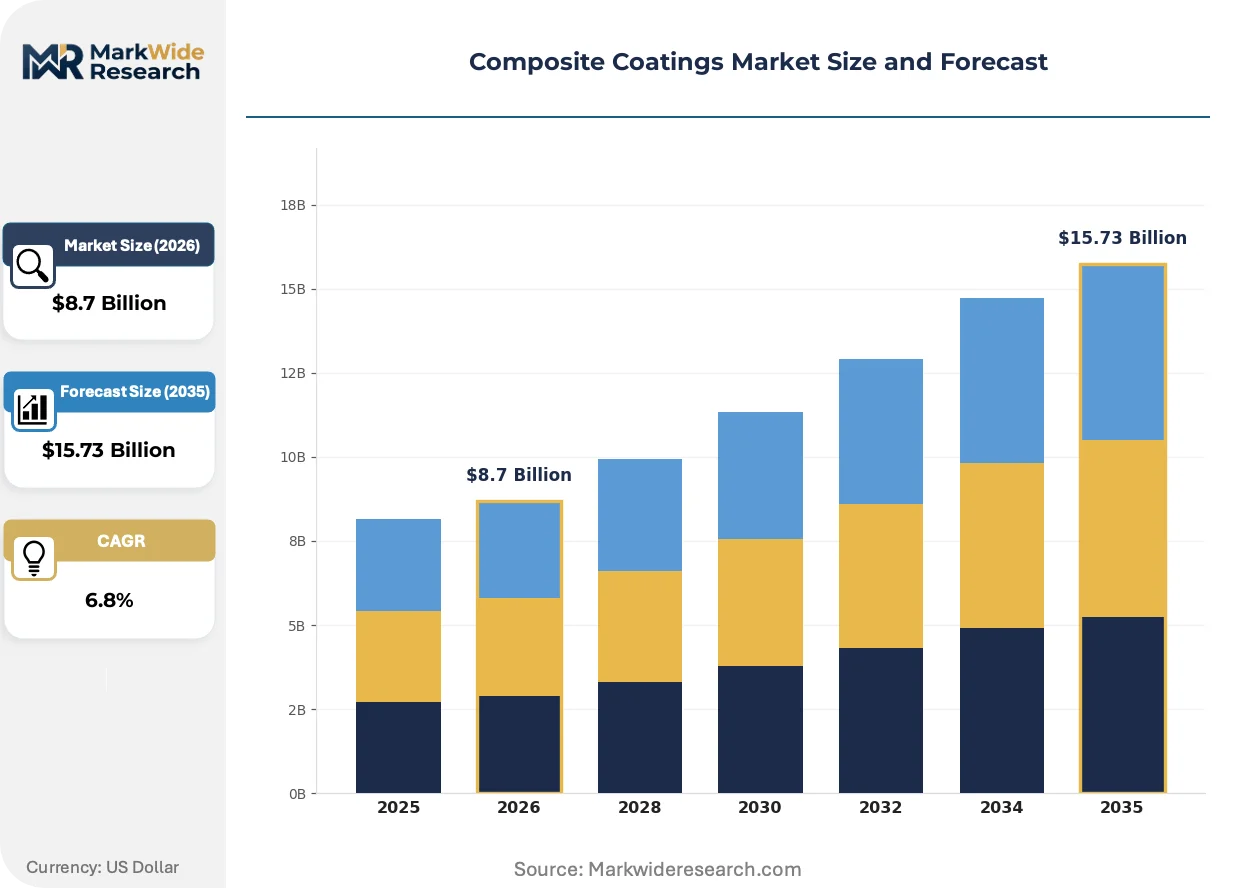
Market Dynamics
Aerospace OEM procurement of ceramic-metal hybrid coatings for turbine blades is compressing qualification timelines and forcing thermal spray equipment providers to expand service networks near engine manufacturing clusters.
Growth Catalysts
- REACH chemical authorization:ECHA's tightening VOC limits under the EU Green Deal are accelerating solvent-free formulation R&D across European coating formulators, creating first-mover advantages for waterborne technology holders.
- Thermal barrier coating demand:Aerospace turbine blade manufacturers are specifying ceramic topcoats with bond coat systems capable of exceeding 1,000 degrees Celsius operational thresholds, pulling investment into plasma spray infrastructure.
- Germany's industrial corridor concentration:Automotive suppliers and chemical processors clustering around coating technology hubs in Baden-Württemberg and North Rhine-Westphalia are generating localized knowledge spillovers and specialized labor pools.
Market Restraints
- Ceramic powder supply concentration:Yttria-stabilized zirconia feedstock for thermal barrier coatings concentrates among limited specialty chemical producers, exposing aerospace coaters to input price volatility and allocation risk.
- Chromium VI restriction friction:ECHA's sunset dates for hexavalent chromium in corrosion-resistant primers force immediate reformulation without fully qualified alternatives, creating performance gaps in marine and industrial applications.
- Hybrid coating technical limitation:Ceramic-polymer matrix adhesion failures under thermal cycling remain unresolved for automotive exhaust system applications, capping penetration in high-temperature flex environments.
Strategic Opportunities
- India automotive underbody protection:BIS standards adoption and domestic OEM localization programs are opening specification windows for ceramic-polymer hybrid coatings in corrosion-prone chassis applications.
- EU F-Gas Regulation phase-down:The refrigerant containment mandate for HVAC equipment is creating retrofit demand for low-permeability polymer barrier coatings on heat exchanger components.
- Plasma spray-cold spray convergence:Equipment manufacturers blending high-velocity oxygen fuel deposition with solid-state cold spray capabilities are enabling multi-material coating architectures for repair and additive applications.
Industry Challenges
- Thermal spray technician certification backlog:OEM qualification requirements for AS9100 and NADCAP coating approvals outpace vocational training program throughput, constraining qualified labor supply for aerospace contract shops.
- Legacy solvent system integration:Industrial equipment manufacturers maintaining conventional high-solids coating lines face parallel inventory complexity during waterborne transition periods, elevating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Coatings Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Coatings, Ceramic Coatings, Metal Coatings, Hybrid Coatings Application: Aerospace, Automotive, Marine, Industrial Equipment End User: Manufacturers, Contractors, Distributors, OEMs Technology: Thermal Spray, Electroplating, Chemical Vapor Deposition, Liquid Coating |
| Companies Covered | The Sherwin-Williams Company, Akzo Nobel N.V., PPG Industries, Inc., Axalta Coating Systems, LLC, RPM International Inc., A.W. Chesterton Company, KC Jones Plating Company, Poeton Industries Ltd., Mader Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Coatings Market Emerging Trajectories
Formulation chemistry and deposition equipment are converging to collapse traditional trade-offs between thermal performance and mechanical flexibility, rewiring specification criteria across aerospace and automotive supply chains.
Cold spray deposition of metal-matrix composites is collapsing the distinction between repair and original manufacturing for turbine components. MRO providers at Singapore's aerospace cluster are adopting portable systems for on-wing blade restoration, compressing turnaround times from weeks to days. The technology is collapsing capital barriers for mid-tier service providers previously excluded from OEM-approved repair networks.
REACH authorization timelines for chromium VI compounds are forcing marine coating formulators to accelerate trivalent chromium and rare-earth inhibitor development. The industrial consequence is a two-tier supply structure separating compliant waterborne systems from grandfathered solvent formulations in restricted applications. Shipyards in Northern Europe are responding by consolidating procurement with formulators holding full substance authorization portfolios.
Automotive OEM coating specifications are rotating toward lifetime corrosion warranties that bundle substrate pretreatment, primer, and topcoat performance accountability. Tier suppliers are displacing discrete coating purchases with integrated subsystem contracts that transfer liability downstream. This concentration is most visible in Germany's supplier network, where exhaust component manufacturers are qualifying single-source hybrid coating providers for 10-year durability guarantees.
Composite Coatings Market Segmentation
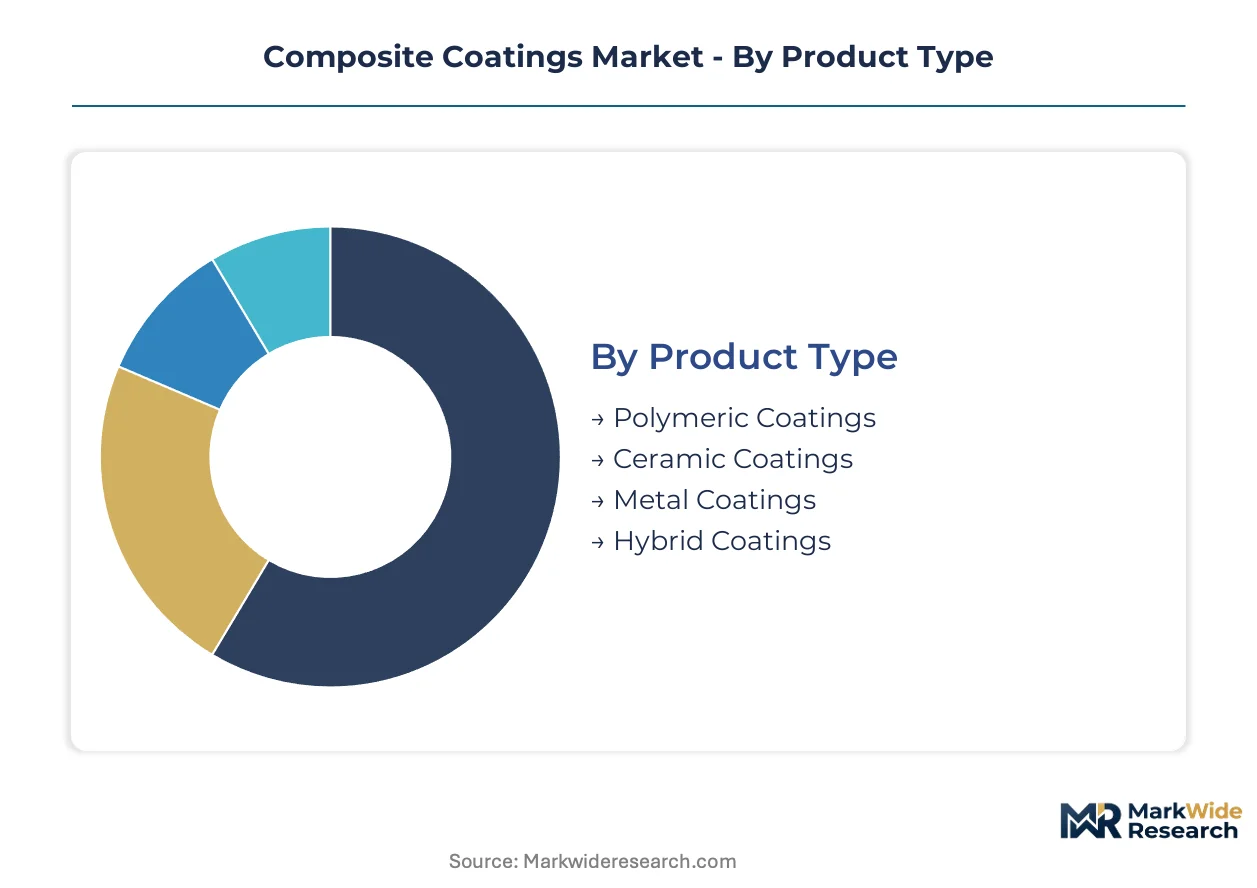
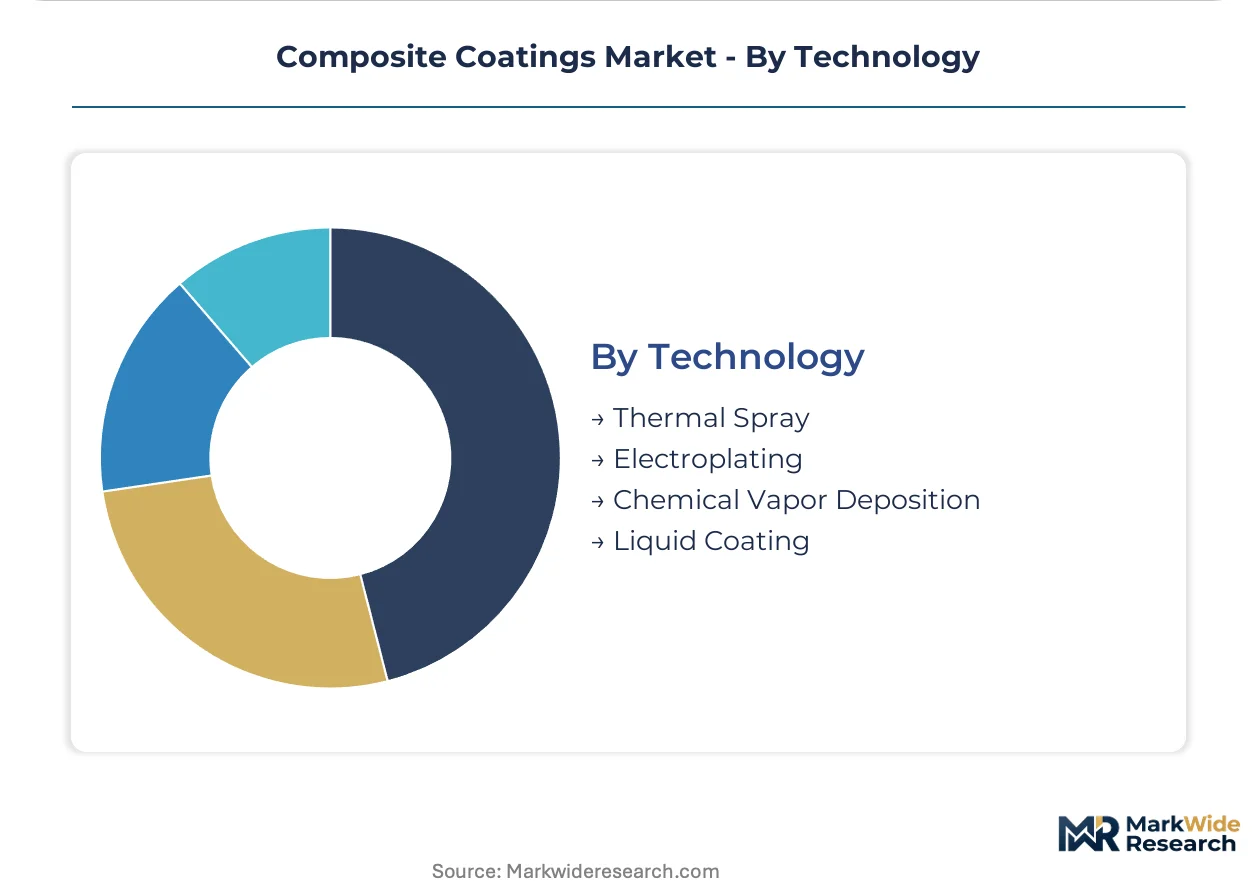
Composite coatings serve divergent performance requirements across temperature extremes, chemical exposure, and mechanical stress. Segmentation reveals how formulation chemistry and deposition technology align with specific industrial durability demands.
Product Type:
Cost tier positioning separates commodity volume plays from premium thermal protection systems.
- Polymeric Coatings:These formulations combine epoxy, polyurethane, and fluoropolymer matrices applied via spray or dip processes for corrosion and chemical resistance. Demand concentrates in marine hull protection and industrial tank linings where film thickness flexibility and substrate adhesion drive specification. REACH VOC limits are accelerating waterborne polymeric transitions across European shipyards.
- Ceramic Coatings:Yttria-stabilized zirconia and alumina-based thermal barrier systems deposited through plasma spray achieve operational thresholds exceeding 1,000 degrees Celsius. Aerospace turbine blade manufacturers in Germany's industrial corridor specify these coatings for bond coat architectures, pulling capital into high-velocity oxygen fuel equipment.
- Metal Coatings:Electroplated and thermally sprayed metal matrices provide wear resistance and electrical conductivity for industrial machinery components.
- Hybrid Coatings:Ceramic-polymer composites blend thermal durability with mechanical flexibility for automotive exhaust and underbody applications.
Polymeric coatings command the established base. The steepest expansion runs through hybrid formulations bridging ceramic and polymer performance domains.
Application:
End-use environment severity dictates coating specification hierarchy from atmospheric corrosion to molten metal exposure.
- Aerospace:Turbine blade thermal barrier systems require ceramic topcoats with engineered porosity for thermal gradient management. OEM procurement in Germany and Singapore clusters compresses qualification timelines for plasma spray service providers.
- Automotive:Exhaust system and underbody protection specifications rotate toward lifetime corrosion warranties bundling pretreatment, primer, and topcoat accountability. Tier suppliers in Baden-Württemberg qualify single-source hybrid coating providers for 10-year durability guarantees.
- Marine:Hull and ballast tank coatings face ECHA chromium VI sunset dates forcing trivalent chromium and rare-earth inhibitor development.
- Industrial Equipment:Chemical processing vessels and pump housings specify coatings for abrasion and chemical attack resistance.
Aerospace applications concentrate premium value. Automotive specifications are gaining share fastest as warranty liability transfers downstream to coating providers.
End User:
Customer type determines specification authority and procurement complexity across direct OEM relationships versus distributor channels.
- Manufacturers:In-house coating operations at automotive and aerospace production facilities control substrate preparation and deposition quality for critical components. These captive operations concentrate in Germany's supplier network where exhaust component makers integrate thermal spray cells.
- Contractors:Specialized applicators serve marine shipyards and industrial maintenance markets with field-applied polymeric systems. Northern European shipyards consolidate procurement with formulators holding full REACH substance authorization portfolios.
- Distributors:Channel intermediaries stock liquid coating inventories for maintenance, repair, and overhaul segments.
- OEMs:Original equipment manufacturers specify coating architectures for supplier compliance and warranty alignment.
Manufacturers retain specification authority for critical applications. Contractors are expanding fastest as MRO demand shifts toward on-site restoration capabilities.
Technology:
Deposition method selection trades capital intensity against coating architecture complexity and substrate thermal exposure limits.
- Thermal Spray:Plasma spray and high-velocity oxygen fuel systems deposit ceramic and metal matrices at elevated temperatures for dimensional restoration and wear resistance. Equipment providers are expanding service networks near engine manufacturing clusters in Germany and Singapore to compress aerospace qualification timelines.
- Electroplating:Aqueous electrolytic deposition applies metallic coatings for corrosion protection and functional surface properties. ECHA chromium VI restrictions force immediate reformulation without fully qualified alternatives, creating performance gaps in marine and industrial primer applications.
- Chemical Vapor Deposition:Gas-phase precursor reactions form dense ceramic coatings for cutting tools and semiconductor processing equipment.
- Liquid Coating:Conventional spray, dip, and flow-coat application of polymeric and hybrid formulations dominates volume through lower capital barriers.
Liquid coating retains volume leadership. Thermal spray infrastructure is climbing fastest as aerospace procurement compresses turnaround requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework anchors European demand as chemical authorization timelines compress formulation cycles across coating value chains. Regional differentiation sharpens as aerospace clusters, automotive manufacturing corridors, and marine shipyards concentrate procurement with compliant formulators.
Germany
Aerospace OEMs in Munich and Stuttgart specify ceramic-metal hybrid coatings for turbine blade architectures exceeding thermal thresholds. EU Green Deal VOC limits accelerate solvent-free R&D at Baden-Württemberg formulators. The industrial corridor between North Rhine-Westphalia and Bavaria clusters thermal spray service providers near engine manufacturing cells.
United States
EPA emissions standards and FAA airworthiness directives shape coating qualification protocols for commercial aviation MRO networks. Defense procurement through the Department of Defense sustains plasma spray infrastructure for turbine component restoration. The Southeast aerospace cluster in Georgia and South Carolina concentrates coating applicators with NADCAP accreditation.
China
MIIT industrial upgrading guidelines prioritize domestic thermal barrier coating capacity for aviation and power generation turbines. GB standards for VOC emissions tighten formulation requirements at Shanghai and Tianjin coating plants. The Yangtze River Delta hosts plasma spray equipment manufacturers serving both domestic aerospace programs and export markets.
Singapore
The Civil Aviation Authority of Singapore's MRO certification framework positions the city-state as a regional hub for on-wing turbine blade restoration using cold spray deposition. Port infrastructure supports marine coating application for vessel hull protection meeting IMO environmental standards. Seletar Aerospace Park concentrates coating service providers with OEM-approved repair station status.
India
BIS standards adoption for automotive corrosion protection opens specification windows for ceramic-polymer hybrid coatings in chassis applications. PLI scheme incentives localize coating formulation capacity for domestic OEM supply chains. Tamil Nadu and Maharashtra automotive corridors cluster exhaust component manufacturers qualifying hybrid coating providers for warranty-aligned supply contracts.
Composite Coatings Market Vendor Landscape
Capability concentration sits with specialized thermal spray service providers holding aerospace OEM approvals; scale advantage sits with diversified coating formulators with continental distribution networks. The market structures around three tiers: global chemical conglomerates with waterborne portfolios, regional thermal spray specialists with NADCAP accreditation, and niche hybrid formulators serving automotive warranty programs. Consolidation pressure runs through M&A activity targeting qualified aerospace coating assets and strategic partnerships bridging formulation chemistry with deposition equipment integration.
Among diversified chemical formulators, PPG Industries, Akzo Nobel N.V., and The Sherwin-Williams Company occupy positions spanning industrial equipment, automotive, and aerospace specification channels. These entities exemplify the scale-driven tier where continental manufacturing networks and distributor channel control anchor market presence. Their positioning reflects the competitive imperative to align waterborne formulation portfolios with tightening ECHA authorization timelines while sustaining R&D intensity in thermal barrier systems.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| Axalta Coating Systems, LLC |
| RPM International Inc. |
| A.W. Chesterton Company |
| KC Jones Plating Company |
| Poeton Industries Ltd. |
| Mader Group |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's thermal spray service cluster concentrates ceramic powder processing capacity for aerospace turbine blade coatings, translating localized supply scarcity into premium pricing power for yttria-stabilized zirconia formulations. REACH compliance costs and ECHA authorization timelines feed directly into coating price structures, separating authorized waterborne formulators from grandfathered solvent systems facing sunset restrictions.
Pricing Analysis
Price spreads between Germany and India for ceramic-polymer hybrid coatings exceed factor differentials driven by ECHA compliance overhead and logistics intensity. Three-tier pricing structure across premium, standard, and economy levels separates NADCAP-accredited aerospace service providers from industrial equipment coaters and marine maintenance contractors. Cost compression in standard-tier polymeric coatings is intensifying because of waterborne formulation transitions and raw material substitution cycles. Marine shipyards exhibit highest price sensitivity due to chromium VI reformulation urgency, while aerospace OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for plasma spray equipment and ceramic powder feedstocks. Yttria-stabilized zirconia supply concentrates in China, Germany, and the United States, with rare-earth stabilizer processing anchored in Chinese chemical complexes. Formulation chemistry draws from epoxy resins, fluoropolymer dispersions, and alumina-ceramic precursors subject to commodity price volatility. Distribution runs through authorized distributor networks for liquid coatings and direct OEM contracting for thermal spray services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite coatings sit in early-cycle expansion as automotive lifetime corrosion warranties displace discrete coating purchases with integrated subsystem accountability. Cold spray deposition convergence with thermal spray infrastructure is accelerating MRO penetration and compressing qualification barriers for mid-tier service providers.
For Market Incumbents: Pre-empt NADCAP-accredited aerospace coating asset consolidation in Germany's industrial corridor before qualification backlogs constrain qualified labor supply. Secure backward integration into ceramic powder feedstock streams to offset yttria-stabilized zirconia allocation risk from Chinese specialty chemical producers. Anchor channel control through exclusive distributor arrangements for waterborne polymeric formulations ahead of ECHA chromium VI sunset dates.
For New Entrants and Emerging Players: India's automotive underbody protection segment represents the most penetrable entry point, with BIS standards adoption and PLI scheme incentives localizing specification windows for ceramic-polymer hybrid coatings. EU F-Gas Regulation retrofit demand for HVAC heat exchanger barrier coatings offers a secondary white-space target with lower capital barriers than aerospace qualification. Pursue joint development agreements with domestic OEMs to embed coating specifications into platform engineering cycles rather than competing as aftermarket suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal spray service providers with OEM-approved repair station status and cold spray capability integration. Long-term viability hinges on deposition equipment convergence and regulatory compliance portfolio breadth rather than formulation chemistry alone. Watch for plasma spray-cold spray equipment manufacturer partnerships as the inflection signal for multi-material coating architecture adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Supply | Secures yttria-stabilized zirconia feedstock access against Chinese allocation risk and price volatility. |
| NADCAP Accreditation Investment | Unlocks aerospace OEM procurement channels with compressed qualification timelines in Germany and Singapore clusters. |
| Waterborne Formulation Transition | Aligns product portfolios with ECHA REACH authorization timelines and EU Green Deal VOC limits. |
| Cold Spray Capability Addition | Enables on-wing turbine blade restoration and collapses turnaround times from weeks to days. |
| Automotive Warranty Integration | Captures downstream liability transfer as OEMs bundle coating performance into 10-year durability guarantees. |
Methodological Framework
Initial hypotheses were tested against primary input from thermal spray service technicians, aerospace OEM procurement managers, marine coating formulators, and automotive Tier 1 supplier quality directors and refined through secondary validation against ECHA substance authorization databases, SEC 10-K filings of diversified coating formulators, customs trade data for ceramic powder imports, and ACC industry reports. Bottom-up demand modeling across application segments triangulated with top-down market sizing from production capacity and equipment installation data.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled by coating chemistry, deposition technology, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle analysis, incorporating aerospace production schedules, automotive platform lifecycles, and shipyard maintenance intervals as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, aerospace delivery rates, or marine freight volumes would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timelines and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Reinforced Plastics Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
Decorative High-Pressure Laminates Market
Composite Materials
Lightweight Materials Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Plastic Composites Market
Composite Materials
Graphite Felt Market