
 Water Based Enamel Market | 2026-2036
Water Based Enamel Market Size, Share, and Industry Trends Forecast 2026-2036
Water Based Enamel Market Intelligence
Performance differentiation in water based enamel is pivoting on durability and low-VOC content, creating a widening gap between premium architectural coatings and standard industrial finishes. Sherwin-Williams leverages its extensive distribution network to serve the North American residential and commercial sectors. In contrast, AkzoNobel specializes in high-performance coatings for industrial machinery and automotive components, focusing on chemical resistance and color retention across its product lines.
Water based enamel is a surface coating that utilizes water as its primary solvent instead of chemical solvents. These formulations typically incorporate acrylic, alkyd, or polyurethane resins to form a hard, protective film upon drying. The principal function is to deliver a durable, washable, and often glossy finish for wood, metal, and walls with significantly lower volatile organic compound (VOC) emissions. Acrylic formulations dominate the market due to their fast-drying properties and excellent adhesion. The residential application segment drives volume, but higher margins are found in specialized industrial and automotive applications requiring advanced polyurethane-based enamels.
Regulations from the US Environmental Protection Agency (EPA) and Europe's ECHA under the REACH framework mandate lower VOC levels in paints, directly favoring water based technologies. China's Ministry of Ecology and Environment (MEE) enforces similar stringent standards, compelling manufacturers to adapt their formulations for market access. Future competitiveness depends on developing cost-effective bio-based resins and achieving superior finish quality without compromising environmental compliance.
Market Dynamics
The market's central dynamic is the tension between stringent global regulations on volatile organic compound (VOC) emissions and the persistent demand for the high-gloss, durable finish traditionally associated with solvent-based systems, forcing innovation in resin and additive technology.
Growth Catalysts
- Regulatory Mandates:Stricter VOC limits under frameworks like the European Union's REACH are accelerating the substitution of solvent-based paints, creating a direct pull for water-based enamel formulations across architectural and industrial sectors.
- Construction Activity:Expansive residential and commercial building projects, particularly in China and Southeast Asia, drive significant volume demand for interior and exterior coatings that comply with new environmental building codes.
- Resin Technology:Advances in acrylic and polyurethane resin chemistry are improving the performance of water-based enamels, delivering better hardness, faster drying times, and enhanced adhesion on diverse substrates like metal and wood.
Market Restraints
- Performance Gaps:Achieving the same level of hardness, chemical resistance, and high-gloss finish as solvent-based alkyd enamels remains a technical hurdle, particularly in demanding industrial and automotive applications.
- Input Cost Volatility:The price and availability of key raw materials, such as titanium dioxide (TiO2) and specialized acrylic binders, are subject to supply chain disruptions and can impact final product cost.
- Alternative Technologies:For some industrial finishing applications, powder coatings and high-solids solvent-based systems present a competitive threat, offering superior durability without the drying time constraints of water-based products.
Strategic Opportunities
- Bio-Based Formulations:Developing enamels using bio-based resins and renewable solvents presents an opportunity to capture share among environmentally conscious consumers and specifiers, moving beyond simple VOC reduction to full lifecycle sustainability.
- Hybrid Chemistries:Combining acrylic and polyurethane resins into hybrid systems allows for the creation of coatings that balance cost-effectiveness with high-performance characteristics like flexibility and abrasion resistance for specialized applications.
- Emerging Economies:Market penetration in Latin American and African nations offers significant growth potential as urbanization and industrialization increase, alongside the gradual adoption of stricter environmental standards for building materials.
Industry Challenges
- Application Technique Sensitivity:Water-based enamels require different surface preparation and application techniques compared to traditional paints, creating a need for extensive contractor and applicator training to ensure proper finish quality and avoid failures.
- Supply Chain Consistency:Maintaining a consistent global supply of high-quality specialty additives, such as flow modifiers and coalescing agents, is a challenge that can affect the final performance and batch-to-batch consistency of enamels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Based Enamel Market |
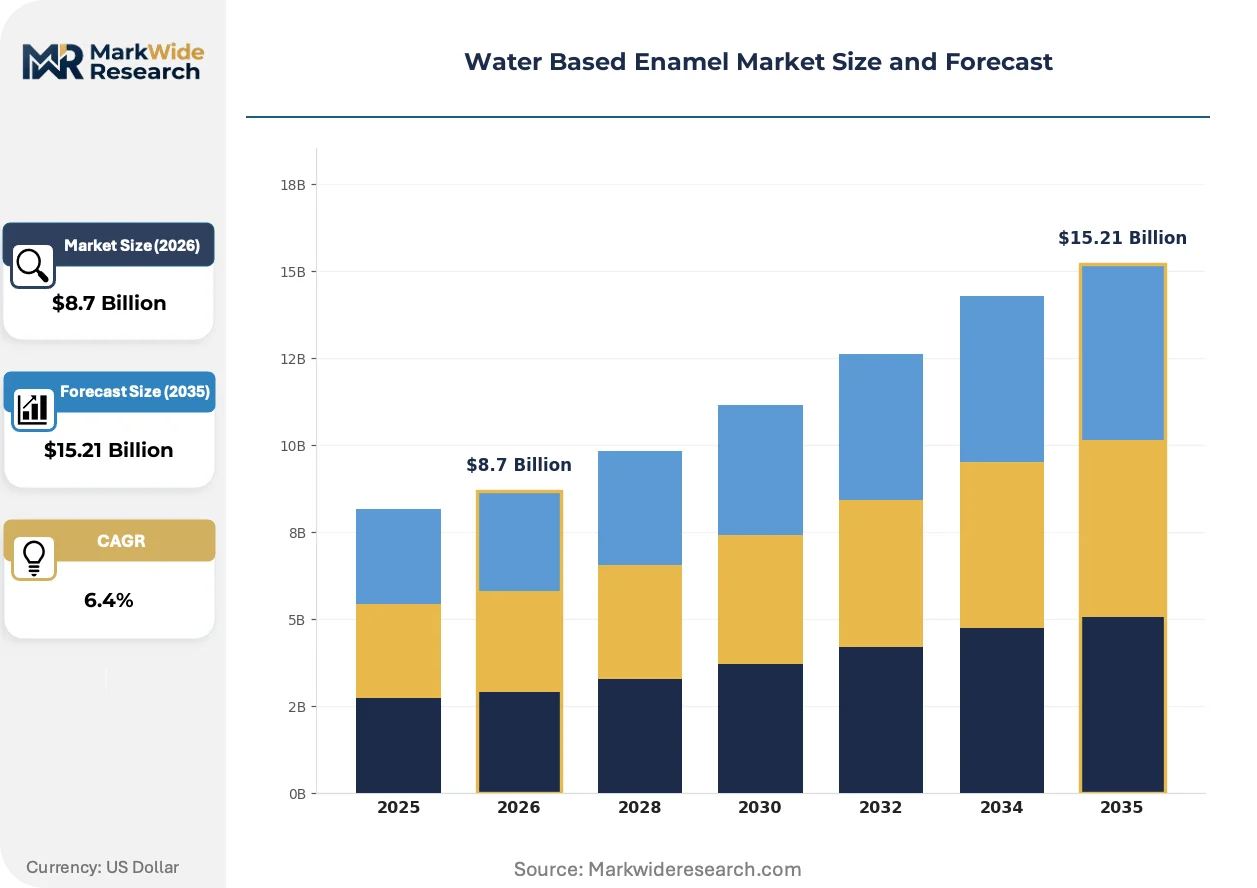
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paint, Exterior Paint, Primers, Sealers Application: Residential, Commercial, Industrial, Automotive Formulation Type: Acrylic, Alkyd, Vinyl, Polyurethane Finish Type: Matte, Gloss, Satin, Semi-Gloss |
| Companies Covered | PPG Industries, Sherwin-Williams, AkzoNobel, BASF, Nippon Paint, Asian Paints, RPM International, Axalta Coating Systems, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Based Enamel Market Strategic Shifts & Innovations
The pursuit of performance parity with solvent-based predecessors defines the current innovation cycle. Development is focused on enhancing durability, chemical resistance, and aesthetic finish while strictly adhering to a complex and ever-tightening global regulatory landscape.
Nanotechnology additives are being incorporated into formulations to improve physical properties like scratch resistance and UV stability. Premium architectural and automotive refinish segments are the primary adopters of these advanced coatings. This technology is integrating enhanced material science directly into the resin matrix, creating films with superior protective qualities without increasing VOC content.
China's Ministry of Ecology and Environment (MEE) has implemented stringent new standards limiting VOC emissions from industrial coatings. This policy is forcing a rapid phase-out of traditional solvent-based enamels in sectors like furniture manufacturing and machinery production. The industrial wood coatings segment is most affected, compelling suppliers to reformulate entire product lines to maintain market access.
A shift toward specifying products with third-party environmental certifications, such as Environmental Product Declarations (EPDs), is gaining traction in procurement. This trend disrupts traditional sales channels in commercial construction by favoring suppliers who can provide verified sustainability data. This behavior is most visible in North American and European green building projects where architects use certifications to meet project requirements.
Water Based Enamel Market Segmentation
Segmentation within the water based enamel market is critical for identifying distinct customer needs and product development priorities. Different end-use requirements for durability, aesthetics, and environmental compliance drive specific formulation choices and application methods. This granular understanding enables manufacturers to target specific market niches and optimize their product portfolios effectively.
Product Type:
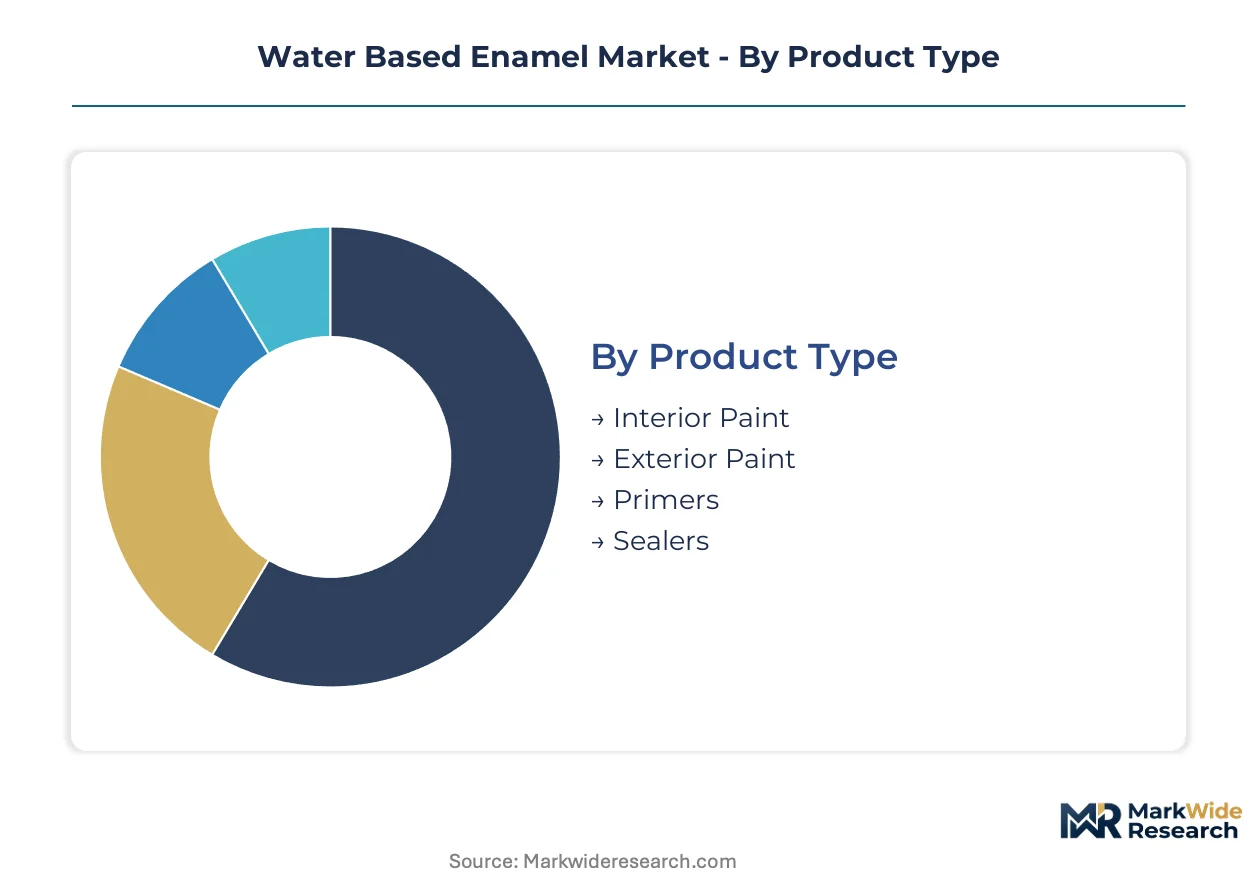
Buyers in the water-based enamel market differentiate their product choices based on the specific surface protection and aesthetic requirements of the project.
- Interior Paint:Formulated for low volatile organic compound emissions and fast drying, these enamels provide durable, washable finishes for indoor walls and trim. Demand concentrates in residential renovations and new commercial building fit-outs across China.
- Exterior Paint:Engineered for weather resistance, UV stability, and mildew protection, these coatings maintain color and integrity on outdoor surfaces. Significant volume demand originates from new residential construction in Southeast Asia.
- Primers:These foundational coatings ensure adhesion and block stains, preparing diverse substrates for subsequent enamel layers.
- Sealers:Designed to penetrate and protect porous surfaces, sealers enhance durability and improve the performance of topcoats.
Volume sits with Interior Paint; growth tilts toward Exterior Paint.
Application:
The intended application dictates the performance specifications and regulatory compliance requirements for water-based enamel products.
- Residential:This segment encompasses interior and exterior coatings for homes, prioritizing low VOCs, ease of application, and aesthetic appeal. Volume demand is substantial across North America and Europe for both new builds and refurbishment projects.
- Industrial:Coatings in this segment provide high chemical resistance, abrasion protection, and corrosion control for machinery, equipment, and infrastructure. Specialized polyurethane-based enamels see strong adoption in European manufacturing sectors.
- Commercial:These enamels are used in offices, retail spaces, and public buildings, focusing on durability and maintenance ease.
- Automotive:Water-based enamels for automotive refinishing offer color matching accuracy and high-gloss finishes, adhering to strict emission standards.
Residential applications command the largest market share, while industrial uses are expanding most quickly due to performance demands.
Formulation Type:
Performance characteristics and cost-effectiveness drive the selection of specific resin chemistries in water-based enamel formulations.
- Acrylic:These formulations offer fast drying times, good adhesion, and color retention, making them prevalent in architectural coatings. The residential construction sector in China heavily utilizes acrylic enamels for interior applications.
- Polyurethane:Known for superior hardness, abrasion resistance, and chemical stability, polyurethane-based enamels serve demanding industrial and automotive applications. European industrial machinery manufacturers increasingly specify these advanced coatings.
- Alkyd:Modified alkyd emulsions provide good flow and leveling properties, often used where solvent-like performance is desired.
- Vinyl:Vinyl-acrylic blends offer flexibility and moisture resistance, suitable for certain exterior and masonry applications.
Acrylic formulations represent the largest volume segment, with polyurethane-based enamels demonstrating the steepest expansion trajectory in specialized markets.
Finish Type:
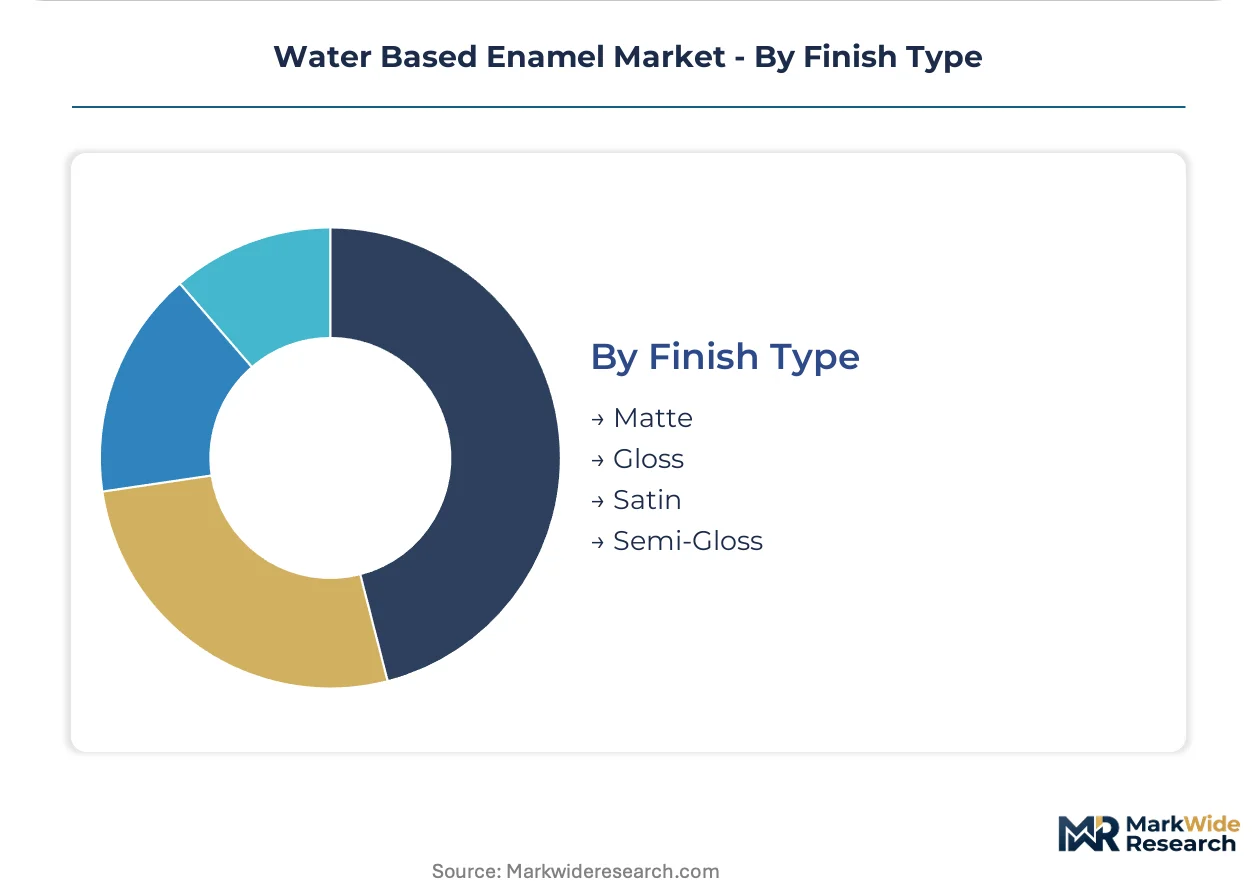
Aesthetic preference and functional requirements for light reflection and surface durability guide choices within the finish type segment.
- Gloss:These enamels provide a highly reflective, smooth surface that is easy to clean and offers excellent durability. High-gloss finishes are popular in automotive refinishing and specialized industrial applications across Germany.
- Matte:Offering a non-reflective, sophisticated appearance, matte finishes are increasingly specified in contemporary architectural designs. Residential interior projects in the United States show strong demand for these low-sheen options.
- Satin:Satin finishes offer a subtle sheen, balancing durability with a softer aesthetic for various interior surfaces.
- Semi-Gloss:Providing a moderate sheen, semi-gloss enamels are commonly used for trim, doors, and cabinets due to their cleanability.
Gloss finishes historically dominate industrial applications, but matte finishes are gaining share fastest in architectural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's burgeoning construction sector drives significant demand for water-based enamel, particularly in residential and commercial projects. Stricter environmental building codes in major urban centers compel architects and developers to specify low-VOC coatings. This focus on sustainable materials reshapes procurement patterns across the country.
China
Extensive building projects in cities like Guangzhou and Shenzhen fuel demand for interior and exterior water-based enamels. The Ministry of Ecology and Environment (MEE) enforces stringent VOC limits, accelerating the shift from solvent-based alternatives. Industrial hubs in the Yangtze River Delta are rapidly adopting these compliant formulations.
United States
Residential renovations and new commercial constructions across states like California and Texas require vast quantities of water-based enamels. The US Environmental Protection Agency (EPA) mandates lower VOC levels in paints, directly influencing product development. Major architectural coating manufacturers in the Midwest are expanding production of eco-friendly options.
Germany
High-performance industrial and automotive applications in regions like Bavaria and North Rhine-Westphalia drive demand for specialized polyurethane-based enamels. Europe's ECHA under the REACH framework sets strict chemical safety standards, favoring advanced water-based technologies. Chemical manufacturing clusters around Ludwigshafen are innovating new bio-based resin systems.
India
Rapid urbanization and infrastructure development in metropolises such as Mumbai and Bangalore increase the need for durable architectural coatings. The Bureau of Indian Standards (BIS) promotes eco-labeling for paints, encouraging the use of greener alternatives. Construction firms in the Delhi-NCR region are increasingly specifying water-based solutions for large-scale projects.
Vietnam
New residential and commercial building activity in Hanoi and Ho Chi Minh City generates substantial volume for exterior water-based paints. The country's environmental protection laws are gradually tightening, pushing manufacturers towards lower-VOC products. Industrial zones near Da Nang are seeing greater adoption of these coatings for various applications.
Water Based Enamel Market Key Industry Players
Premium-margin players sit above commodity-margin players across product performance and specialized application segments. The water-based enamel market exhibits a tiered structure, with global chemical conglomerates operating alongside regional specialists. Strategic archetypes include diversified coating giants, niche industrial solution providers, and architectural paint manufacturers. Geographic expansion and portfolio diversification are dominant competitive moves among these participants.
Diversified coating giants like Sherwin-Williams and AkzoNobel exemplify the global reach and broad product portfolios. These entities often leverage extensive distribution networks to serve both residential and industrial sectors, offering a wide range of water-based enamel solutions designed for diverse performance requirements. Nippon Paint, a prominent Asian firm, represents a strong regional focus within the architectural coatings segment, adapting formulations for local climate and specific building practices across its core markets. These companies anchor distinct competitive approaches within the market, from high-volume architectural finishes to specialized industrial applications demanding advanced material properties.
| Leading Market Players |
|---|
| PPG Industries |
| Sherwin-Williams |
| AkzoNobel |
| BASF |
| Nippon Paint |
| Asian Paints |
| RPM International |
| Axalta Coating Systems |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
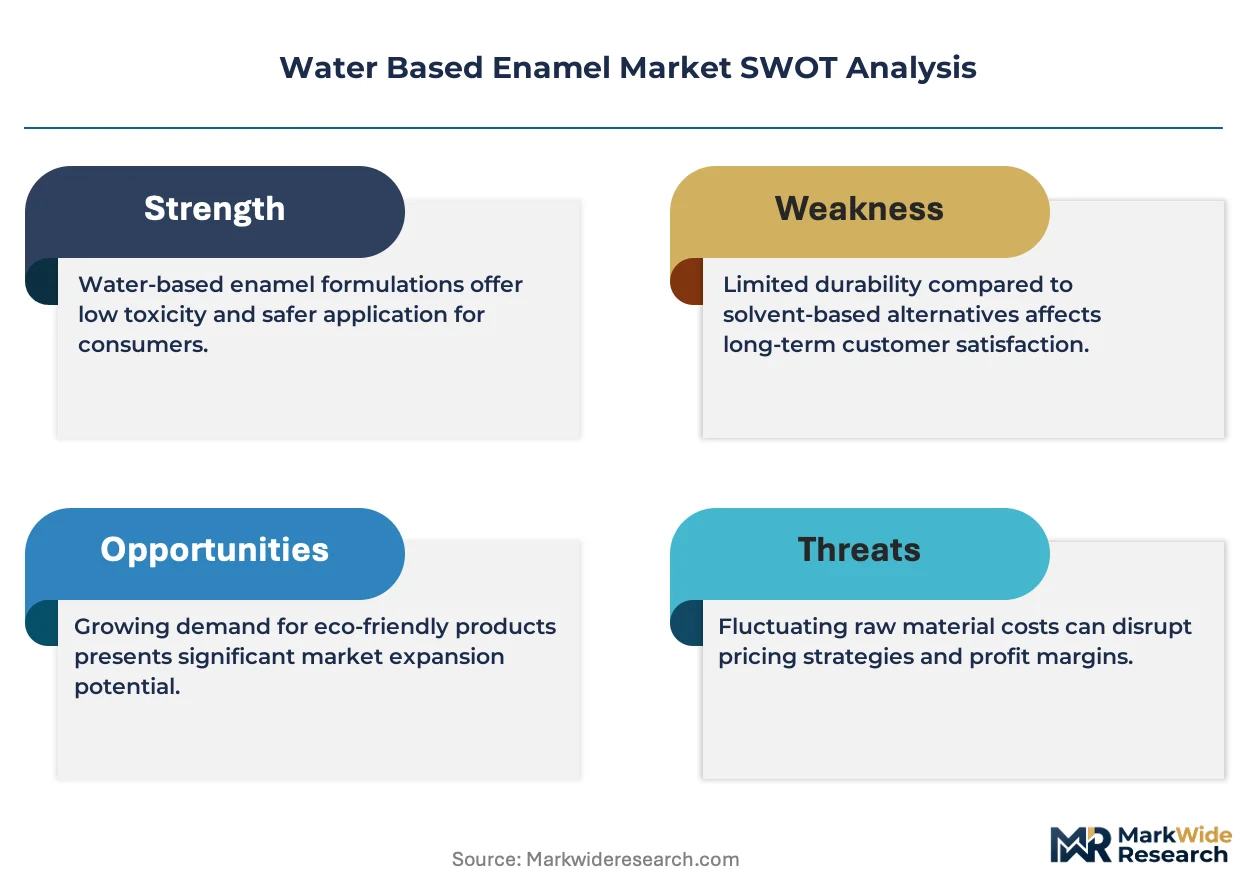
Titanium dioxide (TiO2) price indices, a key raw material for opacity and whiteness, cascade through the water based enamel supply chain, influencing pricing tiers from commodity architectural paints to specialized industrial coatings. This volatility impacts manufacturers' margins and product development strategies. The market dynamic reflects the interplay between raw material costs and the value proposition of low-VOC, high-performance formulations.
Pricing Analysis
Outcome-based pricing anchors the premium segments of the water based enamel market, where performance attributes like durability and low-VOC content command higher value. Price differentiation stems from quality grade, specific environmental certifications like EPDs, and brand premium associated with long-standing manufacturers. Pricing pressure stems from input cost volatility, particularly for specialized binders and additives, and competition from cost-effective solvent-based alternatives in some regions. The residential segment demonstrates higher price sensitivity for volume products, while specialized industrial and automotive applications prioritize performance over cost.
Supply Chain Analysis
Reverse logistics for unused paint and packaging waste are increasingly influencing supply chain design, driven by environmental regulations in Europe and China. Supply concentration for key raw materials like titanium dioxide and specialized acrylic binders centers on China and Germany. The market draws from a global network of chemical suppliers for specialty additives. Commodity price volatility for petrochemical-derived resins presents a structural risk. Distribution runs through extensive regional networks for architectural coatings and direct sales channels for high-performance industrial enamels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water based enamel market is experiencing a vertical-integration race, with players pursuing upstream control over bio-based resin production to meet sustainability mandates.
For Market Incumbents: Anchor market share by investing heavily in advanced resin R&D, particularly in bio-based and hybrid chemistries for superior performance. Expand distribution networks in emerging economies, leveraging existing infrastructure to meet growing demand in residential and commercial sectors. Defend against new entrants by securing third-party environmental certifications like EPDs, which are becoming critical in North American and European green building projects. Consolidate market position through strategic acquisitions of smaller firms with proprietary additive technologies to counter stringent VOC regulations.
For New Entrants and Emerging Players: Environmentally conscious specifiers represent an underserved buyer archetype, seeking transparent and sustainable coating solutions. Target specialized industrial applications in Europe and China requiring advanced chemical resistance and color retention, leveraging novel resin formulations. Penetrate emerging economies like India and Vietnam, where urbanization drives demand for durable, compliant architectural coatings. Focus on a go-to-market strategy emphasizing third-party environmental certifications and superior application support to differentiate from established players.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated specialty chemical firms in Germany and China, focusing on advanced materials science. The long-term viability of this market hinges on the sustained shift towards sustainable building materials and stringent environmental regulations over the next decade. Identify acquisition targets with proprietary bio-based resin technologies or strong positions in high-margin specialized industrial segments. A significant acceleration in global VOC reduction mandates, exceeding current industry reformulation capabilities, serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bio-Based Resins | Increases supply of sustainable raw materials, aligning with global environmental compliance and green building standards. |
| Joint Venture for Nanotechnology Additives | Accelerates development of coatings with enhanced scratch resistance and UV stability for premium applications. |
| Green Manufacturing Transition | Reduces operational environmental footprint, attracting environmentally conscious customers and improving brand perception. |
| Long-term Supply Agreement for TiO2 | Mitigates input cost volatility, ensuring stable production and predictable pricing for end products. |
| Certification Investment (EPDs) | Validates product sustainability claims, meeting procurement requirements for green building projects in key markets. |
Research Approach
Multi-period observation of VOC emission levels, construction activity indices, and resin technology advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. The study combined primary data from R&D directors, procurement leads for construction firms, regulatory compliance officers, and architectural specifiers with extensive secondary research. Data validation involved cross-referencing information from EPA, ECHA, and MEE regulatory documents, construction industry reports, chemical industry association publications, and company annual reports, ensuring robust bottom-up and top-down triangulation.
An input-output matrix framing guided the analytical framework across the analysis window, modeling market dynamics across product type, application, formulation type, finish type, and regional adoption patterns. Compound annual growth rates were derived from historical performance and projected shifts in regulatory landscapes and technological advancements. Key industry-specific forecast inputs included anticipated regulatory enforcement schedules for VOC limits and new building code adoptions in major urban centers.
Revisions become necessary when unforeseen raw material supply disruptions, accelerated regulatory changes, or significant shifts in construction sector growth materialize. Forecasts reflect assumptions regarding technological progression and market acceptance of sustainable solutions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Polyaspartic Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Global Polyurea Coating Market
Coatings
Wood Preservative Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Thermal Insulation Coating Market
Coatings
Japan Marine Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Marine Nanocoating Market
Coatings
Consumer Appliance Coatings Market
Coatings
Polyester Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Polyurethane Powder Coatings Market