
 Filter Panels Market | 2026-2036
Filter Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Filter Panels Market Insights
HEPA-grade specification upgrades is redrawing competitive boundaries in the filter panels market. Mann+Hummel leverages its automotive filtration heritage to anchor industrial panel supply chains across Europe. Donaldson Company specializes in ruggedized panel designs for heavy manufacturing environments. Freudenberg Filtration Technologies extends its polymer media expertise into cleanroom-grade panel applications.
Filter panels are rigid or pleated media assemblies housed in framed enclosures, typically rated by MERV, HEPA, or ULPA efficiency standards against particle sizes down to 0.3 microns, serving to remove contaminants from air or liquid process streams. HEPA product types command premium positioning in pharmaceutical and semiconductor cleanrooms where particle retention thresholds are non-negotiable. Activated carbon panels capture volatile organic compounds in HVAC systems across commercial and residential end users. Fiberglass variants occupy cost-sensitive manufacturing applications where replacement frequency exceeds performance sensitivity.
EPA establishes minimum efficiency reporting value benchmarks for commercial panel installations under the National Ambient Air Quality Standards framework. ISO 16890 and EN 779 test protocols are displacing older rating systems across European and Asian procurement specifications. OSHA ventilation requirements in manufacturing facilities mandate periodic panel replacement cycles that sustain aftermarket demand. Stakeholders must weigh media material selection against evolving multi-jurisdictional certification burdens.
Market Dynamics
ISO 16890 test protocols are displacing legacy EN 779 ratings across procurement specifications, forcing manufacturers to recertify entire product lines while buyers reassess supplier qualifications against particle size efficiency curves rather than synthetic dust arrestance.
Growth Catalysts
- Semiconductor cleanroom expansion:Taiwan's foundry buildouts and South Korea's memory fabrication plants are mandating HEPA-grade panel installations at volumes that strain existing supply chains.
- EPA National Ambient Air Quality Standards:The agency's tightened PM2.5 thresholds are compelling commercial HVAC retrofits across US healthcare and educational facilities.
- Activated carbon composite media:Hybrid panels capturing both particulate and VOC loads are penetrating pharmaceutical packaging lines where single-function filtration previously dominated.
Market Restraints
- Glass microfiber supply concentration:Japanese and German specialty fiber producers control critical input volumes, exposing panel assemblers to freight cost volatility and allocation rationing during demand spikes.
- MEE enforcement in China:The Ministry of Ecology and Environment's emissions audits are shuttering unlicensed media coating facilities, constricting domestic supply for cost-sensitive fiberglass variants.
- Extended-life synthetic media substitution:Washable electrostatic filters are capturing residential and light commercial segments where disposable panel replacement cycles previously guaranteed recurring revenue.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Subsidized semiconductor and component fabrication investments in Gujarat and Karnataka are generating first-time cleanroom filtration demand from domestic rather than imported sources.
- EU F-Gas Regulation phase-down:Refrigerant containment requirements in HVAC systems are accelerating demand for activated carbon panels with specialized adsorption chemistries.
- Direct procurement platforms:Industrial buyers in Germany are bypassing distribution layers through B2B marketplaces that expose price transparency and compress supplier margins.
Industry Challenges
- ISO 16890 laboratory certification backlog:Testing facility capacity constraints in Europe and Asia are extending product validation timelines from weeks to months, freezing new product introductions.
- Pleating automation capex requirements:Mini-pleat geometries demanded by semiconductor customers require capital equipment upgrades that mid-tier assemblers cannot finance without dilutive raises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filter Panels Market |
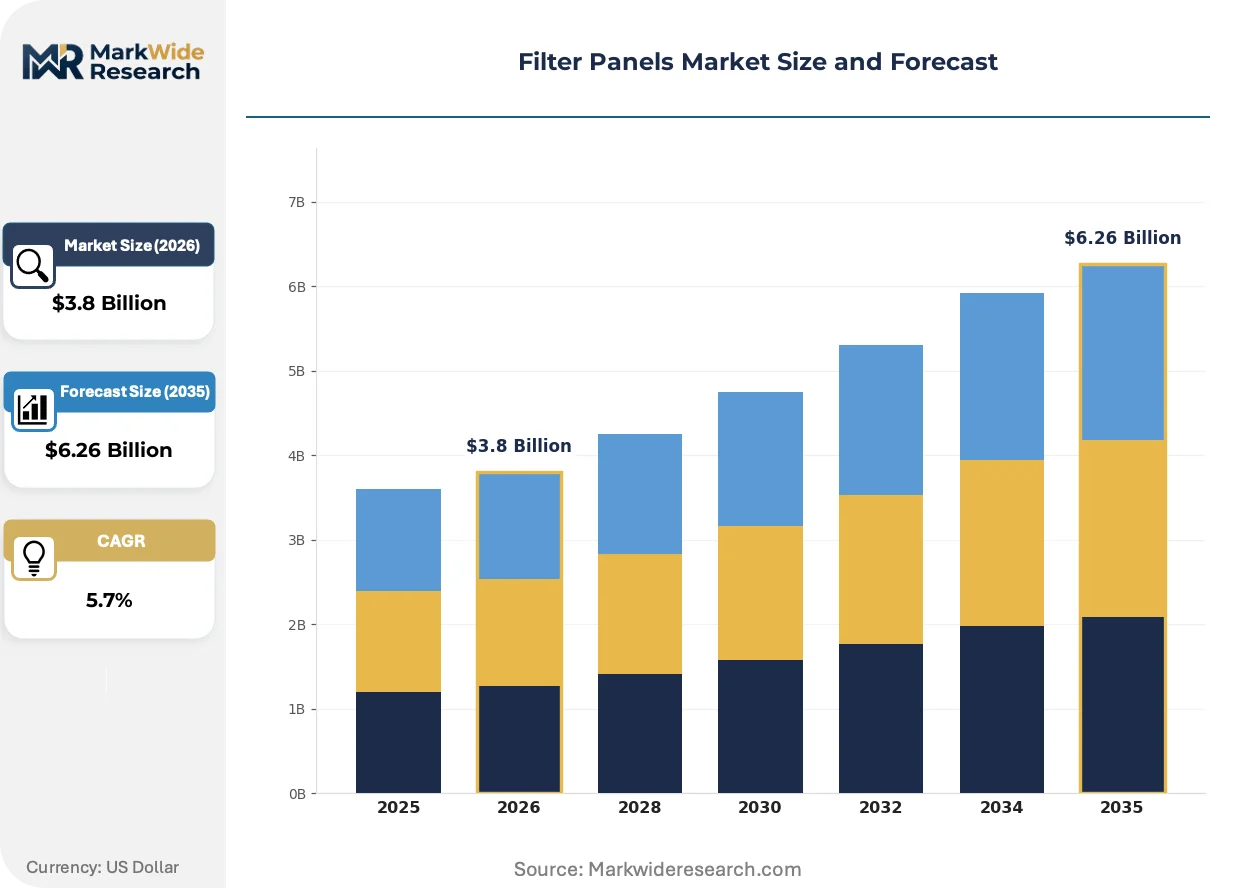
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Electrostatic, Fiberglass Application: Air Filtration, Liquid Filtration, HVAC Systems, Cleanrooms Material: Polymer, Metal, Glass Fiber, Non-Woven End User: Manufacturing, Healthcare, Food & Beverage, Residential |
| Companies Covered | Camfil AB, AAF International, AFPRO Filtration Group, Mann+Hummel, Parker Hannifin, Donaldson Company, Freudenberg Filtration Technologies, Koch Filter Corporation, Troy Filters Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filter Panels Market Trends and Innovations
Electrospun nanofiber surface layers are penetrating premium panel tiers while regulatory test protocols fragment across jurisdictions. Buyers now prioritize documented efficiency curves over nominal MERV ratings.
Nanofiber-coated substrate technology applies sub-micron polymer webs to conventional cellulose or fiberglass bases. Pharmaceutical aseptic processing facilities are specifying these composites for sub-HEPA prefiltration stages. The technology is displacing depth-loading media in applications where pressure drop stability across service life determines energy cost exposure.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-repellent treatments historically applied to HVAC panels in food processing environments. Panel manufacturers are reformulating with silicone-based alternatives that sacrifice some hydrophobic performance. German and French food safety auditors are rejecting legacy-treated inventories, forcing accelerated replacement cycles.
Lifecycle service contracts are unbundling panel supply from installation and disposal logistics. Hospital facilities management departments in the United Kingdom are contracting directly with filtration service providers who own inventory risk and schedule replacement intervals. This compresses distributor roles while shifting working capital burdens upstream to manufacturers.
Filter Panels Market Segmentation
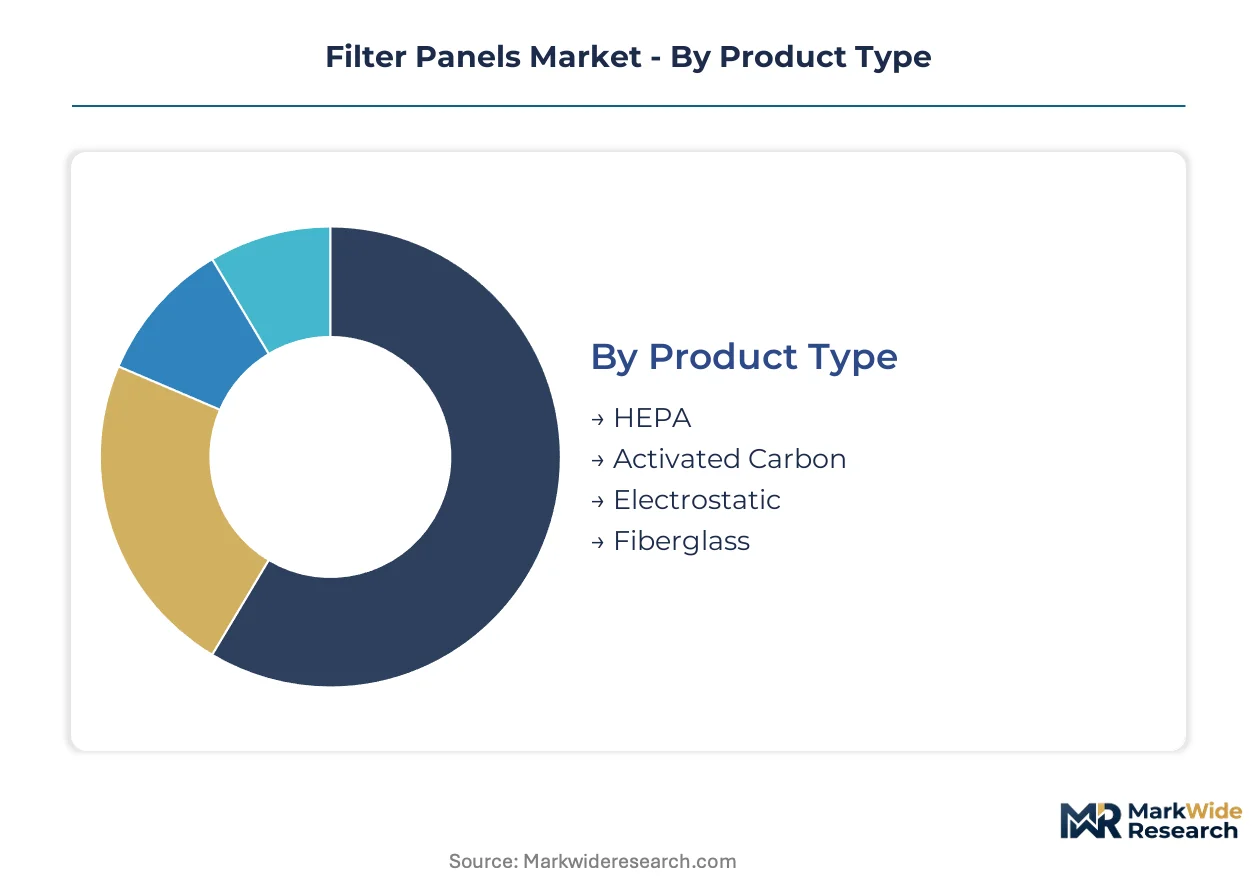
Filter panel procurement varies sharply across efficiency grades and installation environments. Semiconductor fabs in Taiwan and South Korea drive HEPA specifications while cost-sensitive manufacturing in India and Southeast Asia anchors fiberglass demand. Understanding segment boundaries clarifies where margin pools concentrate versus where volume commoditization prevails.
Product Type:
Domestic production concentrates HEPA and activated carbon supply in Germany and Japan, while electrostatic and fiberglass variants source heavily from Chinese coating facilities serving export markets.
- HEPA:Glass microfiber media pleated into aluminum or wood frames achieves 99.97% retention at 0.3 microns. Taiwan Semiconductor Manufacturing and Samsung's Pyeongtaek memory complexes mandate these specifications, straining Japanese fiber supply during foundry buildout waves.
- Activated Carbon:Impregnated carbon layers bonded to particulate substrates capture VOCs and refrigerant vapors. EU F-Gas Regulation compliance is accelerating demand from HVAC service contractors in Germany and France who retrofit commercial systems for refrigerant containment.
- Electrostatic:Washable polymer media with embedded conductive fibers serve residential and light commercial segments where disposable replacement cycles face cost pressure.
- Fiberglass:Depth-loading glass fiber mats in cardboard frames occupy cost-sensitive industrial prefiltration stages across India's textile belt and Vietnam's electronics assembly corridors.
HEPA commands the established base. The steepest expansion runs through activated carbon composites addressing dual-contaminant loads.
Application:
Cost tier separation is pronounced: cleanroom installations absorb premium pricing while HVAC retrofits compete on installed cost per square meter.
- Air Filtration:General ventilation panels rated MERV 8-13 protect equipment and occupants across commercial buildings and manufacturing floors. EPA PM2.5 enforcement is compelling healthcare facility upgrades in California and Texas where older ASHRAE 52.2 ratings no longer satisfy compliance.
- Liquid Filtration:Pleated polymer or cellulose cartridges remove particulates from process fluids in pharmaceutical manufacturing and food processing. FDA process validation requirements in Massachusetts and North Carolina biotech clusters specify documented retention ratings with batch traceability.
- HVAC Systems:Standardized panel dimensions dominate replacement demand from facility management contractors. The segment faces margin compression as German industrial buyers migrate to B2B procurement platforms that expose price transparency.
- Cleanrooms:ISO 14644-1 compliance mandates mini-pleat geometries with gel-seal or knife-edge frames. South Korea's Ministry of Trade, Industry and Energy subsidizes domestic filter panel production for semiconductor fabs, reducing import dependence.
Cleanroom applications capture premium margins. HVAC replacement volumes expand most quickly as aging commercial building stock triggers retrofit cycles.
Material:
Supply concentration shapes procurement risk: glass fiber dependence on Japanese and German producers creates allocation vulnerability during demand spikes.
- Polymer:Synthetic melt-blown or electrospun media offer tunable efficiency with lower pressure drop than glass alternatives. Pharmaceutical packaging lines in Switzerland and Ireland specify nanofiber-coated polymers for prefiltration stages where energy cost stability matters.
- Metal:Expanded aluminum or stainless steel mesh frames and support grids provide structural integrity in high-humidity or corrosive environments. Food processing facilities in Denmark and the Netherlands specify stainless housings for washdown compatibility.
- Glass Fiber:Borosilicate microfibers achieve sub-micron retention with depth-loading characteristics. Japanese producers Nippon Electric Glass and German Johns Manville control critical supply volumes, exposing assemblers to freight volatility.
- Non-Woven:Synthetic or cellulose webs thermally or mechanically bonded offer disposable economy for coarse prefiltration. China's Yangtze River Delta manufacturing corridor consumes volumes for general industrial ventilation.
Glass fiber retains the installed base. Polymer composites are gaining share fastest as energy efficiency specifications tighten.
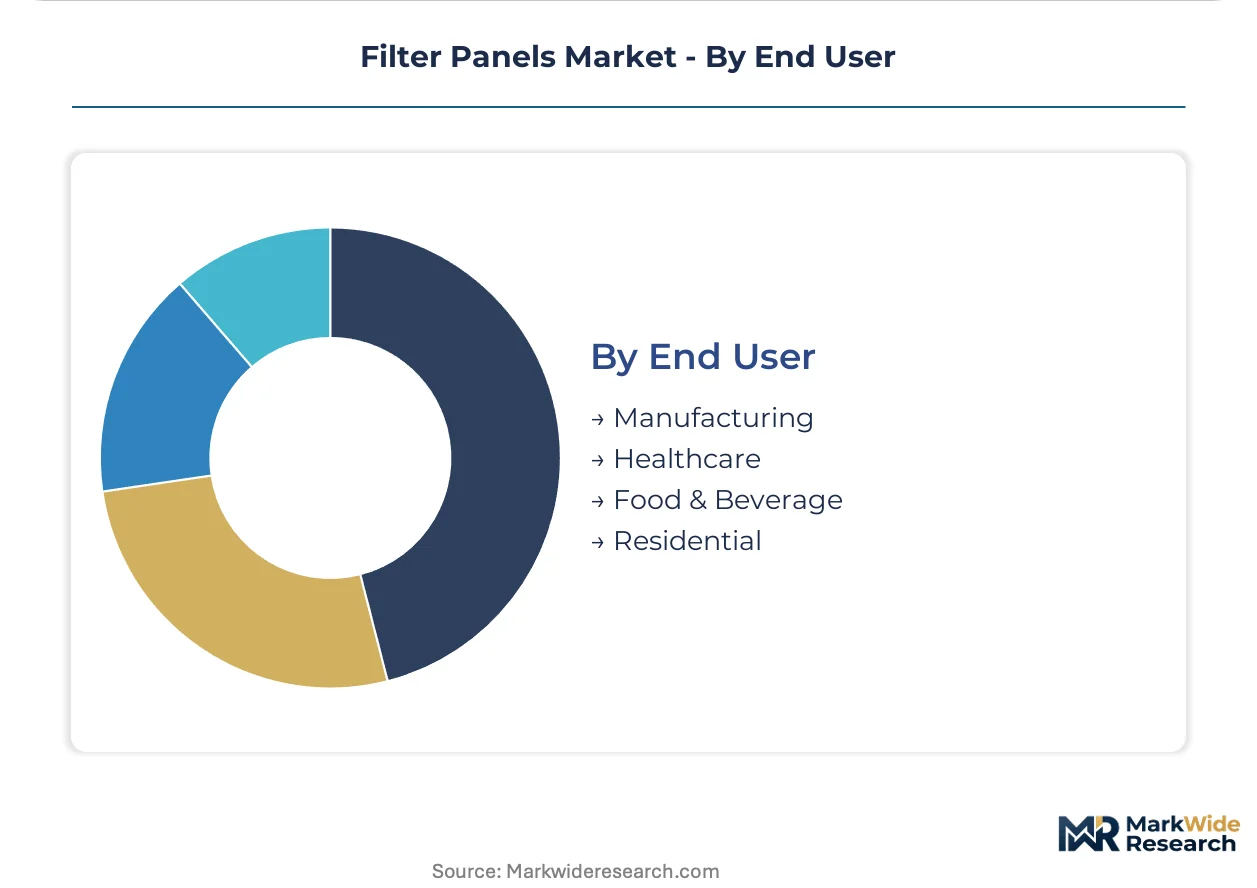
End User:
Customer type determines service model: manufacturing and healthcare sustain lifecycle contracts while residential demand fragments across retail channels.
- Manufacturing:Automotive paint booths, electronics assembly, and metalworking operations specify panels by contaminant type and process sensitivity. India's PLI scheme for electronics manufacturing is generating first-time cleanroom filtration demand in Gujarat and Karnataka.
- Healthcare:Hospital HVAC and isolation room requirements mandate HEPA terminal filtration with documented changeout protocols. UK's National Health Service facilities management departments are contracting filtration-as-a-service, shifting inventory risk to suppliers.
- Food & Beverage:Hygienic design requirements and allergen control drive specified panel selections. REACH restrictions on PFAS oil-repellent treatments are forcing accelerated replacement of legacy inventories in German and French audit regimes.
- Residential:Consumer-grade panels for home HVAC systems and standalone purifiers compete on initial purchase price. Extended-life electrostatic alternatives are capturing share from disposable panels in North American and European consumer segments.
Manufacturing absorbs the highest unit volumes. Healthcare service contract penetration is climbing fastest as procurement models shift from product to outcome-based arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: semiconductor fabs in Taiwan and South Korea absorb premium pricing without volume sensitivity, while industrial buyers in India and Southeast Asia prioritize installed cost per square meter over efficiency specifications.
United States
Healthcare facility retrofits and commercial HVAC upgrades drive procurement volumes. EPA's tightened National Ambient Air Quality Standards PM2.5 thresholds compel replacement cycles in California and Texas hospital systems. Massachusetts and North Carolina biotech clusters specify FDA-validated liquid filtration panels with batch traceability requirements.
Germany
EU F-Gas Regulation compliance accelerates activated carbon panel demand for refrigerant containment in commercial HVAC systems. REACH restrictions on PFAS oil-repellent treatments force accelerated replacement of legacy food-processing inventories. Industrial buyers in the Ruhr region migrate to B2B procurement platforms that expose price transparency and compress supplier margins.
China
Yangtze River Delta manufacturing corridor consumes fiberglass prefiltration volumes for general industrial ventilation. MEE emissions audits shutter unlicensed media coating facilities, constricting domestic supply for cost-sensitive variants. Subsidized semiconductor fabrication investments in Shanghai and Wuxi generate first-time cleanroom-grade HEPA demand.
Japan
Glass microfiber supply concentration gives domestic producers leverage over global panel assemblers during demand spikes. METI industrial standards shape procurement specifications for automotive and electronics manufacturing. Nagoya automotive paint booths and Osaka pharmaceutical packaging lines specify polymer composite prefiltration with nanofiber surface layers.
India
PLI scheme subsidies for electronics manufacturing generate cleanroom filtration demand in Gujarat and Karnataka greenfield facilities. BIS efficiency standards tighten minimum performance thresholds for commercial installations. Textile belt manufacturers in Maharashtra and Tamil Nadu prioritize disposable economy panels where replacement frequency exceeds performance sensitivity.
Filter Panels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium specifications command 3-4x pricing multiples over commodity fiberglass variants. The vendor base spans multinational filtration conglomerates with polymer media expertise, regional assemblers serving HVAC replacement channels, and specialized cleanroom-grade fabricators. Three archetypes dominate: integrated media-to-panel manufacturers controlling fiber supply, pleating specialists with mini-pleat automation, and service-contract operators owning lifecycle logistics. Consolidation pressures concentrate around ISO 16890 certification capacity and pleating equipment financing.
Among European-integrated filtration groups, Mann+Hummel and Freudenberg Filtration Technologies exemplify archetypes leveraging polymer media heritage into industrial panel applications. Donaldson Company occupies a position representing ruggedized panel design specialization for heavy manufacturing environments. These anchors demonstrate how automotive and industrial filtration legacies translate into cleanroom and commercial HVAC segment positioning.
| Leading Market Players |
|---|
| Camfil AB |
| AAF International |
| AFPRO Filtration Group |
| Mann+Hummel |
| Parker Hannifin |
| Donaldson Company |
| Freudenberg Filtration Technologies |
| Koch Filter Corporation |
| Troy Filters Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day glass microfiber lead times from Japanese and German suppliers concentrate pricing power upstream, forcing panel assemblers to absorb freight volatility or pass through cost surges to semiconductor fabs with limited alternative sourcing. This inventory exposure stratifies the market into tiers where captive fiber supply commands 3-4x multiples over import-dependent competitors serving cost-sensitive HVAC retrofits.
Pricing Analysis
Lifecycle service contracts now drive lifetime value beyond initial panel sales. Three-tier pricing structure across premium, standard, and economy levels separates gel-seal HEPA installations for semiconductor cleanrooms from cardboard-framed fiberglass variants in industrial prefiltration. Price differentiation rests on ISO 16890 certification tier and mini-pleat automation scale. Cost compression in standard-grade HVAC panels is intensifying because German industrial buyers migrate to B2B procurement platforms that expose price transparency. Residential segments exhibit highest price sensitivity; semiconductor fabs absorb premiums without volume negotiation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for glass microfiber shipments from Japan and Germany. Raw material supply concentrates in China for non-woven coating, Japan and Germany for borosilicate microfiber, and the United States for polymer melt-blown media. Critical inputs include aluminum framing extrusions, activated carbon impregnation chemicals, and pleating adhesives. Single-source vulnerability runs through Japanese specialty fiber producers who ration allocation during foundry buildout waves. Distribution runs through filtration service providers who own inventory risk and schedule replacement intervals for healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter panel demand follows semiconductor capital expenditure cycles, with Taiwan foundry buildouts and South Korea memory expansion marking the current upswing phase. Recovery durability depends on sustained cleanroom construction timelines across East Asia.
For Market Incumbents: Fortify captive supply of glass microfiber through backward integration into fiber production or long-term offtake agreements with Japanese and German producers. Invest in ISO 16890 laboratory certification capacity to clear product validation backlogs that freeze competitor introductions. Mini-pleat automation capex requirements represent a consolidation lever—acquire mid-tier assemblers unable to finance equipment upgrades independently.
For New Entrants and Emerging Players: Lifecycle logistics ownership represents a service-layer gap where incumbents under-serve hospital facilities management departments. Target filtration-as-a-service contracts in the United Kingdom and Germany where procurement models shift from product to outcome-based arrangements. Penetrate India's Gujarat and Karnataka electronics manufacturing corridors where PLI scheme subsidies generate first-time cleanroom demand without entrenched supplier relationships. Lead with direct procurement platform partnerships that compress distributor margins and accelerate customer acquisition.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-demand annuity play because EPA PM2.5 enforcement and OSHA ventilation mandates sustain aftermarket panel consumption regardless of new construction volatility. Acquisition targets should cluster around pleating specialists with mini-pleat automation and service-contract operators owning lifecycle logistics. Watch semiconductor capital expenditure announcements from Taiwan and South Korea as the demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive glass microfiber supply insulates margin from Japanese and German producer allocation rationing. |
| ISO 16890 Laboratory Certification Expansion | Testing capacity ownership accelerates product validation timelines that competitors cannot match. |
| Lifecycle Service Contract Scaling | Filtration-as-a-service models shift inventory risk upstream while locking hospital customers into recurring revenue. |
| Mini-Pleat Automation Equipment Investment | Gel-seal geometry capability qualifies suppliers for semiconductor fab specifications that command premium pricing. |
| Direct Procurement Platform Partnerships | B2B marketplace exposure captures German industrial buyers migrating away from traditional distribution layers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA enforcement records, and semiconductor capital expenditure disclosures. Primary interviews engaged cleanroom engineering directors, HVAC procurement managers at hospital systems, filtration service contract operators, and glass microfiber supply planners. Secondary validation drew from ISO 16890 test protocol documentation, MEE emissions audit records, and EU F-Gas Regulation implementation guidance. Bottom-up panel shipment data triangulates against top-down cleanroom construction spend estimates.
Segmentation dimensions modeled include efficiency grade tier, application environment, media material type, and end-user industry vertical across the projection horizon. CAGRs derive from fitted growth curves applied to disclosed foundry buildout schedules and EPA compliance retrofit mandates. Industry-specific forecast inputs incorporate semiconductor fab equipment spend patterns and REACH restriction timelines for PFAS oil-repellent treatments.
Underlying assumptions cover sustained EPA PM2.5 enforcement intensity and continued Taiwan-South Korea semiconductor capacity expansion, with deviation risk concentrated in glass microfiber supply disruption and MEE audit scope expansion in China. Practitioners should keep alternative scenarios live as ISO 16890 laboratory certification bottlenecks and electrostatic filter substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Arc Fault Detection Market