
 Photonic Sensors and Detectors Market | 2026-2036
Photonic Sensors and Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Photonic Sensors and Detectors Market Analytics
Industrial-grade precision is bifurcating the photonic sensor landscape into aerospace-qualified and consumer-tier supply streams. Hamamatsu Photonics leverages vertical integration across scintillator crystal growth and photomultiplier assembly to dominate radiation detection niches. Excelitas Technologies anchors its position through captive mercury-cadmium-telluride foundry capacity for infrared sensing. Thorlabs specializes in modular fiber-coupled sensor architectures that compete on configurability rather than unit cost.
Photonic sensors and detectors convert electromagnetic radiation across ultraviolet to terahertz bands into quantifiable electrical signals, with spectral responsivity, noise-equivalent power, and quantum efficiency defining performance boundaries. Silicon Photonic Sensors lead volume production due to CMOS compatibility, though InGaAs Detectors capture premium margin pools in short-wave infrared applications where silicon loses sensitivity beyond 1000 nanometers. Fiber Optic Sensors represent the fastest-growing product category as distributed acoustic sensing displaces conventional electrical gauges in oilfield monitoring and structural health diagnostics.
REACH restrictions on hazardous substances and the EU F-Gas Regulation constrain refrigerant-based detector cooling systems, compelling manufacturers toward thermoelectric and Stirling-cycle alternatives. FDA 510(k) pathways govern photonic diagnostic platforms in healthcare, while IEC 60825 laser safety standards shape emitter-integrated sensor designs. Stakeholders must monitor how quantum dot sensor maturation disrupts incumbent InGaAs and mercury-cadmium-telluride supply chains without overcommitting to unproven fabrication yields.
Market Dynamics
Solid-state photonic arrays are compressing component counts in automotive lidar while federal quantum photonics funding in Germany accelerates commercialization timelines for precision sensing applications.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are forcing detector cooling system redesigns toward thermoelectric alternatives, opening procurement windows for Stirling-cycle suppliers.
- Autonomous Navigation:OEM integration of solid-state photonic arrays for automotive lidar is pulling demand for compact emitter-detector modules at scale.
- German Federal Funding:Quantum photonics research clusters around Jena and Munich are compressing technology transfer timelines from laboratory to commercial deployment.
Market Restraints
- Mercury-Cadmium-Telluride Supply Concentration:Captive foundry capacity at a handful of defense contractors limits infrared detector availability for commercial buyers.
- Indium Gallium Arsenide Wafer Costs:Substrate scarcity and epitaxial growth complexity maintain premium pricing for short-wave infrared sensors beyond silicon's spectral limits.
- REACH Material Restrictions:Hazardous substance constraints on optical coatings and sensor housings force reformulation cycles that extend qualification timelines.
Strategic Opportunities
- Distributed Acoustic Sensing:Fiber optic sensor deployment in oilfield monitoring and structural health diagnostics represents underpenetrated white space in civil infrastructure.
- FDA 510(k) Pathway Expansion:Photonic diagnostic platforms in point-of-care settings benefit from streamlined premarket notification processes for optical biosensors.
- Quantum Dot Maturation:Colloidal synthesis advances are converging with CMOS readout integration to challenge incumbent InGaAs and mercury-cadmium-telluride supply chains.
Industry Challenges
- Specialized Photonics Talent Scarcity:Packaging engineers with expertise in fiber-coupled architectures and thermal management remain concentrated in legacy telecom and defense supply bases.
- IEC 60825 Certification Complexity:Laser safety standard compliance for emitter-integrated sensors requires extensive testing protocols that strain development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photonic Sensors and Detectors Market |
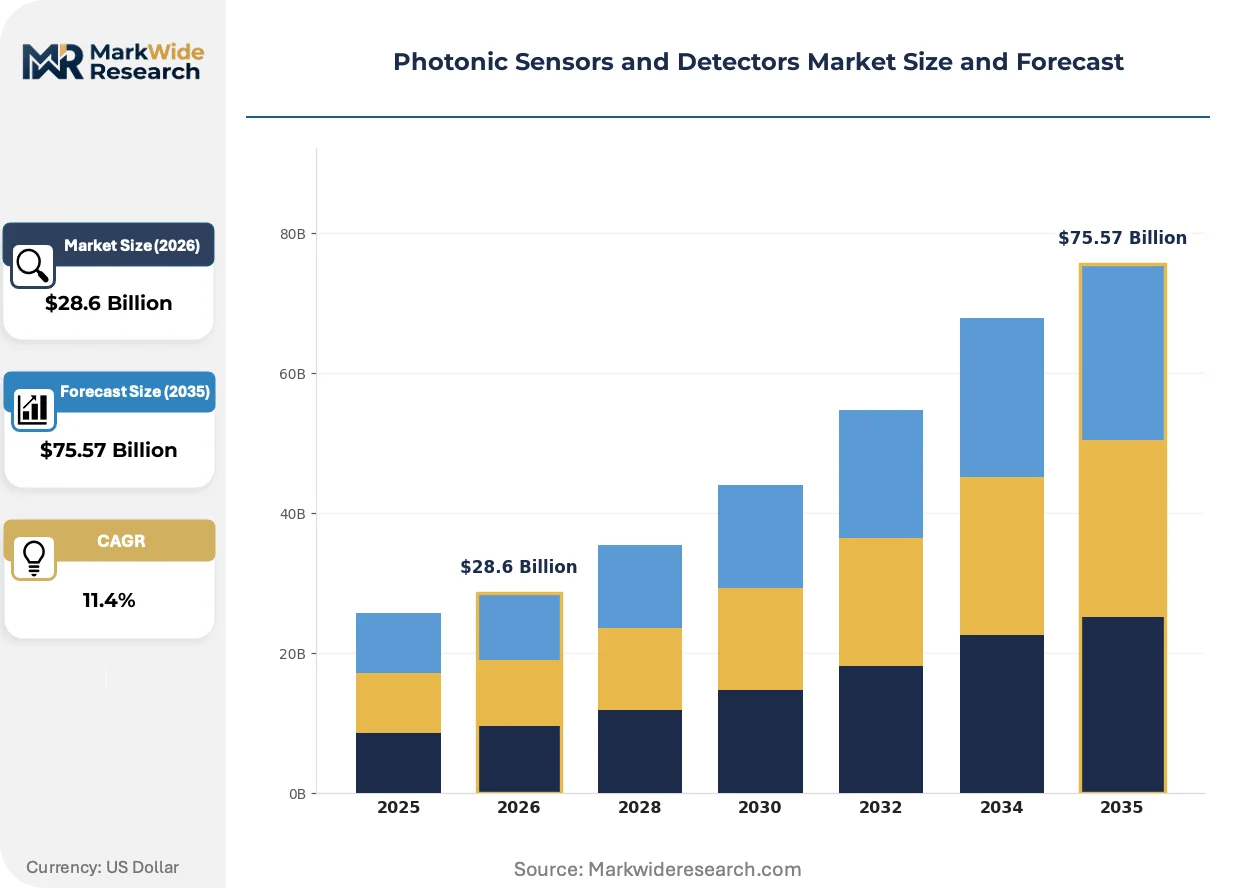
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Photonic Sensors, InGaAs Detectors, Fiber Optic Sensors, CMOS Sensors Technology: Active Sensors, Passive Sensors, Quantum Dot Sensors, Microelectromechanical Systems Application: Environmental Monitoring, Industrial Automation, Healthcare Diagnostics, Telecommunications End User: Aerospace, Automotive, Consumer Electronics, Government |
| Companies Covered | Hamamatsu Photonics, Excelitas Technologies, Thorlabs, IPG Photonics, ams-OSRAM AG, ON Semiconductor, STMicroelectronics N.V., Honeywell International Inc., Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photonic Sensors and Detectors Market Evolving Landscape
Photonic sensor architectures are fragmenting along precision-grade boundaries while regulatory material constraints and procurement model evolution reshape competitive positioning across end-use verticals.
Silicon photonics is decomposing traditional discrete component assemblies into integrated photonic circuits. Automotive lidar developers are adopting co-packaged laser and detector arrays to reduce assembly complexity. This integration is decomposing the historical separation between emitter manufacturing and detector module assembly, compressing supply chain tiers.
REACH compliance frameworks are tightening specifications for sensor housings and optical coatings across European manufacturing. Material substitution mandates are accelerating qualification programs for halogen-free and brominated-flame-retardant alternatives. German precision optics clusters are responding with captive chemical analysis capabilities to maintain export eligibility.
Specification-driven procurement is consolidating buying power among tier-one automotive and aerospace OEMs. Long-term supply agreements with technical performance clauses are displacing spot-market purchasing for high-reliability photonic components. This shift is most visible in German and Japanese automotive supply chains where lidar qualification cycles demand vendor lock-in.
Photonic Sensors and Detectors Market Segmentation
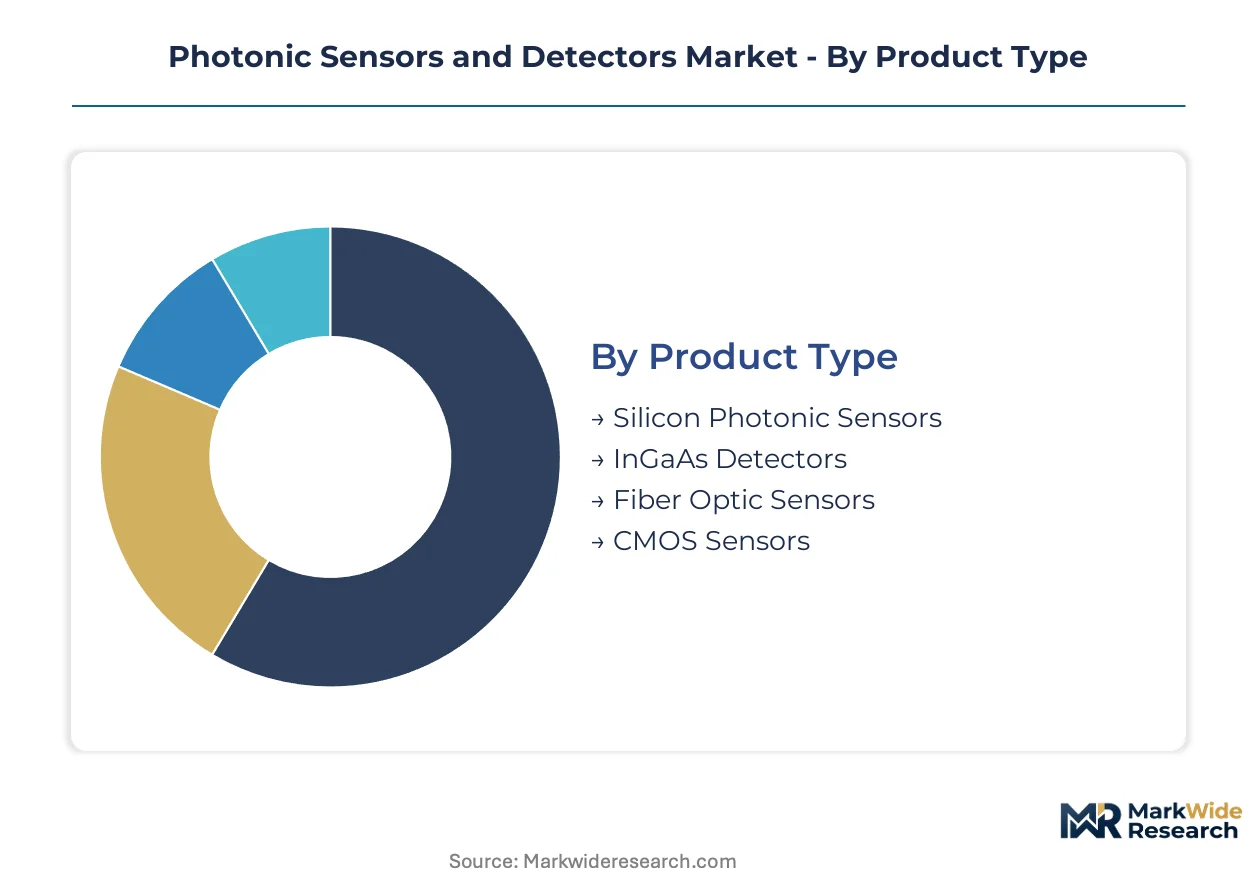
Photonic sensor procurement channels diverge sharply between high-reliability aerospace qualification streams and high-volume consumer electronics distribution. Understanding which segments flow through defense contractors versus mass-market distributors determines margin capture and inventory risk exposure.
Product Type:
Silicon Photonic Sensors dominate CMOS-compatible foundry output, while InGaAs and fiber optic variants command premium positioning through specialized distribution networks.
- Silicon Photonic Sensors:These devices leverage standard semiconductor fabrication, enabling wafer-scale integration with electronic readout circuits. German automotive lidar developers and Taiwanese consumer electronics assemblers absorb the majority of volume output from 200mm and 300mm foundries.
- InGaAs Detectors:Epitaxial growth on indium phosphide substrates extends spectral sensitivity to 1700 nanometers for short-wave infrared applications. Defense imaging contracts in the United States and satellite payload manufacturers in France sustain pricing premiums despite substrate scarcity.
- Fiber Optic Sensors:Distributed acoustic sensing deployments in Norwegian subsea oilfields and Japanese railway infrastructure drive specialty cable procurement.
- CMOS Sensors:Image sensor foundries in South Korea and Japan supply smartphone camera modules and machine vision systems through tier-one electronics distributors.
By volume, Silicon Photonic Sensors leads. By growth pace, Fiber Optic Sensors is expanding most quickly.
Technology:
Cost tiers separate mature active and passive architectures from emerging quantum dot and MEMS platforms still seeking fabrication yield parity.
- Active Sensors:Integrated emitter-detector pairs with onboard signal conditioning dominate automotive lidar and industrial ranging applications. German OEM qualification programs lock in multi-year supply agreements with tier-one module suppliers.
- Passive Sensors:These devices rely on external illumination, reducing unit cost and power consumption for ambient light monitoring and simple proximity detection. Chinese smartphone manufacturers and Japanese appliance producers specify these for cost-sensitive consumer tiers.
- Quantum Dot Sensors:Colloidal synthesis on silicon readout circuits promises CMOS-compatible infrared detection without exotic substrates.
- Microelectromechanical Systems:MEMS-based optical switches and tunable filters serve telecommunications wavelength management and LiDAR beam steering.
Active Sensors capture the largest revenue pool. Quantum Dot Sensors show the steepest expansion trajectory as fabrication yields improve.
Application:
Customer type segmentation reveals divergent procurement patterns between specification-driven government buyers and price-sensitive industrial integrators.
- Environmental Monitoring:Spectrometric and radiometric sensors track atmospheric composition and water quality parameters. European Space Agency satellite programs and United States EPA air quality networks sustain demand for calibrated, traceable instrumentation.
- Industrial Automation:Machine vision, displacement interferometry, and laser triangulation systems enable precision manufacturing and robotic guidance. German automotive assembly lines and Japanese electronics factories drive replacement cycles for 3D sensing modules.
- Healthcare Diagnostics:Optical coherence tomography and fluorescence-based assays require FDA 510(k) clearance pathways.
- Telecommunications:Dense wavelength division multiplexing depends on photodiode arrays and optical channel monitors for signal integrity management.
Industrial Automation generates the highest unit volume. Healthcare Diagnostics is gaining share fastest as point-of-care platforms proliferate.
End User:
Supply concentration varies dramatically between captive defense production and fragmented consumer electronics assembly.
- Aerospace:Radiation-hardened and extreme-temperature-qualified sensors serve satellite payloads, aircraft flight control, and space telescopes. NASA and ESA mission specifications drive qualification protocols that exclude commercial-grade alternatives.
- Automotive:Solid-state lidar and driver monitoring systems integrate photonic arrays for autonomous navigation and cabin sensing. German and Japanese OEMs consolidate procurement through tier-one module suppliers with dedicated automotive quality certifications.
- Consumer Electronics:Smartphone cameras, biometric authentication, and ambient sensing modules ship in billion-unit annual volumes.
- Government:Military imaging, border surveillance, and scientific research programs sustain specialized production lines with restricted export controls.
Consumer Electronics dominates unit shipments. Automotive is climbing the fastest as lidar penetration accelerates through model year refreshes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in photonic sensors and detectors tilt toward net exporters with precision manufacturing bases, while import-dependent economies concentrate in final assembly and system integration. Germany and the United States maintain structural surpluses in high-reliability components, whereas China and South Korea dominate volume production for consumer-tier applications.
Germany
Automotive lidar qualification programs at BMW and Mercedes-Benz pull demand for solid-state photonic arrays through tier-one module suppliers. The EU F-Gas Regulation accelerates thermoelectric cooling system redesigns among Jena-based precision optics manufacturers. Federal quantum photonics funding compresses technology transfer timelines from Fraunhofer institutes to commercial deployment in Munich and Berlin-Brandenburg clusters.
United States
Defense imaging contracts and NASA satellite payloads sustain demand for radiation-hardened mercury-cadmium-telluride detectors with restricted export controls. FDA 510(k) pathways govern photonic diagnostic platforms in point-of-care settings, particularly in Greater Boston and San Diego biomedical corridors. Silicon photonics foundries in Arizona and Oregon supply emitter-detector modules for automotive lidar developers.
China
Machine vision deployment in electronics assembly and smartphone camera module production absorbs CMOS sensor output from foundries in Shanghai and Shenzhen. MIIT standards for industrial automation equipment shape procurement specifications for fiber optic sensors in Yangtze River Delta manufacturing zones. Domestic substitution programs target InGaAs detector supply chains currently dominated by Japanese and European sources.
Japan
Automotive tier-one suppliers consolidate procurement of compact photonic modules for driver monitoring systems through long-term agreements with METI-backed manufacturing consortia. JIS standards for optical channel monitors govern telecommunications equipment procurement. Hamamatsu and Nagoya precision optics clusters maintain captive scintillator crystal growth capacity for radiation detection applications.
South Korea
Smartphone camera module assemblers in Gyeonggi Province drive billion-unit annual demand for CMOS image sensors from domestic foundries. National semiconductor R&D programs target silicon photonics integration for next-generation lidar systems. Seoul-based electronics distributors manage inventory risk for consumer-tier photonic components flowing into Chinese final assembly.
Photonic Sensors and Detectors Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and qualification timelines, creating a tiered structure where public companies scale through foundry partnerships while private firms defend niche margins through captive process technology. The vendor base separates into three strategic archetypes: diversified semiconductor conglomerates with photonic divisions, pure-play sensor specialists with vertical process control, and modular component suppliers competing on configurability. Dominant competitive moves include backward integration into epitaxial wafer growth and strategic partnerships with automotive tier-one module suppliers.
Among Japanese precision optics manufacturers, Hamamatsu Photonics and Omron Corporation exemplify the specialist archetype with concentrated expertise in radiation detection and industrial sensing applications. Excelitas Technologies occupies a position within the North American defense-aerospace supply tier, reflecting the captive foundry capacity structure that limits commercial infrared detector availability. Thorlabs represents the modular configurability vector, competing through fiber-coupled architectures rather than unit cost scale.
| Leading Market Players |
|---|
| Hamamatsu Photonics |
| Excelitas Technologies |
| Thorlabs |
| IPG Photonics |
| ams-OSRAM AG |
| ON Semiconductor |
| STMicroelectronics N.V. |
| Honeywell International Inc. |
| Omron Corporation |
| Others |
Value Network & Pricing Analysis
Long-term supply agreements with technical performance clauses lock in both supply access and price visibility for automotive lidar developers, compressing procurement windows for tier-one module suppliers while insulating qualified vendors from spot-market volatility. German OEM qualification programs tether pricing to multi-year offtake commitments, whereas consumer electronics buyers absorb CMOS sensor pricing through tier-one electronics distributors managing inventory risk.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with aerospace-qualified sensors commanding substantial premiums over consumer-tier alternatives due to extended qualification timelines and traceability requirements. Price differentiation rests on certification grade—ISO 9001 and IATF 16949 tiers separate automotive-qualified modules from industrial-grade alternatives—and volume scale, with billion-unit smartphone camera contracts compressing per-unit costs below precision sensing tiers. Cost compression in consumer-tier silicon photonic sensors is intensifying because foundry capacity expansion outpaces demand absorption. Consumer electronics assemblers exhibit the highest price sensitivity, while government buyers prioritize performance specifications over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for CMOS-compatible photonic sensors, while Germany and the United States concentrate precision optics manufacturing and radiation-hardened detector assembly. Raw material dependencies draw from indium phosphide substrates for InGaAs epitaxial growth, scintillator crystals for radiation detection, and specialty optical glass for sensor housings. Single-source vulnerability permeates mercury-cadmium-telluride foundry capacity, with captive production lines at defense contractors limiting commercial availability. Distribution runs through tier-one automotive module suppliers for lidar components and specialized photonics distributors for research-grade instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonic sensor platforms are approaching an interoperability inflection where silicon photonics integration decomposes discrete component supply chains into co-packaged emitter-detector ecosystems, compressing vendor tiers and reshaping procurement relationships.
For Market Incumbents: Secure captive epitaxial wafer growth capacity to defend margin position against quantum dot sensor substitution threatening InGaAs and mercury-cadmium-telluride supply chains. Deepen automotive tier-one module supplier relationships through dedicated foundry capacity reservations, as OEM qualification cycles create vendor lock-in that excludes second-source alternatives. For New Entrants and Emerging Players: Lead with distributed acoustic sensing deployments in civil infrastructure monitoring, where fiber optic sensor penetration remains underdeveloped relative to oilfield applications. Target Japanese railway infrastructure and European bridge structural health diagnostics through specialty cable procurement partnerships, leveraging configurability advantages against incumbent unit-cost scale. For Investors and Strategic Acquirers: Modular component suppliers with fiber-coupled architecture expertise present acquisition targets positioned to capture configurability premiums as silicon photonics integration fragments traditional supply tiers. Long-term viability hinges on CMOS readout circuit integration capabilities across the analysis window. Monitor quantum dot fabrication yield improvements as the signal indicating incumbent detector technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Growth | Captive indium phosphide substrate supply insulates InGaAs detector margins from substrate scarcity. |
| Automotive Tier-One Module Partnership | Long-term supply agreements with BMW and Mercedes-Benz procurement lock in lidar volume commitments. |
| Quantum Dot Sensor Platform Launch | Colloidal synthesis advances on silicon readout circuits challenge incumbent infrared detector supply chains. |
| Distributed Acoustic Sensing Expansion | Fiber optic sensor deployment in Norwegian subsea oilfields and Japanese railway infrastructure accelerates specialty cable procurement. |
| Thermoelectric Cooling System Redesign | EU F-Gas Regulation compliance opens procurement windows for Stirling-cycle alternatives to refrigerant-based cooling. |
Research Methodology
Cross-validation between primary interviews with photonic sensor procurement managers, automotive platform engineers, and precision optics manufacturing directors and secondary sources including SEC filings, ECHA REACH registration databases, and customs trade data anchors the qualitative findings. Bottom-up triangulation across foundry output estimates, tier-one module supplier capacity disclosures, and OEM bill-of-materials analysis converges with top-down macroeconomic drivers. Primary fieldwork with Fraunhofer institute technology transfer officers and German federal funding program administrators validates commercialization timeline assumptions.
Sensitivity analysis across the projection horizon tests demand elasticity for automotive lidar penetration rates, quantum dot sensor yield improvement trajectories, and fiber optic sensor substitution in structural health monitoring. Segmentation dimensions modeled include product type, technology maturity tier, application vertical, and end-user procurement pattern. CAGRs derive from regression analysis against historical foundry capacity expansion, regulatory compliance cost trajectories, and technology transfer velocity from research clusters to commercial deployment.
Forecasts assume regulatory continuity in EU REACH and F-Gas Regulation regimes; material policy shifts tightening hazardous substance constraints or accelerating refrigerant phase-downs would require re-modeling. Technology disruption risk from quantum dot maturation and supply concentration vulnerability in mercury-cadmium-telluride foundry capacity represent primary forecast revision triggers. Recalibration cycles align with material shifts in German quantum photonics funding allocations, automotive lidar platform standardization decisions, and foundry yield disclosures for emerging sensor architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Weather Radar Market