
 Indeflator Devices Market | 2026-2036
Indeflator Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Indeflator Devices Market Foresight
Market Context
Hospital systems is rotating toward automated indeflator platforms as surgical centers scale back capital spending on legacy manual units. Medtronic plc leverages its integrated cath lab ecosystem to bundle indeflator sales with balloon catheter contracts. Boston Scientific Corporation anchors its position through R&D intensity focused on pressure-feedback algorithms. Teleflex Incorporated competes via specialized distribution channels in North American academic medical centers.
Technical Definition and Segment Structure
Indeflator devices are precision pressure-control instruments designed to inflate and deflate medical balloons during interventional procedures, typically operating within calibrated ranges of 1-30 atmospheres with digital or analog pressure feedback. These instruments serve primarily to ensure controlled dilation during angioplasty, stent deployment, and urological stricture management. Balloon catheters command the largest revenue pool due to recurring procedural consumption, while electromechanical systems represent the fastest-expanding technology segment as clinicians prioritize pressure accuracy and reduced operator variability. Disposable devices capture expanding share in infection-sensitive settings, though reusable manual systems retain dominance in cost-constrained surgical centers.
Regulatory Frame and Outlook
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for indeflator manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety protocols further constrain design choices for electromechanical platforms. Stakeholders must monitor evolving notified body capacity in Europe and FDA digital health guidance for pressure-sensor software to anticipate compliance cost trajectories and competitive positioning shifts.
Market Dynamics
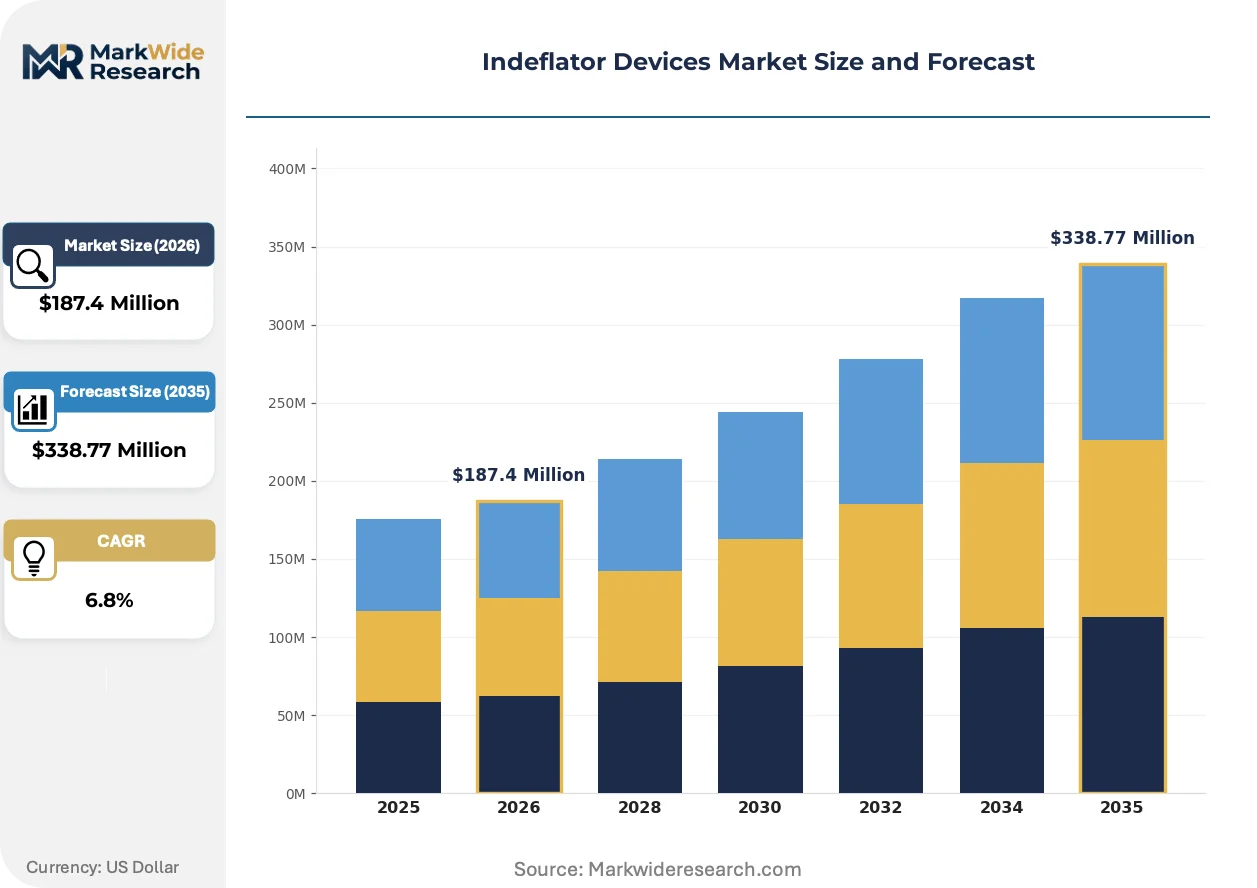
Electromechanical inflation systems are displacing manual indeflator units across cath lab networks as cardiovascular procedural volumes concentrate in high-throughput hospital systems. This technology rotation compresses capital equipment replacement cycles while elevating pressure calibration standards for interventional suites.
Growth Catalysts
- EU MDR compliance deadlines:European notified body capacity constraints are accelerating hospital procurement of certified electromechanical platforms ahead of technical documentation submission requirements.
- Angioplasty volume concentration:United States hospital systems are consolidating interventional cardiology services into hub-and-spoke networks that favor standardized, automated inflation equipment.
- Digital pressure feedback integration:Real-time sensor algorithms are reducing operator variability during stent deployment, driving cath lab preference for precision-controlled systems.
Market Restraints
- Silicon pressure sensor supply:Concentrated sourcing from East Asian semiconductor foundries exposes manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) pathway friction:Software-as-medical-device classification for pressure-feedback algorithms extends clearance timelines and elevates legal compliance expenditure.
- Manual unit longevity:Durable mechanical indeflators in cost-constrained surgical centers resist replacement, compressing addressable market expansion in outpatient settings.
Strategic Opportunities
- Japanese super-aging infrastructure:METI-funded hospital modernization programs create procurement windows for electromechanical platforms in peripheral vascular intervention suites.
- Remote pressure monitoring convergence:Integration of indeflator telemetry with cath lab information systems enables procedure documentation automation and quality analytics.
- Disposable channel innovation:Infection-sensitive ambulatory surgical centers are adopting single-use inflation syringes through specialized distributor networks.
Industry Challenges
- Biomedical engineering talent scarcity:Electromechanical system maintenance requires specialized technicians that hospital systems struggle to recruit and retain.
- Legacy cath lab integration:New pressure-control platforms must interface with proprietary balloon catheter protocols from incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indeflator Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Inflation Devices, Accessories, Delivery Systems Application: Cardiovascular Procedures, Urological Treatments, Gastrointestinal Use, Peripheral Interventions End User: Hospitals, Surgical Centers, Specialty Clinics, Research Institutions Technology: Manual Inflation, Automatic Inflation, Electromechanical Systems, Disposable Devices |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Teleflex Incorporated, Merit Medical Systems, Cook Medical, Terumo Corporation, Abbott Laboratories, Becton, Dickinson and Company, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indeflator Devices Market Shifts & Advancements
Software-defined pressure control is fragmenting traditional hardware-centric competitive positioning. Vendors now differentiate through algorithmic accuracy and data integration rather than mechanical reliability alone.
MEMS-based pressure sensing is fragmenting conventional analog gauge architectures. These microelectromechanical systems deliver sub-atmosphere resolution for delicate urological and neurovascular procedures. Academic medical centers in Germany and Japan are piloting MEMS-integrated platforms for complex interventions. The technology is fragmenting price-performance curves across premium and mid-tier product tiers.
EU MDR Annex XIV clinical evaluation requirements are compressing product development timelines for electromechanical indeflators. Manufacturers must generate post-market clinical follow-up data for pressure-safety claims. Class IIa device reclassification is forcing European market entrants to establish notified body relationships earlier in development cycles.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts. Third-party technical service providers are capturing maintenance revenue previously retained by original equipment manufacturers. This pattern is most visible in United States health system purchasing where GPO-negotiated agreements separate warranty terms from service level commitments.
Indeflator Devices Market Segmentation
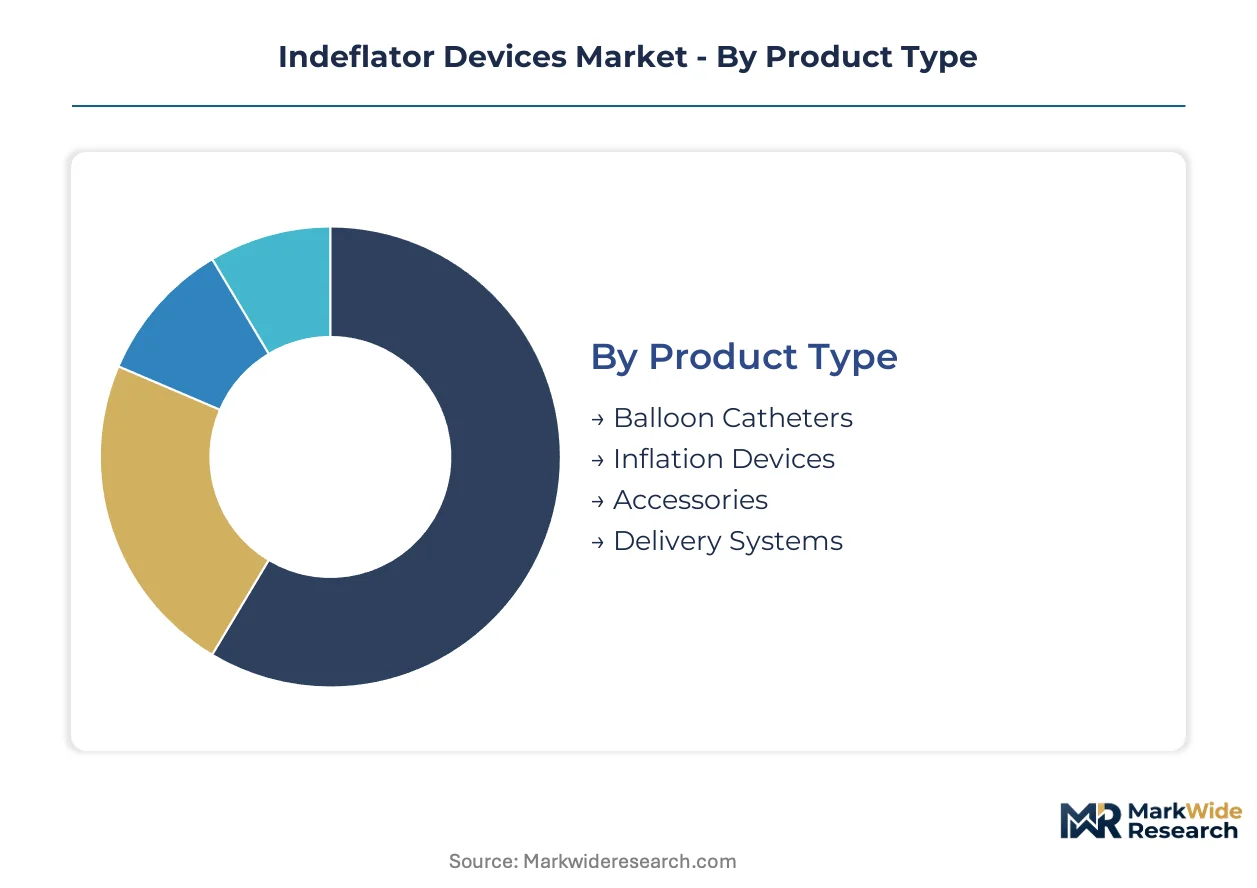
Indeflator device segmentation reveals how regulatory pathways, clinical settings, and technology maturity create distinct commercial battlegrounds. Each dimension carries unique margin profiles and compliance burdens that shape vendor strategy.
Product Type:
FDA 510(k) clearance complexity varies sharply across product categories, with electromechanical platforms facing software-as-medical-device scrutiny while manual units navigate simpler mechanical device pathways.
- Balloon Catheters:Polymer-based dilation instruments with integrated inflation lumens, calibrated for 1-30 atmosphere pressure ranges. Demand concentrates in United States hospital cath labs where cardiovascular procedure volumes are consolidating into hub-and-spoke networks, driving recurring consumption that anchors manufacturer revenue streams.
- Inflation Devices:Precision pressure-control instruments with digital or analog feedback mechanisms. United States academic medical centers are standardizing on automated platforms to reduce operator variability during stent deployment, compressing replacement cycles for legacy manual units.
- Accessories:Pressure tubing, stopcocks, and connection adapters with ISO 80369 small-bore compatibility.
- Delivery Systems:Integrated catheter-indeflator combinations for complex peripheral vascular interventions.
Balloon catheters handle the majority of throughput; inflation devices are expanding most quickly on share as cath labs automate.
Application:
Clinical indication determines reimbursement intensity and capital equipment requirements, with cardiovascular suites commanding premium pricing against cost-sensitive urology settings.
- Cardiovascular Procedures:Angioplasty and stent deployment in coronary and peripheral vessels. Germany and Japan are expanding cath lab infrastructure under hospital modernization programs, creating procurement windows for pressure-calibrated electromechanical systems.
- Peripheral Interventions:Lower-extremity and carotid artery dilation procedures. United States outpatient surgical centers are adopting disposable inflation syringes to manage infection risk in cost-constrained environments.
- Urological Treatments:Stricture dilation and stone manipulation with sub-atmosphere pressure precision.
- Gastrointestinal Use:Esophageal and biliary stricture management via endoscopic delivery.
Cardiovascular procedures dominate absolute volume; peripheral interventions are gaining share fastest as outpatient capacity expands.
End User:
Procurement authority and service infrastructure requirements fragment the customer base across integrated delivery networks and independent surgical facilities.
- Hospitals:High-throughput interventional suites with dedicated biomedical engineering staff. United States health systems are unbundling after-sales service from capital contracts, enabling third-party technical providers to capture maintenance revenue.
- Surgical Centers:Ambulatory facilities prioritizing disposable devices to minimize sterilization overhead and capital commitment.
- Specialty Clinics:Cardiology and urology practices with limited cath lab infrastructure.
- Research Institutions:Academic centers piloting MEMS-integrated platforms for novel interventional protocols.
Hospitals absorb the bulk of electromechanical system shipments; surgical centers are climbing fastest as outpatient migration accelerates.
Technology:
EU MDR Annex XIV clinical evaluation requirements are compressing development timelines, with Class IIa reclassification forcing earlier notified body engagement for software-integrated platforms.
- Electromechanical Systems:Automated inflation platforms with real-time pressure feedback algorithms. Japanese METI-funded hospital modernization is creating procurement windows as super-aging infrastructure demands precision control for complex interventions.
- Disposable Devices:Single-use inflation syringes and pressure systems for infection-sensitive settings. United States ambulatory surgical centers are adopting these through specialized distributor networks to minimize cross-contamination risk.
- Manual Inflation:Mechanical syringe-based systems with analog pressure gauges.
- Automatic Inflation:Pre-programmed pressure cycle devices for standardized dilation protocols.
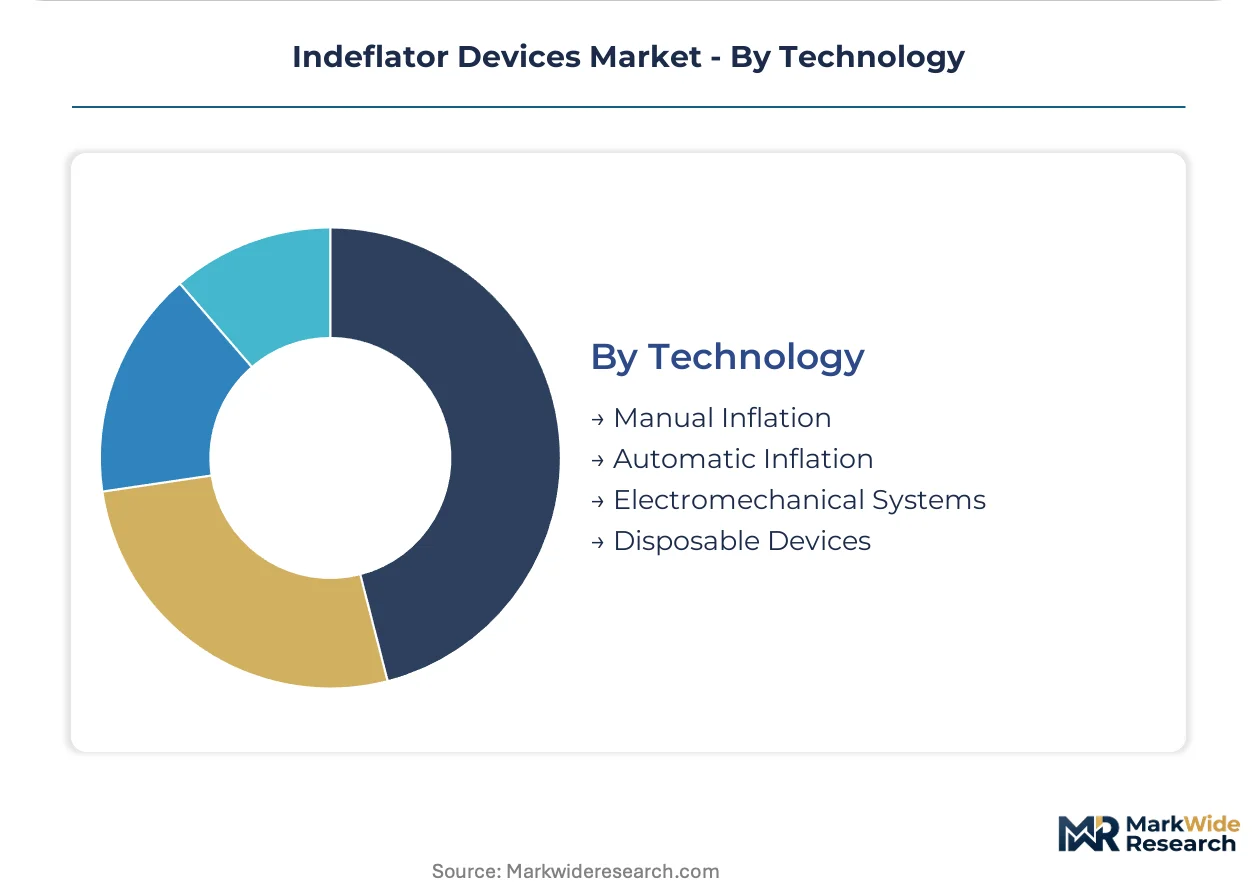
Manual systems still handle baseline procedural volume; electromechanical platforms are ascending fastest as calibration standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of electromechanical indeflator systems concentrates in the United States, Germany, and Japan where cath lab infrastructure density supports precision medical device production. FDA 510(k) clearance pathways in the United States and EU MDR technical documentation requirements in Germany create divergent compliance cost structures. Hospital procurement committees in these markets favor automated pressure-control platforms as cardiovascular procedural volumes consolidate into high-throughput networks.
United States
Hospital systems are consolidating interventional cardiology services into hub-and-spoke networks that demand standardized electromechanical inflation equipment. FDA software-as-medical-device classification for pressure-feedback algorithms extends clearance timelines for new entrants. The Cleveland Clinic and Mayo Clinic anchor cath lab standardization efforts across Midwest academic medical centers.
Germany
EU MDR Annex XIV clinical evaluation requirements are compressing product development timelines for electromechanical indeflators entering European markets. Notified body capacity constraints in Berlin and Munich are accelerating hospital procurement of certified platforms ahead of submission deadlines. The Medical Valley cluster around Erlangen drives MEMS pressure sensor integration for neurovascular applications.
Japan
METI-funded hospital modernization programs are creating procurement windows for precision-controlled indeflator systems as super-aging infrastructure demands complex peripheral vascular interventions. PMDA review pathways for software-integrated devices maintain rigorous quality benchmarks. The Kobe and Osaka medical device corridors concentrate electromechanical system manufacturing for Asia-Pacific distribution.
China
NMPA medical device registration requirements are elevating barriers for imported electromechanical indeflators while domestic manufacturers scale production of manual inflation systems. Local hospital procurement favors cost-calibrated platforms for tier-two and tier-three city cath labs. The Suzhou and Shenzhen industrial zones anchor balloon catheter and inflation device component supply chains.
India
CDSCO medical device rules are tightening quality benchmarks for imported electromechanical systems while cost-constrained surgical centers retain manual indeflator units. Hospital infrastructure expansion in Delhi-NCR and Mumbai concentrates demand for disposable inflation syringes in infection-sensitive settings. The Andhra Pradesh medical device park near Visakhapatnam attracts component assembly operations for regional supply.
Indeflator Devices Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage integrated cath lab ecosystems to bundle indeflator sales with balloon catheter contracts. The vendor base spans three strategic tiers: multinational platform suppliers with full interventional portfolios, specialized pressure-control instrument manufacturers, and regional disposable device fabricators. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and portfolio diversification into MEMS-integrated platforms for delicate urological procedures.
Among diversified medical technology conglomerates, Medtronic plc and Boston Scientific Corporation exemplify platform suppliers that anchor market positioning through integrated cath lab ecosystems. Teleflex Incorporated occupies a specialized position within North American academic medical center distribution channels. These three entities represent distinct competitive archetypes: ecosystem bundling, R&D-intensive algorithm development, and channel-specialized service models.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Merit Medical Systems |
| Cook Medical |
| Terumo Corporation |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
MEMS-based pressure sensor substitution for legacy analog gauges simultaneously shifts component sourcing toward East Asian semiconductor foundries and compresses margin structures for mid-tier electromechanical platforms. This input transition concentrates pricing power with sensor suppliers while forcing indeflator manufacturers to absorb calibration-certification costs or cede share to manual-system incumbents.
Pricing Analysis
FDA 510(k) software-as-medical-device classification dictates the pricing tier structure across electromechanical indeflator platforms, separating premium FDA-cleared systems with algorithmic pressure feedback from standard manual units and economy disposable syringes. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling, with academic medical centers least sensitive and cost-constrained outpatient surgical centers most responsive to unit economics. Pricing pressure stems from silicon sensor input cost volatility, compressing margins for mid-tier manufacturers lacking backward integration into pressure-transducer supply.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from East Asian semiconductor hubs periodically disrupt just-in-time delivery schedules for MEMS pressure sensor modules. Component sourcing concentrates in Taiwan, South Korea, and Japan for precision sensors, with Germany and the United States anchoring final electromechanical assembly operations. The supply chain rests on concentrated silicon wafer foundry capacity and proprietary balloon-catheter interface protocols, exposing manufacturers to single-source vulnerability for FDA-validated sensor calibrations. Distribution runs through specialized medical device distributors serving hospital purchasing committees and GPO-negotiated agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The indeflator devices market exhibits cyclical recovery characteristics as hospital capital expenditure cycles normalize following cath lab infrastructure consolidation. Cardiovascular procedural volume concentration into hub-and-spoke networks drives replacement demand for automated platforms.
For Market Incumbents: Secure notified body relationships ahead of EU MDR Annex XIV clinical evaluation deadlines to defend European market access against emerging MEMS-integrated competitors. Anchor backward integration into pressure sensor calibration capabilities to offset silicon foundry pricing volatility and preserve margin structures across mid-tier product lines. For New Entrants and Emerging Players: After-sales service unbundling from capital equipment contracts creates white-space opportunities for third-party technical service providers capturing maintenance revenue from United States health systems. Target disposable inflation syringe penetration in infection-sensitive ambulatory surgical centers through specialized distributor partnerships, leveraging lower FDA clearance barriers versus electromechanical platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized pressure-control instrument manufacturers lacking integrated cath lab ecosystems. Five-to-ten year viability hinges on software-defined pressure control differentiation and MEMS sensor integration capabilities. Monitor FDA digital health guidance publication as inflection signal for algorithm-intensive platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Classification Pathway | Accelerates clearance timelines for pressure-feedback algorithms in electromechanical platforms. |
| EU MDR Notified Body Engagement | Secures European market access ahead of Annex XIV clinical evaluation deadlines. |
| Hospital System Partnership | Locks in standardized procurement across hub-and-spoke cardiovascular networks. |
| MEMS Sensor Integration Program | Enables sub-atmosphere precision for neurovascular and urological intervention suites. |
| Reimbursement Strategy Development | Aligns electromechanical platform adoption with CMS procedure coding updates. |
Research Methodology
The analysis maps electromechanical systems, manual inflation devices, disposable syringes, and integrated delivery platforms, each validated through cath lab directors, hospital purchasing committee members, biomedical engineering managers, and GPO contracts specialists. Primary intelligence combines structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up shipment estimates triangulate with top-down cardiovascular procedure volume benchmarks.
Consistency checks against external cardiovascular intervention databases and cath lab capital expenditure surveys validate volume and value outputs across the projection horizon. Segmentation dimensions model product type, application indication, end-user facility category, and technology architecture. CAGRs derive from fitted growth curves applied to procedural volume trajectories and equipment replacement cycle assumptions, incorporating PMDA review timeline data and METI hospital modernization program disbursement schedules as Japan-specific inputs.
Underlying assumptions cover stable FDA software-as-medical-device classification interpretation, EU notified body capacity recovery, and silicon sensor supply normalization, with deviation risk concentrated in East Asian semiconductor trade policy shifts and cardiovascular service line consolidation pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Signaling Devices Market