
 Global Non-Destructive Testing and Inspection Market | 2026-2036
Global Non-Destructive Testing and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Destructive Testing and Inspection Market Foresight
Aerospace manufacturing is shifting toward more stringent in-service inspection protocols for composite structures and additive-manufactured components. SGS SA leverages its global laboratory network to anchor certification workflows across aviation supply chains. Bureau Veritas competes through marine and energy sector specialization, while Waygate Technologies dominates industrial radiography with digital detector arrays.
Non-destructive testing and inspection encompasses methods that evaluate material integrity, geometric conformity, and structural performance without impairing future usability, employing techniques such as ultrasonic wave propagation at frequencies from 0.1 to 25 MHz or X-ray attenuation measured in keV ranges to identify subsurface discontinuities. Ultrasonic testing leads in revenue contribution due to its versatility across metals, composites, and welded joints, whereas eddy current testing captures expanding share in aerospace tube and fastener inspection where conductivity differentials reveal fatigue cracks. Infrared thermography grows fastest among inspection types as passive thermography and active pulse methods penetrate civil infrastructure monitoring for delamination and moisture ingress detection.
FAA airworthiness directives and EASA certification memoranda mandate recurrent NDT for commercial aircraft structures, while OSHA process safety management rules and EPA leak detection requirements enforce periodic inspection cycles across US refineries and chemical plants. China's SAMR enforces GB standards for pressure equipment and elevator safety ropes, creating parallel compliance demand for radiographic and magnetic particle testing services. Stakeholders must monitor divergence between regional certification reciprocity agreements and emerging digital qualification standards for automated ultrasonic and phased-array systems.
Market Dynamics
Phased-array ultrasonic systems are compressing inspection cycle times for composite airframes while regulatory divergence between FAA airworthiness directives and China's GB standards forces service providers to maintain parallel certification workflows.
Growth Catalysts
- EU Pressure Equipment Directive updates:Tighter compliance mandates for pressure vessels across Germany, France, and Italy are expanding contracted inspection volumes for radiographic and ultrasonic testing services.
- Composite airframe penetration:Boeing and Airbus production ramps for carbon-fiber primary structures are accelerating demand for subsurface flaw detection using high-frequency ultrasonic arrays.
- Industrial clustering:Munich and Hamburg automotive-aviation corridors concentrate procurement of automated eddy-current systems for fastener and tube inspection.
Market Restraints
- Digital detector array supply concentration:Manufacturing of amorphous selenium and cesium iodide flat panels concentrates in Japan and South Korea, creating single-source vulnerability for radiography equipment.
- Phased-array technician scarcity:Advanced ultrasonic certification requires 18-24 month training pipelines, constraining service capacity expansion faster than hardware deployment.
- Helium-3 neutron detector shortage:Radiographic testing alternatives face input cost volatility as nuclear security stockpiles limit semiconductor-grade helium availability.
Strategic Opportunities
- India infrastructure buildout:National highway and bridge construction programs under BIS structural codes are opening greenfield markets for ground-penetrating radar and impact-echo testing.
- Drone-mounted thermography:Unmanned aerial platforms carrying thermal cameras are penetrating wind turbine blade and solar farm inspection, displacing rope-access teams.
- EU AI Act compliance pathways:Automated defect recognition software for radiographic film digitization qualifies for regulatory sandbox fast-tracking, accelerating algorithm deployment.
Industry Challenges
- Multi-standard technician certification:ASNT, PCN, and ISO 9712 qualification divergence forces training redundancy, inflating labor costs for international service contracts.
- Legacy film archive digitization:Decades of radiographic weld records on analog film require capital-intensive scanning and AI-tagging to meet modern traceability requirements.
- Additive manufacturing qualification gaps:Lack of consensus NDT protocols for powder-bed fusion and directed energy deposition parts delays aerospace adoption of printed structural components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Destructive Testing and Inspection Market |
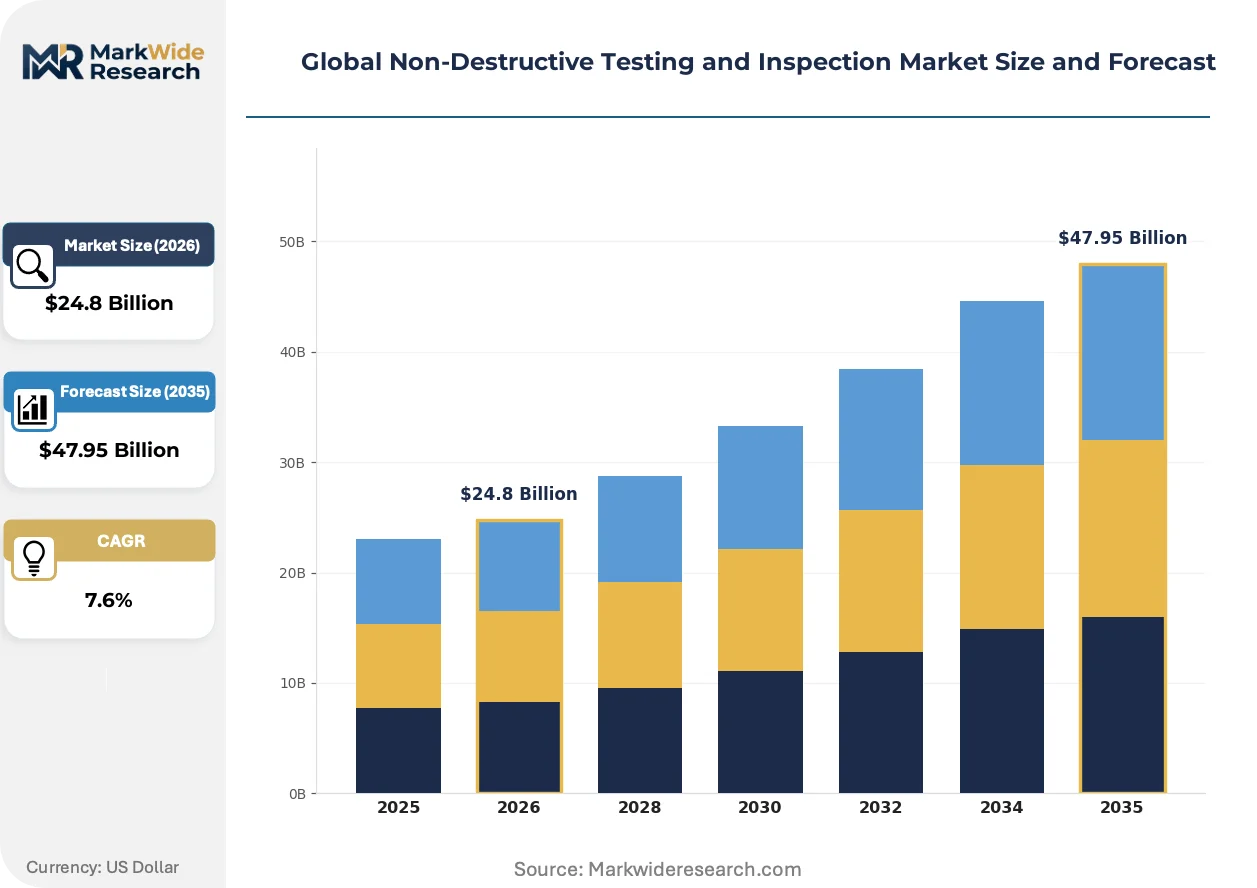
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $47.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: Ultrasonic Testing, Radiographic Testing, Eddy Current Testing, Magnetic Particle Testing, Acoustic Emission Testing Inspection Type: Visual Inspection, Leak Testing, Penetrant Testing, Infrared Thermography, Vibration Analysis Application Area: Oil & Gas, Aerospace Manufacturing, Power Generation, Civil Infrastructure, Marine Engineering End User Industry: Manufacturing Plants, Construction Firms, Energy Producers, Transportation Operators, Research Laboratories |
| Companies Covered | SGS SA, Bureau Veritas, Applus+ Services, Mistras Group, Intertek Group, Baker Hughes, Olympus Corporation, Waygate Technologies, Eddyfi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Destructive Testing and Inspection Market Shifts & Advancements
Machine-learning defect classification and portable robotics are compressing inspection timelines while regulatory bodies accelerate digital qualification standards for automated systems.
Deep-learning convolutional networks trained on radiographic image databases are automating crack and porosity detection in pipeline girth welds. Oil and gas operators in the US Gulf Coast and North Sea are adopting these tools for real-time acceptance decisions. This compression of analysis time is automating technician workforce requirements and reshaping service provider staffing models.
REACH chemical restrictions on traditional penetrant dyes are forcing formulation shifts toward water-removable fluorescent systems with lower volatile organic compound content. German automotive OEMs and their Tier-1 stamping suppliers face mandatory transition timelines under ECHA substance evaluation protocols. Magnetic particle testing suppliers are responding with pre-mixed aerosol alternatives that bypass mixing station environmental controls.
Asset owners are unbundling inspection service contracts from maintenance agreements, creating standalone procurement for NDT specialists. European wind farm operators now separately tender blade thermography from turbine OEM service packages. This disintermediation is most visible in Denmark and Germany, where independent inspection bureaus capture recurring revenue from multi-vendor turbine fleets.
Global Non-Destructive Testing and Inspection Market Segmentation
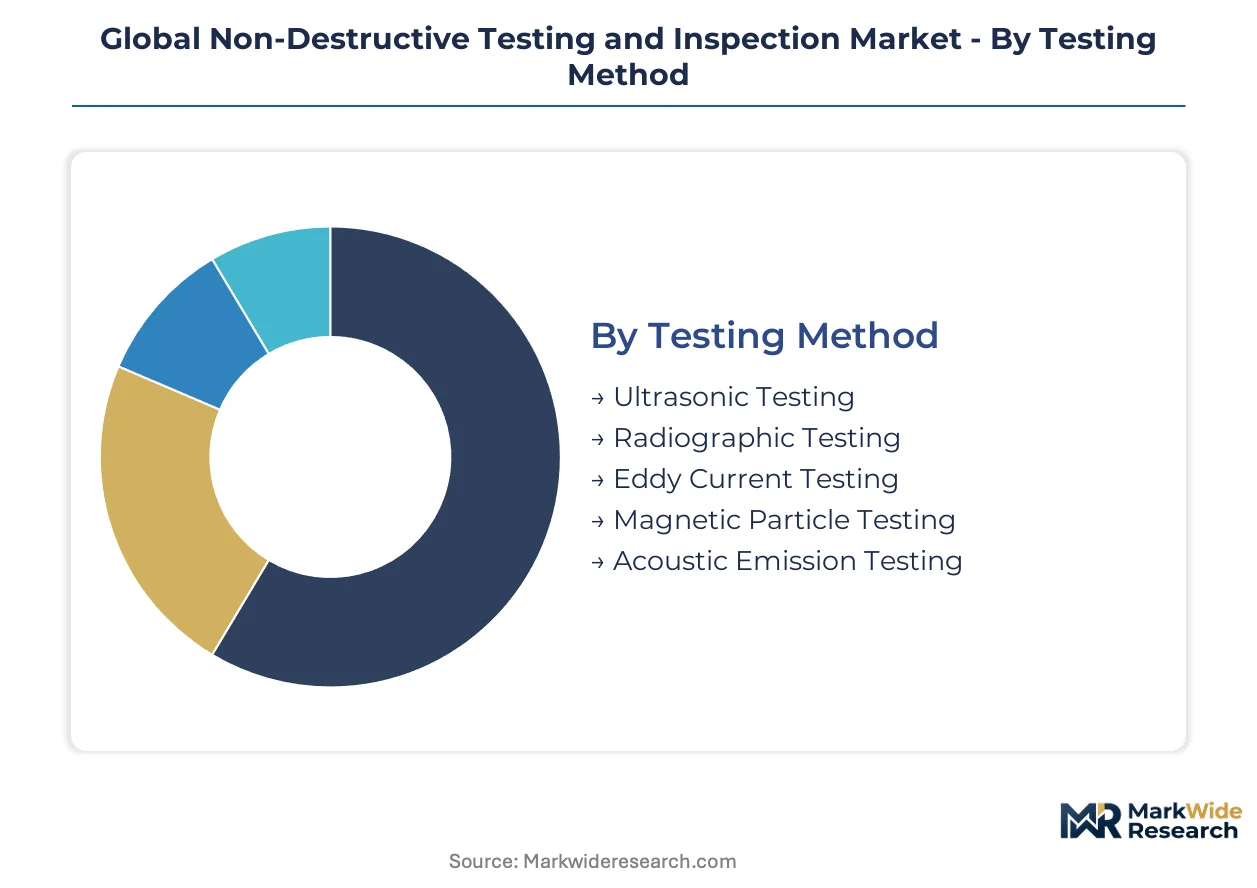
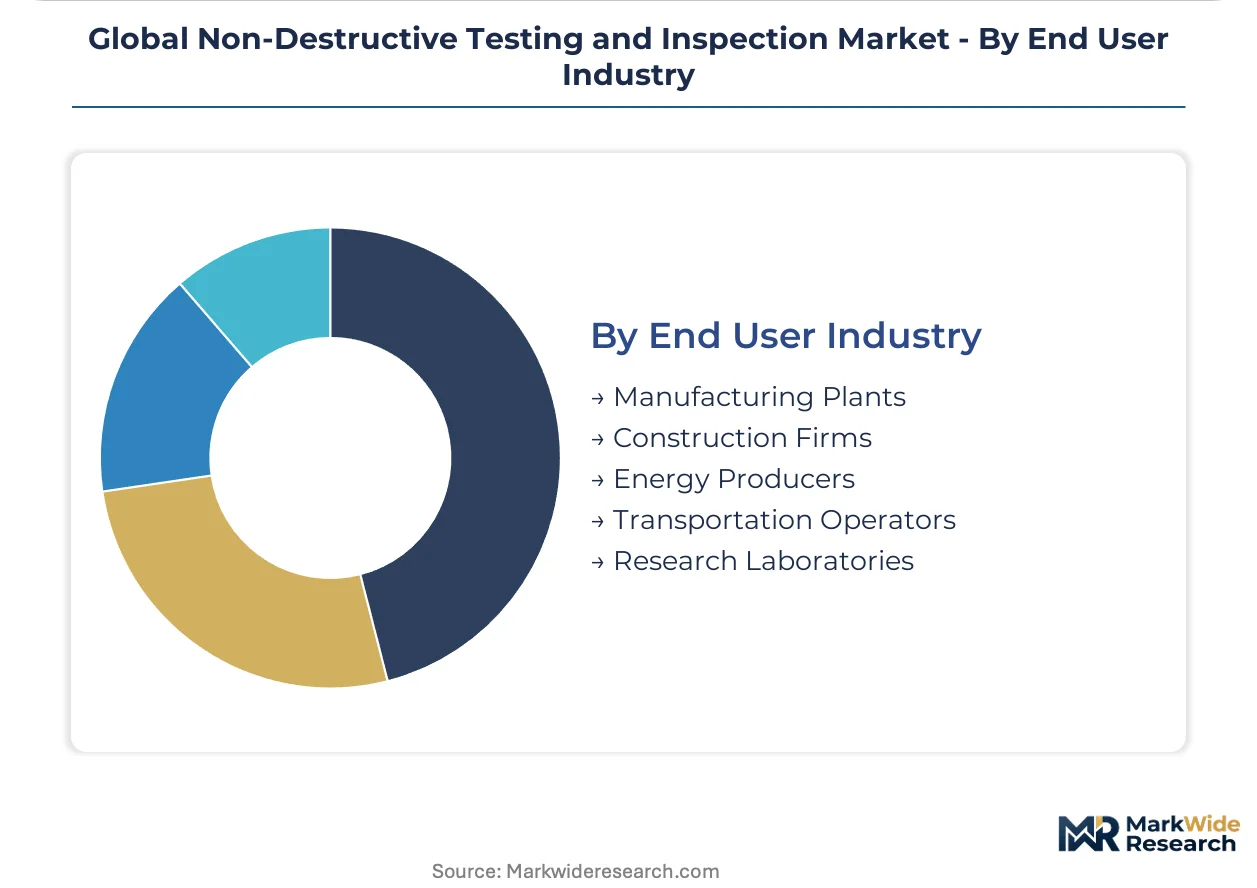
Testing method selection determines equipment capital intensity and technician certification requirements across the Global Non-Destructive Testing and Inspection Market. End-use industry fragmentation creates divergent procurement patterns between asset owners seeking in-house capability and outsourced inspection services.
Testing Method:
Ultrasonic testing dominates by volume while radiographic systems command premium pricing through digital detector array hardware.
- Ultrasonic Testing:Phased-array systems operating at 0.1–25 MHz propagate shear and longitudinal waves through metals, composites, and welded joints to map subsurface discontinuities. Boeing and Airbus composite airframe programs in Germany and France are compressing inspection cycle times with automated scanning arrays. Technician scarcity constrains service capacity expansion.
- Radiographic Testing:X-ray attenuation measured in keV ranges identifies internal voids and cracks through film or digital flat-panel capture. Japan and South Korea concentrate manufacturing of amorphous selenium and cesium iodide detector panels, creating single-source supply vulnerability for equipment procurement.
- Eddy Current Testing:Conductivity differentials reveal surface and near-surface fatigue cracks in aerospace tubes and fasteners.
- Magnetic Particle Testing:Ferromagnetic material inspection using magnetic field distortion and particle aggregation detects surface-breaking flaws.
- Acoustic Emission Testing:Passive monitoring of stress-wave energy release evaluates structural integrity under load.
Today's leader: Ultrasonic Testing. Tomorrow's challenger: Radiographic Testing.
Inspection Type:
Passive thermography climbs fastest as drone platforms displace rope-access teams for blade and solar farm inspection.
- Visual Inspection:Baseline technique requiring no specialized equipment but limited to surface-accessible defects.
- Leak Testing:Pressure decay and helium mass spectrometry methods verify containment integrity in process equipment.
- Penetrant Testing:ECHA REACH restrictions on traditional dye formulations force German automotive OEMs toward water-removable fluorescent systems with lower volatile organic compound content.
- Infrared Thermography:Passive thermography and active pulse methods detect delamination and moisture ingress in civil infrastructure. Denmark and Germany wind farm operators separately tender blade thermography from turbine OEM service packages.
- Vibration Analysis:Rotating machinery condition monitoring through spectral frequency analysis predicts bearing and shaft failures.
Passive thermography expands most quickly. Visual inspection retains the largest installed base.
Application Area:
Aerospace manufacturing concentrates premium procurement while civil infrastructure drives volume through aging asset monitoring.
- Oil & Gas:Pipeline girth weld inspection and pressure vessel integrity programs. US Gulf Coast operators adopt deep-learning convolutional networks for real-time crack and porosity detection.
- Aerospace Manufacturing:Composite primary structures and additive-manufactured components require subsurface flaw detection. FAA airworthiness directives and EASA certification memoranda mandate recurrent inspection cycles.
- Power Generation:Boiler tube, turbine blade, and nuclear pressure boundary examination.
- Civil Infrastructure:Bridge deck delamination and rebar corrosion assessment. India's national highway construction programs under BIS structural codes open greenfield markets for ground-penetrating radar.
- Marine Engineering:Hull thickness measurement and offshore platform structural surveys.
Aerospace Manufacturing commands premium pricing. Civil Infrastructure delivers volume scale.
End User Industry:
Asset owners unbundle inspection from maintenance agreements, creating standalone procurement for NDT specialists.
- Manufacturing Plants:In-process quality control and outgoing inspection for metal fabrication and assembly operations.
- Construction Firms:Structural steel weld verification and concrete integrity assessment during building erection.
- Energy Producers:Refinery turnaround inspection and power plant outage planning. OSHA process safety management rules and EPA leak detection requirements enforce periodic inspection cycles across US facilities.
- Transportation Operators:Rail wheel and axle testing, aircraft maintenance checks, and maritime classification surveys.
- Research Laboratories:Material characterization and failure analysis for product development and litigation support.
Manufacturing Plants anchor current demand. Energy Producers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Hamburg anchor European inspection service procurement, with industrial corridors driving automated eddy-current system deployment for automotive and energy infrastructure verification.
Germany
Bavarian automotive-aviation clusters concentrate phased-array ultrasonic deployment for composite airframe verification. The country's national pressure equipment regulator enforces updated compliance mandates under EU directive frameworks. Munich and Hamburg industrial corridors anchor procurement of automated inspection systems for fastener and tube examination.
United States
Gulf Coast oil and gas operators adopt deep-learning convolutional networks for real-time pipeline weld analysis. OSHA process safety management rules and EPA leak detection requirements enforce periodic inspection cycles across refineries and chemical plants. Houston and New Orleans industrial zones drive radiographic testing service contracting for pressure boundary examination.
China
National infrastructure buildout accelerates demand for ground-penetrating radar and impact-echo testing under GB structural standards. SAMR enforces compliance mandates for pressure equipment and elevator safety rope verification. Yangtze River Delta manufacturing zones concentrate procurement of magnetic particle and radiographic testing services for export-oriented production.
India
National highway and bridge construction programs under BIS structural codes open greenfield markets for civil infrastructure monitoring. The country's national standards body mandates structural integrity verification for public works procurement. Western and Southern industrial states concentrate non-destructive testing service demand from steel fabrication and power generation asset owners.
France
Aerospace manufacturing in Toulouse and Paris regions drives premium procurement for subsurface flaw detection in carbon-fiber primary structures. EASA certification memoranda mandate recurrent inspection cycles for commercial aircraft structures. Île-de-France and Occitanie industrial zones anchor specialized service provider networks for aviation supply chain certification.
Global Non-Destructive Testing and Inspection Market Competitive Landscape
Portfolio diversification dominates the current landscape as service providers expand method capabilities and geographic coverage to capture unbundled inspection contracts. The vendor base stratifies across three archetypes: diversified multinational testing houses, specialized equipment manufacturers, and regional inspection bureaus. Consolidation through strategic acquisitions and technology licensing agreements reshapes competitive positioning across aviation and energy verticals.
Within the diversified multinational tier, SGS SA and Bureau Veritas occupy positions as archetypal certification workflow anchors across aviation supply chains. Waygate Technologies exemplifies the equipment-specialist archetype with concentration in industrial radiography systems. These three entities represent distinct strategic postures: service network scale, sector-specific specialization, and hardware-anchored platform development.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| Applus+ Services |
| Mistras Group |
| Intertek Group |
| Baker Hughes |
| Olympus Corporation |
| Waygate Technologies |
| Eddyfi Technologies |
| Others |
Supply & Pricing Matrix
Phased-array technician scarcity in Germany and France compresses service capacity and widens pricing spreads between premium-certified inspection bureaus and economy-tier regional operators. Labor-cost differentials between Munich's aviation-corridor specialists and Eastern European training pipelines stratify contract rates for composite airframe verification.
Pricing Analysis
Input-cost pass-through from amorphous selenium and cesium iodide flat-panel manufacturing in Japan and South Korea elevates radiography equipment pricing. Three-tier pricing structure across premium, standard, and economy levels separates ASNT-PCN dual-certified technicians from single-qualification operators and uncertified trainees. Cost compression in the economy tier intensifies because hardware leasing models displace capital purchases among small inspection bureaus. Energy producers exhibit highest price sensitivity due to cyclical turnaround budgeting, while aerospace OEMs prioritize certification pedigree over rate negotiation.
Supply Chain Analysis
Refurbishment flows for legacy ultrasonic transducers and digital detector arrays create secondary supply channels that moderate new-equipment pricing pressure. Manufacturing concentrates in Japan, South Korea, and Germany for semiconductor-grade detector substrates, precision piezoelectric crystals, and automated scanning hardware. Raw material dependencies span rare-earth dopants for scintillator crystals, high-purity copper for eddy-current probes, and specialized alloys for phased-array wedges. Single-source vulnerability for helium-3 neutron detectors amplifies radiographic testing cost volatility. Distribution runs through OEM-direct sales for large energy and aerospace accounts, with regional distributors serving fragmented construction and manufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory inspection mandates across aviation and pressure equipment create recurring revenue visibility. Asset owners unbundle inspection from maintenance, generating standalone procurement growth.
For Market Incumbents: Anchor service network density in Germany's automotive-aviation corridors to capture unbundled contracts from wind farm operators and refinery asset managers. Deepen backward integration into automated defect recognition software development to offset technician scarcity pressure. Defend against emerging drone-thermography specialists by certifying proprietary aerial platforms under EASA-specific protocols. For New Entrants and Emerging Players: Cloud-based inspection-data platforms offer the lowest customer-acquisition friction for mid-sized manufacturing plants seeking ISO 9712-compliant record management. White-space concentrates in India's civil infrastructure buildout, where BIS-mandated bridge verification outpaces qualified service bureau supply. Target state-level highway authorities with ground-penetrating radar subscription bundles that displace project-based contracting. For Investors and Strategic Acquirers: Valuations sit cheapest among regional inspection bureaus holding single-method certifications in fragmented European markets. Long-term viability rests on regulatory inspection-frequency expansion rather than cyclical capital expenditure. Watch FAA-EASA reciprocity negotiations for digital qualification standards as the inflection signal for automated system deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Phased-Array Technician Training Pipeline Expansion | ASNT and PCN certification programs in Munich and Hamburg alleviate capacity constraints for composite airframe inspection. |
| Drone-Mounted Thermography Platform Certification | EASA-compliant aerial systems displace rope-access teams for wind turbine blade examination in Denmark and Germany. |
| Automated Defect Recognition Software Licensing | EU AI Act sandbox fast-tracking accelerates algorithm deployment for radiographic film digitization in aviation supply chains. |
| Helium-3 Detector Alternative Sourcing | Semiconductor-grade neutron detection materials from non-nuclear-security stockpiles reduce radiographic testing input cost volatility. |
| India Infrastructure Inspection Joint Venture | BIS structural code compliance for national highway programs opens greenfield markets for ground-penetrating radar services. |
Research Methodology
Bottom-up energy and aerospace manufacturing modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with NDT service directors, plant maintenance engineers, certification body training leads, and aviation supply chain quality managers combined with secondary validation from FAA airworthiness directives, EASA certification memoranda, SAMR GB standards filings, and BIS structural code documentation. Trade data from customs authorities, sector association membership directories, and equipment OEM order backlogs provided supply-side triangulation.
Input-output matrices linking inspection method adoption to end-use capital expenditure cycles generated volume and value estimates across the projection horizon. Segmentation dimensions encompassed testing method, inspection type, application area, and end-user industry, with regional regulatory cluster as an additional modeling layer. CAGRs derived from fitted growth curves applied to equipment installed base expansion and service contract renewal rates, incorporating composite airframe production schedules and pressure equipment compliance mandate timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for drone-mounted thermography and AI-driven defect recognition would alter the outlook if regulatory qualification timelines compress or extend. Forecasts reflect assumptions regarding technician training pipeline throughput, helium-3 supply continuity, and EU-China certification reciprocity stability. Practitioners should monitor FAA-EASA digital qualification standard convergence and SAMR enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
Europe Electronic Test and Measurement Market
Test and Measurement
Digital Height Gauges Market