
 Europe Portable Gas Detector Market | 2026-2036
Europe Portable Gas Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Portable Gas Detector Market Foresight
German sensor foundries and Czech electronics assemblers is recalibrating output schedules to match the surge in European industrial safety procurement. Drägerwerk AG & Co. KGaA anchors its position through captive production of electrochemical sensor cells at its Lübeck facilities. MSA Safety Incorporated competes by extending its rental-service footprint across Benelux petrochemical corridors. Honeywell International Inc. leverages its Manchester design center to specialize in firmware for multi-gas algorithms.
A portable gas detector is a self-contained, battery-operated instrument that samples ambient air through diffusion or pumped inlet to measure combustible gas percentages, oxygen deficiency, or toxic compound concentrations in parts per million, typically weighing under 500 grams for belt or lapel wear. These devices prevent asphyxiation, explosion, and chronic exposure in confined spaces, tank farms, and underground workings where fixed monitoring cannot reach. Multi gas detectors command the widest deployment breadth because single-function units no longer satisfy integrated permit-to-work systems. Electrochemical sensors retain cost leadership for hydrogen sulfide and carbon monoxide detection, though optical sensing is displacing legacy catalytic beads in methane-heavy environments.
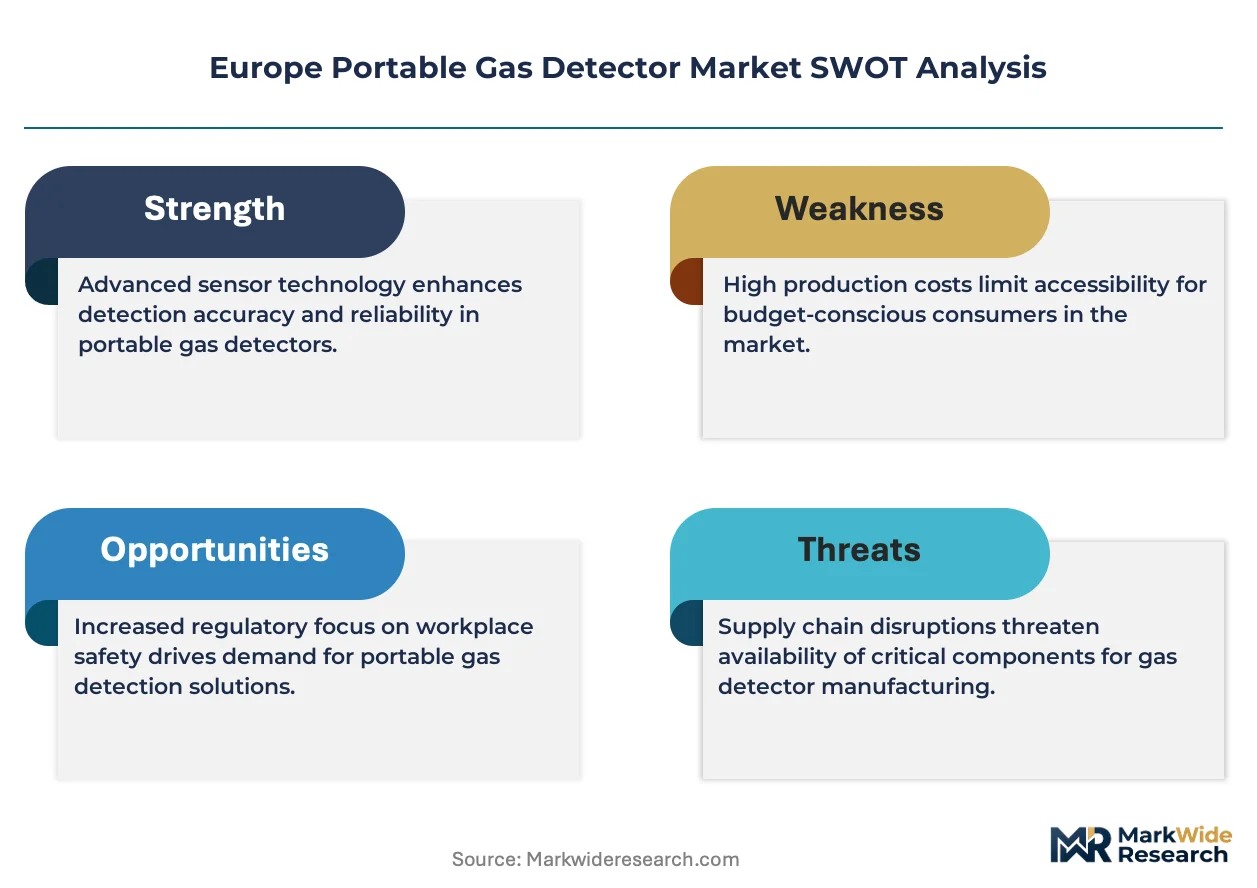
ATEX directives and the EU F-Gas Regulation shape hardware design by mandating intrinsic safety certification and restricting certain sensor refrigerants, while Germany's BetrSichV and France's CNIL-aligned workplace data rules add national compliance layers. ECHA's evolving substance restrictions on lead-based sensor components are forcing manufacturers to requalify alternative electrode materials. Stakeholders must monitor how the EU AI Act's risk-classification framework applies to predictive-maintenance algorithms embedded in next-generation connected detectors.
Market Dynamics
ATEX certification requirements and Germany's tightened BetrSichV calibration mandates are compressing replacement cycles and forcing foundries to requalify sensor materials ahead of ECHA substance restrictions.
Growth Catalysts
- North Sea oil and gas expansion:Platform operators are mandating wearable multi-gas units for all confined-space entries, creating fleet-wide procurement waves across Norwegian, UK, and Dutch offshore zones.
- REACH substance restrictions:ECHA's evolving limits on lead-based electrochemical electrodes are accelerating R&D investment in alternative sensor chemistries that extend operational lifespans.
- Connected safety ecosystems:Refinery maintenance contractors in Germany's chemical parks are integrating portable detectors into permit-to-work digital platforms, requiring networked device architectures.
Market Restraints
- Sensor material cost volatility:Palladium and platinum price swings in catalytic bead production compress margin buffers for electrochemical cell manufacturers.
- Lithuanian and Estonian supply concentration:Baltic electronics assemblers control a disproportionate share of ATEX-certified enclosure fabrication, creating single-source vulnerability.
- Optical sensing substitution:Infrared and laser-based methane detection in tank farm applications is eroding demand for legacy catalytic pellistor technology.
Strategic Opportunities
- Polish industrial safety lag:Chemical and coal sectors in Silesia and Pomerania remain underpenetrated by connected multi-gas systems relative to German adoption rates.
- EU AI Act risk classification:Predictive maintenance algorithms embedded in next-generation detectors will require compliance certification, creating first-mover advantage for firmware-ready manufacturers.
- Rental-service channel expansion:Benelux petrochemical corridors are showing receptivity to instrument-leasing models that bundle calibration and data analytics services.
Industry Challenges
- Firmware talent scarcity:Manchester and Lübeck design centers compete for embedded systems engineers capable of multi-gas algorithm development under ATEX intrinsic safety constraints.
- ATEX recertification timelines:Requalification of lead-free sensor variants requires 18-24 month approval cycles that delay product launches ahead of ECHA enforcement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Portable Gas Detector Market |
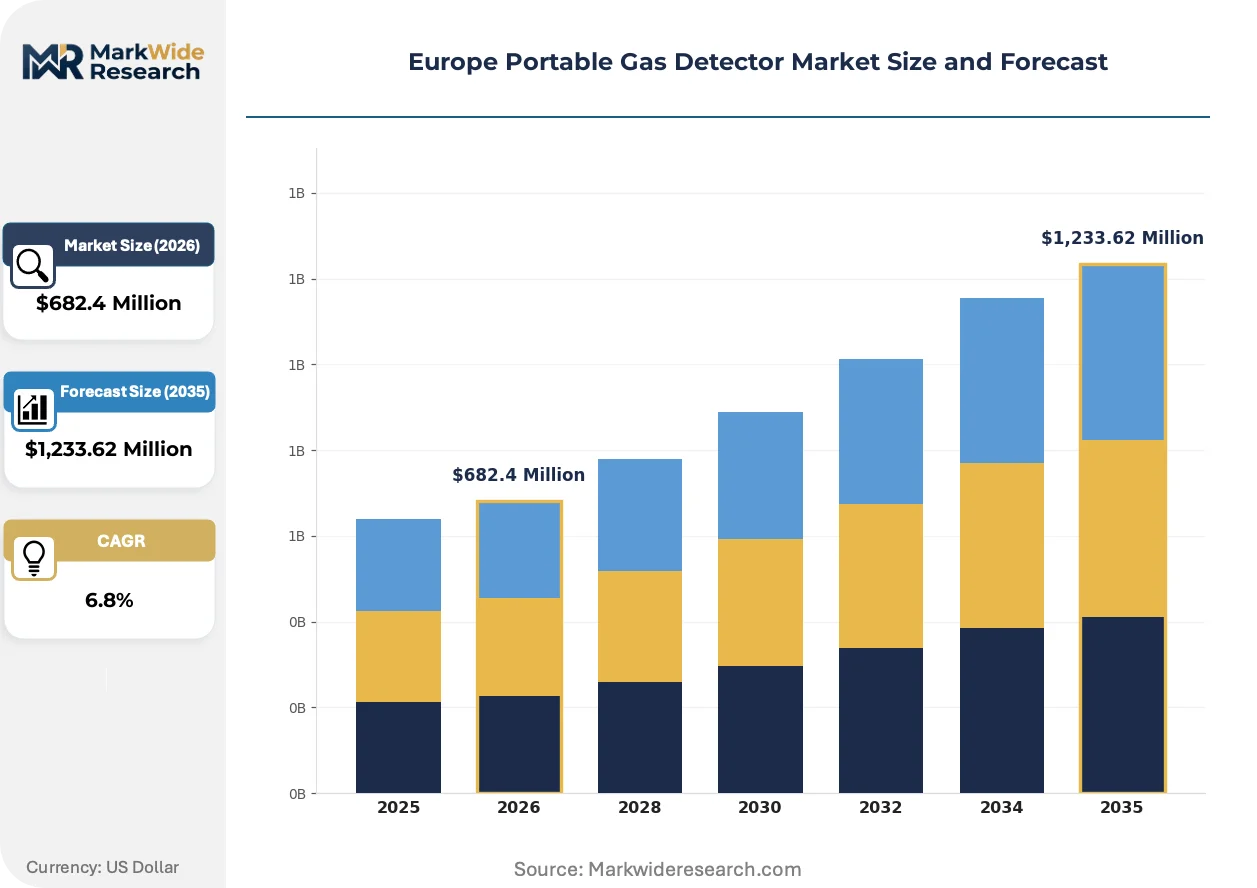
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,233.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Gas Detectors, Multi Gas Detectors, Toxic Gas Detectors, Infrared Gas Detectors Technology: Catalytic Sensors, Electrochemical Sensors, Photoionization Detection, Optical Sensors End User: Mining, Oil & Gas, Fire Services, Environmental Monitoring Sales Channel: Direct Sales, Distributors, Online Retail, Third-Party Resellers |
| Companies Covered | Honeywell International Inc., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Thermo Fisher Scientific Inc., Industrial Scientific, GfG Gas Detection, Crowcon Detection Instruments Ltd., Teledyne Technologies Incorporated, AMETEK, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Portable Gas Detector Market Shifts & Advancements
Optical sensing architectures and predictive connectivity layers are restructuring how detection data flows from field instruments to centralized safety management systems across European industrial sites.
Photonic methane detection using tunable diode laser absorption spectroscopy is decentralizing calibration requirements for offshore platform operators. North Sea maintenance crews are adopting these units at accelerating rates to eliminate the drift and poisoning susceptibility of catalytic beads. The technology is decentralizing maintenance schedules by enabling six-month calibration intervals rather than monthly cycles, compressing total cost of ownership for fleet operators.
The EU F-Gas Regulation's restrictions on sensor refrigerants are forcing hardware redesigns for infrared detector cooling systems. Manufacturers must eliminate hydrofluorocarbon-dependent thermal management from portable form factors. German chemical park operators are most affected, pressing suppliers for solid-state cooling alternatives that maintain detection sensitivity in high-humidity tank farm environments.
Rental-service contracts with embedded predictive analytics are displacing outright purchase models among Benelux refinery contractors. These arrangements bundle real-time exposure data with maintenance liability, transferring calibration burden to equipment providers. The shift is most visible in Rotterdam-Antwerp petrochemical corridors, where integrated safety procurement favors outcome-based vendor relationships over capital expenditure cycles.
Europe Portable Gas Detector Market Segmentation
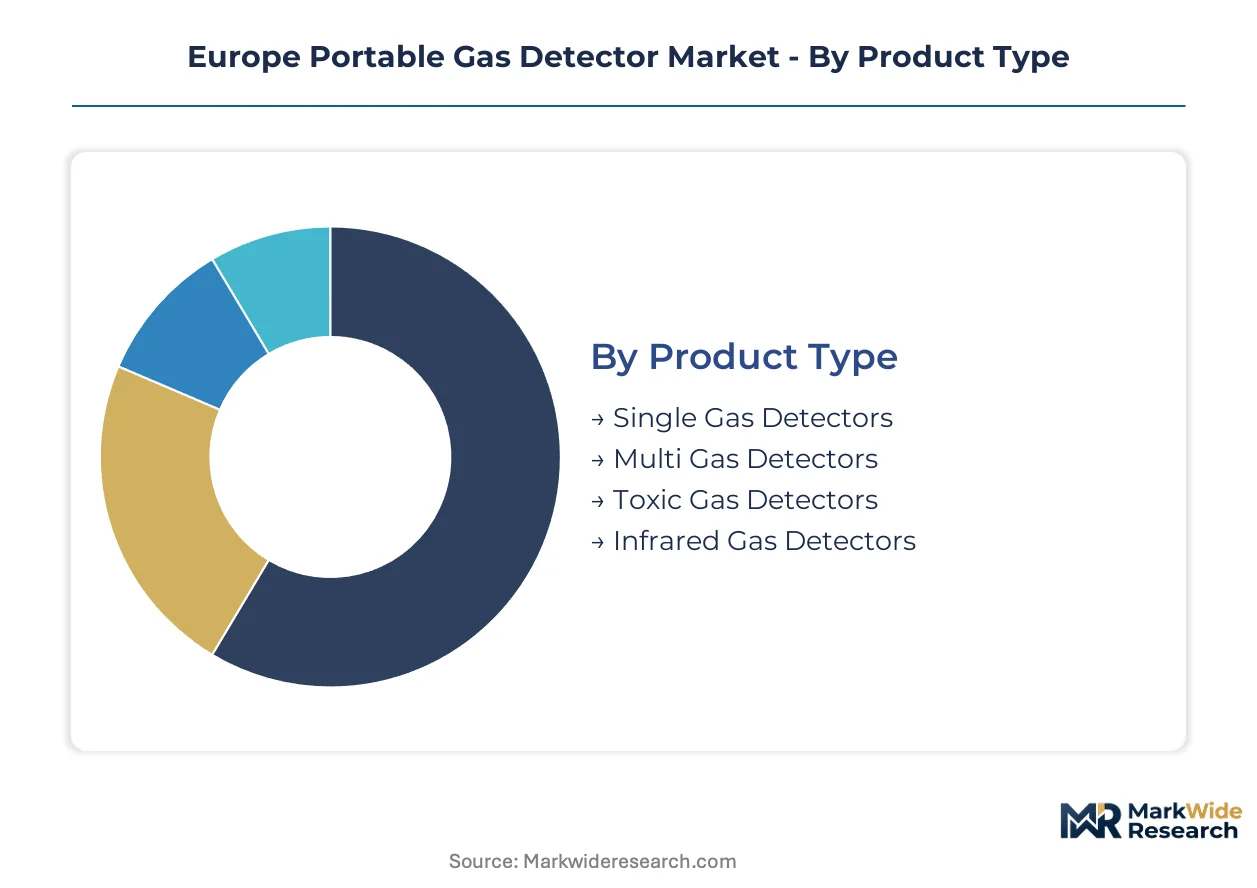
Portable gas detector procurement patterns diverge sharply across specification tiers, with multi-gas functionality and connected architectures commanding premium positioning in German chemical parks and North Sea offshore fleets. Understanding how product type, sensor technology, and channel structure intersect reveals where margin pools concentrate and where standardization pressures erode pricing power.
Product Type:
Detection architecture determines unit economics, with single-function legacy designs facing displacement as integrated safety ecosystems mandate broader sensing arrays.
- Single Gas Detectors:Compact electrochemical or catalytic units measuring one target compound, typically H2S or CO. German confined-space contractors in Rhineland refineries still deploy these for budget-constrained spot-checking, though fleet standardization pressures are narrowing procurement windows.
- Multi Gas Detectors:Simultaneous monitoring of combustible gases, oxygen deficiency, and multiple toxic species through modular sensor slots. North Sea platform operators mandate these for all permit-to-work entries, creating synchronized replacement cycles across Norwegian, UK, and Dutch offshore zones.
- Toxic Gas Detectors:Specialized units for hydrogen sulfide, ammonia, or chlorine detection in chemical processing environments. Czech electronics assemblers produce ATEX-certified variants for Central European chemical park maintenance contractors.
- Infrared Gas Detectors:Non-dispersive infrared absorption systems for methane and hydrocarbon monitoring. Tank farm operators in Rotterdam-Antwerp corridors specify these for drift-resistant performance in high-humidity conditions.
Multi Gas Detectors leads on scale; Infrared Gas Detectors leads on momentum.
Technology:
Sensor chemistry selection drives calibration burden, operational lifespan, and compliance recertification timelines under evolving ECHA substance restrictions.
- Catalytic Sensors:Pellistor beads detecting combustible gas through catalytic oxidation. Legacy offshore platforms retain these for methane monitoring, though poisoning susceptibility from silicone vapors accelerates replacement demand.
- Electrochemical Sensors:Amperometric cells for toxic gas quantification, dominant in hydrogen sulfide and carbon monoxide detection. Drägerwerk's Lübeck foundries manufacture these with shortened calibration intervals mandated by Germany's updated BetrSichV ordinances.
- Photoionization Detection:Ultraviolet lamp ionization for volatile organic compound measurement at parts-per-billion sensitivity. Environmental monitoring contractors in French industrial zones deploy these for fugitive emission surveys.
- Optical Sensors:Tunable diode laser and infrared absorption architectures eliminating drift and poisoning risks. North Sea maintenance crews are expanding adoption to compress calibration cycles from monthly to six-month intervals.
Electrochemical Sensors anchors volume; Optical Sensors is expanding most quickly.
End User:
Sector-specific hazard profiles dictate sensor array requirements, with offshore hydrocarbon extraction and confined-space chemical processing representing the highest unit-value deployment environments.
- Mining:Underground coal and metal operations requiring methane and oxygen deficiency monitoring. Polish Silesian operations remain underpenetrated by connected multi-gas systems relative to German adoption benchmarks.
- Oil & Gas:Upstream exploration, midstream storage, and downstream refining across North Sea platforms and Benelux petrochemical corridors. Integrated permit-to-work digitization is mandating networked detector architectures.
- Fire Services:Emergency response teams requiring rapid-deployment units for unknown atmosphere entry. French CNIL-aligned workplace data rules add compliance complexity for connected device deployment.
- Environmental Monitoring:Regulatory compliance and fugitive emission detection for industrial perimeter surveillance. German chemical park operators press suppliers for solid-state cooling alternatives under EU F-Gas Regulation constraints.
Oil & Gas dominates procurement value; Environmental Monitoring is climbing the fastest.
Sales Channel:
Channel structure determines service bundling capabilities and calibration liability allocation, with rental-service models gaining traction in outcome-oriented procurement environments.
- Direct Sales:Manufacturer-led account management for large fleet operators. MSA Safety extends this model across Benelux petrochemical corridors with embedded maintenance contracts.
- Distributors:Regional inventory and technical support networks. German industrial safety distributors maintain calibration service capabilities for BetrSichV compliance.
- Online Retail:E-commerce procurement for standard configurations and replacement sensors. Limited penetration in ATEX-certified segments requiring technical consultation.
- Third-Party Resellers:Independent specialists bundling instruments with training and compliance documentation. Concentrated in Baltic states with electronics assembly proximity.
Distributors maintains volume leadership; Direct Sales is gaining share fastest through rental-service conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in fleet procurement density, while the Netherlands concentrates rental-service innovation for offshore contractors. National regulatory divergence creates distinct compliance burdens across the region's industrial corridors.
Germany
Rhineland refineries and Bavarian chemical parks drive multi-gas detector deployment for confined-space maintenance. BetrSichV ordinances mandate shortened calibration intervals, compressing replacement cycles for electrochemical sensor cells. The Lübeck sensor foundry cluster supplies captive production to domestic safety equipment manufacturers.
United Kingdom
North Sea platform operators mandate wearable detection units for all permit-to-work entries across Aberdeen and Great Yarmouth supply bases. The Health and Safety Executive enforces ATEX certification rigor for offshore intrinsic safety compliance. Manchester design centers specialize firmware development for multi-gas algorithm architectures serving North Sea fleets.
Netherlands
Rotterdam-Antwerp petrochemical corridors favor rental-service contracts bundling calibration with real-time exposure analytics. The Dutch Working Conditions Act aligns with EU F-Gas Regulation constraints on infrared detector cooling systems. Integrated safety procurement in the Port of Rotterdam cluster transfers maintenance liability to equipment providers.
Norway
Offshore maintenance crews in Stavanger and Bergen adopt tunable diode laser absorption spectroscopy to extend calibration intervals. The Norwegian Petroleum Safety Authority enforces stringent atmospheric monitoring for platform confined-space entries. Photonic methane detection is displacing legacy catalytic beads across North Sea Norwegian sectors.
France
Environmental monitoring contractors in Lyon and Marseille industrial zones deploy photoionization detection for fugitive emission surveys. CNIL-aligned workplace data rules add compliance complexity for connected device architectures in French chemical processing. The Auvergne-Rhône-Alpes cluster remains underpenetrated by networked safety ecosystems relative to German adoption benchmarks.
Europe Portable Gas Detector Market Competitive Landscape
German producers anchor the premium tier through captive sensor manufacturing; US specialists hold scale positions across rental-service channels. The vendor structure concentrates around vertically integrated safety conglomerates and regional electronics assemblers. Three archetypes dominate: electrochemical sensor foundries, firmware-specialized design houses, and integrated safety service providers. Capacity expansion in Baltic enclosure fabrication and strategic partnerships for predictive analytics licensing represent the primary competitive vectors.
Among Germany-based fabricators, Drägerwerk AG & Co. KGaA exemplifies the captive-production archetype through its Lübeck sensor foundry operations. MSA Safety Incorporated and Honeywell International Inc. represent the multinational service-integrated tier, occupying positions that bundle hardware with maintenance liability transfer. These three anchors illustrate how geographic specialization and channel structure differentiation create distinct competitive positioning across the European industrial safety procurement landscape.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Thermo Fisher Scientific Inc. |
| Industrial Scientific |
| GfG Gas Detection |
| Crowcon Detection Instruments Ltd. |
| Teledyne Technologies Incorporated |
| AMETEK |
| Others |
Supply & Pricing Matrix
Captive sensor production at Drägerwerk's Lübeck foundries anchors premium pricing power for German electrochemical cell manufacturers while compressing margin buffers for assemblers dependent on Baltic enclosure suppliers. This integration choice insulates domestic producers from palladium price volatility in catalytic bead inputs but exposes outsourced fabricators to single-source vulnerability in ATEX-certified housing supply.
Pricing Analysis
Capacity additions in Czech electronics assembly are reshaping price floors for standard multi-gas detector configurations. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified fleet units with predictive analytics from basic confined-space spot-checkers. Price differentiation hinges on calibration service bundling and firmware-enabled connectivity rather than hardware alone. Pricing pressure stems from optical sensing substitution eroding legacy catalytic pellistor demand, with Polish mining contractors showing highest price sensitivity and North Sea platform operators least sensitive due to total-cost-of-ownership procurement criteria.
Supply Chain Analysis
Embedded systems engineer scarcity in Manchester and Lübeck design centers constrains firmware development throughput for multi-gas algorithm architectures. Supply concentrates in Germany for electrochemical sensor cells, the Baltic states for ATEX-certified enclosure fabrication, and the Czech Republic for electronics assembly. Raw material dependencies span palladium and platinum for catalytic beads, lead-free electrode alloys for ECHA compliance, and solid-state cooling components for F-Gas Regulation adherence. Single-source vulnerability in Lithuanian and Estonian enclosure supply creates structural risk. Distribution runs through German industrial safety distributors with calibration service capabilities, Benelux direct-sales rental channels, and regional third-party resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where North Sea platform operators now mandate six-month calibration intervals and predictive connectivity as baseline specifications, displacing commodity spot-checking units.
For Market Incumbents: Deploy captive sensor foundry capacity as a defensive moat against optical sensing substitution threatening legacy electrochemical architectures. Deepen backward integration into solid-state cooling component supply to meet EU F-Gas Regulation constraints without margin erosion. Consolidate calibration service networks in Germany's chemical park corridors before rental-service models transfer maintenance liability to equipment providers. For New Entrants and Emerging Players: EU AI Act risk classification in Germany opens a window for firmware-specialized entrants to capture predictive maintenance algorithm certification ahead of incumbent recertification timelines. Polish Silesian mining operations and French Auvergne-Rhône-Alpes chemical processing clusters remain underpenetrated by connected multi-gas systems relative to German benchmarks. Pursue channel partnerships with Benelux rental-service providers to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional electronics assemblers with ATEX certification capabilities because Baltic supply concentration creates scarcity value for acquirers seeking geographic diversification. Target vertically integrated mid-cap specialists with captive sensor production and established German chemical park relationships. Watch ECHA enforcement windows for lead-free electrode materials as the inflection signal determining which sensor chemistry platforms achieve scale viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Cell Production | Captive electrochemical cell supply insulates Drägerwerk and German peers from ECHA substance restriction delays. |
| Optical Sensing Platform Migration | Tunable diode laser absorption spectroscopy adoption by North Sea operators compresses calibration cycles from monthly to six-month intervals. |
| Rental-Service Channel Expansion | Outcome-based contracts in Rotterdam-Antwerp corridors transfer calibration liability from petrochemical contractors to equipment providers. |
| Firmware Certification Investment | EU AI Act compliance for predictive maintenance algorithms creates first-mover advantage in next-generation connected detector architectures. |
| Baltic Enclosure Supply Diversification | Reducing single-source dependence on Lithuanian and Estonian ATEX-certified housing fabricators mitigates geopolitical and logistics risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with safety equipment procurement managers at German chemical parks, North Sea platform maintenance directors, and Czech electronics assembly operations heads with secondary validation against ATEX certification databases, ECHA substance restriction filings, and EU F-Gas Regulation implementation guidance. Bottom-up unit deployment estimates triangulated against top-down industrial safety expenditure benchmarks across the analysis window.
Comparable-period anchoring linked historical reference data through the projection horizon without year-specific citation. The analytical framework modeled segmentation across product architecture, sensor chemistry, end-use sector hazard profile, and channel service bundling capability. CAGRs derived from fitted growth curves incorporating replacement cycle compression from BetrSichV calibration mandates and optical sensing substitution rates in methane-heavy environments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA enforcement acceleration or Baltic supply disruption scenarios. Forecasts reflect assumptions on regulatory timeline adherence and technology substitution elasticity. Material deviation in EU AI Act certification requirements or palladium price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Digital Metal Detector Market