
 Hydrogen Leak Detector Market | 2026-2036
Hydrogen Leak Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Leak Detector Market Analytics
IEC 60079-29-1 certification for explosive atmosphere gas detection is unwinding the competitive field, forcing smaller participants toward costly third-party validation or OEM partnerships. INFICON leverages its mass spectrometry heritage to dominate high-sensitivity applications in semiconductor fabs. Honeywell International Inc. anchors its position through backward integration into sensor manufacturing and captive calibration protocols. MSA Safety Incorporated differentiates via channel control across industrial safety distributors in North America.
A hydrogen leak detector senses trace concentrations of hydrogen gas through electrochemical reaction, thermal conductivity variation, or ultrasonic acoustic emission, typically achieving detection thresholds below 1000 ppm to prevent explosive mixture formation in confined spaces. Fixed detectors command the largest installed base across manufacturing plants and oil & gas facilities where continuous perimeter monitoring is mandatory, while portable units represent the fastest-expanding category as maintenance crews adopt personal protective instrumentation for hot-work permitting. Electrochemical sensors retain cost leadership in standard industrial safety monitoring, though infrared technology is displacing legacy semiconductor architectures in cold-climate hydrogen liquefaction terminals where thermal drift compromises accuracy.
The EPA enforces hydrogen safety under Clean Air Act risk management planning for facilities exceeding threshold quantities, while OSHA mandates process safety management protocols that specify detector placement density and response-time requirements. The EU AI Act and Machinery Directive impose conformity assessment burdens on smart detectors with embedded diagnostic algorithms, creating compliance divergence between connected and legacy analog units. Stakeholders must monitor how IEC standard revisions address hydrogen purity grades in emerging electrolyzer applications, as detection thresholds calibrated for industrial-grade hydrogen may prove inadequate for fuel cell vehicle supply chains requiring 99.97% purity assurance.
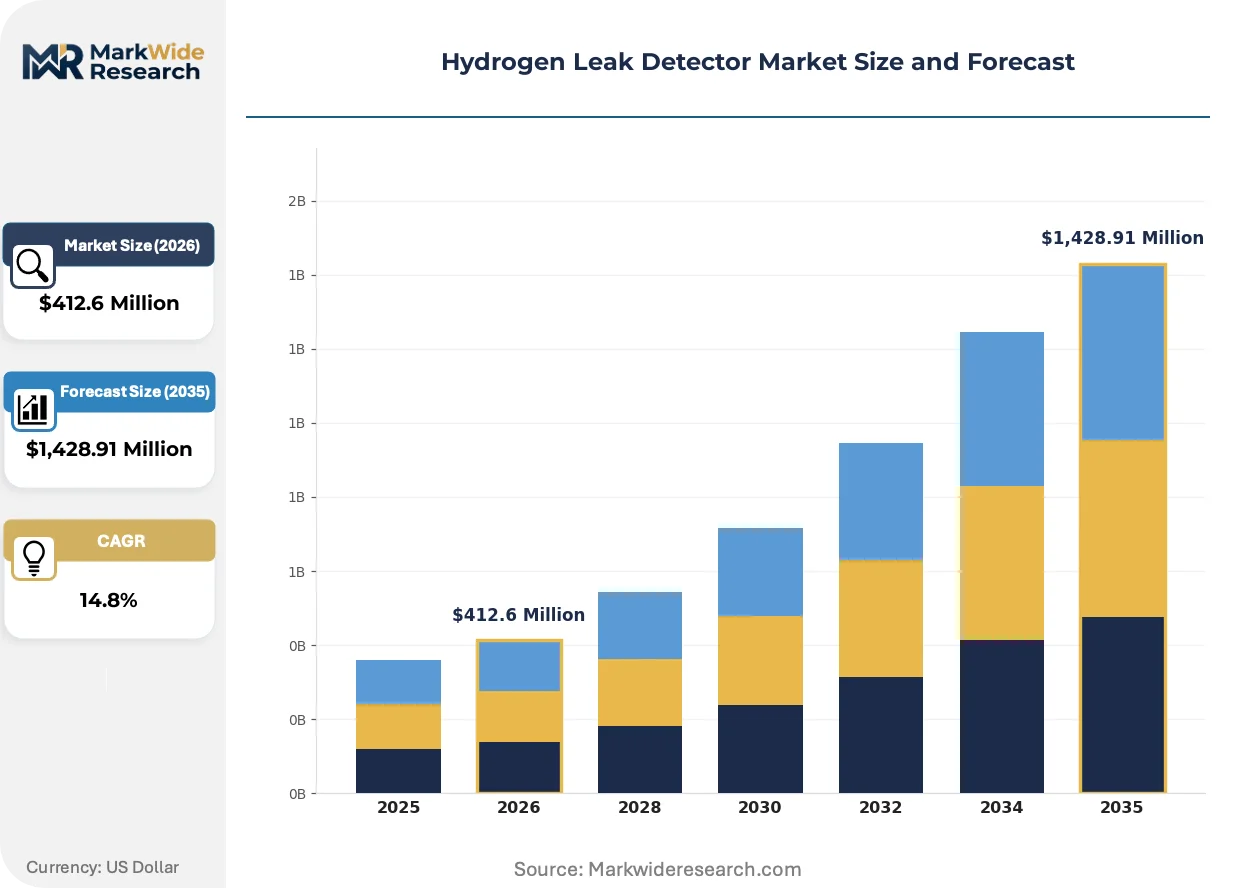
Market Dynamics
Electrochemical sensor architectures face systematic displacement as infrared and ultrasonic detection methods penetrate hydrogen liquefaction terminals and fuel cell manufacturing lines, driven by thermal drift failures in sub-zero environments and tightening IEC 60079-29-1 certification thresholds.
Growth Catalysts
- EU Green Deal hydrogen hub mandates:Germany, the Netherlands, and France channel public capital into refueling infrastructure, mandating detector deployment density at production and distribution nodes.
- Fuel cell vehicle fleet scaling:OEM maintenance protocols now specify portable leak detection for technician hot-work permitting, expanding the addressable instrument base beyond fixed installations.
- Electrolyzer purity grade escalation:PEM and alkaline systems targeting 99.97% hydrogen output require sub-100 ppm detection thresholds, forcing sensor recalibration across existing industrial safety networks.
Market Restraints
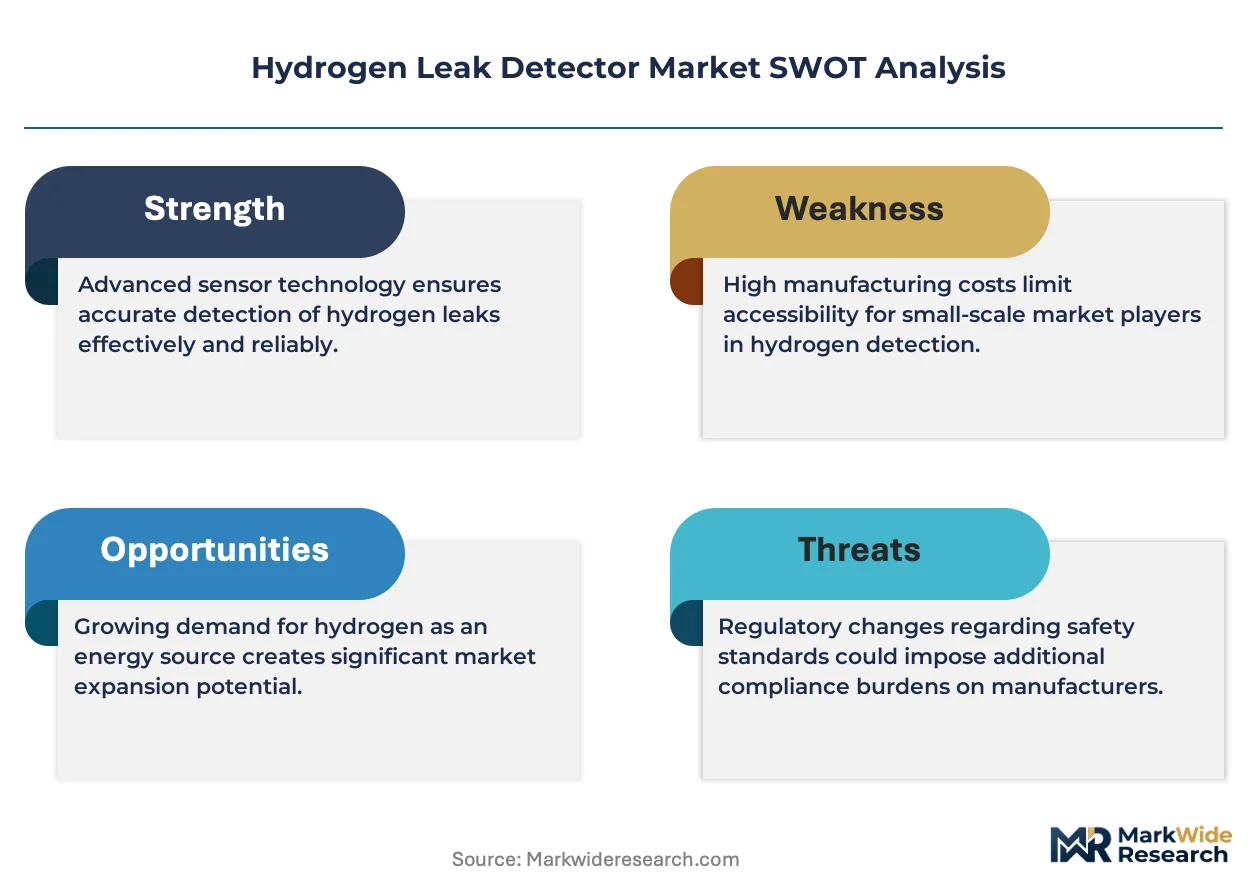
- Palladium catalyst supply concentration:Electrochemical sensor membranes depend on Russian and South African palladium refining, exposing cost structures to geopolitical supply shocks.
- IEC 60079-29-1 third-party validation costs:Certification expenses for explosive atmosphere equipment exceed $50,000 per product variant, squeezing mid-tier participants toward OEM partnerships or exit.
- Infrared detector thermal management complexity:Optical path heating requirements in cryogenic hydrogen terminals elevate power consumption and maintenance intervals versus legacy semiconductor architectures.
Strategic Opportunities
- India National Hydrogen Mission infrastructure:Green hydrogen production targets of 5 million tonnes annually by 2030 create first-mover positioning for detector suppliers in electrolyzer and pipeline projects.
- AI-embedded predictive maintenance:Machine learning algorithms processing acoustic emission patterns enable pre-leak anomaly detection, opening premium pricing tiers for connected instrument portfolios.
- Service unbundling from hardware sales:Calibration-as-a-subscription models penetrate North American industrial safety distributors, decoupling recurring revenue from capital expenditure cycles.
Industry Challenges
- IEC standard revision latency:Draft amendments addressing hydrogen purity grades in electrolyzer applications remain in committee, leaving manufacturers without definitive detection threshold guidance for fuel cell supply chains.
- Cross-functional technician training gaps:Maintenance crews require simultaneous competence in gas detection, electrical safety, and fuel cell system architecture, constraining deployment velocity at refueling stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Leak Detector Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,428.91 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Handheld Detectors, Stationary Detectors Technology: Electrochemical Sensors, Infrared Sensors, Semiconductor Sensors, Ultrasonic Sensors End User: Manufacturing Plants, Oil & Gas Industry, Research Facilities, Transportation Sector Application: Safety Monitoring, Leak Detection, Process Control, Environmental Monitoring |
| Companies Covered | Teledyne Gas and Flame Detection, INFICON, Honeywell International Inc., Industrial Scientific Corporation, Crowcon Detection Instruments Ltd., MSA Safety Incorporated, Emerson Electric Co., Fuji Electric, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Leak Detector Market Evolving Landscape
Photonic and acoustic sensing modalities are compressing the performance-cost frontier for hydrogen detection, while regulatory frameworks in Europe and Asia-Pacific impose algorithmic transparency requirements on smart instruments with embedded diagnostics.
Tunable diode laser absorption spectroscopy is supplanting thermal conductivity sensors in hydrogen liquefaction terminals. Japanese and South Korean energy majors deploy these instruments at export-scale facilities. The technology enables continuous pipeline monitoring without thermal drift compensation, collapsing maintenance schedules from quarterly to annual intervals.
The EU AI Act conformity assessment obligations now extend to safety instruments with embedded diagnostic algorithms. Smart detectors must document decision pathways for explosive atmosphere classifications. European electrolyzer OEMs are bifurcating procurement between connected units for greenfield sites and legacy analog architectures for retrofit projects to manage compliance timeline risk.
Refueling station operators now specify detector calibration certificates as standalone procurement line items, decoupling service from original equipment purchases. German and South Korean hydrogen hub developers mandate third-party validation documentation in tender requirements. This unbundling compresses hardware margins while expanding recurring service revenue pools for certified calibration providers.
Hydrogen Leak Detector Market Segmentation
Detector classification shapes procurement specifications across hydrogen value chains. Regulatory mandates in Germany, Japan, and South Korea dictate certification tiers that segment demand by installation permanence and mobility requirements.
Product Type:
Regulatory frameworks in the EU, Japan, and South Korea mandate distinct installation protocols for permanent versus mobile detection assets, creating divergent compliance cost structures.
- Portable Detectors:Battery-powered units with electrochemical or semiconductor sensing elements achieve sub-1000 ppm thresholds for technician hot-work permitting. Demand concentrates in German and South Korean hydrogen refueling station maintenance protocols where OSHA-style personal protective equipment mandates expand instrument fleets.
- Fixed Detectors:Hardwired perimeter installations with continuous data logging satisfy IEC 60079-29-1 certification for explosive atmosphere classification. Manufacturing plants in Japan and oil & gas facilities in Germany represent the largest installed base where continuous monitoring is mandatory.
- Handheld Detectors:Compact single-gas units serve spot-check applications in research facilities.
- Stationary Detectors:Rack-mounted multi-point systems integrate with building management systems in electrolyzer control rooms.
Established volume favors fixed installations; emerging adoption favors portable units.
Technology:
Cost tiers separate legacy electrochemical architectures from premium infrared and ultrasonic modalities.
- Electrochemical Sensors:Palladium-catalyzed membrane cells deliver cost leadership in standard industrial safety monitoring. South Korean manufacturing plants and German oil & gas distributors specify these for ambient temperature applications where thermal drift is absent.
- Infrared Sensors:Tunable diode laser absorption spectroscopy eliminates thermal compensation requirements in cryogenic hydrogen terminals. Japanese liquefaction facilities and Dutch export-scale hubs deploy these for annual rather than quarterly maintenance intervals.
- Semiconductor Sensors:Metal oxide films retain niche positioning in budget-constrained research facilities.
- Ultrasonic Sensors:Acoustic emission detection enables pre-leak anomaly identification in fuel cell manufacturing lines.
Electrochemical architectures dominate unit volume; infrared modalities command premium pricing tiers.
End User:
Application maturity varies sharply across hydrogen purity grades and regulatory exposure.
- Manufacturing Plants:Electrolyzer OEMs and fuel cell stack producers in Germany and Japan require sub-100 ppm detection thresholds for 99.97% purity assurance. IEC standard revision latency leaves procurement teams without definitive calibration guidance.
- Oil & Gas Industry:Refinery hydrogen pipeline networks in South Korea and the Netherlands mandate fixed detector density per process safety management protocols. EU Green Deal hydrogen hub investments channel public capital into retrofit installations.
- Research Facilities:National laboratories in Japan specify handheld units for experimental apparatus verification.
- Transportation Sector:Bus depots and truck fleet maintenance bays in Germany adopt portable detection for technician safety.
Oil & gas retrofit demand anchors near-term revenue; manufacturing plant purity requirements drive specification escalation.
Application:
Functional deployment determines sensor selection criteria and replacement cadence.
- Safety Monitoring:Personnel protection systems in confined spaces mandate redundant detection with alarm integration. German refueling stations and Japanese manufacturing plants specify these for zone classification compliance.
- Leak Detection:Pipeline integrity verification in Dutch and South Korean distribution networks employs portable ultrasonic instruments for rapid source identification.
- Process Control:Electrolyzer output quality assurance in research facilities requires continuous purity verification.
- Environmental Monitoring:Fugitive emission quantification at liquefaction terminals supports regulatory reporting.
Safety monitoring commands replacement frequency; leak detection applications are climbing fastest on maintenance protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal channels public capital into hydrogen infrastructure across multiple jurisdictions, while Japan and South Korea accelerate fuel cell vehicle deployment through dedicated national strategies. National hydrogen hub programs in Germany, the Netherlands, and France mandate detector deployment density at production and distribution nodes.
Germany
Hydrogen refueling station networks and electrolyzer manufacturing clusters drive detector demand across Bavaria and North Rhine-Westphalia. The national hydrogen strategy mandates safety protocols at production nodes, with KBA enforcing certification requirements for explosive atmosphere equipment. Industrial safety distributors in the Ruhr region report accelerating procurement of fixed perimeter installations.
Japan
Fuel cell vehicle fleet expansion and liquefaction terminal investments concentrate demand in the Kanto and Kansai regions. METI oversees hydrogen safety standards through JIS certification frameworks for gas detection equipment. Export-scale facilities in Chubu deploy tunable diode laser absorption spectroscopy for continuous pipeline monitoring.
South Korea
Hydrogen city pilot programs and refinery retrofit projects anchor detector procurement in the Seoul Capital Area and Busan-Ulsan corridor. MFDS-aligned safety regulations specify detector placement density for process safety management compliance. Electrolyzer OEMs in Daegu-Gyeongbuk require sub-100 ppm detection thresholds for fuel cell supply chain integration.
United States
Clean hydrogen production tax credits under the IRA stimulate electrolyzer deployment in Texas and California industrial corridors. OSHA mandates process safety management protocols specifying detector response-time requirements for facilities exceeding threshold hydrogen quantities. Gulf Coast refinery operators specify portable detection for technician hot-work permitting.
Netherlands
Rotterdam hydrogen hub investments and pipeline network expansions drive fixed detector installations across the Randstad region. EU Green Deal funding mechanisms require IEC 60079-29-1 certification for explosive atmosphere equipment at import terminals. Export-scale distribution facilities specify infrared modalities to eliminate thermal drift compensation.
Hydrogen Leak Detector Market Competitive Landscape
Player mix skews toward diversified industrial safety conglomerates with captive sensor manufacturing capabilities. Market structure concentrates around three to five integrated participants controlling certification pathways and distribution channels. Strategic archetypes separate mass spectrometry heritage specialists, backward-integrated sensor manufacturers, and channel-controlled safety distributors. Competitive moves center on third-party validation partnerships for IEC compliance and service unbundling to capture recurring calibration revenue.
Within the diversified industrial safety tier, Honeywell International Inc. and MSA Safety Incorporated exemplify channel-controlled positioning across North American distributors. INFICON occupies a distinct archetype leveraging mass spectrometry heritage for high-sensitivity applications. Emerson Electric Co. and Teledyne Gas and Flame Detection represent scale-driven instrumentation portfolios spanning multiple gas detection modalities. Drägerwerk AG & Co. KGaA anchors European safety equipment consolidation through integrated manufacturing and service networks.
| Leading Market Players |
|---|
| Teledyne Gas and Flame Detection |
| INFICON |
| Honeywell International Inc. |
| Industrial Scientific Corporation |
| Crowcon Detection Instruments Ltd. |
| MSA Safety Incorporated |
| Emerson Electric Co. |
| Fuji Electric |
| Drägerwerk AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Electrolyzer manufacturing scale economies in Germany and South Korea compress unit production costs while concentrating procurement leverage among a handful of OEMs, which in turn squeezes detector suppliers into volume-discount structures and captive calibration arrangements that lock in multi-year service revenue at the expense of hardware margins.
Pricing Analysis
IEC 60079-29-1 certification grade creates the primary spread between premium and standard detector tiers, with third-party validated units commanding substantial premiums over uncertified alternatives in EU and South Korean procurement tenders. Pricing stratifies across premium infrared modalities for cryogenic terminals, standard electrochemical architectures for ambient industrial safety, and economy semiconductor units for research spot-check applications. Cost compression in the electrochemical tier intensifies as palladium catalyst supply volatility from Russian and South African refiners feeds through to membrane cell production. Maintenance crews at German refueling stations exhibit the highest price sensitivity, deferring portable unit replacements until calibration subscription bundles force hardware refresh cycles.
Supply Chain Analysis
Palladium catalyst refining concentration in Russia and South Africa exposes electrochemical sensor membrane production to geopolitical supply disruption and price volatility. Detector manufacturing draws from Japanese optical component suppliers for tunable diode laser spectroscopy modules, German precision engineering for fixed-installation housing assemblies, and Chinese PCB fabrication for signal processing electronics. Single-source vulnerability in palladium catalyst supply represents the dominant structural risk, with no near-term substitution pathways for hydrogen-selective membrane chemistry. Distribution runs through captive industrial safety distributor networks in North America and direct OEM relationships in European hydrogen hub developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen leak detector market rewards participants who control scarce certification pathways and sensor fabrication capabilities, as IEC standard revision latency and palladium catalyst supply concentration create persistent bottlenecks that disciplined capital can exploit.
For Market Incumbents: Fortify backward integration into palladium catalyst membrane manufacturing or secure long-term offtake agreements with Russian and South African refiners before supply disruption accelerates. Deepen channel control across German and South Korean industrial safety distributors to lock out mid-tier competitors seeking IEC 60079-29-1 certification partnerships. Prioritize AI-embedded diagnostic algorithm development to capture EU AI Act compliance premiums before conformity assessment burdens fully crystallize. For New Entrants and Emerging Players: Lead with ultrasonic acoustic emission detection for fuel cell manufacturing line pre-leak anomaly identification, where incumbent electrochemical portfolios lack technical credibility and infrared modalities prove cost-prohibitive for line-integration scale. Target Indian electrolyzer OEMs under the National Hydrogen Mission infrastructure buildout, where first-mover positioning in greenfield projects avoids entrenched competitor relationships. Pursue calibration-as-a-subscription go-to-market models that decouple recurring revenue from capital expenditure approval cycles at North American refinery operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mass spectrometry heritage specialists with existing high-sensitivity application credibility and established third-party validation relationships for IEC explosive atmosphere certification. Long-term viability hinges on sensor modality diversification beyond electrochemical architectures as infrared and ultrasonic penetration accelerates in cryogenic and manufacturing applications. Watch for IEC standard revision finalization addressing hydrogen purity grades as the inflection signal for fuel cell supply chain specification escalation and associated detection threshold recalibration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Catalyst Supply | Secures membrane cell production continuity against Russian and South African supply disruption. |
| AI-Embedded Diagnostic Algorithm Development | Captures EU AI Act conformity assessment premiums for smart detector portfolios in European markets. |
| Calibration-as-a-Subscription Service Unbundling | Decouples recurring revenue from capital expenditure cycles at North American industrial safety distributors. |
| Ultrasonic Detection Portfolio Entry | Addresses pre-leak anomaly identification white space in fuel cell manufacturing line integration. |
| India National Hydrogen Mission First-Mover Positioning | Establishes supplier relationships before electrolyzer and pipeline project procurement finalizes. |
Research Methodology
A spread of perspectives from detector OEM product managers, industrial safety distributor procurement heads, electrolyzer facility engineering directors, and refueling station maintenance supervisors converged on the working assumptions through structured primary interviews, validated against IEC certification documentation, EU Green Deal funding mechanism disclosures, and national hydrogen strategy implementation reports, with bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows across the analysis window.
Segmentation dimensions modeled include detector installation permanence, sensing modality technology, end-user industry vertical, and functional application deployment, with value and volume outputs derived through cross-referencing equipment procurement specifications from German KBA enforcement protocols, Japanese METI JIS certification frameworks, and South Korean MFDS-aligned safety regulations, incorporating hydrogen purity grade escalation trajectories and fuel cell vehicle fleet scaling assumptions throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained public capital commitment to hydrogen hub infrastructure, stable palladium catalyst supply from concentrated refining jurisdictions, and timely IEC standard revision finalization would require recalibration. Practitioners should keep alternative scenarios live as regulatory certification timelines, geopolitical supply disruptions, and technology modality substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Gas Detectors Market