
 Pyro Electric Infrared Detectors Market | 2026-2036
Pyro Electric Infrared Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Pyro Electric Infrared Detectors Market Analytics
A shortage of trained photonics engineers is unwinding manufacturing expansion plans across the supply base. Excelitas Technologies leverages its captive crystal growth capability to sustain margin control on lithium tantalate substrates. Lynred anchors European defense procurement through its mastery of multi-channel detector arrays. Murata Manufacturing dominates consumer electronics volumes with automated packaging lines that compress unit economics.
Pyroelectric infrared detectors are thermal sensors that generate surface charge when exposed to infrared radiation, typically fabricated from pyroelectric crystals such as lithium tantalate or deuterated triglycine sulfate with responsivity values reaching 10^4 V/W. Their primary commercial purpose is non-contact temperature measurement and motion sensing in environments where active illumination is impractical or prohibited. Digital detectors are capturing share from analog architectures as microcontroller integration eliminates external amplification stages. Passive sensors lead unit shipments in building security and energy management, while hybrid sensors command premium positioning in aerospace and medical imaging where signal fidelity requirements are stringent.
FDA 510(k) pathways govern medical imaging deployments in the United States, while REACH and RoHS constrain material selection for European manufacturers. ECHA substance restrictions on lead-bearing solders are forcing redesigns of detector packaging and interconnect schemes. Stakeholders must monitor how dual-use export controls from national regulators reshape access to defense-grade detector technologies.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-dependent infrared cooling architectures while automotive OEMs in Stuttgart and Wolfsburg scale pedestrian detection procurement, creating a bifurcation between passive pyroelectric and active cooled alternatives.
Growth Catalysts
- EU Green Deal decarbonization mandates:Building automation retrofits across German commercial real estate are specifying passive infrared occupancy sensors to meet Energy Performance of Buildings Directive thresholds.
- Lithium tantalate crystal availability:Captive substrate production by specialized photonics suppliers is stabilizing input costs for detector fabricators serving medical imaging OEMs.
- Automotive safety regulation:Euro NCAP pedestrian protection protocols are mandating infrared-based night vision systems in premium vehicle segments.
Market Restraints
- Raw material concentration:High-purity lithium tantalate ingot supply concentrates among three Japanese and German crystal growers, exposing detector manufacturers to allocation risk.
- Microbolometer substitution:Vanadium oxide and amorphous silicon thermal arrays are capturing price-sensitive motion detection applications below 100 millimeter focal lengths.
- REACH substance restrictions:ECHA candidate list scrutiny of lead-containing electrode materials is forcing packaging redesigns with extended qualification timelines.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are attracting detector packaging investments to serve domestic HVAC and security system integrators.
- Medical imaging convergence:Integration of pyroelectric arrays with CMOS readout circuits is enabling compact thermography devices for point-of-care fever screening in Japanese clinics.
- Defense dual-use channels:Multi-channel detector configurations are qualifying for national security procurement frameworks in France and Germany with multi-year offtake guarantees.
Industry Challenges
- Photonics engineering scarcity:Detector design requires rare expertise in pyroelectric physics and MEMS packaging simultaneously, constraining R&D team expansion.
- ISO 9001 and ISO 13485 certification timelines:Medical device qualification cycles extend 18-24 months, delaying revenue recognition for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyro Electric Infrared Detectors Market |
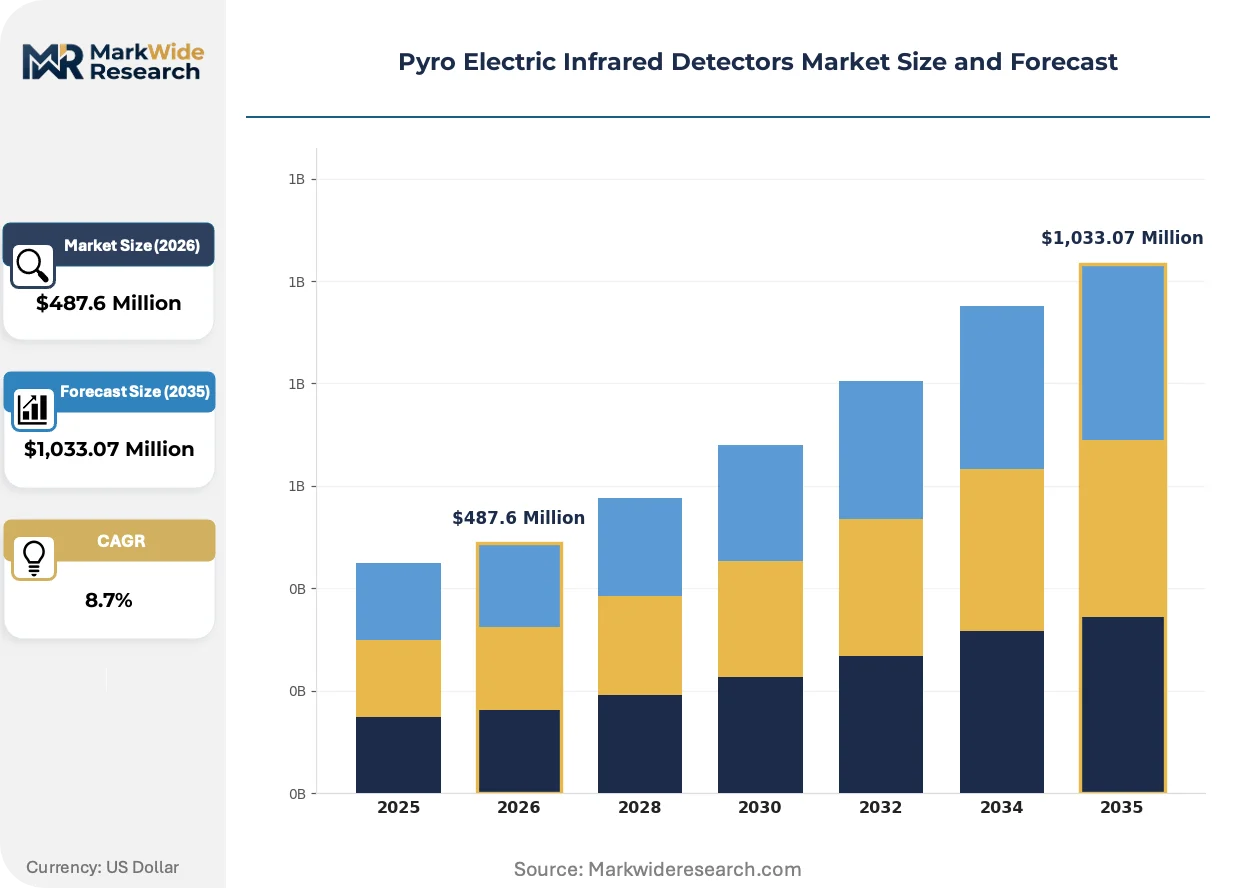
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Detectors, Analog Detectors, Multi-Channel Detectors, Single-Channel Detectors Application: Automotive Safety, Industrial Automation, Building Security, Medical Imaging Technology: Active Sensors, Passive Sensors, Hybrid Sensors, Fiber-Optic Sensors End User: Consumer Electronics, Aerospace, Defense, Healthcare |
| Companies Covered | Excelitas Technologies, Lynred, Murata Manufacturing, Hamamatsu Photonics, Teledyne FLIR, Texas Instruments, Infratec, ULIS, Leonardo DRS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyro Electric Infrared Detectors Market Evolving Landscape
Digital readout integration and material substitutions are compressing traditional analog detector architectures while regulatory pressure on refrigerants accelerates passive technology roadmaps across automotive and building systems.
Deuterated triglycine sulfate (DTGS) pyroelectric crystals are fragmenting the long-wave infrared sensing landscape for laboratory spectroscopy applications. Research institutions in Germany and Japan are adopting DTGS detectors for Fourier-transform infrared systems requiring room-temperature operation. This material shift is fragmenting market share previously held by liquid-nitrogen-cooled alternatives in analytical instrumentation segments.
REACH authorization procedures for lead-bearing solders are forcing interconnect material transitions in European detector packaging. Manufacturers serving medical imaging OEMs must validate silver-epoxy or sintered copper alternatives through accelerated aging protocols. German packaging houses are absorbing the highest compliance burden as they supply FDA-registered device assemblers in the United States.
System integrators are consolidating vendor panels around detector suppliers offering embedded signal processing firmware. Building automation contractors in France and the Netherlands now specify digital-output pyroelectric modules with integrated motion algorithms to reduce microcontroller programming burden. This specification shift favors detector manufacturers with captive ASIC design capabilities over discrete component vendors.
Pyro Electric Infrared Detectors Market Segmentation
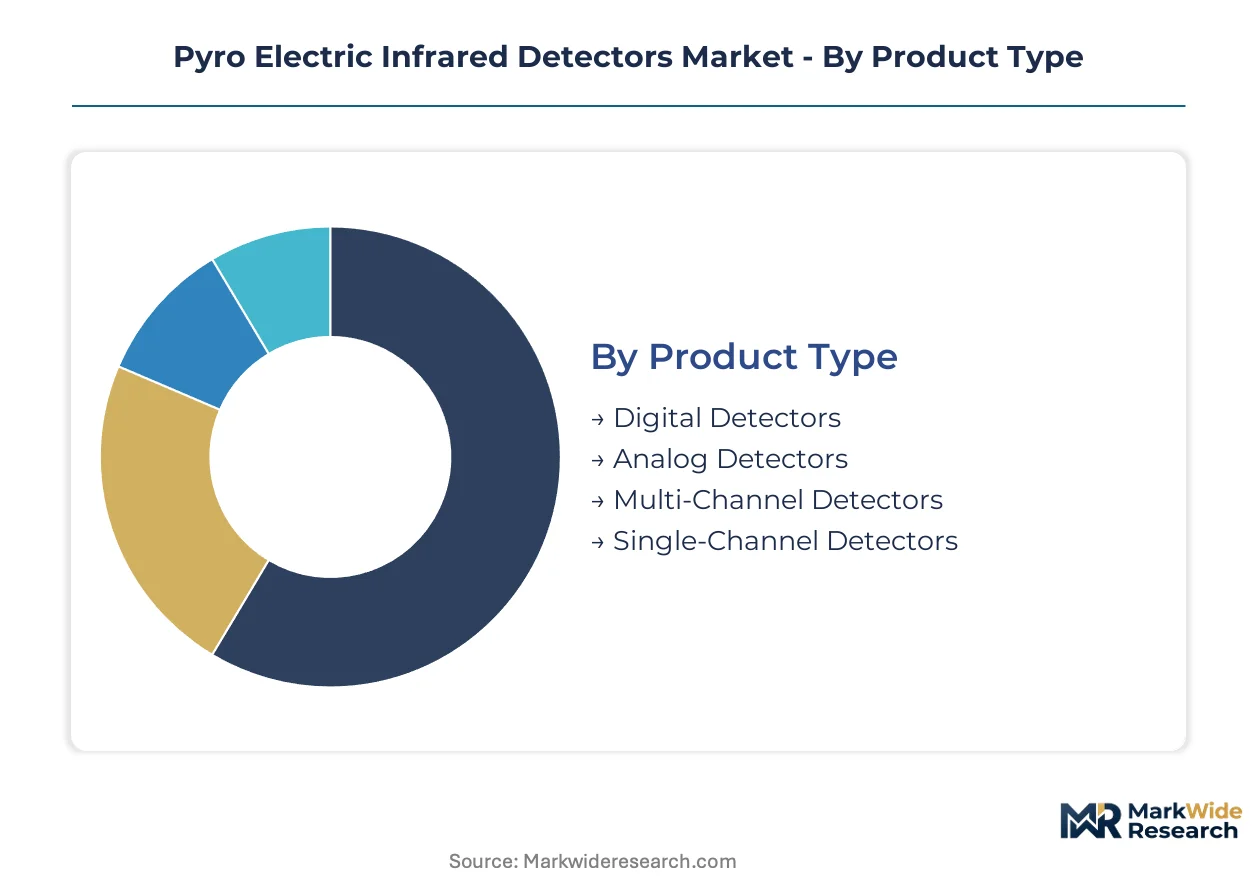
Segmentation in pyroelectric infrared detectors reveals how technical specifications align with end-use requirements across radically different performance and cost thresholds. Understanding these divisions exposes where captive manufacturing capabilities and regulatory compliance burdens concentrate competitive advantage.
Product Type:
Digital detectors serve export-led demand from German automotive OEMs, while analog architectures retain domestic relevance in cost-sensitive building automation across France and the Netherlands.
- Digital Detectors:These integrate microcontroller-compatible outputs that eliminate external amplification stages. Stuttgart-based Tier 1 suppliers specify digital modules for pedestrian detection systems to compress BOM complexity and accelerate Euro NCAP compliance timelines.
- Analog Detectors:Continuous voltage output architectures persist in legacy building security installations. French facility managers favor analog sensors for retrofit compatibility with existing 4-20mA control loops, though specification share is compressing.
- Multi-Channel Detectors:Array configurations with parallel readout channels address aerospace thermography requirements. Lynred supplies these to French defense procurement frameworks with multi-year offtake structures.
- Single-Channel Detectors:Discrete element designs dominate consumer motion sensing. Murata Manufacturing's automated packaging lines in Japan compress unit economics for this high-volume category.
Digital detectors command the established base. The steepest expansion runs through multi-channel configurations.
Application:
Cost tier stratification separates premium medical imaging from price-pressured building security, with automotive safety occupying a mid-tier volume position.
- Automotive Safety:Night vision and occupant monitoring systems drive specification. Wolfsburg OEMs scale pedestrian detection procurement under Euro NCAP protocols, creating dedicated demand for automotive-qualified detector variants with extended temperature ranges.
- Industrial Automation:Process monitoring and predictive maintenance applications require robust packaging. German factory automation clusters in Bavaria specify passive infrared for non-contact temperature measurement in hazardous environments.
- Building Security:Motion detection for intrusion systems represents high-unit, low-margin demand. Dutch commercial real estate retrofits under EU Green Deal mandates specify passive occupancy sensors for energy management compliance.
- Medical Imaging:Thermography and fever screening demand signal fidelity. Japanese clinics adopt pyroelectric-CMOS hybrid arrays for point-of-care deployment under PMDA guidance.
Building security commands volume leadership. Medical imaging delivers the highest margin expansion trajectory.
Technology:
Passive architectures dominate unit shipments where refrigerant elimination is mandated, while hybrid sensors capture premium positioning in performance-critical deployments.
- Passive Sensors:These operate without external cooling, converting thermal radiation directly through pyroelectric crystals. EU F-Gas Regulation compliance accelerates substitution of refrigerant-dependent alternatives in German commercial building retrofits.
- Active Sensors:Thermoelectric or Stirling-cycle cooling enables extended wavelength sensitivity. Laboratory spectroscopy in German research institutions retains demand despite regulatory pressure on refrigerant architectures.
- Hybrid Sensors:Combined pyroelectric and semiconductor architectures optimize signal-to-noise ratios. Aerospace thermography in France specifies these for satellite-based earth observation with stringent radiometric calibration requirements.
- Fiber-Optic Sensors:Remote sensing configurations isolate detectors from harsh environments. Industrial process monitoring in Japan adopts these for high-temperature furnace applications where electronics cannot survive.
Passive sensors command installed base dominance. Hybrid configurations are climbing the fastest in value terms.
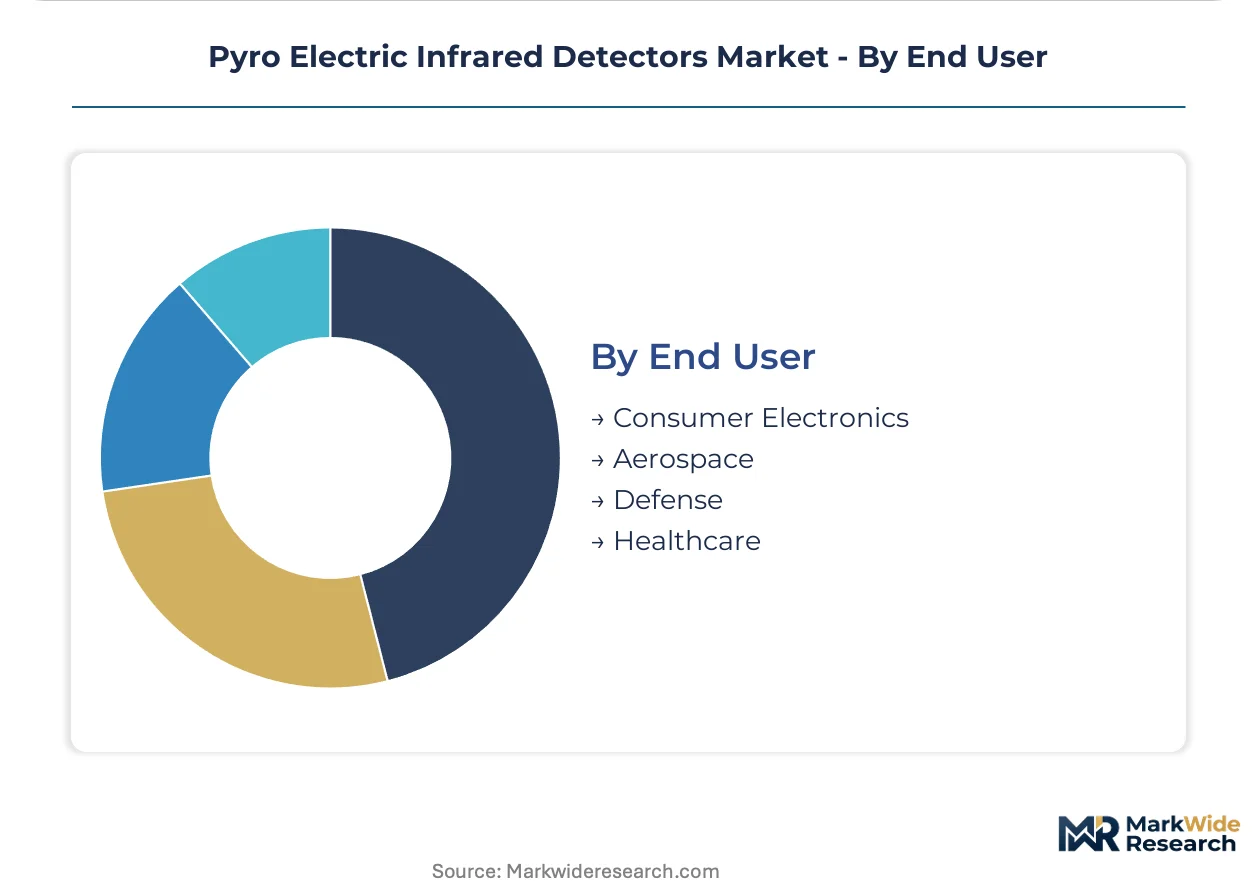
End User:
Customer type determines certification burden and procurement cycle length, with defense and healthcare imposing the most stringent qualification requirements.
- Defense:National security procurement frameworks in France and Germany require multi-channel detector arrays with ITAR-equivalent traceability. Dual-use export controls reshape supplier access to this segment.
- Healthcare:FDA 510(k) and MDR compliance extend qualification timelines. German packaging houses serving FDA-registered device assemblers absorb the highest REACH substance restriction burdens for lead-free interconnect validation.
- Aerospace:Satellite and aircraft applications demand radiation-hardened variants. ESA-qualified suppliers in Germany maintain captive crystal growth for lithium tantalate substrate traceability.
- Consumer Electronics:Motion-activated devices and smart home systems drive massive unit volumes. Automated packaging lines in Japan and Korea compress economics for this price-sensitive category.
Consumer electronics commands unit shipment leadership. Defense procurement delivers the most stable revenue visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance restrictions on lead-bearing solders are compressing European detector packaging capacity while automotive OEM procurement concentrates in German industrial clusters. National security frameworks in France and export licensing regimes in Japan reshape access to defense-grade technologies.
Germany
Stuttgart and Wolfsburg automotive OEMs scale pedestrian detection procurement under Euro NCAP protocols. The EU F-Gas Regulation accelerates substitution of refrigerant-dependent alternatives in commercial building retrofits. Bavarian factory automation clusters specify passive infrared for non-contact temperature measurement in hazardous process environments.
United States
FDA 510(k) pathways govern medical imaging deployments while NHTSA safety standards drive automotive infrared qualification. EPA refrigerant phase-down rules pressure active cooling architectures in laboratory instrumentation. Greater Boston photonics corridors absorb REACH compliance burdens for lead-free interconnect validation serving European device assemblers.
Japan
METI industrial automation incentives channel detector procurement toward HVAC and security system integrators. PMDA guidance shapes thermography device qualification for point-of-care fever screening in clinical settings. Osaka-based packaging houses compress unit economics through automated production lines for consumer motion sensing volumes.
France
National security procurement frameworks require multi-channel detector arrays with ITAR-equivalent traceability for defense applications. ANSM oversight constrains medical device material selection and extended qualification timelines. Lyon-area system integrators consolidate vendor panels around digital-output pyroelectric modules with embedded motion algorithms.
India
PLI scheme incentives for electronics manufacturing attract detector packaging investments to serve domestic industrial automation demand. BIS certification requirements shape product qualification for building security and energy management deployments. Maharashtra-based HVAC contractors specify passive occupancy sensors for Green Building Council compliance in commercial real estate retrofits.
Pyro Electric Infrared Detectors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive crystal growth capabilities separating margin-protected positions from assembly-dependent competitors. The structure concentrates around three strategic archetypes: substrate-integrated fabricators controlling lithium tantalate supply, defense-anchored array specialists, and scale-driven consumer electronics suppliers. Consolidation pressure runs through M&A targeting photonics engineering talent, while capacity expansion concentrates in automated packaging corridors serving price-sensitive motion detection volumes.
Among substrate-integrated fabricators, Excelitas Technologies exemplifies vertical control through captive lithium tantalate production. Lynred occupies a position within the defense-specialist tier, anchoring European multi-channel array procurement. Murata Manufacturing represents the scale-driven archetype, with automated packaging lines compressing economics for high-volume consumer applications.
| Leading Market Players |
|---|
| Excelitas Technologies |
| Lynred |
| Murata Manufacturing |
| Hamamatsu Photonics |
| Teledyne FLIR |
| Texas Instruments |
| Infratec |
| ULIS |
| Leonardo DRS |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between German automotive OEMs and lithium tantalate substrate suppliers lock in volume allocations while freezing input cost visibility for detector fabricators serving medical imaging and defense channels. This contract architecture shields Tier 1 suppliers from spot market volatility in high-purity crystal feedstock while compressing margin flexibility for packaging houses absorbing REACH compliance burdens.
Pricing Analysis
Price spreads between Japanese and German supply corridors reflect captive crystal growth premiums versus merchant substrate sourcing. Three-tier pricing structure across automotive-qualified, medical-grade, and consumer-tier detectors separates Euro NCAP-certified modules from standard building automation variants. Cost compression in consumer motion sensing intensifies as Murata Manufacturing's automated Osaka lines set unit economic benchmarks. Building security integrators exhibit highest price sensitivity, while defense procurement frameworks tolerate premium positioning for ITAR-traceable multi-channel arrays.
Supply Chain Analysis
Strategic stockpiling of lithium tantalate ingots prevails among German and Japanese detector fabricators, while just-in-timed component flows dominate consumer electronics packaging in Korea and Taiwan. High-purity pyroelectric crystal supply concentrates in Germany, Japan, and China, with electrode materials and ceramic packages drawing from South Korean and Taiwanese merchant foundries. Single-source vulnerability runs through three Japanese and German crystal growers controlling ingot purification. Distribution runs through specialized photonics distributors serving OEM procurement teams in Stuttgart, Wolfsburg, and Lyon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware and calibration service contracts are expanding faster than hardware unit shipments as building automation contractors specify digital-output modules with pre-integrated motion algorithms. This service-attach layer captures recurring revenue from system integrators seeking to reduce microcontroller programming burden.
For Market Incumbents: Fortify substrate supply through backward integration into lithium tantalate crystal growth or long-term offtake structures with Japanese and German ingot suppliers. Microbolometer substitution in sub-100mm focal length applications threatens pyroelectric share in price-sensitive motion detection; counter by accelerating digital readout integration to compress BOM complexity for automotive Tier 1s. For New Entrants and Emerging Players: Lead with PLI scheme incentives in Maharashtra and Gujarat to establish detector packaging capacity serving India's domestic HVAC and security system integrators. India's industrial automation segment offers lowest incumbent saturation among major economies; pursue BIS certification pathways for Green Building Council-compliant occupancy sensors in commercial real estate retrofits. For Investors and Strategic Acquirers: Captive crystal growth specialists with FDA-registered packaging capabilities represent the most defensible acquisition profile in this market. Long-term viability hinges on dual-use export control navigation and REACH-compliant interconnect validation cycles. Watch ECHA candidate list expansions for lead-bearing solder restrictions as the inflection signal forcing packaging redesign investments.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lithium Tantalate Crystal Growth | Excelitas Technologies sustains margin control through in-house substrate production for medical imaging OEMs. |
| Digital Readout ASIC Integration | Microcontroller-compatible outputs eliminate external amplification stages for Stuttgart-based automotive Tier 1 suppliers. |
| REACH-Compliant Packaging Redesign | German packaging houses validate silver-epoxy interconnects through accelerated aging for FDA-registered device assemblers. |
| Multi-Channel Defense Array Qualification | Lynred anchors French national security procurement frameworks with ITAR-equivalent traceability requirements. |
| Automated Consumer Electronics Packaging | Murata Manufacturing compresses unit economics through Osaka-based production lines for motion sensing volumes. |
Research Methodology
A spread of perspectives from detector design engineers, automotive Tier 1 procurement managers, medical device regulatory affairs leads, and building automation system integrators converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from ECHA substance restriction filings, FDA 510(k) clearance databases, Euro NCAP technical protocols, and METI industrial automation incentive disclosures. Bottom-up unit shipment estimates triangulated against top-down value projections across product type, application, technology, and end user segmentation.
Segmentation dimensions modeled include digital versus analog detector architectures, automotive safety versus medical imaging versus building security applications, passive versus hybrid sensor technologies, and defense versus healthcare versus consumer electronics end user categories. CAGRs were derived through regression analysis of historical procurement patterns and regulatory mandate timelines, incorporating lithium tantalate crystal availability constraints and microbolometer substitution elasticities as industry-specific forecast inputs across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement or accelerated microbolometer cost reduction would require recalibration. Forecasts reflect assumptions around REACH authorization timelines for lead-bearing solders and Euro NCAP pedestrian protection protocol adoption rates. Revision becomes warranted when microbolometer price-performance ratios cross thresholds displacing pyroelectric detectors in sub-premium motion sensing applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Europe Portable Gas Detector Market