
 Global Gas Leak Detectors Market | 2026-2036
Global Gas Leak Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Leak Detectors Market Foresight
Sensor manufacturing capacity in East Asia is expanding to serve rising orders from petrochemical operators worldwide. MSA Safety leverages its vertical integration across sensing elements and calibration services to sustain pricing power in fixed detector installations. Honeywell International anchors its position through channel control with fire and safety distributors across North American industrial corridors. Dräger competes on R&D intensity in electrochemical sensing platforms for hazardous gas environments.
Gas leak detectors are instruments engineered to identify the presence of combustible, toxic, or oxygen-deficient gases in ambient air, typically employing electrochemical sensors with detection thresholds measured in parts per million or catalytic bead sensors calibrated for lower explosive limit percentages. These devices serve the primary industrial purpose of preventing explosions, asphyxiation incidents, and regulatory violations in enclosed or high-risk process areas. Fixed gas detectors dominate installed base value across petrochemical plants and refineries where continuous perimeter monitoring is mandated, while portable and wireless gas detectors represent the fastest-expanding category as maintenance crews adopt connected devices for confined-space entry protocols. Infrared gas detectors command premium positioning in applications requiring non-contact methane measurement and immunity to sensor poisoning.
The EPA enforces methane monitoring requirements under Clean Air Act amendments that directly shape detector specification standards for US oil and gas infrastructure operators. EMA safety directives and ATEX certification frameworks in Europe govern product market access and drive replacement cycles toward intrinsically safe designs. China's NMPA and GB standards for explosion-proof electrical equipment add a third compliance layer for manufacturers serving state-owned refinery expansions. Stakeholders must monitor how tightening jurisdictional standards for hydrogen infrastructure and carbon capture sites will redefine sensor portfolio requirements before the next capital planning cycle.
Market Dynamics
Tightening methane emission thresholds across multiple jurisdictions are forcing detector replacement cycles and specification upgrades faster than historical equipment lifecycles would predict.
Growth Catalysts
- EPA methane rules:US oil and gas infrastructure operators must deploy continuous monitoring systems at wellheads and compressor stations, creating mandated demand for fixed detector installations.
- Petrochemical capacity expansion:State-owned refinery operators in China are commissioning greenfield complexes with integrated safety systems, requiring explosion-proof detector specifications under GB standards.
- Wireless sensor networks:Maintenance crews in confined-space protocols are adopting battery-powered connected devices that transmit real-time alerts to central control rooms.
Market Restraints
- Semiconductor input volatility:MEMS sensing element fabrication depends on specialized foundry capacity concentrated in Taiwan, exposing detector manufacturers to wafer allocation constraints.
- Calibration gas supply concentration:Certified reference mixtures for sensor validation rely on a limited base of specialty gas suppliers in Germany and the United States.
- Electrochemical sensor poisoning:Catalytic bead detectors face performance degradation in sulfur-rich environments common to sour gas processing facilities.
Strategic Opportunities
- Hydrogen infrastructure buildout:Germany's H2 pipeline networks and refueling stations require new detector specifications for small-molecule leakage detection at pressures above conventional natural gas.
- Carbon capture and storage:CO2 transport and sequestration sites need specialized infrared detectors for high-concentration monitoring in dense phase conditions.
- Cloud-based predictive maintenance:Industrial safety distributors are bundling detector hardware with subscription analytics platforms that flag sensor drift before calibration failure.
Industry Challenges
- ATEX/IECEx certification timelines:Intrinsically safe design approvals for new wireless form factors face 12-18 month evaluation periods at notified bodies.
- Legacy system integration:Brownfield petrochemical plants operate 4-20 mA analog control architectures that resist digital retrofit without expensive signal converter deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Leak Detectors Market |
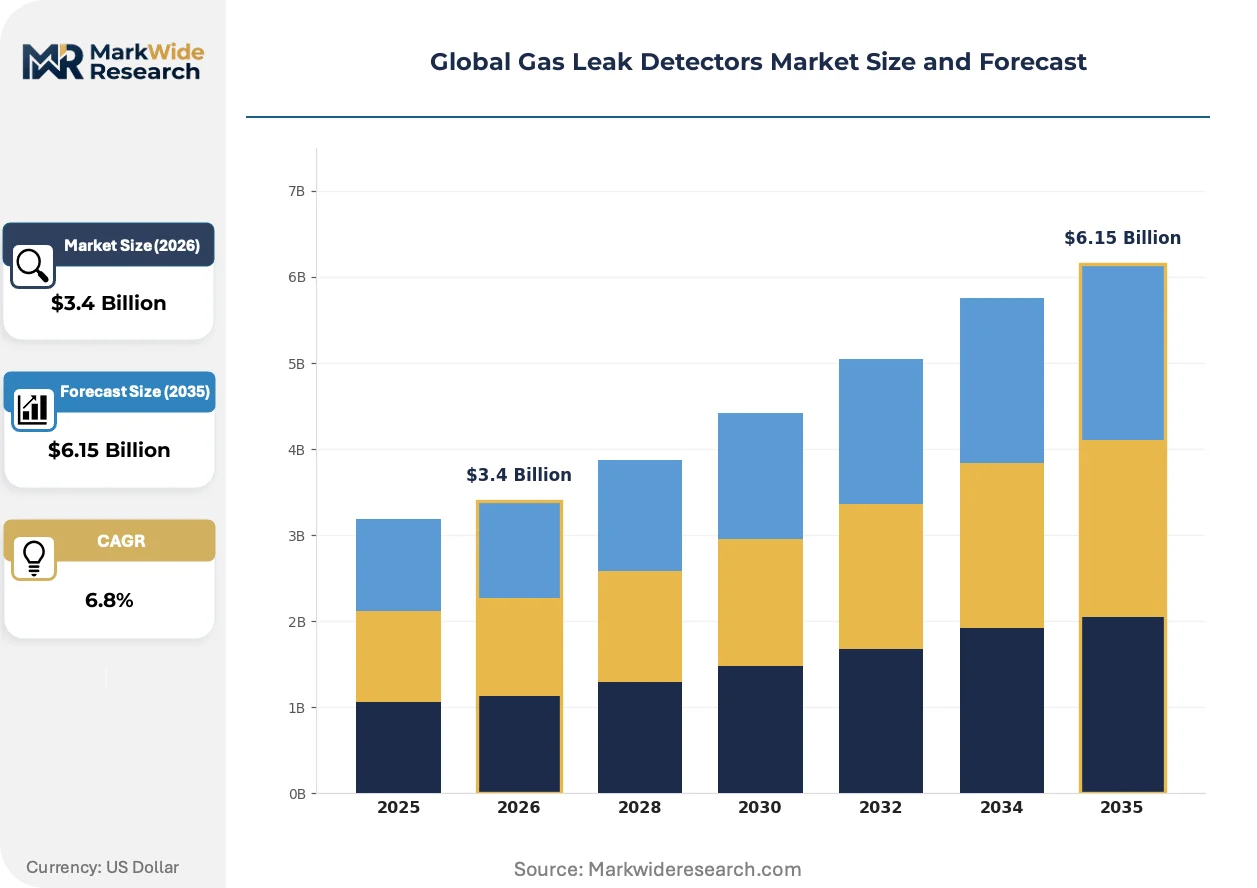
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Gas Detectors, Portable Gas Detectors, Wireless Gas Detectors, Handheld Gas Detectors, Infrared Gas Detectors Technology: Electrochemical Sensors, Catalytic Bead Sensors, Ultrasonic Sensors, Photoionization Detectors, Semiconductor Sensors Application: Petrochemical Plants, Refineries, Chemical Processing, HVAC Systems, Mining Operations End User Industry: Oil & Gas Companies, Manufacturing Facilities, Construction Firms, Environmental Agencies, Energy Providers |
| Companies Covered | MSA Safety, Honeywell International, Dräger, Industrial Scientific, Riken Keiki, Teledyne Technologies, Halma, New Cosmos Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Leak Detectors Market Shifts & Advancements
Sensor modalities and connectivity architectures are converging to enable predictive safety management rather than reactive alarm response.
Photoacoustic spectroscopy is overtaking traditional infrared absorption for methane quantification in unmanned aerial inspection applications. Pipeline operators in the Permian Basin and North Sea are deploying drone-mounted systems that eliminate the need for ground crew access to remote infrastructure. The technology is compressing survey cycle times from quarterly walks to continuous overflight coverage.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration and industrial processes, indirectly tightening requirements for leak detection system sensitivity in cold chain facilities. Industrial refrigeration operators must now install detectors with lower minimum detectable levels to comply with stepped reduction quotas. German chemical manufacturers are responding by specifying electrochemical sensors with sub-ppm resolution for ammonia and HFC blends.
Buyers are unbundling hardware procurement from calibration service contracts that historically locked in multi-year vendor relationships. Large petrochemical operators in the United States are tendering detector supply and maintenance as separate line items, opening specialist calibration houses to compete with original equipment manufacturers. This pattern is most visible in the Gulf Coast refinery corridor where third-party metrology labs have secured accredited status for EPA-mandated sensor verification protocols.
Global Gas Leak Detectors Market Segmentation
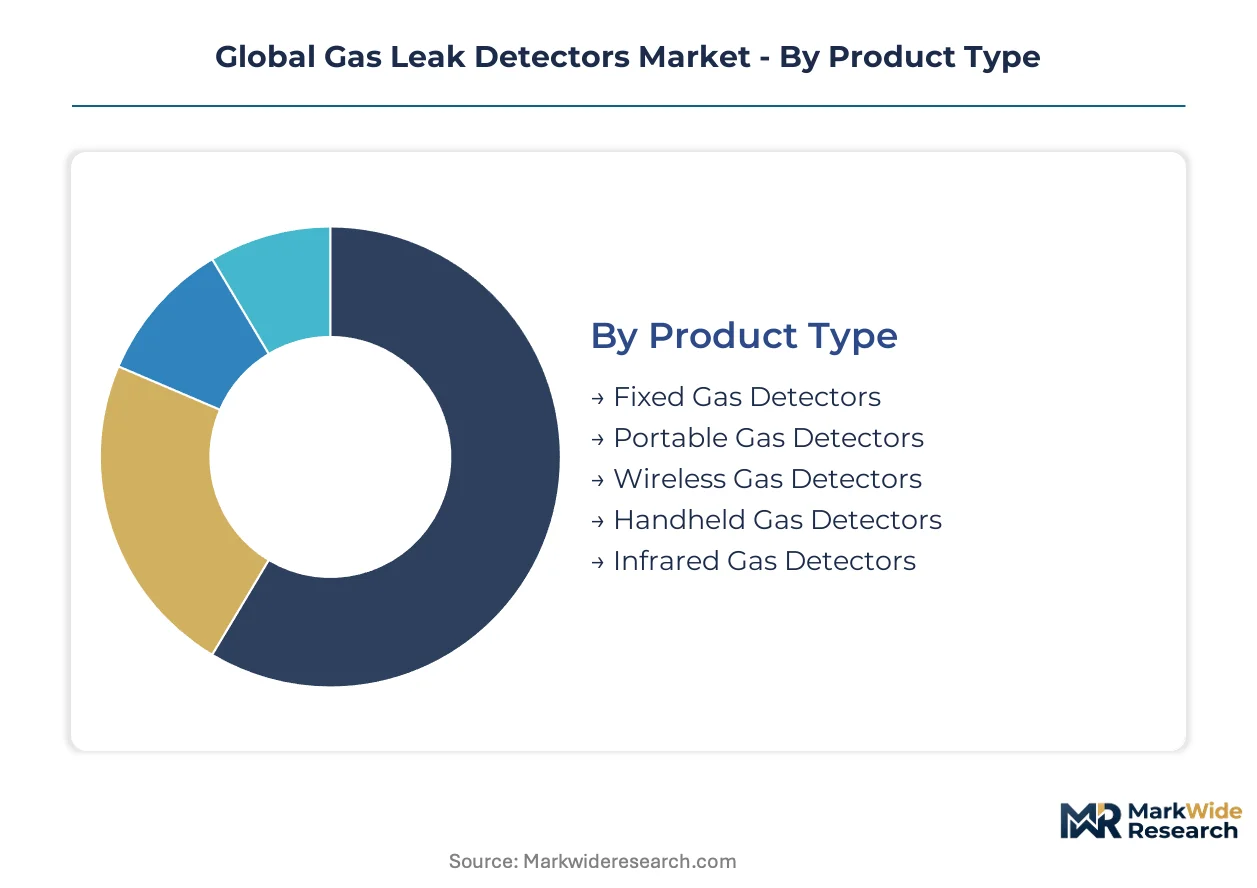
Gas leak detector procurement varies sharply by deployment context—continuous perimeter monitoring demands ruggedized fixed installations, while maintenance mobility drives portable and wireless adoption. Specification requirements diverge across electrochemical, infrared, and emerging photoacoustic technologies based on target gas chemistry and environmental conditions.
Product Type:
Fixed detectors dominate installed base value through mandate-driven replacement cycles, while wireless units capture the steepest expansion trajectory as connected safety protocols penetrate confined-space operations.
- Fixed Gas Detectors:Hardened enclosures with 4-20 mA or digital outputs provide continuous perimeter surveillance at US wellheads and EU refinery boundaries. EPA methane rules and ATEX certification requirements force replacement cycles faster than historical equipment lifecycles would predict.
- Wireless Gas Detectors:Battery-powered mesh networks transmit real-time alerts from confined-space entries to central control rooms, eliminating cabling costs in brownfield retrofits. Chinese state-owned refineries specify explosion-proof wireless nodes under GB standards for greenfield complexes.
- Portable Gas Detectors:Personal monitors with electrochemical or catalytic bead sensors clip to worker harnesses during tank cleaning and turnaround maintenance.
- Handheld Gas Detectors:Spot-check instruments serve leak survey crews performing regulatory compliance walks at compressor stations.
- Infrared Gas Detectors:Non-contact open-path systems command premium positioning for methane quantification across fence-line monitoring applications.
Today's leader: Fixed Gas Detectors. Tomorrow's challenger: Wireless Gas Detectors.
Technology:
Electrochemical platforms anchor mainstream demand through cost-calibrated sensitivity, while photoacoustic spectroscopy gains inspection applications requiring drone-mounted methane quantification.
- Electrochemical Sensors:Three-electrode cells with polymer electrolytes detect toxic gases at ppm thresholds across petrochemical process areas. German chemical manufacturers specify sub-ppm resolution units for ammonia and HFC blend monitoring under stepped F-Gas reduction quotas.
- Catalytic Bead Sensors:Wheatstone bridge configurations calibrated for lower explosive limit percentages serve combustible gas detection in upstream oilfield infrastructure. Performance degradation in sulfur-rich sour gas environments limits deployment scope.
- Ultrasonic Sensors:Acoustic leak detection bypasses gas-specific calibration for pressurized system monitoring.
- Photoionization Detectors:UV lamp ionization enables volatile organic compound detection at ppb sensitivity for environmental monitoring.
- Semiconductor Sensors:Metal oxide films offer cost-minimized detection for residential and light commercial applications.
Electrochemical Sensors retain volume leadership. Photoacoustic methods gain fastest in aerial inspection niches.
Application:
Petrochemical and refinery deployments concentrate procurement volume through integrated safety system mandates, while HVAC applications expand through refrigeration leak detection compliance.
- Petrochemical Plants:Integrated gas detection architectures with SIL-rated logic solvers protect ethylene crackers and aromatics complexes. Chinese greenfield commissions require GB-standard explosion-proof specifications across perimeter and process unit coverage.
- Refineries:Catalytic reforming and hydrotreating units demand multi-gas detection for hydrogen sulfide and benzene exposure limits. US Gulf Coast operators unbundle hardware procurement from calibration contracts to third-party metrology labs.
- Chemical Processing:Batch and continuous reactors require toxic gas monitoring for chlorine and phosgene handling.
- HVAC Systems:Commercial and industrial refrigeration operators install stepped-sensitivity detectors to comply with EU F-Gas phase-down quotas.
- Mining Operations:Underground coal and hard-rock extraction mandates methane and carbon monoxide monitoring for worker safety.
Petrochemical Plants command current procurement scale. HVAC Systems face the most steepening compliance curve.
End User Industry:
Oil and gas operators drive specification standards through regulatory mandate density, while environmental agencies shape verification protocols that ripple across industrial procurement.
- Oil & Gas Companies:Upstream and downstream operators deploy continuous monitoring networks at wellheads, compressor stations, and storage terminals. EPA Clean Air Act amendments directly shape detector specifications for US infrastructure.
- Manufacturing Facilities:Automotive paint shops and semiconductor fabs specify VOC and toxic gas detection for process safety and product quality.
- Construction Firms:Tunneling and underground utility projects mandate portable multi-gas detection for confined-space entry protocols.
- Environmental Agencies:Regulatory enforcement bodies accredit calibration laboratories and audit compliance monitoring systems.
- Energy Providers:Natural gas utilities and hydrogen pipeline operators specify leak detection for distribution network integrity.
Oil & Gas Companies set technical standards. Energy Providers face the most radical specification shift with hydrogen infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping detector procurement patterns as manufacturers relocate assembly capacity toward jurisdictions with streamlined ATEX and GB certification pathways. Cost-of-compliance gaps between notified bodies in Europe and test laboratories in East Asia are accelerating sourcing diversification.
United States
Upstream operators in the Permian Basin and Appalachian shale corridors are deploying continuous methane monitoring networks at wellheads and compressor stations. EPA Clean Air Act amendments mandate specific detection thresholds that force faster replacement cycles than historical equipment lifespans. Gulf Coast refineries in Texas and Louisiana are unbundling hardware procurement from calibration contracts to third-party metrology labs.
Germany
Industrial refrigeration operators face stepped sensitivity requirements under EU F-Gas Regulation phase-down quotas for hydrofluorocarbon use. Chemical manufacturers in the Rhine-Ruhr and Ludwigshafen clusters specify electrochemical sensors with sub-ppm resolution for ammonia and HFC blend monitoring. Hydrogen pipeline networks and H2 refueling stations require new detector specifications for small-molecule leakage detection at elevated pressures.
China
State-owned refinery operators are commissioning greenfield petrochemical complexes with integrated safety systems requiring explosion-proof detector specifications under GB standards. NMPA certification frameworks for explosion-proof electrical equipment add compliance layers for manufacturers serving Sinopec and PetroChina expansions. Yangtze River Delta industrial zones concentrate detector procurement for ethylene crackers and aromatics complexes.
Japan
Automotive paint shops and semiconductor fabrication facilities specify VOC and toxic gas detection for process safety and product quality assurance. METI industrial safety directives drive adoption of intrinsically safe wireless form factors in confined-space maintenance protocols. Osaka-Kobe chemical corridor operators are integrating cloud-based predictive maintenance platforms with existing detector networks.
Saudi Arabia
Aramco upstream and downstream infrastructure expansion is concentrating procurement volume for fixed detector installations at wellheads, gas processing trains, and export terminals. The country's national oil company mandates SIL-rated logic solvers across new greenfield commissions in the Eastern Province. Jubail Industrial City complexes require multi-gas detection for hydrogen sulfide exposure limits in sour gas processing units.
Global Gas Leak Detectors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless connectivity and drone-mounted inspection niches. The vendor base stratifies across three maturity tiers: diversified safety conglomerates with captive distribution, electrochemical specialists with R&D intensity in hazardous environments, and regional fabricators serving price-sensitive procurement in developing markets. Competitive positioning depends on certification velocity, calibration service bundling, and backward integration into sensing element fabrication. M&A activity targets wireless sensor network capabilities and photoacoustic spectroscopy IP. Geographic expansion concentrates on Chinese state-owned refinery corridors and German hydrogen infrastructure clusters.
Among diversified safety conglomerates, MSA Safety and Honeywell International exemplify archetypes with channel control across North American industrial corridors and vertical integration into calibration services. Dräger occupies a position representing R&D-intensive specialists in electrochemical sensing platforms. These three anchors illustrate how competitive positioning separates players with captive distribution infrastructure from those competing on sensor modality innovation or regional price positioning.
| Leading Market Players |
|---|
| MSA Safety |
| Honeywell International |
| Dräger |
| Industrial Scientific |
| Riken Keiki |
| Teledyne Technologies |
| Halma |
| New Cosmos Electric |
| ABB |
| Others |
Supply & Pricing Matrix
EPA methane monitoring mandates gate qualified supply access and premium-tier pricing power for detector manufacturers serving US oil and gas infrastructure operators. Buyers seeking ATEX-certified or intrinsically safe wireless form factors face extended lead times and elevated procurement costs compared to standard fixed-installation units.
Pricing Analysis
Distributor margins in fire and safety channels absorb 25-35 points before reaching end-user procurement teams at petrochemical operators. Three-tier pricing structure across premium, standard, and economy levels separates SIL-rated logic solver integrations from basic catalytic bead configurations. Cost compression in economy-tier portable units is intensifying because Chinese regional fabricators are flooding developing markets with unbundled hardware. Refinery procurement teams in the US Gulf Coast demonstrate highest price sensitivity through competitive tendering of calibration services separately from detector supply.
Supply Chain Analysis
Specialized sensor assembly labor availability in Malaysia and Vietnam is expanding as manufacturers diversify from Taiwan concentration risks. MEMS sensing element fabrication draws from semiconductor foundry capacity concentrated in Taiwan, South Korea, and Japan. Single-source vulnerability in certified reference gas mixtures from German and US specialty suppliers creates calibration bottlenecks. Distribution runs through captive fire and safety distributor networks across North American industrial corridors and direct OEM relationships for Chinese state-owned refinery projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA methane rules and EU F-Gas phase-down quotas generate replacement-cycle demand independent of macroeconomic cycles.
For Market Incumbents: Deploy backward integration into electrochemical sensing element fabrication to defend margin position against emerging entrants with modular wireless platforms. Accelerate ATEX/IECEx certification velocity for new form factors before 12-18 month evaluation periods erode first-mover advantage in hydrogen infrastructure specifications. Channel control with fire and safety distributors remains the priority defensive lever against unbundled procurement trends. For New Entrants and Emerging Players: Industrial safety distributors represent the most accessible channel partner type for penetrating brownfield retrofit opportunities without captive OEM relationships. Target wireless gas detector deployments in Chinese greenfield refinery complexes where GB-standard explosion-proof specifications create certification barriers for established Western suppliers. Photoacoustic spectroscopy IP for drone-mounted methane inspection offers the most penetrable technology white space against infrared incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service specialists because unbundled procurement trends are fragmenting maintenance relationships away from original equipment manufacturers. Five-to-ten year viability hinges on hydrogen infrastructure buildout velocity and carbon capture site commissioning rates. Watch German H2 pipeline network deployment timelines as the critical inflection signal for small-molecule detector specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Photoacoustic Spectroscopy Acquisition | Drone-mounted methane inspection compresses survey cycles from quarterly walks to continuous coverage in Permian Basin operations. |
| Wireless Sensor Network Partnership | Battery-powered mesh protocols penetrate confined-space maintenance protocols at Chinese state-owned refinery greenfield sites. |
| Calibration Service Unbundling | Third-party metrology labs secure EPA-accredited status for sensor verification protocols in US Gulf Coast refinery corridors. |
| Hydrogen Infrastructure Certification Investment | Intrinsically safe design approvals for elevated-pressure small-molecule detection access German H2 refueling station specifications. |
| Cloud-Based Predictive Maintenance Platform Launch | Subscription analytics bundling with detector hardware flags sensor drift before calibration failure at Japanese semiconductor fabs. |
Research Methodology
Direct dialogue with plant safety managers, OEM procurement leads at detector manufacturers, fire and safety distributor principals, and calibration laboratory technical directors grounded qualitative insights. Secondary validation drew from EPA enforcement databases, ATEX/IECEx certification registries, Chinese GB standards documentation, and petrochemical operator tender filings. Bottom-up unit deployment estimates across wellhead, refinery, and industrial refrigeration applications triangulated against top-down market value reconstruction.
Segment-level outputs across fixed, wireless, portable, and infrared product types combined with electrochemical, catalytic bead, and photoacoustic technology splits populated the analytical framework across the projection horizon. CAGRs emerged from regression against regulatory mandate implementation schedules and capital expenditure patterns at named national oil companies. Hydrogen infrastructure commissioning timelines and carbon capture site development rates served as industry-specific demand drivers in the forward model.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry allocation constraints and ATEX certification backlog durations. Assumptions reflect current regulatory enforcement trajectories without contingency for mandate delay or acceleration. Material deviation in EPA methane rule implementation or EU F-Gas phase-down quotas warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Null Detector Market