
 Hitoxic Gas Detector Market | 2026-2036
Hitoxic Gas Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Hitoxic Gas Detector Market Foresight
UL 2075 certification for gas and vapor detectors is collapsing the competitive field to suppliers with certified manufacturing pipelines and documented field performance. Honeywell International leverages its distributed sensing architecture to sustain dominance across North American industrial corridors. Drägerwerk AG & Co. KGaA anchors European demand through specialized breathing apparatus integration and portables calibrated to German DIN standards. Riken Keiki competes aggressively in East Asian shipbuilding and semiconductor fabrication environments with electrochemical platforms optimized for hydrogen sulfide and phosphine detection.
A hitoxic gas detector is an instrument engineered to identify and quantify toxic gas concentrations through sensor technologies capable of detecting parts-per-million thresholds, typically employing electrochemical cells or infrared absorption spectroscopy to trigger alarms before exposure limits breach occupational safety thresholds. Fixed detector installations dominate capital expenditure in oil and gas processing and chemical manufacturing, where continuous perimeter monitoring replaces periodic manual checks. Portable detector demand accelerates in construction sites and confined-space operations, driven by OSHA-mandated pre-entry atmospheric testing protocols. Wireless detector adoption expands fastest among laboratories and distributed manufacturing plants seeking real-time cloud-integrated hazard dashboards without hardwired infrastructure.
FDA oversight of medical gas delivery systems, OSHA permissible exposure limits for toxic substances, and EPA National Emission Standards for Hazardous Air Pollutants collectively mandate detector deployment across healthcare, industrial, and environmental monitoring contexts. The EPA's Risk Management Program and OSHA Process Safety Management standards require facilities handling threshold quantities of regulated substances to install fixed detection networks with documented calibration records. Stakeholders must monitor evolving sensor miniaturization trends and emerging interoperability standards that will determine whether integrated platform providers or specialized sensor manufacturers capture margin pools in next-generation safety systems.
Market Dynamics
UL 2075 certification requirements are compressing the supplier base, favoring manufacturers with certified production pipelines and documented field performance histories over unverified entrants.
Growth Catalysts
- OSHA Confined-Space Rules:United States occupational safety mandates require pre-entry atmospheric testing in tanks, vessels, and underground structures, accelerating portable detector deployment across construction and petrochemical maintenance operations.
- Electrochemical Sensor Miniaturization:Reduced form factors enable integration into personal protective equipment and drone-mounted monitoring systems for perimeter surveillance.
- Gulf Coast Petrochemical Corridor:Refinery and chemical plant density in Texas and Louisiana drives replacement cycles and new fixed-installation demand as facilities modernize aging detection networks.
Market Restraints
- Semiconductor Supply Concentration:Sensor microcontrollers and signal processing chips depend on concentrated East Asian foundry capacity, exposing detector manufacturers to input volatility.
- Calibration Infrastructure Gaps:Remote oil and gas facilities in North Dakota and Wyoming lack local certified calibration services, extending downtime and compliance risk.
- Electrochemical Cell Degradation:Sensor drift in high-humidity environments limits deployment reliability in tropical chemical processing zones without climate-controlled enclosures.
Strategic Opportunities
- EPA Risk Management Program Expansion:Threshold quantity revisions for regulated substances could mandate fixed detection networks at smaller chemical handling facilities previously exempt.
- Wireless Cloud Integration:Laboratories and distributed manufacturing plants seek battery-powered detectors with real-time dashboard connectivity, bypassing hardwired infrastructure costs.
- Semiconductor Fabrication:Phosphine and arsine detection requirements in wafer manufacturing create specialized demand for sub-ppm electrochemical platforms in Arizona and Oregon fabrication clusters.
Industry Challenges
- Certification Timeline Compression:UL 2075 and IEC 60079-29-1 testing protocols require 12-18 month validation cycles, delaying product launches and freezing R&D roadmaps.
- Legacy System Integration:Hardwired 4-20mA detector networks in aging refineries resist retrofit with digital Modbus or wireless protocols without complete control system overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hitoxic Gas Detector Market |
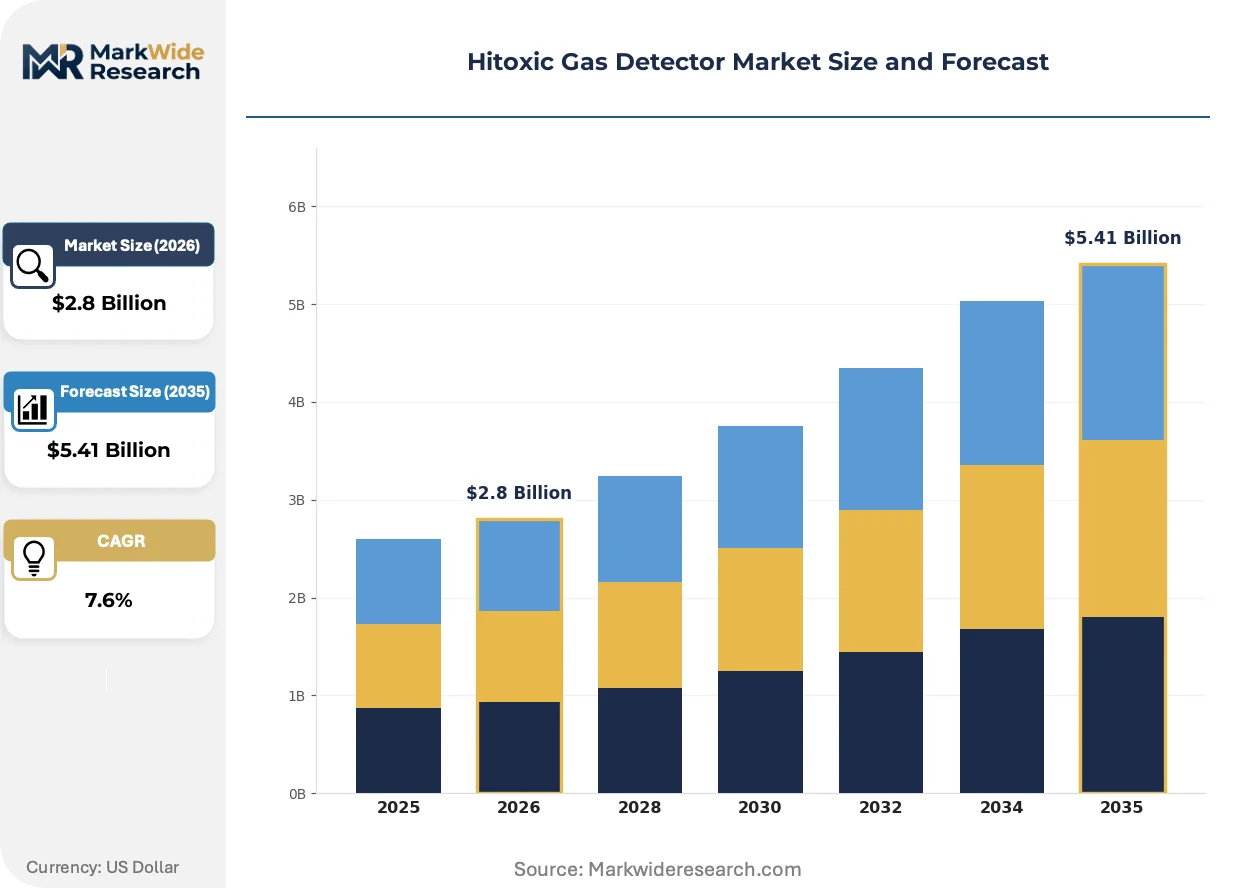
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Multi-Gas Detectors, Wireless Detectors Application: Industrial Safety, Environmental Monitoring, Occupational Health, Home Safety End User: Manufacturing Plants, Oil & Gas, Laboratories, Construction Sites Technology: Electrochemical Sensors, Infrared Sensors, Catalytic Sensors, PID Sensors |
| Companies Covered | Honeywell International, MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, RKI Instruments Inc, Emerson Electric Co, Industrial Scientific Corporation, Riken Keiki, Siemens AG, Det-Tronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hitoxic Gas Detector Market Shifts & Advancements
Photonics-based detection architectures and predictive maintenance algorithms are restructuring how industrial facilities monitor atmospheric hazards, shifting from reactive alarm systems to continuous exposure analytics.
Photoacoustic spectroscopy is displacing traditional electrochemical cells in refinery perimeter monitoring. Saudi Aramco and ExxonMobil facilities in the Gulf Coast are piloting these solid-state platforms for hydrogen sulfide detection at sub-ppm thresholds. The technology eliminates sensor drift and replacement schedules, compressing total cost of ownership for continuous monitoring applications.
EPA National Emission Standards for Hazardous Air Pollutants are tightening leak detection and repair protocols across chemical manufacturing. The 2024 amendments expand monitoring requirements to storage tanks and loading racks previously exempt from continuous surveillance. Process Safety Management coordinators in Texas and Louisiana chemical plants are retrofitting fixed detector grids to capture fugitive emission events in real time.
Refinery procurement departments are consolidating detector purchases under multi-year framework agreements with integrated safety system providers. Spot-market transactions through industrial distributors are losing share to bundled contracts covering calibration, replacement sensors, and cloud analytics subscriptions. This concentration is most visible along the Houston Ship Channel, where integrated procurement reduces vendor management overhead across sprawling multi-site operations.
Hitoxic Gas Detector Market Segmentation
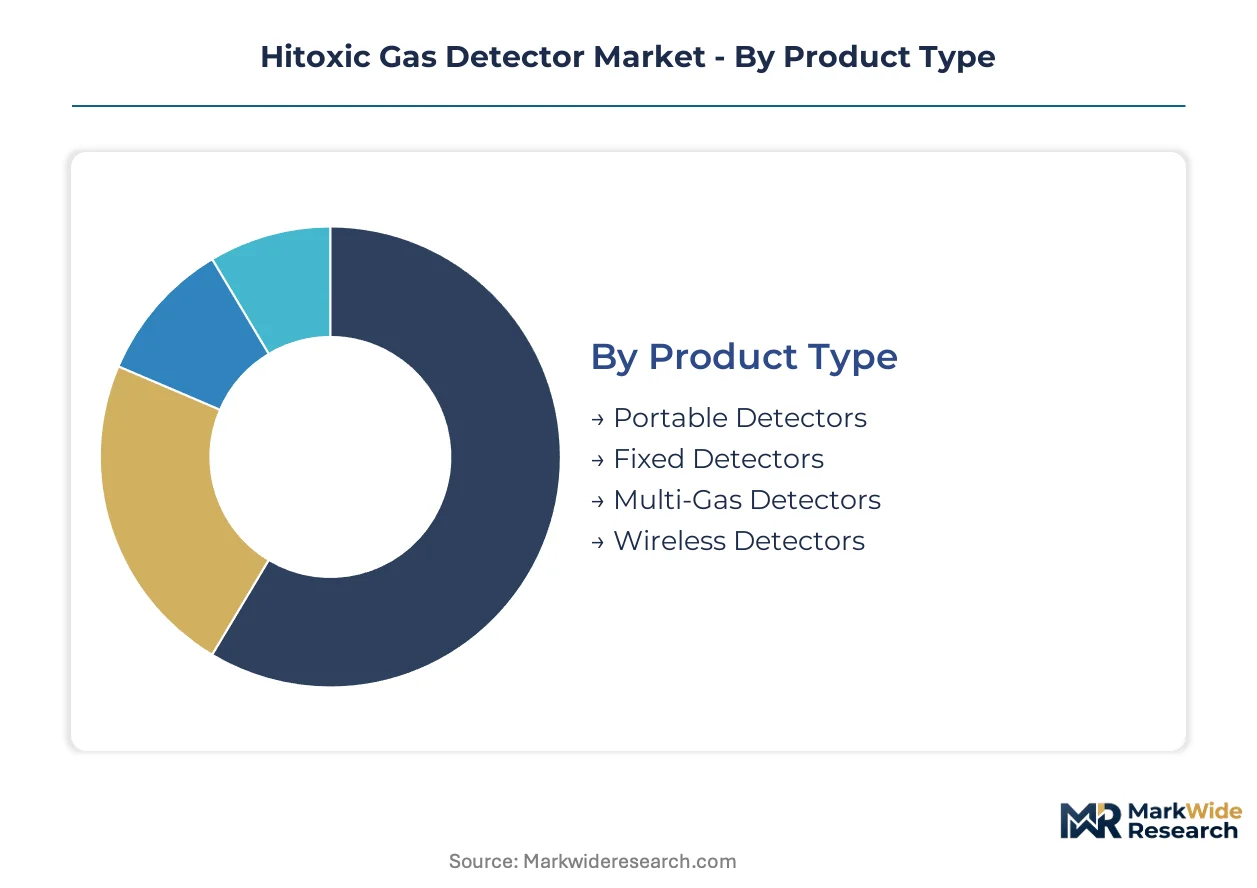
Hitoxic gas detector procurement patterns diverge sharply across product configurations and deployment contexts. Segment boundaries reflect distinct compliance regimes, sensor technology maturities, and capital intensity requirements that reshape vendor priorities and customer switching costs.
Product Type:
Fixed detector demand concentrates in domestic Gulf Coast petrochemical installations, while portable and wireless platforms drive export-led growth into Southeast Asian shipbuilding and Middle Eastern construction markets.
- Portable Detectors:Battery-powered units weighing under 500 grams integrate electrochemical cells calibrated to OSHA permissible exposure limits for confined-space pre-entry testing. Demand clusters in Texas and Louisiana construction maintenance crews, where OSHA mandates pre-work atmospheric verification. Replacement cycles compress to 18-24 months in high-usage environments.
- Fixed Detectors:Hardwired perimeter installations employ 4-20mA or Modbus outputs for continuous refinery and chemical plant monitoring. Gulf Coast facilities in Texas and Louisiana dominate capital deployment, driven by EPA Risk Management Program requirements for threshold quantity facilities.
- Multi-Gas Detectors:Simultaneous H2S, CO, and LEL detection platforms serve offshore platform maintenance and semiconductor fabrication facilities in Oregon and Arizona.
- Wireless Detectors:Battery-powered cloud-integrated units bypass hardwired infrastructure for distributed manufacturing plants and laboratory networks seeking real-time dashboard visibility.
Fixed detectors command the established base. The steepest expansion runs through wireless platforms.
Application:
Cost tier stratification separates high-compliance industrial safety deployments from lower-price environmental monitoring and residential applications.
- Industrial Safety:Continuous perimeter monitoring systems in oil and gas processing and chemical manufacturing replace periodic manual checks with automated alarm networks. OSHA Process Safety Management standards mandate fixed detection grids with documented calibration records at threshold quantity facilities.
- Environmental Monitoring:Fugitive emission detection for EPA National Emission Standards compliance deploys photoacoustic spectroscopy platforms at sub-ppm thresholds. Refinery loading racks and storage tanks in the Gulf Coast corridor drive retrofit demand following tightened leak detection protocols.
- Occupational Health:Personal exposure monitoring in welding and confined-space operations employs wearable electrochemical badges with data logging for compliance documentation.
- Home Safety:Consumer-grade carbon monoxide and natural gas detectors compete on price in retail channels, with limited overlap with industrial-grade hitoxic specifications.
Industrial safety absorbs the dominant share of capital expenditure. Environmental monitoring is climbing the fastest as regulatory thresholds tighten.
End User:
Customer type fragmentation separates asset-intensive process industries from project-based construction and discrete manufacturing environments.
- Manufacturing Plants:Semiconductor fabrication facilities in Arizona and Oregon require sub-ppm phosphine and arsine detection for wafer processing cleanrooms. Electrochemical platforms with specialized calibration protocols dominate this precision segment.
- Oil & Gas:Upstream and midstream operators across Texas, Louisiana, and North Dakota deploy combined fixed and portable networks for hydrogen sulfide monitoring. Remote wellpad locations in Wyoming and North Dakota face calibration infrastructure gaps that extend sensor downtime.
- Laboratories:Research and quality control facilities prioritize wireless cloud-integrated detectors for flexible reconfiguration without hardwired infrastructure investment.
- Construction Sites:Project-based demand for confined-space entry testing accelerates portable detector rental and short-term procurement cycles.
Oil and gas maintains the largest installed base. Semiconductor fabrication represents the steepest expansion trajectory.
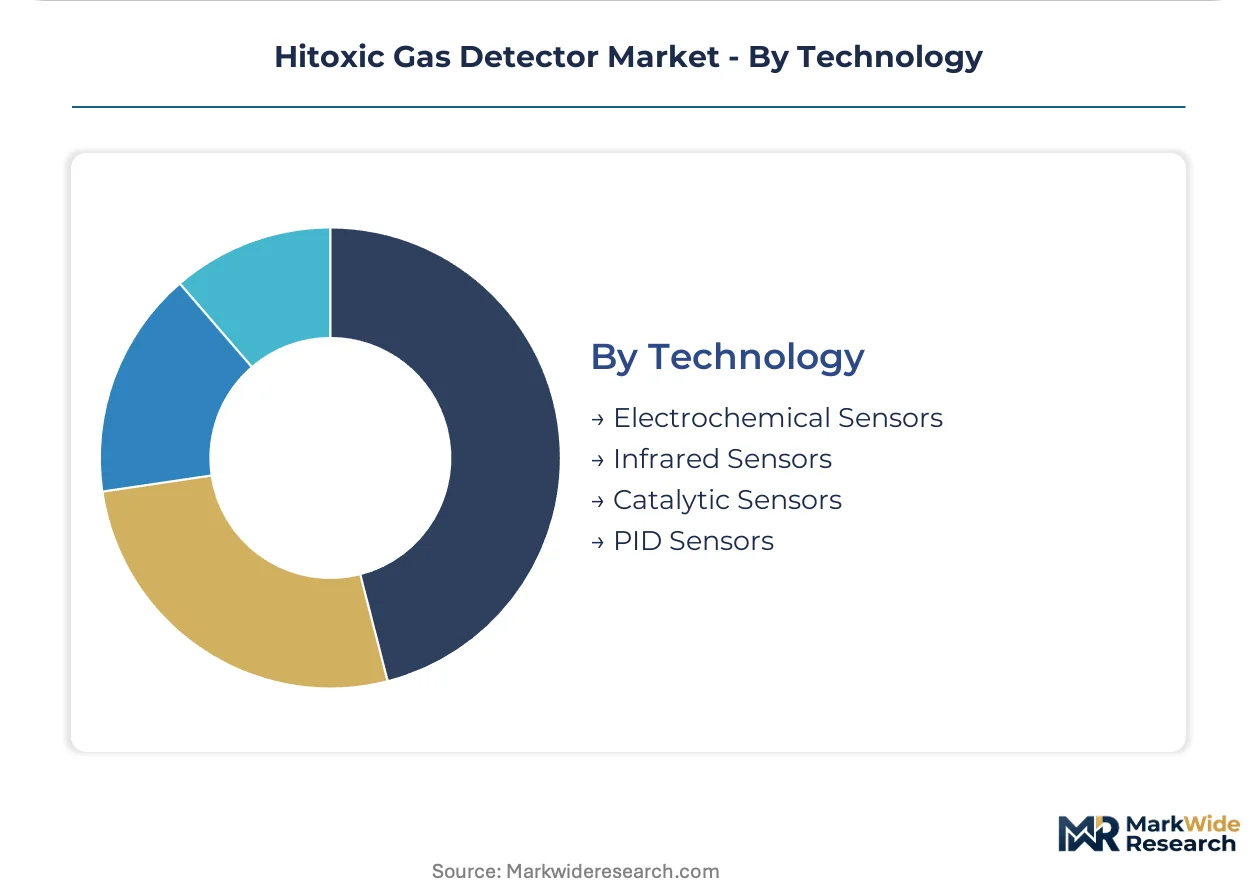
Technology:
Supply concentration in sensor microcontrollers and signal processing chips creates input volatility that favors electrochemical and infrared platforms with established foundry relationships over emerging photonics architectures.
- Electrochemical Sensors:Amperometric cells detect hydrogen sulfide, carbon monoxide, and phosphine at ppm thresholds through redox reactions at catalytic electrodes. Humidity sensitivity limits tropical deployment without climate-controlled enclosures.
- Infrared Sensors:Non-dispersive infrared absorption spectroscopy measures hydrocarbon and carbon dioxide concentrations without sensor drift or calibration drift in refinery perimeter applications. Saudi Aramco and ExxonMobil Gulf Coast facilities pilot solid-state replacements for electrochemical maintenance schedules.
- Catalytic Sensors:Wheatstone bridge configurations detect combustible gas concentrations through catalytic oxidation, dominating LEL detection in general industrial safety applications.
- PID Sensors:Photoionization detection platforms measure volatile organic compounds at ppb thresholds for environmental remediation and indoor air quality assessment.
Electrochemical technology anchors the established base. Infrared platforms are expanding most quickly as solid-state architectures displace maintenance-intensive alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical operators and semiconductor fabricators drive detector procurement across concentrated industrial corridors. Regulatory tightening in emissions monitoring and confined-space safety reshapes replacement cycles. Regional demand clusters where OSHA, EPA, and their international counterparts enforce compliance mandates.
United States
Gulf Coast refinery density and shale expansion sustain fixed detector deployment across Texas and Louisiana. OSHA Process Safety Management standards mandate continuous monitoring networks at threshold quantity facilities. Houston Ship Channel chemical plants retrofit aging hardwired systems with cloud-integrated architectures.
Germany
Industrial safety equipment exports and DIN-standard breathing apparatus integration anchor European demand. REACH chemical safety regulations and the EU Green Deal emissions targets tighten leak detection obligations. Ruhr Valley chemical clusters and Bavarian automotive paint shops drive portable detector replacement programs.
China
Semiconductor fabrication expansion and port chemical handling accelerate sub-ppm detection requirements. MEE air quality standards and GB industrial safety codes mandate detector networks at hazardous chemical facilities. Yangtze River Delta wafer fabs and Tianjin petrochemical terminals deploy phosphine and hydrogen sulfide monitoring grids.
Saudi Arabia
Upstream hydrogen sulfide monitoring and refinery modernization sustain fixed installation demand. SFDA industrial safety oversight and Saudi Aramco procurement standards require certified detection networks. Jubail Industrial City and Yanbu petrochemical complexes pilot solid-state photoacoustic platforms for perimeter surveillance.
Japan
Shipbuilding safety protocols and electronics cleanroom monitoring sustain specialized electrochemical demand. METI industrial safety guidelines and JIS calibration standards enforce documented detector maintenance. Nagoya automotive manufacturing corridors and Yokohama port facilities deploy multi-gas portable units for confined-space operations.
Hitoxic Gas Detector Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with certified manufacturing pipelines and integrated safety system portfolios. The field compresses around UL 2075 and IEC 60079-29-1 certification holders with documented field performance histories. Three archetypes dominate: integrated platform providers bundling calibration and cloud services, specialized sensor manufacturers with electrochemical expertise, and regional safety equipment distributors with local service networks. Competitive moves center on multi-year framework agreements covering replacement sensors and analytics subscriptions, plus technology licensing for solid-state photonics architectures.
Among diversified industrial conglomerates, Honeywell International and Siemens AG exemplify the integrated platform archetype with distributed sensing architectures spanning multiple industrial corridors. Drägerwerk AG & Co. KGaA occupies a specialist position within European breathing apparatus and portable detection markets. These three represent contrasting strategic postures: scale-driven bundling, regional certification depth, and specialized integration expertise.
| Leading Market Players |
|---|
| Honeywell International |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| RKI Instruments Inc |
| Emerson Electric Co |
| Industrial Scientific Corporation |
| Riken Keiki |
| Siemens AG |
| Det-Tronics |
| Others |
Supply & Pricing Matrix
UL 2075 certification gates both supplier qualification and price differentiation in the hitoxic gas detector market, compressing the vendor base to certified manufacturers while stratifying pricing across certification tiers and bundled service levels. Buyers face asymmetric information costs when evaluating uncertified alternatives, amplifying price premiums for documented field performance histories.
Pricing Analysis
Cost-plus contracts with semiconductor input indexation dominate procurement frameworks for fixed detector networks, linking final pricing to microcontroller and signal processing chip spot markets. Three-tier pricing structure across premium, standard, and economy levels separates cloud-integrated platform subscriptions from transactional hardware sales and unbundled sensor replacements. Cost compression in the portable detector tier is intensifying because electrochemical cell commoditization erodes brand premiums. Construction rental fleets exhibit highest price sensitivity; semiconductor fabrication facilities show lowest due to sub-ppm calibration precision requirements.
Supply Chain Analysis
Inbound logistics costs from East Asian foundry ports through Los Angeles and Long Beach container terminals have amplified working capital requirements for detector manufacturers dependent on just-in-time sensor microcontroller delivery. Manufacturing concentration clusters in China, Germany, and the United States, with final assembly drawing from Taiwanese semiconductor foundries and Japanese electrochemical cell suppliers. Single-source vulnerability in 40nm sensor microcontroller fabrication exposes procurement timelines to foundry capacity allocation decisions. Distribution runs through integrated safety system providers with captive calibration service networks, displacing spot-market industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoacoustic spectroscopy commercialization is disrupting electrochemical incumbents, creating asymmetric growth windows for solid-state platform investors while compressing replacement-revenue streams for legacy sensor manufacturers.
For Market Incumbents: Consolidate calibration infrastructure through acquisition of regional service networks in North Dakota and Wyoming, closing the maintenance gap that extends competitor downtime. Anchor cloud platform subscriptions with multi-year sensor replacement clauses, locking out standalone hardware vendors before wireless adoption accelerates in laboratory segments. For New Entrants and Emerging Players: Remote calibration service gaps in upstream oil and gas territories present the most penetrable white-space for mobile service units targeting Wyoming wellpads and North Dakota shale plays. Target semiconductor fabrication facilities in Arizona and Oregon with sub-ppm phosphine detection specialization, bypassing generalist incumbents through DIN-standard calibration protocols and cleanroom installation expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless cloud-integrated detector sub-segments as battery chemistry improvements reduce hardware refresh cycles. Acquire electrochemical specialists with established UL 2075 pipelines rather than greenfield certification investments. Watch EPA Risk Management Program threshold quantity revisions as the signal indicating fixed network mandate expansion into smaller chemical handling facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Real-time dashboard connectivity bypasses hardwired infrastructure costs for distributed manufacturing plants. |
| Photoacoustic Spectroscopy Licensing | Solid-state architectures eliminate sensor drift maintenance schedules at Saudi Aramco Gulf Coast facilities. |
| Regional Calibration Network Expansion | Mobile service units capture stranded demand in Wyoming and North Dakota remote wellpad locations. |
| Semiconductor Fabrication Specialization | Sub-ppm phosphine detection platforms penetrate Arizona and Oregon wafer manufacturing cleanrooms. |
| Multi-Year Framework Agreements | Bundled procurement contracts reduce vendor management overhead across Houston Ship Channel chemical plants. |
Research Methodology
A standing panel of process safety managers, refinery procurement directors, semiconductor fabrication facility engineers, and calibration service technicians provided ongoing calibration against secondary data streams. Primary interviews with OSHA compliance officers and EPA Risk Management Program coordinators cross-referenced against UL certification databases, SEC 10-K equipment disclosures, and customs import records for electrochemical cell and infrared sensor components. Bottom-up unit deployment estimates triangulated with top-down capital expenditure tracking across the Gulf Coast petrochemical corridor.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product configuration, application compliance tier, end-user industry vertical, and sensor technology architecture. CAGRs derived from installed base replacement cycles and regulatory mandate implementation timelines. Forecast inputs incorporated OSHA confined-space enforcement intensity indices and EPA leak detection protocol amendment scopes.
Material uncertainties — semiconductor foundry capacity allocation shifts, EPA threshold quantity revisions, and photoacoustic spectroscopy field validation failures — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and electrochemical cell supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market