
 Electronic Article Surveillance Market | 2026-2036
Electronic Article Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Article Surveillance Market Intelligence
CE marking under the EU Radio Equipment Directive is bifurcating the competitive landscape for radio frequency and acousto-magnetic systems. Sensormatic Solutions leverages its vertical integration across tag manufacturing and detection hardware to sustain pricing power in North American big-box retail. Checkpoint Systems anchors its position through deep channel partnerships with European supermarket operators. Nedap NV differentiates by specializing in high-frequency RFID-electromagnetic hybrid platforms for warehouse environments.
Electronic article surveillance encompasses integrated anti-theft systems combining detection antennas, disposable or reusable tags, and deactivation equipment operating at defined radio frequency or electromagnetic field parameters. These systems detect unauthorized removal of merchandise by sensing resonant circuit disruption or magnetic bias saturation at exit points. Radio frequency systems dominate unit volume in retail apparel, while combination systems represent the fastest-expanding segment as multi-technology floorspace coverage reduces false alarm rates. Software components capture disproportionate margin pools as cloud-based deployment modes shift recurring revenue toward analytics dashboards and remote antenna calibration.
The FCC's Part 15 rules constrain transmit power and spurious emissions for RF-based EAS hardware sold in the United States, while REACH compliance in Europe governs substrate materials in disposable acousto-magnetic tags. Retailers in Germany face additional KBA-equivalent electromagnetic compatibility scrutiny for systems installed near automotive displays. Stakeholders must monitor whether emerging AI-integrated detection algorithms trigger new algorithmic accountability frameworks under the EU AI Act before committing to next-generation platform architectures.
Market Dynamics
Supermarket chains across the United States are tightening shrinkage control protocols, forcing tag deployment rates upward while FCC equipment authorization rules push hardware designs toward certified module architectures.
Growth Catalysts
- Radio frequency module certification:FCC Part 15 compliance mandates are accelerating standardized antenna designs that reduce retailer installation complexity and field calibration costs.
- Apparel sector tag saturation:Soft goods retailers in the United States are expanding disposable tag programs to cover accessory categories previously left unprotected.
- Cloud-based analytics migration:Software dashboards for remote antenna calibration and alarm analytics are pulling recurring revenue streams from hardware-only procurement models.
Market Restraints
- Copper coil input volatility:Resonant circuit substrates in disposable RF tags face raw material price swings that compress tag manufacturing margins.
- Detection hardware supply concentration:Antenna manufacturing clusters in East Asian contract facilities create single-source vulnerability for North American system integrators.
- Electromagnetic interference limits:KBA-equivalent electromagnetic compatibility scrutiny in German automotive retail environments restricts acousto-magnetic system placement near vehicle displays.
Strategic Opportunities
- RFID-electromagnetic hybrid convergence:Warehouse operators in the United States are piloting combination platforms that merge EAS detection with inventory tracking functionality.
- EU AI Act algorithmic accountability:Early compliance positioning for AI-integrated detection systems creates first-mover advantage before mandatory frameworks crystallize.
- Pharmacy chain expansion:Drugstore operators in the United States are adopting source tagging programs for high-shrink over-the-counter categories previously unprotected.
Industry Challenges
- RF engineer talent scarcity:Antenna design and field calibration expertise pools are thinning as legacy technicians retire without sufficient pipeline replacement.
- Legacy system integration friction:Retailers with installed analog detection infrastructure face complex retrofit requirements when upgrading to digital signal processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Article Surveillance Market |
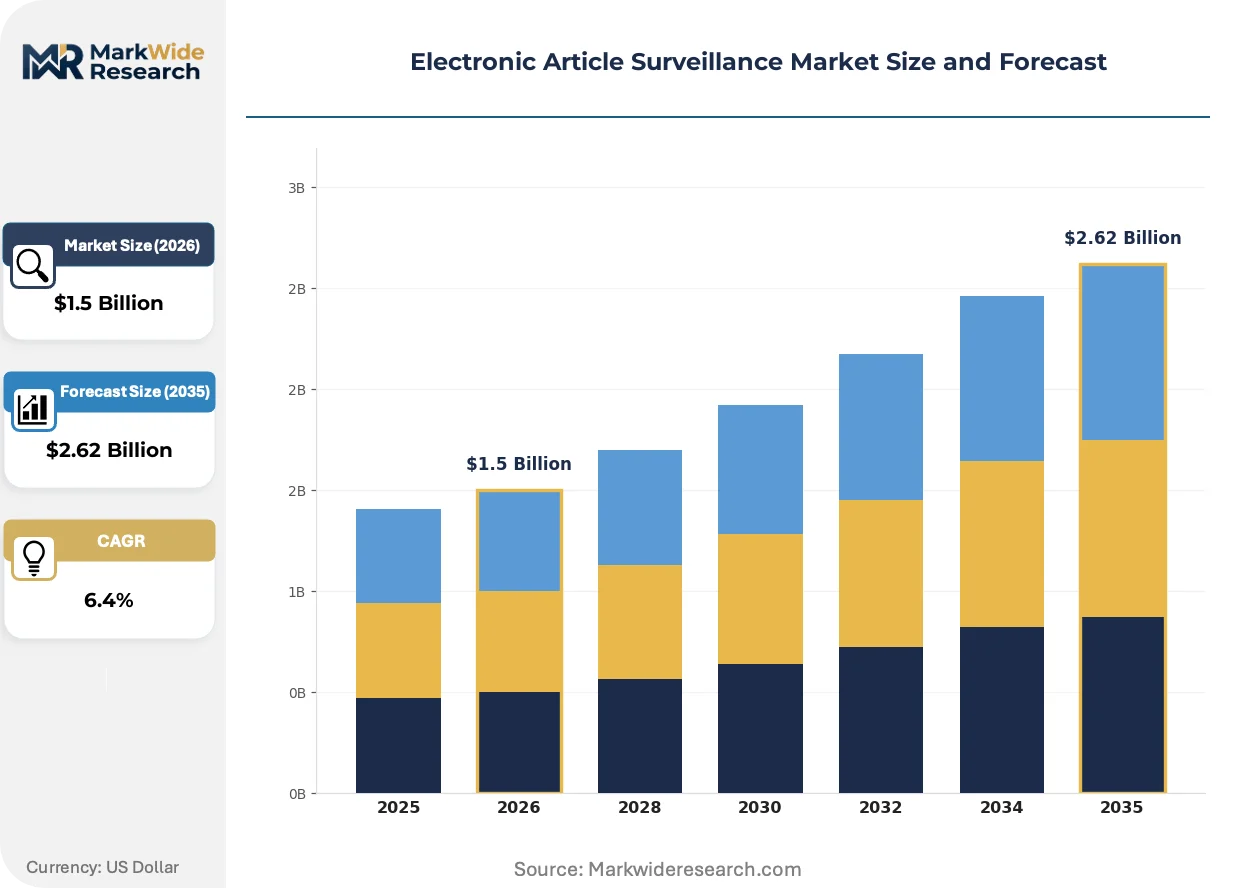
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Acousto-Magnetic, Radio Frequency, Electromagnetic, Combination Systems Component: Tags, Detectors, Antennas, Software End User: Retail Stores, Libraries, Supermarkets, Warehouses Deployment Mode: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Sensormatic Solutions, Checkpoint Systems, Nedap NV, Avery Dennison Corporation, Ketec Inc., ALL-TAG Corporation, Johnson Controls, Agon Systems, Amersec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Article Surveillance Market Strategic Shifts & Innovations
Detection hardware architectures are compressing toward chip-scale implementations while regulatory frameworks on both sides of the Atlantic harden compliance requirements for radio frequency equipment.
Disposable acousto-magnetic tags are miniaturizing through substrate material innovations that maintain resonant frequency stability at reduced coil dimensions. Apparel retailers in the United States are adopting these compact tags for jewelry and eyewear categories where bulkier legacy formats damaged merchandise presentation. This dimensional compression is miniaturizing the visible footprint of anti-theft hardware, enabling tag deployment in premium cosmetic and accessory segments previously resistant to EAS protection.
REACH compliance in Europe is tightening substrate material specifications for disposable tags, forcing reformulation of adhesive compounds and coil encapsulants. Manufacturers serving EU supermarket operators must now document full chemical substance inventories through ECHA registration portals. German retailers face the strictest enforcement timelines, with KBA-equivalent electromagnetic compatibility testing adding secondary certification layers for systems installed near consumer electronics displays.
Buyer concentration among large-format retail consolidators in the United States is compressing procurement cycles toward multi-year framework agreements with embedded technology refresh clauses. Independent regional chains are losing leverage in antenna and tag negotiations as national accounts capture volume-tier pricing. This consolidation pattern is most visible in the grocery sector, where merged entities are standardizing on single-source EAS platforms across combined store footprints.
Electronic Article Surveillance Market Segmentation
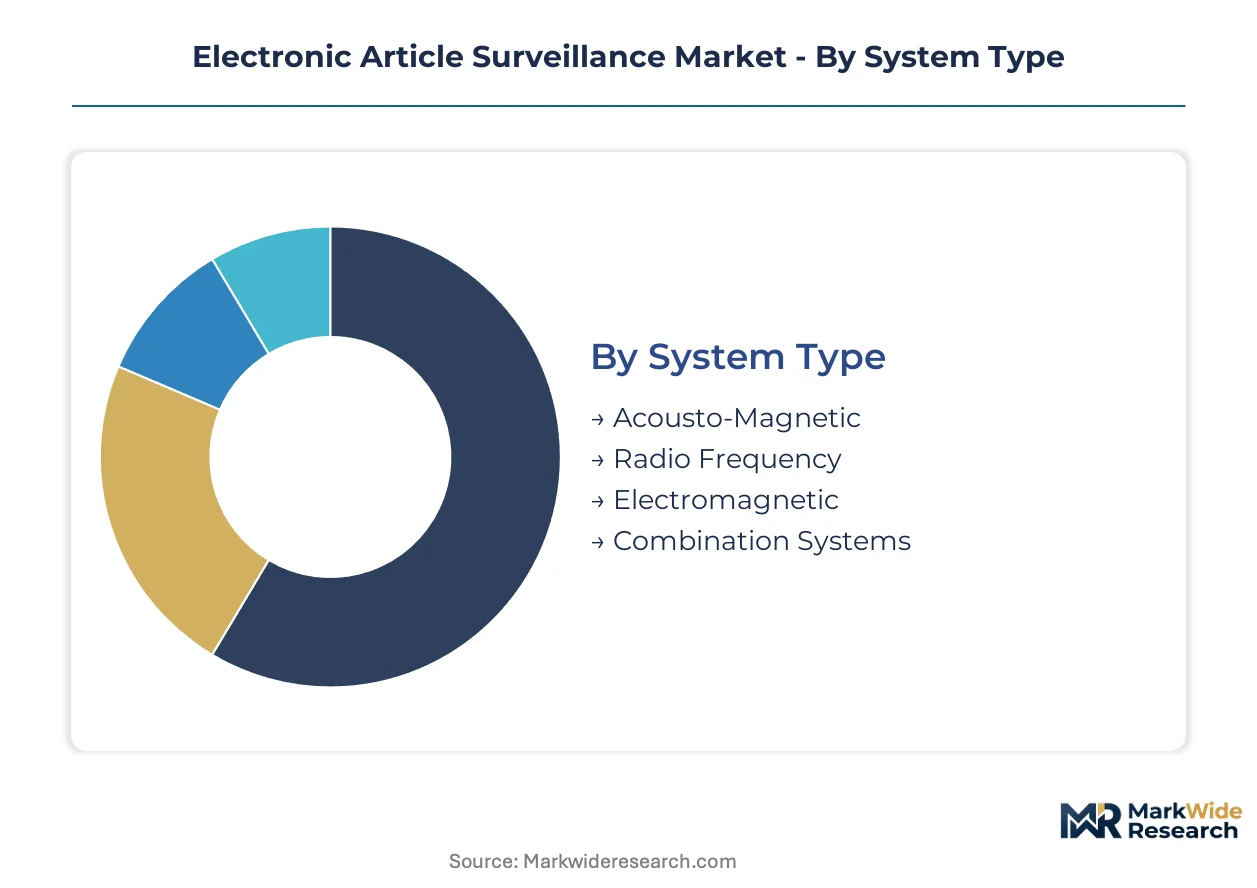
Electronic article surveillance systems fragment across hardware configurations, software architectures, and end-use environments. Each segmentation axis reveals distinct procurement patterns, margin structures, and regulatory exposure profiles that shape vendor positioning strategies.
System Type:
Radio frequency systems dominate domestic United States deployment, while acousto-magnetic platforms concentrate in European supermarket chains seeking REACH-compliant substrate materials.
- Acousto-Magnetic:These systems operate at 58 kHz using amorphous metal strips that saturate under magnetic bias, enabling superior detection through metal shopping carts and foil-lined bags. German supermarket operators favor this technology for high-value liquor and cosmetics aisles where electromagnetic interference from adjacent automotive displays creates false alarm risks under KBA-equivalent scrutiny.
- Radio Frequency:Operating at 8.2 MHz through resonant LC circuits in disposable tags, RF systems achieve the lowest per-unit tag cost in apparel retail. United States soft goods chains are saturating accessory categories—jewelry, eyewear, handbags—with compact tag formats that minimize merchandise presentation disruption.
- Electromagnetic:Reusable tag platforms using ferromagnetic strips suit library and rental environments where circulation volume justifies tag recovery infrastructure.
- Combination Systems:Hybrid architectures merging RF and electromagnetic detection reduce false alarm rates through cross-technology verification at exit gates.
Radio frequency holds the largest share; momentum sits with combination systems as multi-technology floorspace coverage gains retailer preference.
Component:
Margin concentration shifts toward software and away from commodity tag manufacturing as cloud deployment modes expand recurring revenue streams.
- Tags:Disposable RF tags using copper coil substrates face raw material price volatility that compresses manufacturing margins. REACH compliance in Europe is forcing adhesive reformulation and full chemical substance documentation through ECHA portals.
- Detectors:Exit gate electronics integrating analog-to-digital signal processing are climbing the fastest as retailers retrofit legacy analog infrastructure.
- Antennas:Detection pedestals are compressing toward chip-scale implementations with FCC Part 15 certified module designs that reduce field calibration complexity.
- Software:Cloud-based dashboards for remote antenna calibration and alarm analytics are pulling disproportionate margin pools from hardware-only procurement models.
Tags generate the highest unit volume; software commands the steepest margin expansion trajectory.
End User:
Procurement authority concentrates in large-format retail consolidators, squeezing independent regional chains out of volume-tier pricing negotiations.
- Retail Stores:Apparel and department store operators are expanding tag programs into previously unprotected accessory categories. United States big-box chains are standardizing on single-source EAS platforms across merged store footprints.
- Libraries:Public and academic institutions favor reusable electromagnetic tags with integrated circulation management systems.
- Supermarkets:Grocery sector shrinkage control protocols are forcing tag deployment rates upward for high-value categories including premium spirits, infant formula, and over-the-counter pharmaceuticals.
- Warehouses:Logistics operators are piloting RFID-EAS hybrid platforms that merge theft detection with inventory tracking functionality.
Retail stores anchor component demand; warehouses represent the most rapid adoption acceleration.
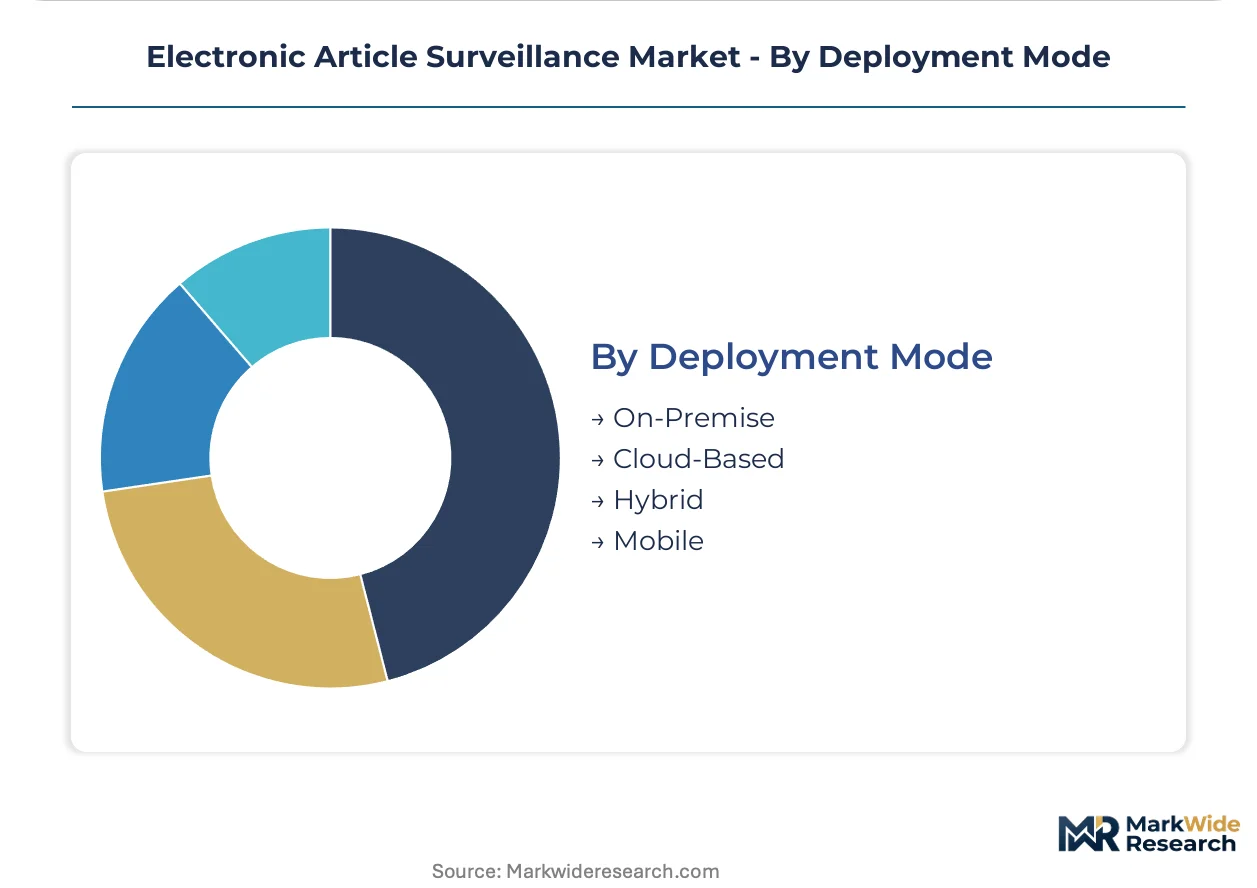
Deployment Mode:
Cloud migration patterns vary by end-use IT maturity, with supermarket chains lagging apparel retailers in SaaS transition timelines.
- On-Premise:Traditional server-based architectures persist in library and warehouse environments with legacy IT infrastructure and stringent data sovereignty requirements.
- Cloud-Based:SaaS delivery of analytics dashboards and remote calibration tools is displacing on-premise installations among United States apparel retailers with centralized IT governance.
- Hybrid:Edge-computing configurations processing detection signals locally while pushing analytics to cloud repositories suit multi-site supermarket operators with uneven connectivity.
- Mobile:Handheld detection units for pop-up retail and temporary event security represent an emerging configuration with limited current penetration.
On-premise retains the installed base; cloud-based deployment is expanding most quickly among fashion retail chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-format retail consolidators in the United States concentrate procurement authority, while European supermarket operators navigate REACH substrate compliance and German automotive retail faces KBA-equivalent electromagnetic scrutiny.
United States
Big-box retail mergers are standardizing EAS platforms across combined store footprints, compressing procurement cycles toward multi-year framework agreements. FCC Part 15 rules constrain transmit power and spurious emissions for RF hardware, pushing designs toward certified module architectures. Antenna manufacturing clusters in East Asian contract facilities create single-source vulnerability for domestic system integrators serving apparel chains in Los Angeles and New York Metro.
Germany
Supermarket operators favor acousto-magnetic systems for high-value liquor and cosmetics aisles where metal shopping carts and foil-lined bags challenge detection. KBA-equivalent electromagnetic compatibility testing adds secondary certification layers for installations near consumer electronics displays. Manufacturing concentration in Baden-Württemberg and Bavaria supports precision coil fabrication for REACH-compliant substrate materials.
United Kingdom
Department store operators are expanding disposable tag programs into jewelry and eyewear categories previously left unprotected. CE marking under the EU Radio Equipment Directive governs RF and acousto-magnetic system deployment, though post-Brexit alignment friction complicates cross-border supply chains. London-based retail headquarters drive centralized IT governance accelerating cloud-based analytics migration.
China
Contract manufacturers cluster in the Yangtze River Delta and Pearl River Delta, producing detection pedestals and resonant circuit substrates for export markets. MIIT radio frequency equipment regulations govern domestic EAS hardware certification, while GB standards apply to electromagnetic compatibility testing. Shenzhen and Shanghai facilities face copper coil input volatility compressing tag manufacturing margins.
Japan
Library and rental environments favor reusable electromagnetic tag platforms with integrated circulation management systems. METI industrial standards influence procurement specifications for public institution deployments. Tokyo and Osaka metropolitan areas concentrate demand for compact tag formats minimizing merchandise presentation disruption in premium cosmetic retail.
Electronic Article Surveillance Market Key Industry Players
Player mix skews toward vertically integrated hardware manufacturers and specialized RFID-electromagnetic hybrid developers. The vendor base splits between consolidated multi-technology platforms and focused single-technology specialists. Three archetypes dominate: full-stack integrators controlling tag-to-detector supply chains, software-centric analytics providers, and component-focused substrate manufacturers. Competitive moves center on backward integration into coil fabrication and strategic partnerships with cloud infrastructure providers.
Within the full-stack integrator tier, Sensormatic Solutions and Checkpoint Systems exemplify archetypes of captive supply chain control and deep channel partnership models respectively. Nedap NV occupies a position representing the hybrid-platform specialist archetype. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning: the Illinois-based corporation, the European limited company, and the Dutch public limited company each sit within distinct competitive vectors shaped by regulatory exposure and end-use concentration.
| Leading Market Players |
|---|
| Sensormatic Solutions |
| Checkpoint Systems |
| Nedap NV |
| Avery Dennison Corporation |
| Ketec Inc. |
| ALL-TAG Corporation |
| Johnson Controls |
| Agon Systems |
| Amersec |
| Others |
Cost & Logistics Intelligence
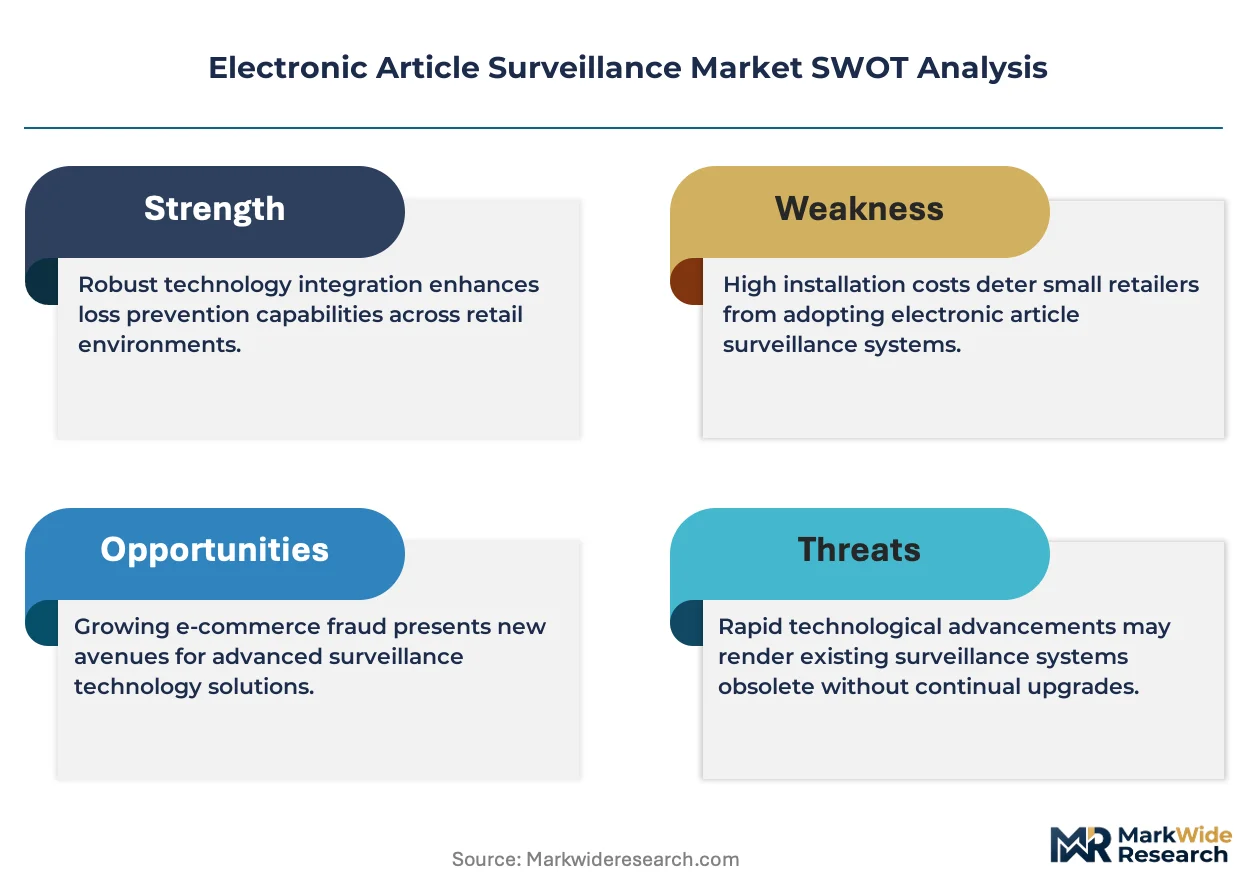
Sixty-to-ninety-day antenna lead times from Yangtze River Delta contract facilities concentrate procurement leverage with United States big-box consolidators, compressing tag pricing through volume-tier framework agreements while copper coil volatility squeezes manufacturing margins.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate disposable RF tag procurement, with pricing stratifying across FCC-certified premium modules, standard CE-marked configurations, and economy-tier uncertified alternatives. Price differentiation hinges on electromagnetic compliance tier and volume scale, with supermarket chains capturing steepest discounts through multi-year commitments. Cost compression in economy tags is intensifying because adhesive reformulation for REACH compliance adds substrate expense. Independent regional retailers exhibit highest price sensitivity; national accounts with captive IT governance show lowest.
Supply Chain Analysis
China and South Korea anchor resonant circuit substrate fabrication and detection pedestal assembly, with Baden-Württemberg precision coil facilities serving REACH-compliant European demand. Raw material draws from Chilean copper concentrate, Malaysian epoxy resin, and German amorphous metal strip feedstock. Single-source vulnerability concentrates in Yangtze River Delta antenna manufacturing clusters. Distribution runs through system integrators holding FCC equipment authorization for North American retail deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large-format retail consolidators in the United States, where merged grocery entities standardize procurement across combined footprints and squeeze independent chains from volume-tier negotiations.
For Market Incumbents: Fortify backward integration into copper coil fabrication to offset raw material volatility, while deepening cloud analytics capabilities to capture recurring revenue streams. Radio frequency engineer talent scarcity threatens antenna design capacity; prioritize certification investment in FCC Part 15 module architectures to lock in retailer switching costs. For New Entrants and Emerging Players: Anchor in pharmacy chain source tagging programs for high-shrink over-the-counter categories, where incumbent penetration remains shallow. Warehouse RFID-EAS hybrid platforms offer the most penetrable white space. Pursue pilot-to-production partnerships with logistics operators seeking inventory-theft convergence. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because software-centric analytics providers command expanding margin pools as hardware commoditizes. Target acquisition archetypes: hybrid-platform specialists with warehouse pilot traction. Monitor FCC algorithmic accountability rulemaking as inflection signal for AI-integrated detection system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Fabrication | Mitigates copper price volatility exposure for disposable tag manufacturers serving REACH-compliant European markets. |
| Cloud Analytics Platform Launch | Captures recurring revenue from apparel retailers migrating from hardware-only procurement to SaaS calibration dashboards. |
| FCC Part 15 Module Certification | Reduces field installation complexity for system integrators deploying across merged United States big-box footprints. |
| RFID-Electromagnetic Hybrid Development | Addresses warehouse operator demand for unified theft detection and inventory tracking functionality. |
| EU AI Act Compliance Positioning | Creates first-mover advantage for algorithmic accountability frameworks governing next-generation detection architectures. |
Research Approach
Initial hypotheses were tested against primary input from retail loss prevention directors, antenna design engineers, FCC equipment authorization consultants, and supermarket procurement managers and refined through secondary validation against customs trade records, SEC 10-K filings of listed component suppliers, FCC equipment authorization databases, and ECHA REACH registration portals. Bottom-up tag volume estimates and top-down system revenue aggregates were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates contribution from system type segmentation, deployment mode migration patterns, and end-use concentration shifts. CAGRs were derived through logarithmic trend fitting across modeled annual intervals. Industry-specific forecast inputs include copper coil price trajectory assumptions and retailer consolidation event schedules.
Decision-makers should treat outputs as directional under base assumptions of continued large-format retail merger activity and stable FCC Part 15 enforcement intensity; material deviation in electromagnetic interference regulatory stringency would warrant model refresh. Recalibration cycles align with material shifts in copper commodity pricing and supermarket chain consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Infrared Detector Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Flooded Member Detection Equipment Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Global Wireless Gas Detection Market