
 Safety Laser Scanner Market | 2026-2036
Safety Laser Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Laser Scanner Market Analysis
A widening capability gap between photonics-foundry owners and fabless assembler brands is reorganizing competitive tiers in the safety laser scanner industry. SICK AG leverages captive optical component fabrication to sustain margin structures that pure-play competitors cannot replicate. OMRON Corporation anchors its position through dense channel control across Japanese automotive OEM supply chains, while Keyence Corporation differentiates via direct salesforce density that bypasses distributor markup layers.
Safety laser scanners emit pulsed or continuous-wave laser beams across defined angular fields, measuring time-of-flight or phase-shift returns to construct real-time point clouds for intrusion detection within configurable safety zones. These devices serve primarily to eliminate mechanical guarding in automated production environments, enabling human-robot collaboration without physical barriers. Fixed scanner deployments occupy the dominant share of installed base across automotive welding lines, though portable scanner configurations represent the fastest-expanding segment as construction and event-logistics operators adopt temporary hazard-perimeter systems. Area protection applications command the deepest margin pools due to certification complexity and integration engineering requirements, while obstacle detection competes primarily on unit cost.
The EU Machinery Directive and CE marking requirements administered by national market surveillance authorities in Germany, France, and Italy mandate performance-level verification for safety-related laser systems, creating structural demand for certified product architectures. In the United States, OSHA general duty clause enforcement and ANSI/RIA robot safety standards shape buyer procurement specifications, particularly in automotive and warehousing end uses. Stakeholders must monitor divergence between regional certification reciprocity agreements and emerging Chinese GB standard harmonization efforts as procurement decisions increasingly factor in multi-jurisdictional compliance costs.
Market Dynamics
Photonics foundry consolidation is compressing supply availability for safety laser scanner producers, forcing fabless assemblers into longer qualification cycles while integrated manufacturers exploit captive optical component fabrication to defend margin structures.
Growth Catalysts
- EU Machinery Directive compliance deadlines:German, French, and Italian market surveillance authorities are enforcing performance-level verification mandates for collaborative robot workspaces, structurally pulling certified area protection systems into manufacturing facilities.
- Automotive OEM retrofit cycles:East Asian production clusters are rebuilding welding and assembly lines with 3D scanning architectures to enable human-robot collaboration without physical guarding.
- Construction logistics adoption:Temporary hazard-perimeter deployments at event venues and infrastructure sites are converting portable scanner configurations from niche to mainstream equipment categories.
Market Restraints
- Optical component supply concentration:Foundry capacity for pulsed laser diodes and precision optics concentrates among a limited set of East Asian contract manufacturers, exposing fabless scanner brands to allocation risk.
- Certification cost structures:Third-party notified body testing for CE marking under the EU Machinery Directive adds fixed engineering overhead that disadvantages smaller product portfolios.
- Mechanical guarding substitution:Low-complexity applications in cost-sensitive warehousing segments continue deploying physical barriers rather than laser-based area protection.
Strategic Opportunities
- GB standard harmonization in China:Emerging alignment between Chinese national standards and IEC 61496 family specifications creates pathways for certified products to access industrial automation procurement.
- Mobile robotics integration:Autonomous mobile robot platforms for warehouse fulfillment require onboard obstacle detection, opening scanner demand outside fixed-installation automotive paradigms.
- Aftermarket service unbundling:Direct salesforce density in Japanese automotive supply chains demonstrates channel models that capture recurring calibration and recertification revenue streams.
Industry Challenges
- Multi-jurisdictional compliance engineering:Product development teams must simultaneously satisfy OSHA general duty clause interpretations, ANSI/RIA robot safety standards, and diverging EU national implementation guidelines.
- Legacy system integration:Brownfield manufacturing facilities require scanner architectures compatible with existing safety PLC networks and fieldbus protocols, extending deployment timelines.
- Photonics engineering talent scarcity:Time-of-flight signal processing and optical system design expertise concentrates among semiconductor industry employers, constraining scanner manufacturer hiring pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Laser Scanner Market |
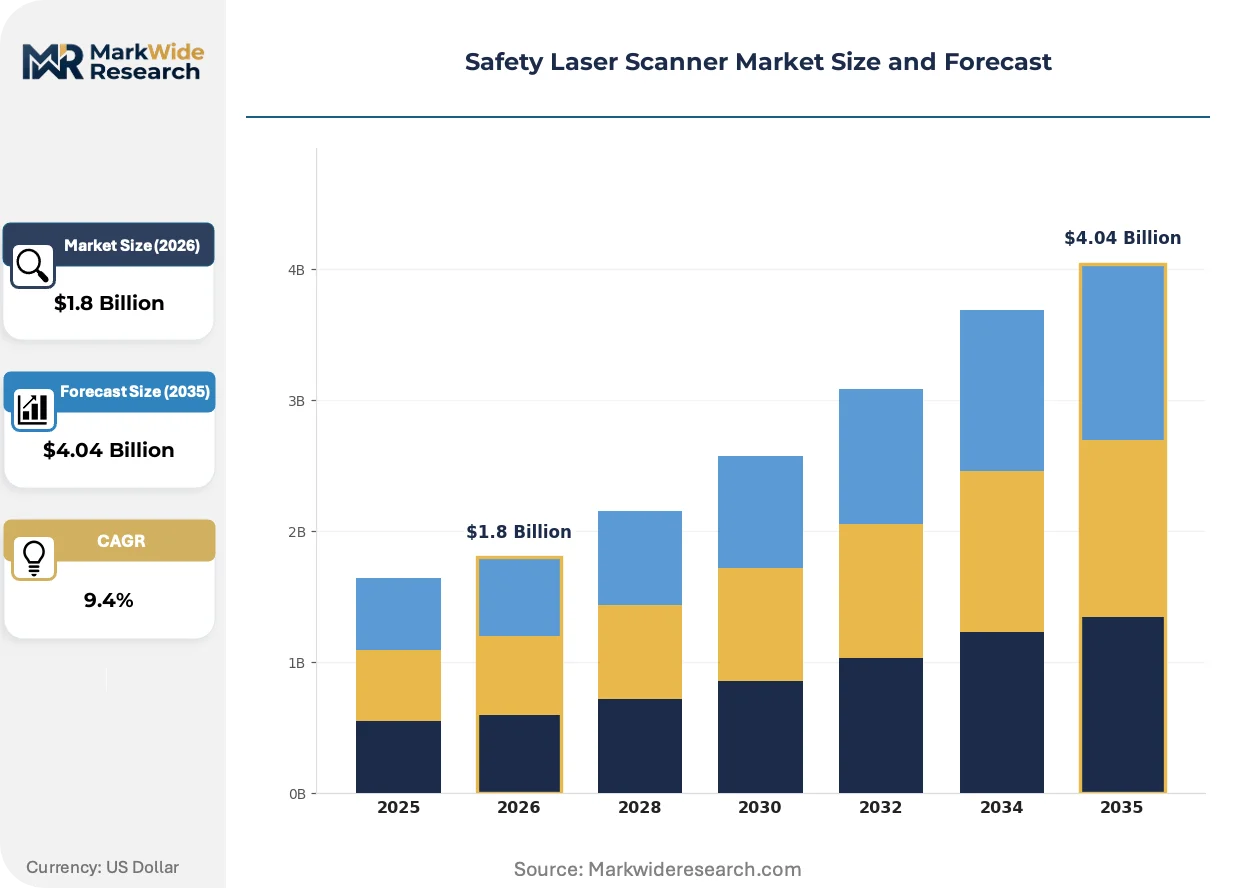
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Scanner, Portable Scanner, 2D Scanner, 3D Scanner End User: Manufacturing, Logistics, Construction, Robotics Technology: Time-of-Flight, Phase Shift, Fuzzy Logic, Lidar Application: Obstacle Detection, Hazard Prevention, Area Protection, Safety Monitoring |
| Companies Covered | SICK AG, OMRON Corporation, Keyence Corporation, Leuze electronic GmbH + Co. KG, IDEC Corporation, Panasonic Corporation, Hans Turck GmbH & Co. KG, Hokuyo Automatic Co. Ltd., Banner Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Laser Scanner Market Emerging Trajectories
Scanner architecture is separating into distinct performance tiers as end-use requirements diverge, with regulatory complexity and application physics driving specialization rather than convergence.
Time-of-flight measurement is bifurcating from phase-shift detection as the dominant range-sensing methodology. Automotive welding lines with long-range area protection requirements are standardizing on time-of-flight architectures for their immunity to ambient light interference, while phase-shift systems compress cost structures for short-range collaborative robot applications. This technical divergence is bifurcating supplier R&D investment and fragmenting component supply chains.
CE marking enforcement under the EU Machinery Directive is tightening performance-level verification documentation requirements. German market surveillance authorities are conducting unannounced factory inspections of safety laser scanner installations, elevating compliance engineering from checkbox exercise to core product architecture consideration. Automotive OEM procurement specifications now mandate third-party test reports prior to supplier qualification.
Buyer preference is rotating toward bundled safety system integration rather than standalone scanner procurement. Japanese automotive OEMs are specifying complete hazard-zone solutions encompassing scanners, safety PLCs, and light curtain backups from single-source suppliers. This specification behavior compresses pure-play scanner margins while rewarding channel control density and system integration capabilities.
Safety Laser Scanner Market Segmentation
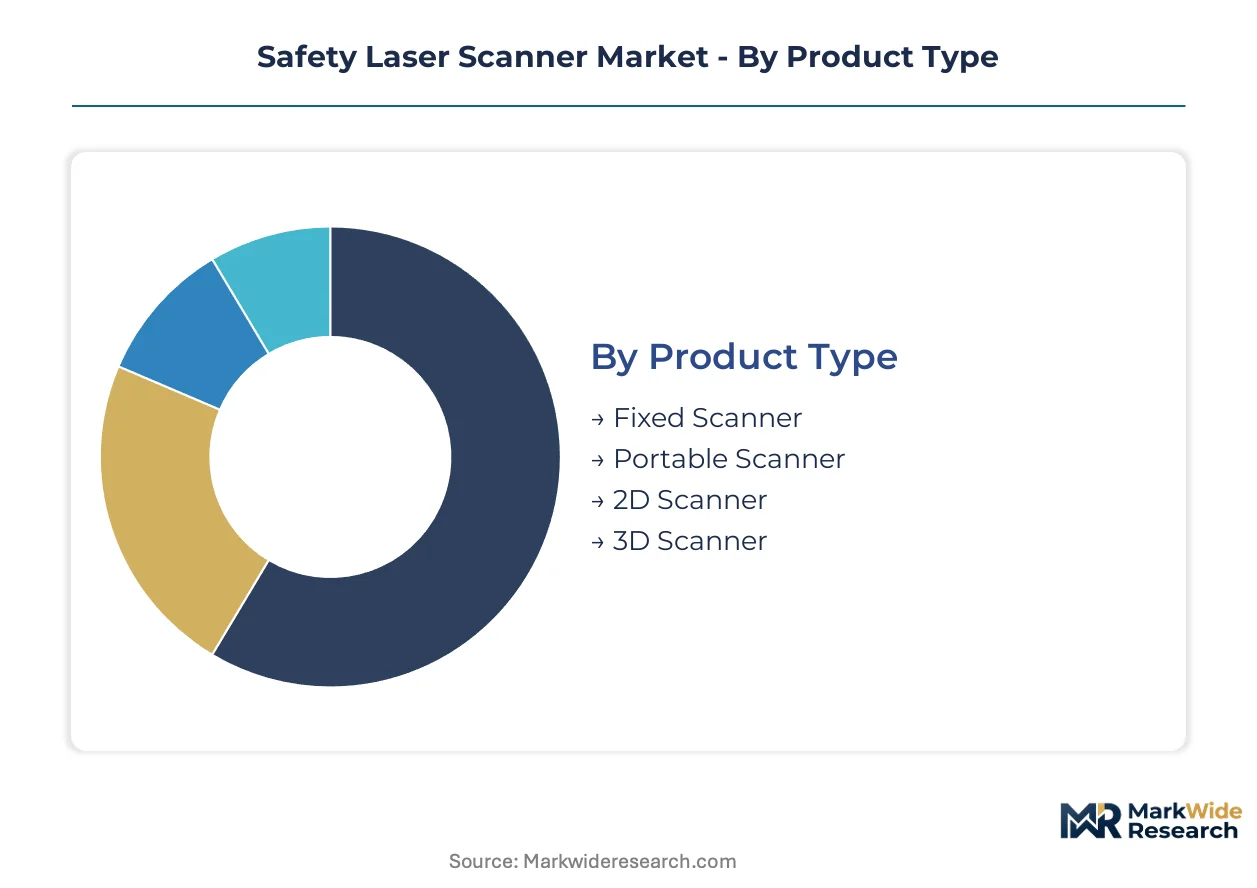
Scanner architecture specialization reflects divergent compliance burdens across application environments. Product configurations now align with specific certification pathways rather than converging toward universal platforms.
Product Type:
CE marking requirements under the EU Machinery Directive impose distinct performance-level verification obligations on each scanner configuration, fragmenting supplier development priorities.
- Fixed Scanner:Stationary installations with permanent mounting infrastructure dominate automotive welding lines and high-volume manufacturing cells. German OEMs specify these for long-range area protection where immunity to ambient light interference is mandatory.
- Portable Scanner:Battery-powered mobile units with rapid deployment capability serve temporary hazard perimeters at event venues and infrastructure construction sites. East Asian logistics operators are converting this configuration from niche equipment to mainstream procurement category.
- 2D Scanner:Single-plane detection systems offer cost-optimized entry points for linear conveyor guarding and simple access control.
- 3D Scanner:Multi-layer point cloud generation enables volumetric zone monitoring for collaborative robot workspaces requiring complex geometry mapping.
Fixed scanner configurations handle the majority of throughput; portable scanner demand is expanding most quickly on share.
End User:
Cost tier differentiation separates capital-intensive automotive deployments from price-sensitive logistics implementations.
- Manufacturing:Automotive production clusters in Germany and Japan drive specification intensity for certified area protection systems with third-party test documentation.
- Logistics:Warehouse fulfillment and distribution centers prioritize obstacle detection for autonomous mobile robot integration, with procurement competing primarily on unit economics.
- Construction:Temporary perimeter applications favor rental and lease models over capital purchase, compressing margin structures for equipment suppliers.
- Robotics:Collaborative robot OEMs require embedded scanner modules with compact form factors and deterministic response times for human-robot interaction safety.
Manufacturing absorbs the deepest engineering investment per installation; logistics represents the steepest expansion trajectory on volume.
Technology:
Measurement methodology selection directly determines range performance and ambient light immunity in target operating environments.
- Time-of-Flight:Pulsed laser emission with nanosecond-scale return timing measurement delivers long-range detection to 65 meters. Automotive welding lines standardize on this architecture for its reliability in high-interference environments.
- Phase Shift:Continuous-wave interferometry achieves sub-millimeter precision at shorter ranges with reduced component cost. Collaborative robot applications in Japanese electronics assembly favor this approach for compact workspace monitoring.
- Fuzzy Logic:Rule-based signal processing algorithms filter environmental noise without deterministic safety certification pathways.
- Lidar:Scanning laser rangefinder arrays generate dense point clouds for mobile robotics navigation and mapping applications.
Time-of-Flight dominates certified safety applications; phase shift systems are climbing the fastest in unit shipments.
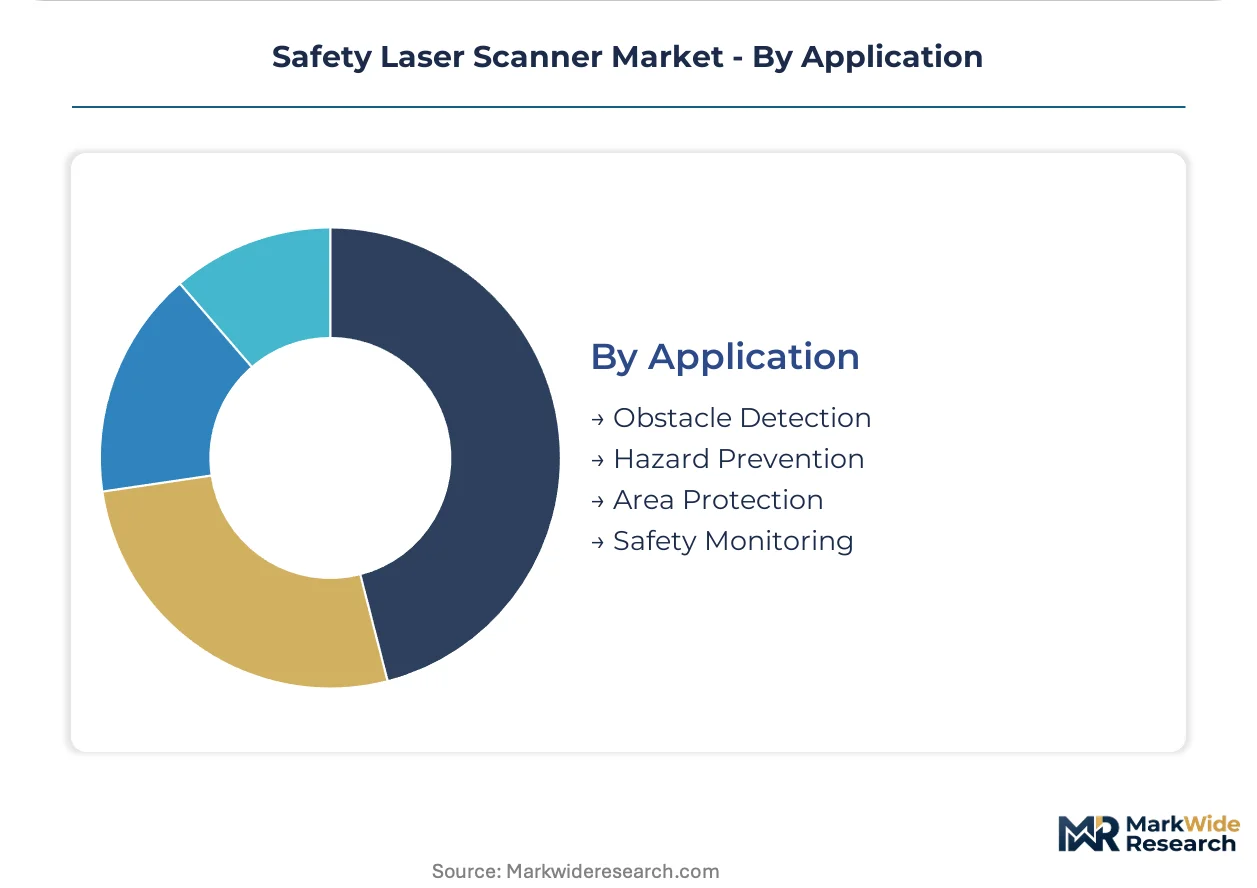
Application:
Margin structure varies with certification complexity and integration engineering intensity.
- Obstacle Detection:Basic intrusion sensing for mobile platforms and automated guided vehicles competes on sensor cost and power consumption metrics.
- Hazard Prevention:Pre-contact warning systems for machinery access points require configurable warning and safety zone layering.
- Area Protection:Certified safety zones with defined performance levels command premium positioning due to third-party testing overhead and liability documentation requirements. German market surveillance authorities mandate this category for collaborative robot workspaces.
- Safety Monitoring:Continuous surveillance applications in process industries integrate scanner outputs with distributed safety PLC networks.
Area protection captures the highest margin pool; obstacle detection is gaining share fastest on mobile robotics adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German manufacturing procurement while East Asian automotive clusters compete on deployment velocity and retrofit cycle speed. Regulatory enforcement intensity varies sharply across jurisdictions, fragmenting certification reciprocity and creating arbitrage opportunities for multi-standard product architectures.
Germany
Automotive OEMs in Stuttgart and Munich drive specification intensity for certified area protection systems with third-party test documentation. KBA market surveillance authorities conduct unannounced factory inspections of collaborative robot workspaces under EU Machinery Directive mandates. The Baden-Württemberg industrial corridor hosts dense concentrations of system integrators specializing in safety PLC network integration.
Japan
Electronics assembly clusters in Aichi Prefecture and Kansai region favor phase-shift detection systems for compact collaborative robot applications. METI industrial safety guidelines shape procurement specifications for human-robot interaction equipment. Nagoya-based automotive suppliers specify complete hazard-zone solutions encompassing scanners, safety PLCs, and light curtain backups from single-source suppliers.
United States
Warehouse fulfillment operators in Michigan and Ohio prioritize obstacle detection for autonomous mobile robot integration with procurement competing on unit economics. OSHA general duty clause enforcement shapes buyer specifications particularly in automotive and warehousing end uses. The Southeast manufacturing belt exhibits fastest retrofit adoption as brownfield facilities upgrade welding lines.
China
Yangtze River Delta automotive production clusters rebuild assembly lines with 3D scanning architectures to enable human-robot collaboration. MIIT and SAMR administer emerging GB standard harmonization efforts with IEC 61496 family specifications. Shanghai and Suzhou industrial zones demonstrate steepest volume expansion for portable scanner configurations in logistics applications.
South Korea
Hyundai and Kia supplier networks in Ulsan and Gwangju drive demand for embedded scanner modules with deterministic response times. MFDS and KOSHA safety regulations govern collaborative workspace certification requirements. The Seoul Capital Area concentrates R&D investment in time-of-flight signal processing for high-interference manufacturing environments.
Safety Laser Scanner Market Vendor Landscape
Concentration sits with integrated photonics manufacturers possessing captive optical component fabrication. The vendor base separates into three tiers: foundry-owning system houses defending margin structures through backward integration, fabless assemblers exposed to allocation risk from East Asian contract manufacturers, and direct-sales specialists capturing recurring service revenue. Dominant competitive moves include M&A activity targeting photonics engineering talent and strategic partnerships bundling scanners with safety PLC networks.
Among German integrated manufacturers, SICK AG and Leuze electronic GmbH + Co. KG exemplify the foundry-owning archetype with positions in captive optical component supply. Japanese direct-sales specialists OMRON Corporation and Keyence Corporation occupy positions emphasizing channel control density over distributor markups. Hans Turck GmbH & Co. KG represents the mid-tier fabless assembler archetype navigating longer qualification cycles amid photonics foundry consolidation.
| Leading Market Players |
|---|
| SICK AG |
| OMRON Corporation |
| Keyence Corporation |
| Leuze electronic GmbH + Co. KG |
| IDEC Corporation |
| Panasonic Corporation |
| Hans Turck GmbH & Co. KG |
| Hokuyo Automatic Co. Ltd. |
| Banner Engineering |
| Others |
Supply Flow & Price Mechanics
CE marking enforcement under the EU Machinery Directive gates both supplier qualification timelines and price differentiation across certified and uncertified product tiers. German market surveillance authorities mandate third-party notified body testing that adds fixed engineering overhead, compressing margins for smaller portfolios while enabling integrated manufacturers to capture premium positioning through captive optical fabrication.
Pricing Analysis
Configured-to-order pricing for area protection systems commands spreads of 40-60 percent above standard catalog configurations due to integration engineering and site-specific safety zone programming. Three-tier pricing structure across premium certified systems, standard industrial scanners, and economy obstacle detection modules reflects certification grade and after-sales service bundling. Pricing pressure stems from fabless assemblers competing on unit cost in logistics obstacle detection where certification requirements are minimal. Warehouse fulfillment operators exhibit highest price sensitivity, while German automotive OEMs prioritize third-party test documentation over procurement cost.
Supply Chain Analysis
Japan and Germany anchor precision optics and photonics component fabrication, while Taiwan and South Korea concentrate pulsed laser diode foundry capacity. Safety laser scanner production draws from precision-machined housings, specialized optical coatings, and time-of-flight signal processing chipsets. Single-source vulnerability concentrates in East Asian contract manufacturers supplying pulsed laser diodes to fabless scanner brands. Distribution runs through system integrators in automotive supply chains and direct salesforces in Japanese electronics assembly markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The safety laser scanner market is recovering from photonics foundry consolidation pressures, with automotive OEM retrofit cycles in East Asia providing cyclical uplift through assembly line rebuilding programs.
For Market Incumbents: Fortify margin structures by deepening backward integration into optical component fabrication before foundry capacity tightens further. SICK AG and Leuze electronic demonstrate how captive laser diode production insulates against allocation risk from East Asian contract manufacturers. Invest in certification engineering capabilities to capture recurring calibration and recertification revenue streams as German market surveillance authorities intensify unannounced factory inspections. For New Entrants and Emerging Players: Anchor in portable scanner configurations for construction logistics and event venue applications where temporary hazard-perimeter demand is converting from niche to mainstream procurement category. Target aftermarket service unbundling in Japanese automotive supply chains where direct salesforce density demonstrates channel models that bypass distributor markups. Pursue mobile robotics integration partnerships for autonomous warehouse fulfillment platforms requiring onboard obstacle detection outside fixed-installation paradigms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 3D scanning architectures as multi-layer point cloud generation requires denser photonics engineering investment than legacy 2D systems. Long-term viability favors integrated manufacturers possessing captive optical fabrication over fabless assemblers exposed to component allocation risk. Monitor GB standard harmonization progress between Chinese national standards and IEC 61496 specifications as inflection indicator for industrial automation procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Foundry Acquisition | Captive laser diode fabrication eliminates allocation risk from East Asian contract manufacturers. |
| Safety PLC Integration Partnership | Bundled hazard-zone solutions capture procurement specifications from Nagoya-based automotive suppliers. |
| GB Standard Certification Investment | Chinese MIIT harmonization creates pathway into Yangtze River Delta industrial automation procurement. |
| Direct Salesforce Expansion | Channel density in Japanese automotive supply chains captures recurring calibration revenue streams. |
| Mobile Robotics Module Development | Compact embedded scanners address autonomous warehouse fulfillment platform requirements. |
Methodological Framework
The analysis maps fixed scanner deployments, portable configurations, 2D and 3D architectures, and time-of-flight versus phase-shift technologies, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and safety system integrators. Primary interviews combined with secondary validation from SEC filings, customs and trade data, automotive production databases, and notified body certification records. Bottom-up installation base modeling triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including industrial automation capex disclosures and automotive OEM supplier qualification databases. Segmentation dimensions modeled encompass product configuration, measurement methodology, end-use industry, application type, and regional regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle analysis, with specific inputs including collaborative robot deployment rates and EU Machinery Directive compliance deadline schedules.
Decision-makers should treat outputs as directional under assumptions of sustained automotive OEM retrofit investment and stable photonics foundry capacity; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding certification reciprocity agreements and Chinese GB standard harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Asia-Pacific Industrial Control System Market