
 Duct Smoke Detectors Market | 2026-2036
Duct Smoke Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Duct Smoke Detectors Market Insights
Modular detector configurations bundled with building management systems is expanding buyer choice across commercial and institutional projects. Honeywell International Inc. leverages its integrated fire and HVAC platform to anchor large-scale infrastructure contracts. GENTEX CORPORATION sustains technology leadership through specialized photoelectric sensing architectures. Kidde competes aggressively on channel density and distributor relationships across North American retrofit markets.
A duct smoke detector is a specialized fire detection device installed within heating, ventilation, and air conditioning ductwork to sample air for combustion products, typically employing photoelectric light-scattering chambers with sensitivity ranges of 0.5% to 4.0% obscuration per foot to trigger alarms before smoke circulates through occupied spaces. Addressable detectors are capturing disproportionate investment as facilities managers prioritize pinpoint location data and reduced wiring complexity in multi-zone buildings. Photoelectric technology dominates new specifications due to superior performance detecting smoldering fires common in commercial duct environments, while ionic technology occupies legacy maintenance replacement cycles where code grandfathering persists.
NFPA 90A mandates duct smoke detector placement in air handling systems exceeding specific capacity thresholds across United States jurisdictions, while the International Mechanical Code shapes product certification requirements adopted by state and municipal building departments. China's GB standards and fire safety regulations enforced by the Ministry of Emergency Management are elevating detector performance benchmarks in high-rise construction. Stakeholders must monitor evolving code harmonization between ASHRAE ventilation guidelines and fire alarm integration standards as smart building architectures blur traditional system boundaries.
Market Dynamics
The duct smoke detectors market is experiencing structural pressure from HVAC digitization mandates, as building automation protocols force integration between fire safety and climate control systems.
Growth Catalysts
- NFPA 90A placement mandates:United States jurisdictions now require detectors in air handling systems above 2,000 cfm, expanding retrofit obligations across commercial portfolios.
- Photoelectric sensing architectures:Facilities managers specify light-scattering chambers for smoldering fire detection, displacing legacy ionic units in specification documents.
- China's high-rise construction wave:GB standards enforcement by the Ministry of Emergency Management is elevating performance benchmarks in mixed-use towers.
Market Restraints
- Semiconductor input volatility:Addressable detector ASICs face allocation constraints from foundry concentration in Taiwan.
- Legacy ionic technology grandfathering:Code exemptions in older United States commercial buildings delay full technology transitions.
- Certification timeline friction:UL 268A testing protocols extend product launch cycles by eight to fourteen months.
Strategic Opportunities
- India's smart city infrastructure:Municipal fire safety tenders in Bengaluru and Mumbai are specifying addressable duct detection for metro rail ventilation.
- BAS convergence:BACnet and Modbus integration is opening specification pathways with building automation vendors.
- Germany's green building certification:DGNB criteria now credit integrated fire-HVAC monitoring, creating procurement preference.
Industry Challenges
- Fire-alarm technician shortage:NICET certification requirements outpace vocational program output in North American metropolitan markets.
- Legacy system integration complexity:Conventional 24VDC wiring architectures resist addressable retrofit without full panel replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duct Smoke Detectors Market |
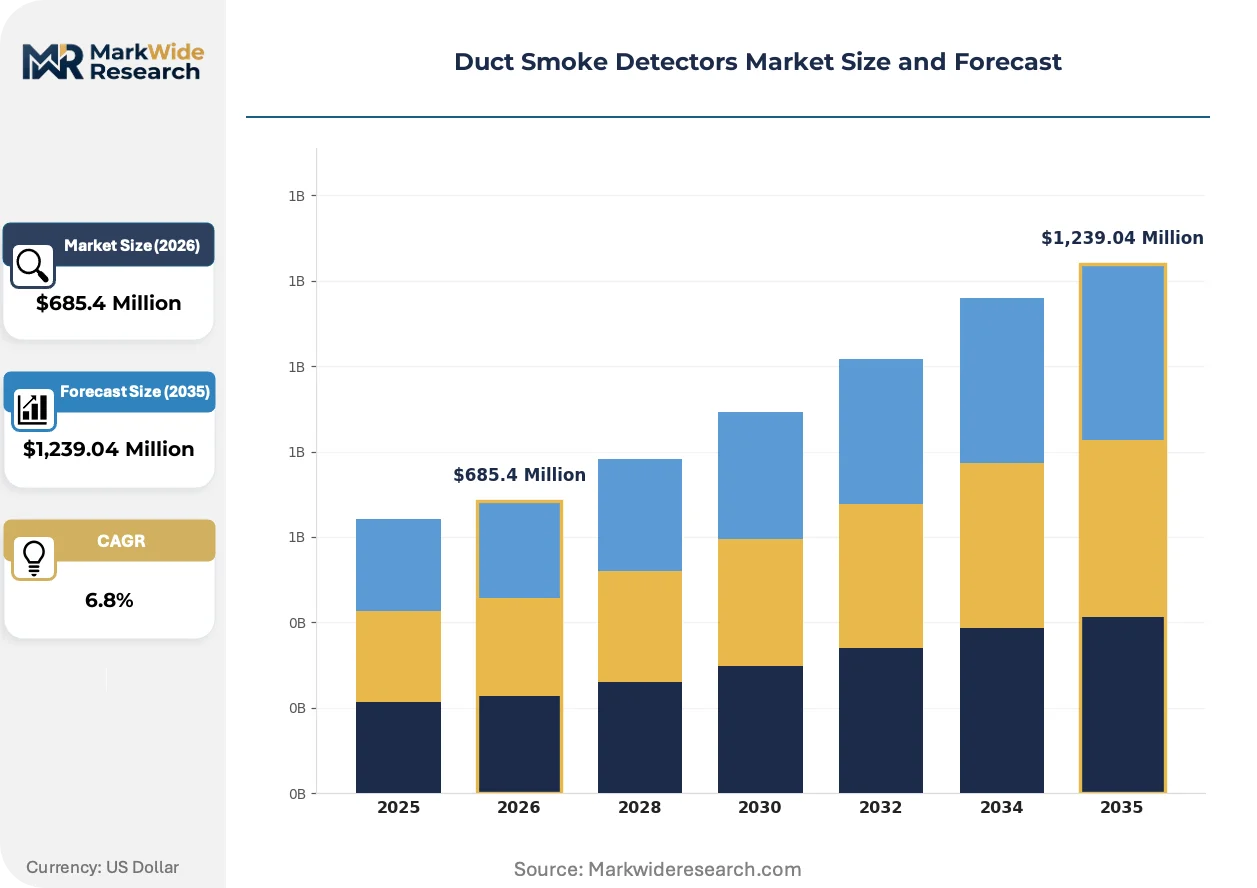
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Detectors, Addressable Detectors, Multi-Criteria Detectors, Dual-Sensor Detectors Technology: Ionic Technology, Photoelectric Technology, Heat Sensors, Hybrid Technology End User: Commercial Buildings, Industrial Facilities, Residential Units, Educational Institutions Installation Type: Ceiling Mount, Wall Mount, Duct Mount, Integrated Systems |
| Companies Covered | Kidde, National Time & Signal, Potter Electric Signal Company, LLC, Greystone Energy Systems Inc., Space Age Electronics, Inc., Honeywell International Inc., Apollo America Inc., GENTEX CORPORATION, Hochiki America Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duct Smoke Detectors Market Trends and Innovations
Intelligent sensing architectures are compressing detection latency while forcing interoperability standards across historically siloed building systems.
Multi-criteria detection is electrifying specification preferences in healthcare and data center verticals. These sensors combine photoelectric light-scattering with carbon monoxide sensing to reduce nuisance alarms from dust accumulation. Hospital facilities managers in the United States are specifying these units for operating suite HVAC returns. The technology is electrifying competitive positioning as pure photoelectric suppliers face specification erosion.
ASHRAE Guideline 36 integration requirements are reshaping procurement documentation for United States commercial projects. The standard mandates coordinated smoke control sequences between detectors and variable air volume terminals. Engineering firms in Texas and California are embedding these specifications in design-build contracts. Fire alarm contractors now submit integrated submittals rather than standalone detector schedules.
Service contract unbundling is fragmenting buyer-supplier relationships in European commercial real estate. Property management platforms in Germany and the Netherlands are separating detector maintenance from panel monitoring agreements. Specialist duct cleaning vendors now carry detector calibration certifications. This restructuring is most visible in Frankfurt and Rotterdam office markets where facility outsourcing has compressed supplier margins.
Duct Smoke Detectors Market Segmentation
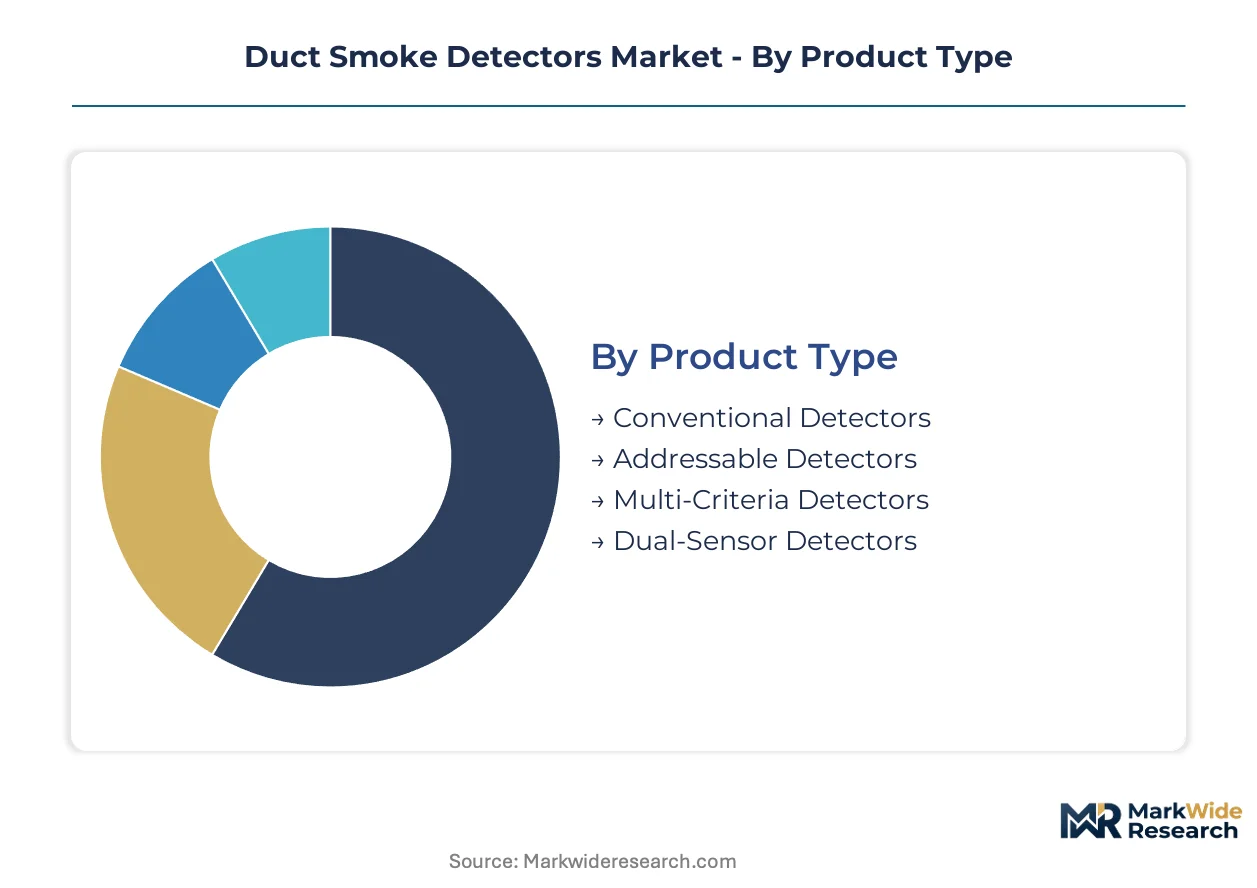
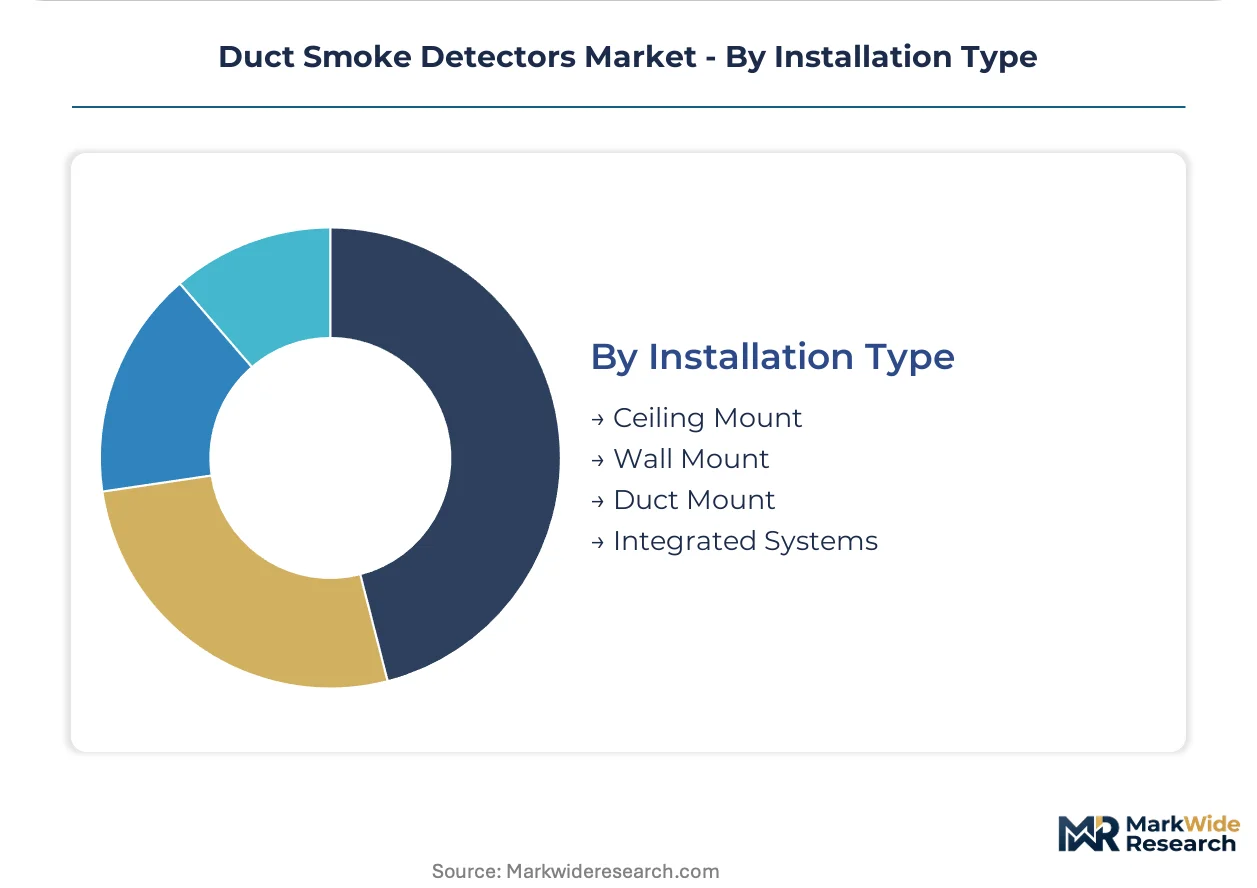
Duct smoke detector procurement splits sharply between legacy replacement cycles and new construction specifications. Facilities managers weigh integration complexity against detection sensitivity when selecting across product architectures, sensing technologies, and mounting configurations.
Product Type:
Standardization dominates conventional offerings while addressable and multi-criteria units demand customized programming for building-specific fire sequences.
- Conventional Detectors:Hardwired 24VDC units with zone-based alarm grouping serve cost-sensitive retrofit projects in older commercial buildings. Demand concentrates in United States secondary markets where NFPA 90A grandfathering delays full addressable upgrades.
- Addressable Detectors:Microprocessor-based devices transmit individual device status over digital communication loops, enabling pinpoint location identification. United States healthcare and education verticals specify these for multi-zone campuses requiring reduced wiring infrastructure.
- Multi-Criteria Detectors:Photoelectric chambers paired with carbon monoxide sensing reduce nuisance alarms in dusty HVAC environments.
- Dual-Sensor Detectors:Combined photoelectric and thermal detection addresses mixed fire risk profiles in industrial duct applications.
Leading the category by volume: Conventional Detectors. Expanding most quickly: Addressable Detectors.
Technology:
Performance tiering separates legacy ionic maintenance from photoelectric specification dominance in new commercial construction.
- Photoelectric Technology:Light-scattering chambers detect smoldering fires at 0.5% to 4.0% obscuration per foot sensitivity. United States engineering firms specify these exclusively for ASHRAE Guideline 36 compliance in Texas and California design-build contracts.
- Ionic Technology:Americium-241 based ionization chambers detect fast-flaming combustion but face regulatory phase-out pressures. Legacy replacement demand persists in United States jurisdictions with extended code grandfathering periods.
- Heat Sensors:Fixed-temperature and rate-of-rise thermal detection supplements smoke sensing in high-airflow industrial environments.
- Hybrid Technology:Combined sensing modalities address complex fire signatures in data center and cleanroom applications.
Photoelectric Technology commands specification preference. Hybrid Technology gains share fastest in specialized verticals.
End User:
Customer type determines sensitivity requirements, with institutional buyers prioritizing addressable integration and residential developers minimizing per-unit cost.
- Commercial Buildings:Office towers, retail centers, and hospitality properties require NFPA 90A compliant detection in air handling systems exceeding 2,000 cfm. United States property management platforms in Class A buildings specify multi-criteria units to reduce false alarm penalties.
- Industrial Facilities:Manufacturing plants and warehouses demand ruggedized housings with extended temperature ratings for harsh duct environments.
- Residential Units:Multi-family construction drives demand for compact duct-mount units in centralized HVAC systems.
- Educational Institutions:K-12 and university campuses prioritize addressable systems for centralized monitoring across dispersed buildings.
Commercial Buildings anchor procurement volume. Educational Institutions show steepest specification upgrade trajectory.
Installation Type:
Mounting configuration selection tracks HVAC system architecture, with duct-specific designs commanding premium positioning against general-purpose alternatives.
- Duct Mount:Sampling tubes extend into HVAC airstreams with adjustable penetration depths for rectangular and round ductwork. United States fire alarm contractors specify these for NFPA 90A compliance in variable air volume systems.
- Integrated Systems:Factory-coordinated detector and damper assemblies streamline commissioning in complex smoke control sequences.
- Ceiling Mount:Standard spot-type detectors adapted for return air plenum monitoring in limited applications.
- Wall Mount:Remote sensor housings for accessible maintenance in restricted ceiling spaces.
Duct Mount configurations lead by unit volume. Integrated Systems climb fastest as ASHRAE 36 compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and Shanghai concentrate electronics manufacturing for fire safety components serving Asia-Pacific retrofit demand.
United States
Commercial building stock exceeding 5.8 billion square feet drives replacement cycles for legacy ionic detectors. NFPA 90A mandates from the National Fire Protection Association now require placement in air handling systems above 2,000 cfm. Houston and Dallas engineering firms specify addressable multi-criteria units for ASHRAE Guideline 36 compliance in Texas medical center expansions.
China
High-rise construction in tier-one cities generates demand for GB-standard compliant detection systems. The Ministry of Emergency Management enforces elevated performance benchmarks through updated fire safety regulations. Shenzhen manufacturers supply photoelectric sensing modules to domestic integrators serving mixed-use towers in Shanghai and Beijing.
Germany
DGNB green building certification creates procurement preference for integrated fire-HVAC monitoring systems. The country's federal building code harmonizes with EU construction product regulations for smoke control equipment. Frankfurt and Rotterdam property management platforms unbundle detector maintenance from panel monitoring agreements in commercial real estate portfolios.
India
Smart city infrastructure tenders in Bengaluru and Mumbai specify addressable duct detection for metro rail ventilation systems. The Bureau of Indian Standards issues certification requirements for fire alarm components in public buildings. Maharashtra state urban development authorities mandate upgraded detection in commercial complexes exceeding specified occupancy thresholds.
United Kingdom
London commercial retrofits accelerate replacement of conventional 24VDC wiring architectures with addressable loops. Building Regulations Approved Document B shapes detector placement requirements in air handling systems. Southeast England engineering consultants embed smoke control sequence specifications in design-build contracts for healthcare and education verticals.
Duct Smoke Detectors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product architecture tiers. The vendor base clusters around three strategic positions: integrated fire-HVAC platform providers, specialized sensing technology developers, and channel-dense retrofit distributors. Consolidation pressures favor scale players with captive distribution, while regional specialists defend positions through certification expertise. Dominant competitive moves include strategic partnerships with building automation vendors and portfolio diversification into multi-criteria detection.
Within the diversified conglomerate tier, Honeywell International Inc. and GENTEX CORPORATION occupy anchor positions through platform breadth and specialized architectures respectively. Kidde exemplifies the channel-density archetype, leveraging distributor relationships across North American retrofit markets. Hochiki America Corporation and Apollo America Inc. represent the specialist manufacturing segment with concentrated expertise in photoelectric sensing applications.
| Leading Market Players |
|---|
| Kidde |
| National Time & Signal |
| Potter Electric Signal Company, LLC |
| Greystone Energy Systems Inc. |
| Space Age Electronics, Inc. |
| Honeywell International Inc. |
| Apollo America Inc. |
| GENTEX CORPORATION |
| Hochiki America Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between UL 268A listed addressable units and conventional 24VDC detectors manifests in both pricing power concentration and supply chain configuration. Premium-tier manufacturers in the United States command project-based pricing for multi-criteria detection with BACnet integration, while commodity-tier suppliers in China compete on spot inventory availability for basic photoelectric replacements.
Pricing Analysis
Short lead-time premiums of 15-25% apply to addressable detector orders requiring UL 268A certification documentation within standard commercial construction windows. The dominant pricing structure runs project-based for integrated fire-HVAC specifications, with price differentiation driven by certification tier and after-sales calibration bundling. Cost compression in conventional detector tiers is intensifying because semiconductor input constraints from Taiwan foundries are forcing allocation prioritization toward higher-margin addressable ASICs. Educational institutions and municipal buyers exhibit highest price sensitivity, while United States healthcare verticals demonstrate lowest sensitivity given penalty avoidance priorities.
Supply Chain Analysis
UL 268A and GB standard certification gating restricts qualified manufacturing to facilities with sustained testing laboratory relationships, concentrating component supply in the United States, China, and Germany. Photoelectric sensing chambers draw from specialized optical component suppliers in Japan and Taiwan, while addressable communication modules rest on foundry output from South Korea. Single-source vulnerability in ASIC fabrication creates exposure to foundry allocation shifts. Distribution runs through fire alarm contractor networks with NICET-certified technician requirements, limiting direct OEM access to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The duct smoke detectors market sits in a technology-transition phase where photoelectric and multi-criteria architectures are systematically displacing legacy ionic technology. Facilities managers are rewriting specification documents to exclude ionization-based units despite code grandfathering provisions in older United States commercial buildings.
For Market Incumbents: Extend platform integration capabilities to capture ASHRAE Guideline 36 specification mandates in Texas and California medical center expansions. Deepen backward integration into photoelectric sensing chamber production to offset Taiwan foundry allocation constraints. Certification investment in BACnet and Modbus interoperability represents the critical defensive lever against building automation vendor encroachment.
For New Entrants and Emerging Players: Begin with India's smart city infrastructure tenders in Bengaluru and Mumbai, where addressable duct detection specifications for metro rail ventilation lack established incumbent relationships. Target Germany's DGNB green building certification projects requiring integrated fire-HVAC monitoring, a segment where specialist expertise outweighs brand recognition. A go-to-market angle through detector calibration certification for unbundled European service contracts opens channel access without panel manufacturing investment.
For Investors and Strategic Acquirers: Re-rating potential sits with addressable detector specialists given NFPA 90A mandate expansion across United States commercial portfolios. Long-term viability over a 5-10 year horizon favors manufacturers with captive photoelectric sensing technology and UL 268A testing relationships. Acquisition targets should display concentrated expertise in multi-criteria detection for healthcare verticals. The signal to watch is ionic technology phase-out acceleration in United States state-level code updates, which would compress legacy replacement revenue windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Criteria Detection Platform Launch | Photoelectric-CO sensing combinations reduce nuisance alarms in United States hospital HVAC returns. |
| Building Automation System Integration | BACnet certification opens specification pathways with Honeywell and Siemens control platforms. |
| UL 268A Testing Laboratory Partnership | Shortened certification timelines compress product launch cycles from fourteen to eight months. |
| India Smart City Tender Participation | Maharashtra state mandates create procurement preference for addressable metro ventilation detection. |
| Photoelectric Sensing Chamber Backward Integration | Captive optical component supply insulates against Japan and Taiwan supplier allocation constraints. |
Research Methodology
Independent corroboration across fire alarm contractor interviews, facilities manager surveys, and regulatory filing analysis underwrites the qualitative findings in this study. Primary fieldwork engaged fire safety engineers, NICET-certified technicians, building automation integrators, and commercial property managers across United States, Chinese, and German markets. Secondary validation drew from NFPA code documentation, UL certification records, GB standard publications, and ASHRAE guideline releases. Bottom-up detector shipment analysis triangulated against top-down construction spending data to establish market sizing.
Rate-of-change decomposition across product type, technology, end user, and installation type dimensions structures the analytical framework. Segmentation modeling incorporated addressable versus conventional architecture splits, photoelectric versus ionic technology transitions, and ASHRAE Guideline 36 compliance penetration rates. CAGRs were derived from installed base replacement cycle analysis and new construction specification trend extrapolation. Industry-specific forecast inputs included HVAC retrofit intensity indices and green building certification adoption curves.
Underlying measurement precision varies by segment; addressable detector forecasts carry tighter precision than conventional replacement projections due to clearer specification documentation. Forecasts reflect assumptions regarding NFPA 90A enforcement consistency and semiconductor supply normalization. A model refresh is warranted upon material change in United States building code grandfathering provisions or Taiwan foundry allocation policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Electronic Article Surveillance Market