
 Walk Through Metal Detector Market | 2026-2036
Walk Through Metal Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Walk Through Metal Detector Market Analytics
Aftermarket service revenue is reconfiguring margin capture across the competitive landscape. CEIA sustains technology leadership through its deep specialization in multi-spectral threat detection architectures. Garrett Electronics anchors its position via extensive channel control across North American stadium and school installations. Smiths Detection differentiates through vertical integration into government security contracts and critical infrastructure screening programs.
A walk through metal detector is an electromagnetic screening portal that generates controlled magnetic fields to identify ferrous and non-ferrous metallic objects concealed on persons passing through its frame, typically operating at frequencies between 1 kHz and 100 kHz with multi-zone coil arrays for spatial localization. The device serves primary commercial purpose in mass transit hubs, entertainment venues, and institutional buildings where high-throughput threat interception balances pedestrian flow efficiency. Fixed installations command the dominant share of technology deployment, reflecting permanent infrastructure commitments at airports and government facilities where total cost of ownership calculations favor stationary configurations over portable alternatives. Electromagnetic detection architectures lead the technology dimension, though inductive systems gain traction in environments demanding reduced false-alarm rates for non-threat metallic items.
FAA directives for checkpoint screening standards, TSA certification requirements for explosive trace detection integration, and EU CE marking under the Electromagnetic Compatibility Directive collectively shape product design thresholds and market access conditions for equipment suppliers. NHTSA guidelines for transportation facility security and OSHA workplace safety protocols further extend regulatory touchpoints across institutional buyer segments. Stakeholders must monitor evolving AI governance frameworks and cross-border data handling rules as connected screening systems proliferate.
Market Dynamics
AI-enhanced threat classification is compressing procurement cycles at major transportation hubs, forcing incumbent suppliers to rearchitect detection algorithms around machine-learning inference pipelines rather than legacy signature-matching approaches.
Growth Catalysts
- FAA Checkpoint Modernization Directives:United States aviation regulators mandate upgraded electromagnetic screening thresholds, compelling airport authorities to replace single-zone units with multi-zone coil arrays.
- India Metro Rail Expansion:Mass transit infrastructure buildout across Delhi, Mumbai, and Bangalore generates sustained volume demand for high-throughput pedestrian screening portals.
- Millimeter-Wave Sensor Fusion:Hybrid detection architectures combining inductive coils with passive millimeter-wave imaging reduce false-alarm rates for non-threat metallic items.
Market Restraints
- Copper Coil Input Volatility:Electromagnetic detection architectures depend on precision-wound copper coil assemblies, exposing manufacturers to London Metal Exchange price swings.
- Chinese Component Concentration:Power supply modules and signal processing chipsets concentrate among Shenzhen-based electronics suppliers, creating single-source vulnerability.
- EU AI Act Compliance Friction:Risk classification requirements for biometric identification systems impose documentation burdens on connected screening platforms with facial recognition integration.
Strategic Opportunities
- Saudi Giga-Project Security Infrastructure:NEOM and Red Sea tourism developments require integrated perimeter screening systems at unprecedented scale.
- AI-Assisted Maintenance Contracts:Predictive failure analytics enable suppliers to unbundle hardware sales from recurring remote diagnostics revenue streams.
- Brazil Correctional Facility Modernization:Federal penitentiary expansion programs under ANVISA safety mandates create demand for contraband detection at visitor entry points.
Industry Challenges
- Electromagnetic Compatibility Certification:CE marking under the EU Electromagnetic Compatibility Directive requires extensive third-party testing, extending product launch timelines by 8-14 months.
- Legacy Analog System Integration:Airport authorities with installed bases of 1990s-era single-zone detectors face forklift upgrade costs that strain capital allocation committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walk Through Metal Detector Market |
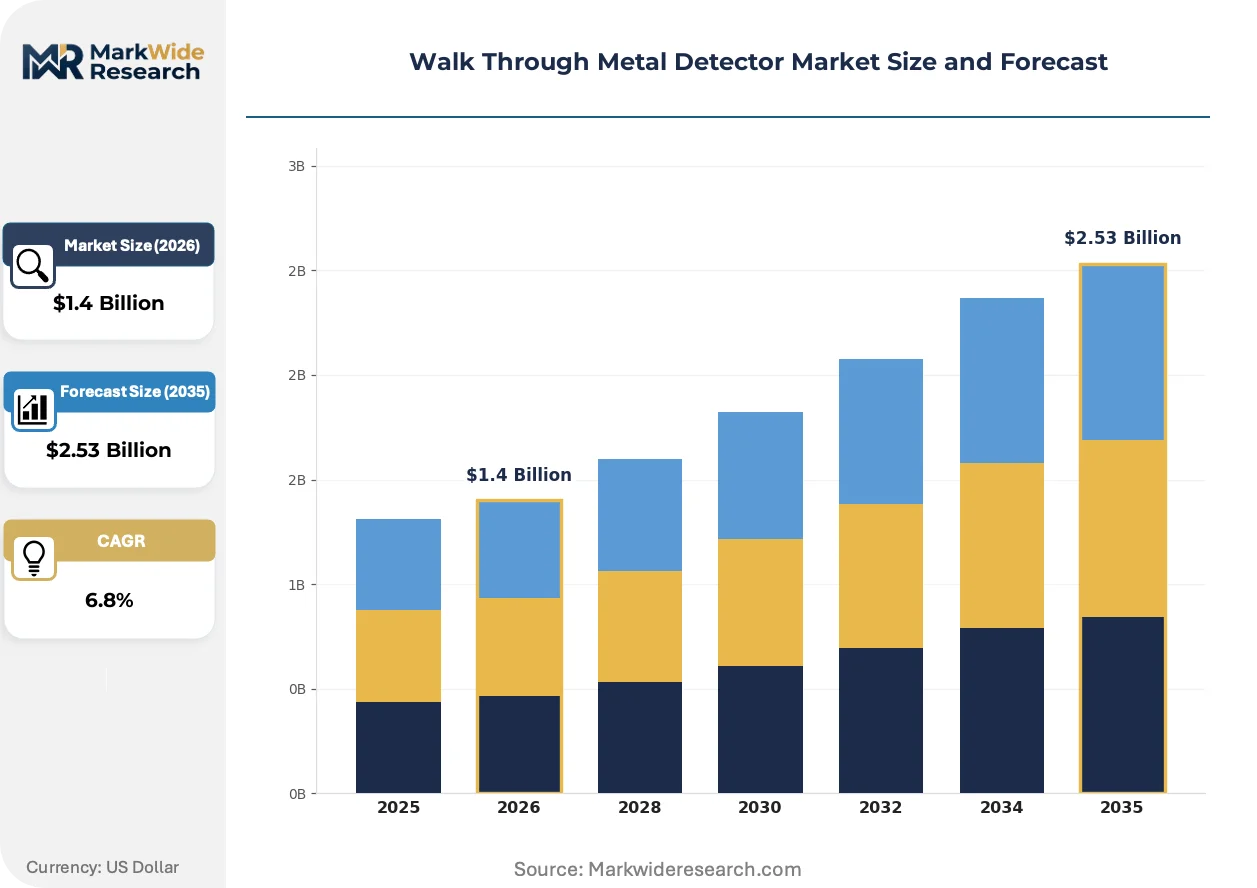
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Airports, Stadiums, Malls, Schools Technology: Electromagnetic, Inductive, Magnetic, Optical Installation: Fixed, Portable, Temporary, Permanent Application: Security Screening, Access Control, Event Management, Risk Assessment |
| Companies Covered | CEIA, Nuctech Company, Smiths Detection, Garrett Electronics, Rapiscan Systems, Safeway Inspection System, ZKTeco, Leidos, Safran Morpho Detection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walk Through Metal Detector Market Evolving Landscape
Detection architectures are bifurcating between premium AI-native platforms and cost-optimized electromagnetic workhorses, with procurement committees weighing total cost of ownership against threat-interception sophistication.
Deep-learning inference engines trained on synthetic threat libraries now power real-time classification of ferrous and non-ferrous signatures. Major United States airport authorities deploy these systems at primary checkpoints, compressing passenger processing rates while rendering obsolete rule-based discrimination algorithms that required manual sensitivity recalibration.
The EU AI Act establishes conformity assessment obligations for biometric identification subsystems integrated into screening portals. Equipment suppliers must document algorithmic transparency and bias mitigation protocols, with German critical infrastructure operators already demanding third-party algorithmic audits as contract preconditions.
Service unbundling is fragmenting traditional hardware-plus-maintenance bundles into discrete software subscription, remote diagnostics, and on-site technical support tiers. Large United States school districts and municipal stadium operators now separately negotiate AI analytics modules from base electromagnetic detection hardware, with procurement teams favoring vendors offering API-accessible threat data feeds.
Walk Through Metal Detector Market Segmentation
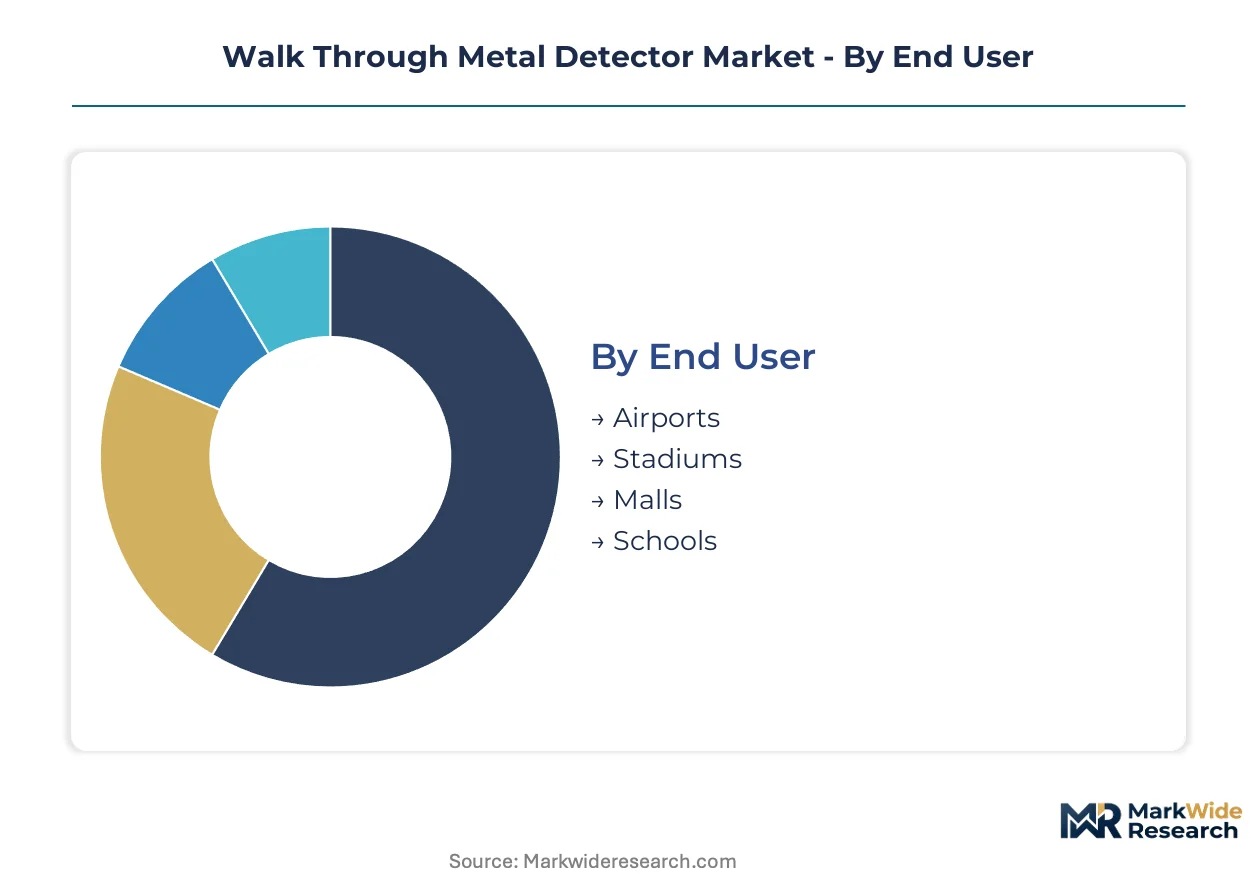
End-user procurement patterns diverge sharply across threat environments, with aviation authorities demanding multi-zone precision while educational institutions prioritize throughput economics. Technology selection follows installation permanence and operational tempo rather than threat sophistication alone.
End User:
Application context dictates performance thresholds and certification requirements across buyer categories.
- Airports:Multi-zone electromagnetic architectures with FAA-certified sensitivity bands dominate procurement specifications. United States aviation authorities mandate explosive trace detection integration at primary checkpoints, compressing vendor qualification timelines.
- Stadiums:High-throughput pedestrian screening balances contraband interception with queue velocity during event ingress. Municipal operators in Germany and China favor modular coil arrays permitting rapid sensitivity reconfiguration between concert and sporting event profiles.
- Malls:Retail security managers prioritize discrete form factors and reduced audible alarm disruption. Electromagnetic detection units with directional LED indicators concentrate in Middle Eastern luxury retail developments.
- Schools:Budget-constrained districts select single-zone inductive systems with minimal maintenance overhead. United States K-12 procurement committees favor TSA-approved equipment lists for grant funding eligibility.
Airports command the established base. The steepest expansion runs through Schools.
Technology:
Detection physics determine false-alarm rates, metallic discrimination depth, and electromagnetic compatibility compliance burdens.
- Electromagnetic:Precision-wound copper coil assemblies generate controlled magnetic fields between 1 kHz and 100 kHz. Airport authorities in China and the United States specify electromagnetic architectures for primary checkpoint deployment due to established FAA and CAAC certification pathways.
- Inductive:Eddy-current sensing reduces nuisance alarms from benign metallic objects including coins and belt buckles. German critical infrastructure operators specify inductive systems for government facility lobbies under EU Electromagnetic Compatibility Directive requirements.
- Magnetic:Fluxgate magnetometer arrays detect ferromagnetic anomalies with minimal power consumption. Correctional facilities in Brazil deploy magnetic detection at visitor screening points under ANVISA safety mandates.
- Optical:Passive millimeter-wave and infrared fusion architectures supplement inductive coils for non-metallic threat identification. Saudi Giga-project security specifications require optical-electromagnetic hybrid systems at perimeter checkpoints.
Electromagnetic systems anchor current procurement volumes. Inductive platforms are gaining share fastest in environments demanding reduced false-alarm rates.
Installation:
Capital commitment horizon and relocation frequency shape hardware configuration selection.
- Fixed:Permanent frame-mounted installations with embedded power and network infrastructure. Airport terminals in the United States, Germany, and China favor fixed configurations where total cost of ownership calculations amortize acquisition over decade-long operational lifespans.
- Portable:Battery-powered collapsible units with rapid deployment capability. Indian metro rail authorities procure portable systems for temporary construction-phase screening at Delhi and Mumbai station sites.
- Temporary:Short-term rental configurations for discrete events or facility maintenance windows. Brazilian federal penitentiary expansion programs lease temporary units during visitor entry point construction.
- Permanent:Architecturally integrated screening portals with custom cladding and building management system connectivity. Saudi NEOM development specifications mandate permanent installations with API-accessible threat data feeds.
Fixed installations dominate infrastructure-heavy deployments. Portable configurations show the steepest demand acceleration in transit construction phases.
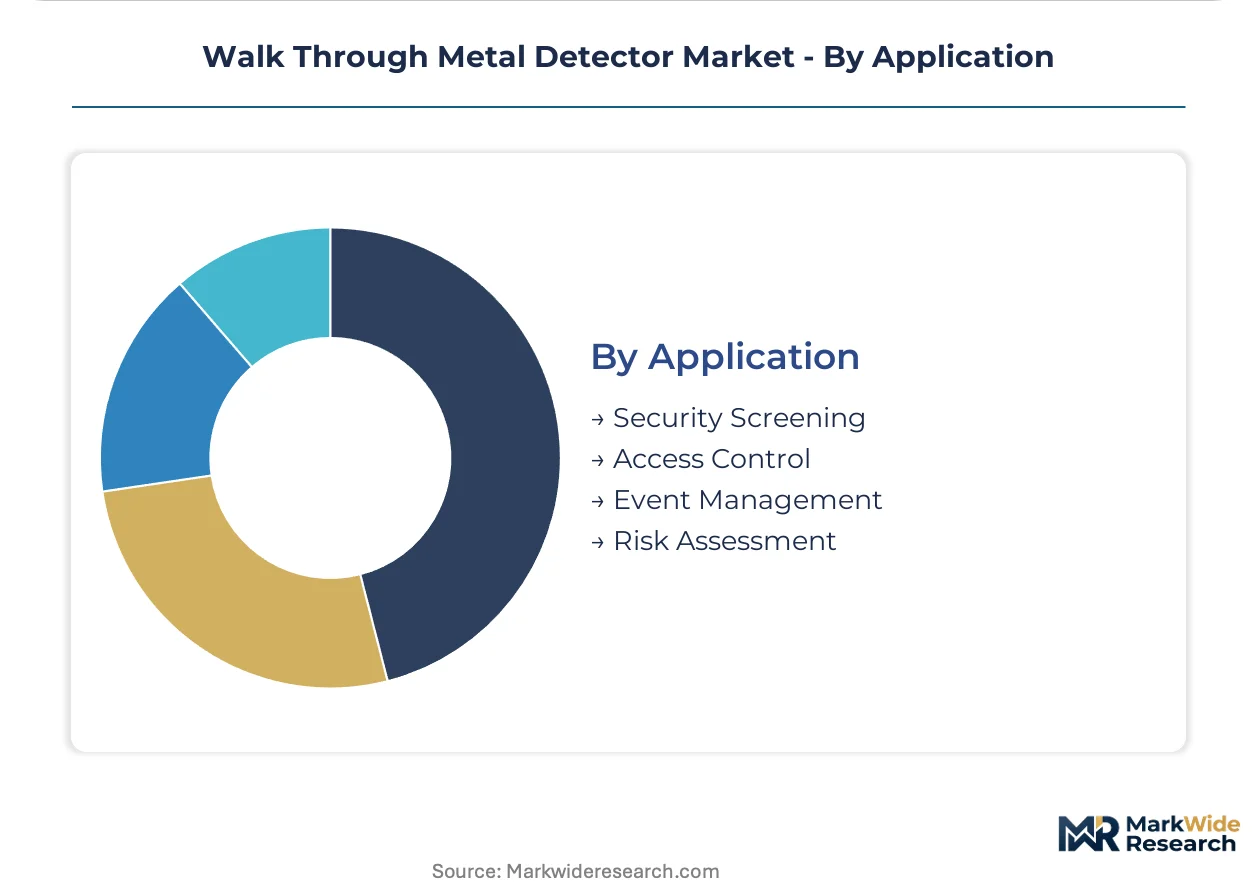
Application:
Operational purpose determines sensor fusion requirements and data retention protocols.
- Security Screening:Primary threat interception at mass transit and critical infrastructure entry points. United States TSA certification requirements and EU CE marking shape product design thresholds for security screening deployments.
- Access Control:Credential-verified entry management with metallic object logging. German government facilities integrate access control screening with biometric identification systems subject to EU AI Act conformity assessments.
- Event Management:Temporary crowd safety operations with rapid sensitivity calibration. Stadium operators in China deploy event management configurations for mixed-use venues hosting international exhibitions.
- Risk Assessment:Anomaly detection with predictive analytics for behavioral pattern analysis. United States school districts pilot risk assessment modules with AI-enhanced threat classification algorithms.
Security Screening represents the revenue core. Risk Assessment applications are climbing the fastest as AI governance frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States aviation authorities prioritize multi-zone precision for explosive trace integration, while Indian transit operators favor portable configurations for construction-phase deployment. German critical infrastructure mandates EU AI Act compliance for biometric screening, and Saudi Giga-projects demand architecturally integrated permanent installations.
United States
FAA checkpoint modernization directives and TSA certification requirements drive airport authority procurement of multi-zone electromagnetic arrays. Federal mandates for explosive trace detection integration compress vendor qualification timelines at primary screening points. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor demand concentration as authorities replace single-zone legacy units.
China
CAAC certification pathways and mass transit infrastructure buildout sustain volume demand across aviation and metro rail applications. GB standards for electromagnetic compatibility shape product design thresholds for domestic suppliers. Beijing Capital and Shanghai Pudong airports concentrate procurement of AI-enhanced threat classification systems.
Germany
EU Electromagnetic Compatibility Directive requirements and EU AI Act conformity assessments govern government facility procurement. Critical infrastructure operators demand third-party algorithmic audits for biometric identification subsystems. Frankfurt and Munich airports specify inductive systems with reduced false-alarm rates for non-threat metallic items.
India
Metro rail expansion across Delhi, Mumbai, and Bangalore generates sustained demand for high-throughput pedestrian screening. Bureau of Indian Standards certification requirements and CEA electrical safety protocols extend regulatory touchpoints. Delhi Metro Rail Corporation procures portable configurations for temporary construction-phase screening at station sites.
Saudi Arabia
NEOM and Red Sea tourism developments require integrated perimeter screening systems at unprecedented scale. SFDA safety mandates and critical infrastructure protection budgets expand procurement authorization. Riyadh and the Western Region concentrate demand for permanent installations with API-accessible threat data feeds.
Walk Through Metal Detector Market Competitive Landscape
Capability concentration sits with specialized electromagnetic architecture designers; scale advantage sits with diversified security equipment conglomerates. The vendor base organizes around three strategic archetypes: multi-spectral threat detection specialists, channel-controlled North American installers, and government-contract-integrated critical infrastructure suppliers. Consolidation pressure operates through technology licensing agreements and strategic partnerships rather than outright acquisition.
Among Italy-based specialists, CEIA exemplifies the multi-spectral detection architecture tier. Garrett Electronics occupies a position within the channel-controlled installation segment across North American stadium and school markets. Smiths Detection anchors the government-contract-integrated archetype through critical infrastructure screening program relationships. These three company representations illustrate how competitive positioning fragments across technology specialization, geographic channel control, and vertical market depth rather than converging on unified scale leadership.
| Leading Market Players |
|---|
| CEIA |
| Nuctech Company |
| Smiths Detection |
| Garrett Electronics |
| Rapiscan Systems |
| Safeway Inspection System |
| ZKTeco |
| Leidos |
| Safran Morpho Detection |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese signal processing module production is compressing supplier margins while forcing electromagnetic detection manufacturers toward longer contract terms that lock in component pricing. This utilization dynamic simultaneously erodes pricing power at the component tier and incentivizes downstream bundling of hardware with recurring service revenue streams.
Pricing Analysis
Long-term offtake agreements dominate procurement between airport authorities and established electromagnetic detection suppliers, insulating buyers from copper coil volatility while locking in multi-zone array pricing. Three-tier pricing structure across premium AI-native platforms, standard FAA-certified systems, and economy inductive units differentiates by certification grade and after-sales integration depth. Cost compression in the economy tier intensifies because Chinese power supply module overcapacity feeds aggressive quoting by emerging vendors. Schools and municipal stadium operators exhibit the highest price sensitivity, while aviation authorities prioritize threat-interception sophistication over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk planning for electromagnetic detection manufacturers dependent on Shenzhen-sourced signal processing chipsets and precision-wound copper coil assemblies. Production gravity centers on China for power electronics, Germany for inductive sensing components, and the United States for AI inference hardware. The supply chain draws from copper concentrate markets, rare-earth magnet materials, and semiconductor foundry capacity. Single-source vulnerability concentrates in Chinese power supply modules. Distribution runs through authorized security equipment dealers and direct government contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enhanced threat classification is compressing procurement cycles and reconfiguring competitive advantage around software-native detection architectures rather than legacy electromagnetic hardware. FAA mandates for explosive trace integration and EU AI Act conformity assessments for biometric subsystems accelerate this disruption.
For Market Incumbents: Pre-empt algorithmic obsolescence by acquiring synthetic threat library training capabilities and rearchitecting detection pipelines around machine-learning inference rather than signature-matching approaches. CEIA and Smiths Detection should deepen backward integration into multi-spectral sensor fusion components to defend margin position against modular AI-native entrants. Channel control across North American stadium and school installations remains a defensible lever against price erosion.
For New Entrants and Emerging Players: Brazilian federal penitentiary expansion programs under ANVISA safety mandates represent the most penetrable white-space target, with magnetic detection demand for visitor screening points outpacing established supplier presence. Indian metro rail construction phases offer portable configuration entry points where temporary deployment models bypass entrenched fixed-installation incumbents. A software-first go-to-market angle unbundling AI analytics modules from base hardware resonates with municipal procurement committees.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with predictive maintenance contracts and API-accessible threat data feeds, positioning service-unbundled business models for premium valuation multiples. Acquisition targets should exhibit installed base scale in aviation or critical infrastructure verticals with multi-year replacement cycles. The signal to monitor is FAA certification queue length for explosive trace detection integration, as backlog compression indicates inflection toward AI-native platform procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Detection Platform Launch | Machine-learning inference engines trained on synthetic threat libraries displace legacy signature-matching algorithms at TSA-certified checkpoints. |
| Explosive Trace Detection Integration | FAA mandates compress vendor qualification timelines and favor suppliers with pre-certified multi-zone electromagnetic array architectures. |
| Service Unbundling and Subscription Conversion | Predictive maintenance contracts and remote diagnostics revenue streams decouple hardware margins from recurring software monetization. |
| Strategic Partnership for Millimeter-Wave Sensor Fusion | Hybrid architectures combining inductive coils with passive imaging reduce false-alarm rates for non-threat metallic items at German critical infrastructure facilities. |
| Geographic Expansion into Saudi Giga-Projects | NEOM and Red Sea tourism developments require integrated perimeter screening systems with architecturally integrated permanent installations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with airport security directors, TSA procurement officials, electromagnetic detection R&D leads, and critical infrastructure protection officers; and secondary validation against FAA certification databases, EU CE marking registries, BIS standards filings, and customs trade records for copper coil and power electronics imports. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against aviation authority capital expenditure budgets anchored volume estimates.
Forecast inputs span technology segmentation by detection physics, installation permanence categories, end-user verticals from aviation to correctional facilities, and geographic regulatory clusters. CAGRs were derived from elasticity modeling against infrastructure investment cycles and replacement timelines for legacy single-zone units. Copper price volatility indices and AI governance framework adoption curves fed scenario-weighted projections across the analysis window.
Practitioners should monitor FAA checkpoint modernization directive implementation pace and EU AI Act biometric subsystem enforcement intensity for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Surge Suppression IC Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Digital Underground Metal Detector Market