
 Europe Trace Detection Market | 2026-2036
Europe Trace Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Trace Detection Market Insights
Modular sensor packaging is broadening buyer choice across the Europe Trace Detection Market, as vendors unbundle hardware from software subscriptions and service contracts. Smiths Detection Group Ltd leverages its vertical integration into detector manufacturing to sustain premium positioning in airport security lanes. Teledyne FLIR LLC anchors its European presence through specialized handheld platforms for military and law enforcement channels. Bruker Corporation differentiates via R&D intensity in mass spectrometry architectures that serve forensic laboratories.
Europe trace detection encompasses analytical instrumentation designed to identify minute quantities of explosives, narcotics, chemical warfare agents, and toxic industrial chemicals at parts-per-billion sensitivity thresholds, employing ion mobility spectrometry, gas chromatography, and surface-enhanced Raman spectroscopy as core detection modalities. These systems serve critical screening functions across transportation nodes, industrial facilities, and criminal justice settings where rapid material identification prevents harm or enables prosecution. Ion mobility spectrometry dominates current procurement volumes due to its speed and portability, while surface-enhanced Raman spectroscopy represents the fastest-expanding technology segment as forensic laboratories adopt non-destructive molecular fingerprinting. Security screening applications command the largest share of deployed units, though environmental monitoring is gaining structural importance under tightening EU chemical emissions frameworks.
The EU AI Act and MDR frameworks are reshaping product certification requirements for automated detection systems, while REACH and the F-Gas Regulation constrain material inputs and refrigerant-based sample preparation methods. ECHA's evolving substance restrictions directly influence detector design specifications and supplier qualification pathways across member states. Stakeholders must monitor harmonized standards development under CEN-CENELEC to anticipate conformity assessment burdens before placing next-generation devices on the European market.
Market Dynamics
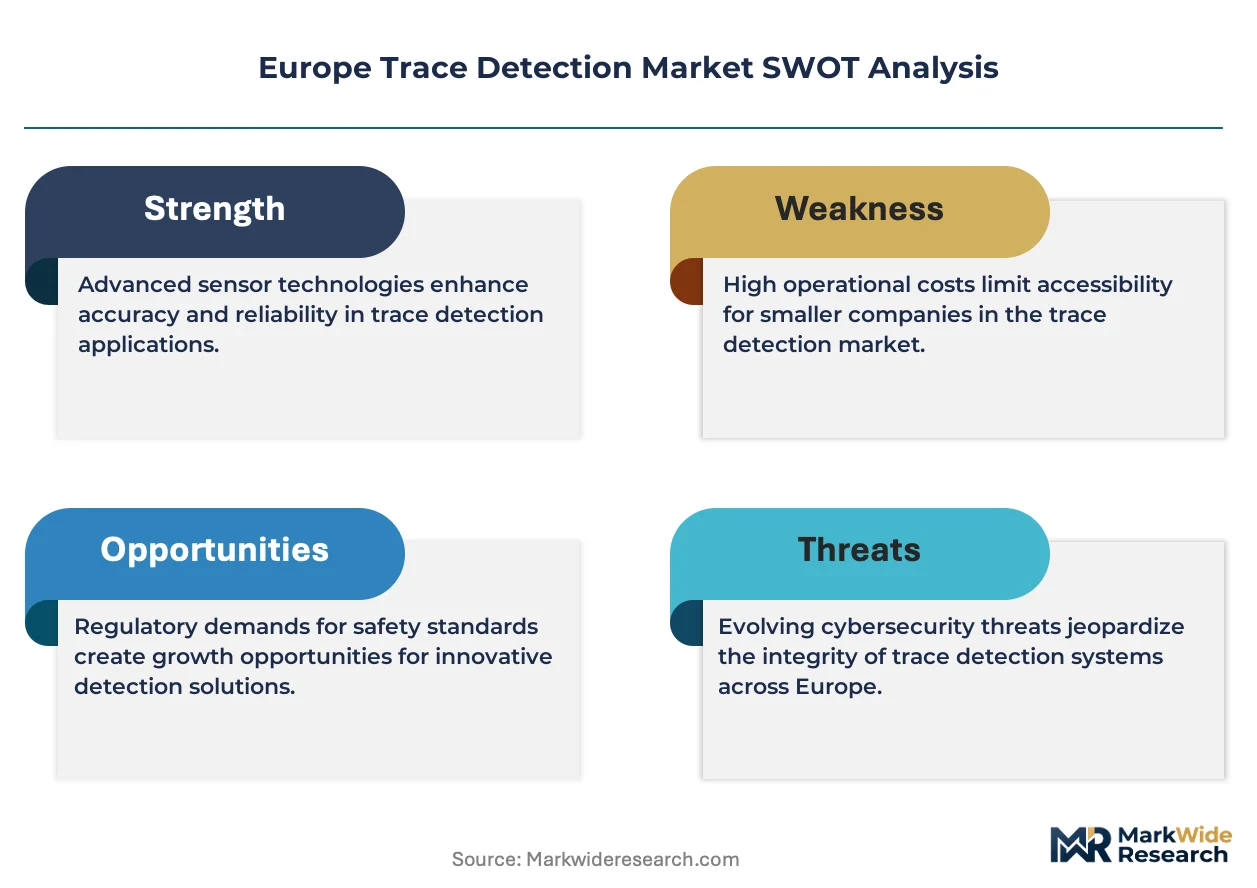
EU chemical disclosure mandates and refrigerant phase-outs are forcing detector manufacturers to redesign hardware architectures and supply chains simultaneously, compressing product development cycles while elevating compliance costs.
Growth Catalysts
- REACH substance restrictions:Chemical manufacturers across German industrial corridors must deploy real-time emissions monitoring, generating equipment refresh cycles at production facilities.
- Border control modernization:Schengen perimeter agencies in France and Italy are consolidating procurement of dual-use detection platforms for passenger and cargo lanes.
- Surface-enhanced Raman spectroscopy:Forensic laboratories in the Netherlands and Belgium are adopting non-destructive molecular fingerprinting to accelerate evidence processing.
Market Restraints
- Specialized sensor materials:Rare-earth components and noble-metal catalysts face price volatility and concentrated sourcing from limited supplier bases.
- F-Gas Regulation compliance:Legacy cooling systems in sample preparation modules require complete redesign, extending R&D timelines and certification costs.
- Substitution by canine teams:Explosives detection dogs retain cost advantages for low-throughput screening scenarios at smaller transportation nodes.
Strategic Opportunities
- Polish and Romanian border infrastructure:Eastern frontier expansion creates first-mover positioning for portable trace detector vendors establishing service networks.
- EU AI Act certification pathways:Automated detection algorithms with explainable output features qualify for expedited conformity assessment, differentiating compliant suppliers.
- Environmental monitoring convergence:Industrial safety and emissions compliance budgets are merging, enabling cross-selling of multi-threat detection platforms to chemical plant operators.
Industry Challenges
- Spectroscopy expertise scarcity:Mass spectrometry and Raman system engineering talent pools are shallow across European technical universities, constraining product development velocity.
- MDR certification timelines:Medical device classification for forensic toxicology applications extends regulatory approval periods beyond commercial planning horizons.
- Legacy system interoperability:Airport security networks operate mixed-vendor architectures, complicating data integration for next-generation detection nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Trace Detection Market |
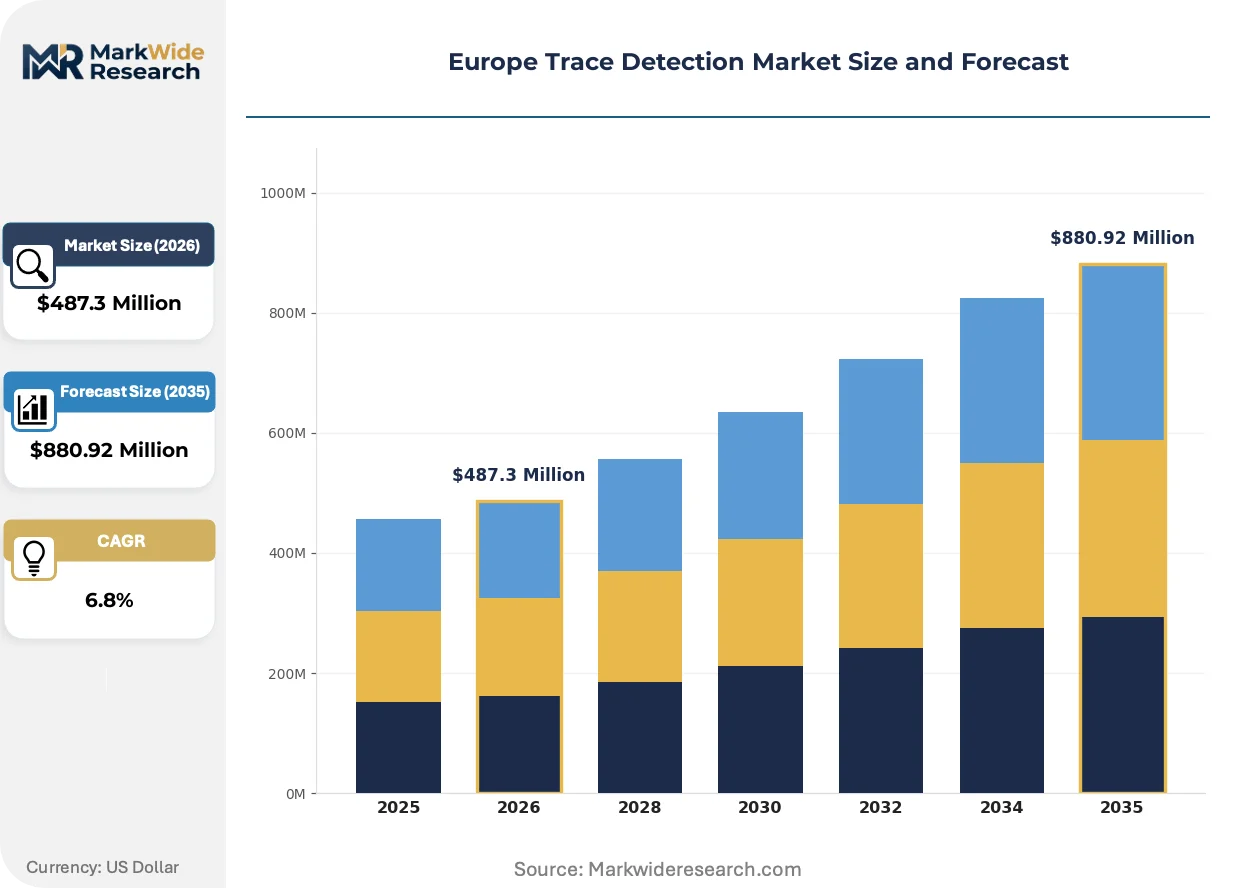
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
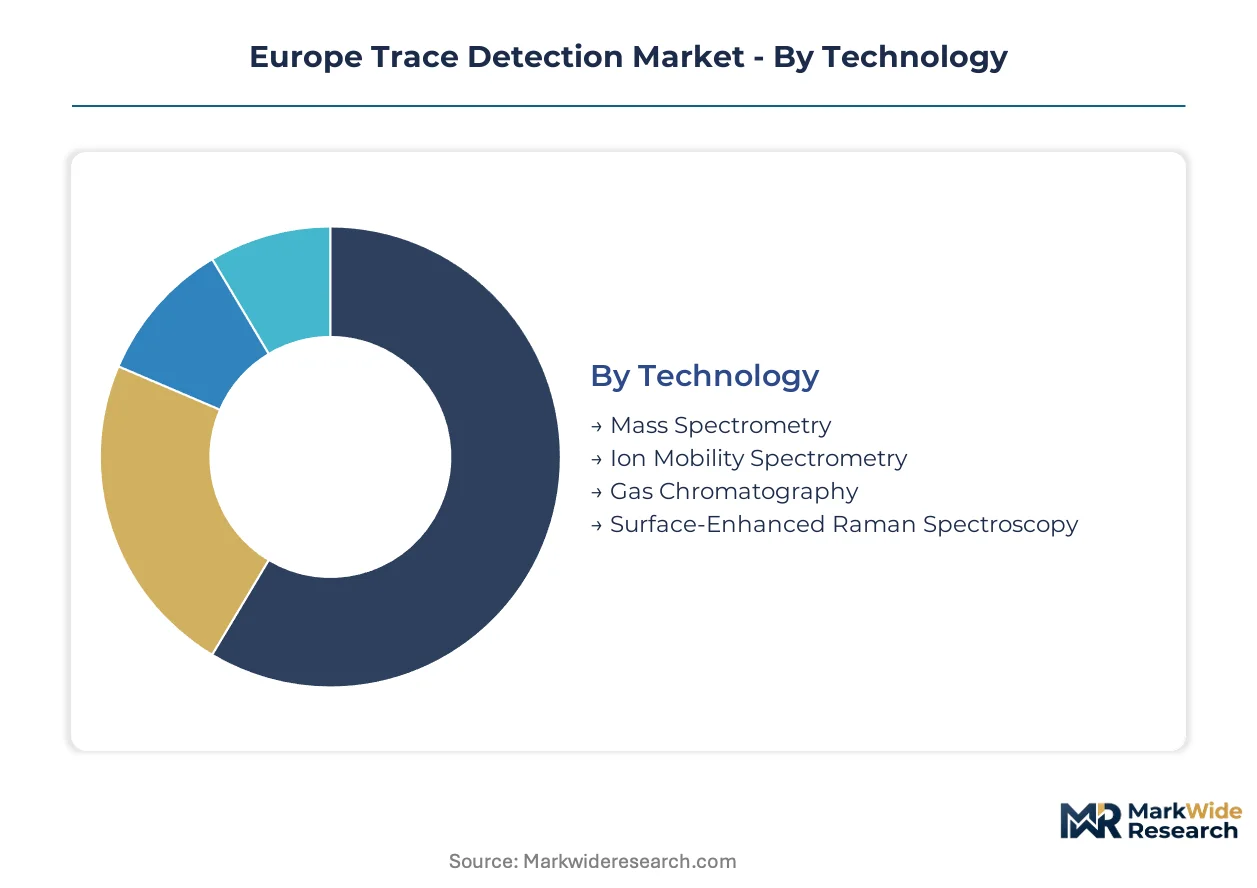
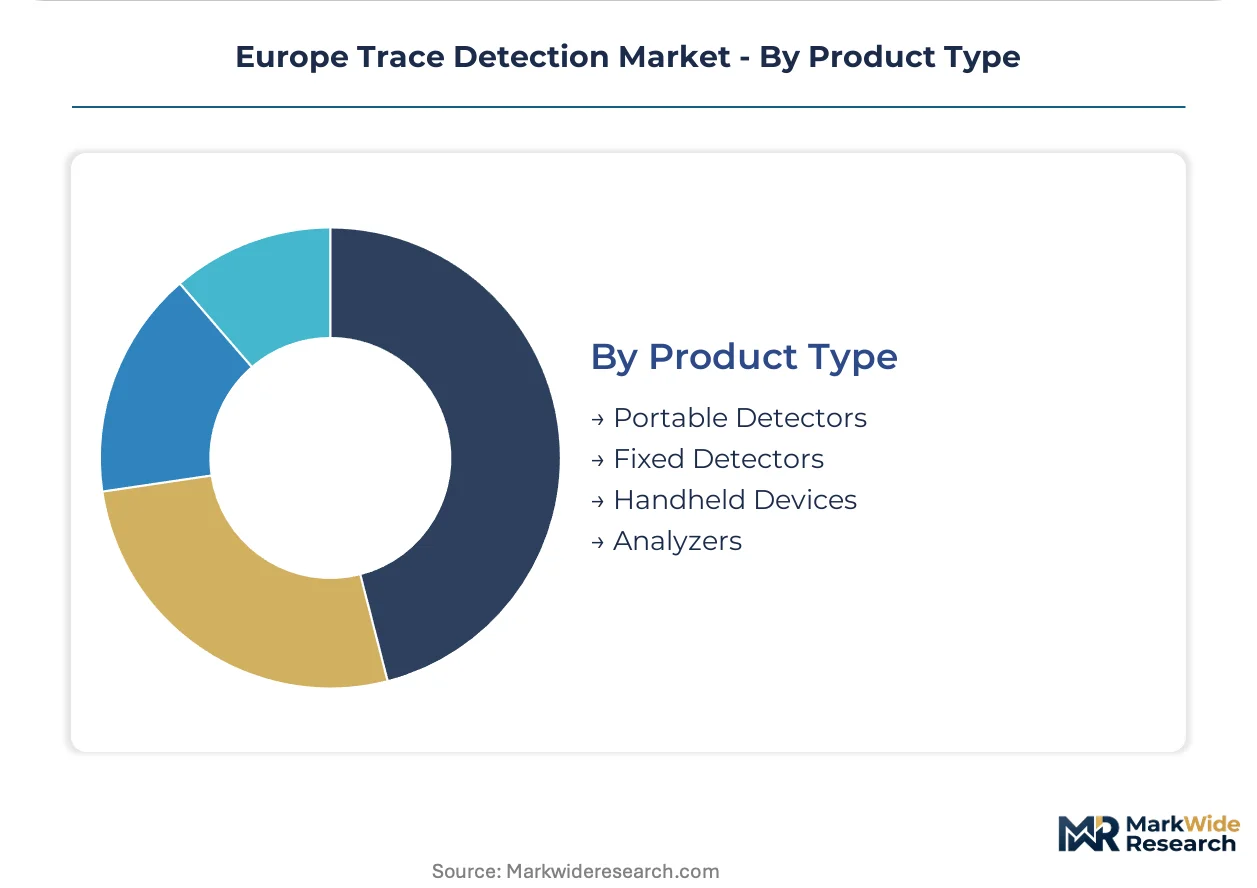
| Segmentation | Technology: Mass Spectrometry, Ion Mobility Spectrometry, Gas Chromatography, Surface-Enhanced Raman Spectroscopy Application: Security Screening, Environmental Monitoring, Forensic Analysis, Industrial Safety End User: Government Agencies, Law Enforcement, Research Institutions, Industrial Facilities Product Type: Portable Detectors, Fixed Detectors, Handheld Devices, Analyzers |
| Companies Covered | Smiths Detection Group Ltd, Teledyne FLIR LLC, Leidos Holdings Inc, Bruker Corporation, Autoclear LLC, OSI Systems Inc, Chemring Group PLC, NUCTECH COMPANY LIMITED, 3DX-RAY Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Trace Detection Market Trends and Innovations
Detection technology architectures are fragmenting into modular, service-enabled platforms that separate hardware ownership from analytical capability access, reshaping how buyers consume screening functionality.
Miniaturized ion mobility spectrometry sensors are rewriting the portability-performance tradeoff in security screening. German federal police units and French customs agencies are fielding handheld units that match benchtop sensitivity thresholds. This compression of form-factor constraints is enabling point-of-use deployment models that bypass centralized laboratory workflows entirely.
The EU AI Act's risk classification framework for automated decision systems is restructuring product development roadmaps for detection equipment with embedded classification algorithms. Manufacturers must now document training data provenance and algorithmic explainability before CE marking. Airport security integrators in the United Kingdom and Spain are prioritizing vendors with pre-validated conformity assessment packages to accelerate deployment timelines.
Service unbundling is restructuring buyer-supplier relationships across European public procurement channels. Dutch and Swedish border agencies are piloting detection-as-a-service contracts where vendors retain equipment ownership and deliver guaranteed uptime with performance-based payment terms. This shift transfers capital burden to suppliers while accelerating technology refresh cycles at operational sites.
Europe Trace Detection Market Segmentation
Trace detection procurement across Europe fragments sharply by certification pathway, with airport security lanes demanding CE-MDR dual marking while industrial emissions monitors navigate REACH substance restrictions. Buyers in German chemical corridors and French border agencies face divergent compliance burdens that reshape vendor qualification and deployment timelines.
Technology:
EU AI Act risk classification and MDR conformity assessment apply unevenly across detection modalities, with automated classification algorithms triggering stricter documentation requirements than passive spectroscopic methods.
- Ion Mobility Spectrometry:Dominant portable detection architecture utilizing drift-time measurement of ionized molecules at ambient pressure. German federal police and UK Border Force procurement concentrates here, driven by sub-10-second response requirements for passenger screening lanes.
- Surface-Enhanced Raman Spectroscopy:Non-destructive molecular fingerprinting employing plasmonic nanoparticle substrates to amplify weak Raman signals. Forensic laboratories in the Netherlands and Belgium are expanding adoption, constrained by ECHA scrutiny of silver nanomaterial inputs under REACH authorization procedures.
- Mass Spectrometry:High-resolution molecular identification through mass-to-charge ratio measurement, predominantly benchtop-deployed in analytical laboratories.
- Gas Chromatography:Separation-based detection requiring thermal desorption and column chromatography, common in industrial emissions verification.
Ion Mobility Spectrometry sits at the top of the volume ranking, with Surface-Enhanced Raman Spectroscopy climbing the fastest.
Application:
Procurement budgets diverge between security-focused agencies operating under Schengen border codes and industrial operators responding to tightening F-Gas Regulation enforcement.
- Security Screening:Passenger, cargo, and baggage threat detection at transportation nodes and critical infrastructure. French customs and Italian Carabinieri drive dual-use platform demand, consolidating explosives and narcotics detection into single-deployment units.
- Environmental Monitoring:Real-time emissions surveillance and chemical release detection at manufacturing perimeters. German chemical producers in the Ruhr and Ludwigshafen clusters face REACH-mandated monitoring obligations, generating equipment refresh cycles.
- Forensic Analysis:Laboratory-based evidence processing for criminal prosecution, requiring chain-of-custody documentation.
- Industrial Safety:Workplace exposure monitoring and confined-space entry verification, common in petrochemical and pharmaceutical manufacturing.
Security Screening commands the largest installed base, while Environmental Monitoring gains share fastest under tightening EU chemical disclosure frameworks.
End User:
Contracting authority type determines procurement channel complexity, with central government agencies leveraging framework agreements that smaller municipal forces cannot access.
- Government Agencies:National border control, customs, and transportation security authorities operating centralized procurement. Schengen perimeter agencies in Poland and Romania are expanding portable detector fleets ahead of eastern frontier infrastructure upgrades.
- Law Enforcement:Municipal and regional police forces with decentralized acquisition authority. Belgian and Dutch units prioritize handheld interoperability with existing radio and biometric systems.
- Research Institutions:University and national laboratory users demanding highest analytical sensitivity for method development.
- Industrial Facilities:Chemical, pharmaceutical, and energy sector operators integrating detection into safety and compliance workflows.
Government Agencies account for the dominant procurement volume, with Industrial Facilities expanding most quickly as emissions compliance budgets merge with safety spending.
Product Type:
Form-factor selection trades detection sensitivity against mobility, with fixed installations offering parts-per-trillion thresholds that portable units cannot match.
- Portable Detectors:Battery-operated units with field-replaceable consumables, designed for rapid deployment without infrastructure dependency. Polish and Romanian border modernization programs are driving tender volumes for lightweight platforms under 3 kilograms.
- Handheld Devices:Single-operator pistol-grip or wand-format detectors for point screening. French customs agencies field these for cargo container inspection, prioritizing ergonomic design for extended shift use.
- Fixed Detectors:Permanent-installation systems with continuous sampling and centralized alarm integration.
- Analyzers:Laboratory-grade benchtop instruments requiring controlled environment operation and trained technician staffing.
Portable Detectors lead procurement volumes, with Handheld Devices showing the steepest expansion trajectory as miniaturized sensor architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trace detection technology first achieved operational scale in European airport security lanes during the 1990s, with German and British authorities pioneering ion mobility spectrometry deployment for explosives screening. This institutional foundation established procurement patterns that persist across the continent today.
Germany
Federal police units and Ruhr chemical manufacturers drive dual-use detector demand. ECHA's REACH substance restrictions force real-time emissions monitoring at Ludwigshafen production clusters. Bavarian border control agencies consolidate explosives and narcotics detection into single-platform procurement tenders.
France
Customs authorities field handheld units for cargo container inspection across Channel ports. The EU AI Act's risk classification framework shapes algorithmic explainability requirements for automated detection systems. Paris-region forensic laboratories adopt non-destructive molecular fingerprinting to accelerate evidence processing workflows.
United Kingdom
Border Force procurement concentrates on sub-10-second response systems for passenger screening lanes. Post-Brexit regulatory divergence creates parallel certification tracks alongside EU MDR frameworks. Scottish police forces prioritize handheld interoperability with existing radio and biometric infrastructure networks.
Netherlands
Schiphol airport security integrators demand pre-validated conformity assessment packages to accelerate deployment timelines. Dutch border agencies pilot detection-as-a-service contracts with performance-based payment terms. Rotterdam chemical terminals deploy continuous sampling systems for F-Gas Regulation compliance verification.
Poland
Eastern frontier infrastructure upgrades generate tender volumes for portable platforms under three kilograms. Schengen perimeter expansion programs consolidate procurement of dual-use detection equipment. Warsaw-based security contractors establish service networks ahead of sustained border modernization spending.
Europe Trace Detection Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with CE-MDR dual marking and EU AI Act algorithmic validation separating price tiers. The vendor base concentrates around three strategic archetypes: vertically integrated security conglomerates with captive detector manufacturing, specialized spectroscopy houses with R&D-intensive mass spectrometry architectures, and diversified industrial technology groups leveraging cross-border service networks. Dominant competitive moves include backward integration into sensor component supply and geographic expansion through Eastern European service infrastructure.
Among UK- and US-based security technology conglomerates, Smiths Detection Group Ltd and Leidos Holdings Inc exemplify the vertically integrated archetype with upstream control over hardware production. Bruker Corporation represents the R&D-intensive spectroscopy specialist tier. These three anchors occupy positions across the premium-to-standard margin spectrum, with detection-as-a-service contracting models now transferring capital burden from public agencies to vendor balance sheets.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd |
| Teledyne FLIR LLC |
| Leidos Holdings Inc |
| Bruker Corporation |
| Autoclear LLC |
| OSI Systems Inc |
| Chemring Group PLC |
| NUCTECH COMPANY LIMITED |
| 3DX-RAY Ltd |
| Others |
Pricing and Supply Chain Analysis
Rare-earth oxide price indices cascade through European trace detector manufacturing, elevating input costs for ion mobility spectrometry drift tubes and surface-enhanced Raman substrates while compressing margins at standard-tier suppliers. REACH substance restrictions compound this pressure by forcing reformulation of plasmonic nanoparticles and refrigerant-based sample preparation modules, widening the cost gap between compliant premium systems and legacy equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-MDR dual-marked systems with EU AI Act algorithmic validation from single-certification units and unbundled hardware-only configurations. Price differentiation hinges on certification grade and after-sales service bundling, with premium tiers commanding substantial uplifts for pre-validated conformity packages. Cost compression in standard-tier portable units is intensifying because Polish and Romanian border agencies consolidate procurement into framework agreements. Municipal police forces exhibit highest price sensitivity due to decentralized budgets, while German federal police and UK Border Force prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and the United Kingdom operate hub-and-spoke patterns for detector spare parts and consumables, with Warsaw and Bucharest emerging as Eastern European logistics nodes. Manufacturing concentration rests on Germany, the United Kingdom, and the United States for finished systems, while rare-earth components and noble-metal catalysts draw from Chinese and Russian supplier bases. Single-source vulnerability in plasmonic nanoparticle substrates creates exposure to ECHA authorization delays. Distribution runs through authorized service networks rather than open-channel electronics distributors, tying equipment availability to vendor-certified technician density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Trace Detection Market compounds steadily as regulatory compliance mandates generate predictable replacement cycles across transportation security and industrial emissions monitoring. Schengen border modernization and F-Gas Regulation enforcement provide durable demand anchors.
For Market Incumbents: Anticipate margin compression in portable ion mobility spectrometry by consolidating aftermarket service contracts and deepening captive production of drift-tube assemblies. Detection-as-a-service contracting transfers capital burden to vendor balance sheets while locking out low-cost competitors lacking service infrastructure. EU AI Act algorithmic explainability requirements favor incumbents with pre-validated documentation libraries.
For New Entrants and Emerging Players: Enter via handheld device specialization for Eastern European border agencies, where Polish and Romanian tender volumes exceed established service network coverage. Environmental monitoring convergence at German chemical clusters offers white-space positioning for multi-threat platforms combining safety and emissions compliance. Partner with Warsaw-based security contractors to bypass incumbent distribution lock-in.
For Investors and Strategic Acquirers: Asymmetric upside sits with spectroscopy specialists possessing mass spectrometry IP and forensic laboratory relationships, as surface-enhanced Raman spectroscopy climbs fastest. Long-term viability hinges on R&D intensity and certification pipeline depth rather than volume scale. Watch ECHA substance authorization timelines as inflection indicators for platform redesign cycles and supplier qualification disruptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Components | Captive supply of drift tubes and plasmonic substrates insulates margins from rare-earth price volatility and REACH authorization delays. |
| EU AI Act Pre-Validation Investment | Documented algorithmic explainability packages accelerate CE marking for automated detection systems at UK and Spanish airport integrators. |
| Eastern European Service Network Buildout | Warsaw and Bucharest technician hubs capture Polish and Romanian border modernization tender volumes ahead of incumbent response. |
| Detection-as-a-Service Contracting | Performance-based payment terms transfer capital burden from Dutch and Swedish border agencies to vendor balance sheets. |
| Multi-Threat Platform Development | Combined explosives-narcotics-emissions detection consolidates procurement budgets at German chemical corridors under merged safety and compliance spending. |
Research Methodology
Direct dialogue with airport security integrators, border agency procurement officers, forensic laboratory directors, chemical plant safety managers, and detector manufacturer product managers grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance restriction databases, EU AI Act implementation guidance, CEN-CENELEC harmonized standards drafts, and customs procurement tender records. Bottom-up equipment deployment estimates triangulated against top-down market sizing from regulatory mandate scope and budget allocation disclosures.
Installed base and revenue projections across the analysis window segmented by detection modality, application type, end-user category, and product form-factor. CAGRs derived from equipment replacement cycle analysis tied to F-Gas Regulation phase-out timelines and REACH substance restriction effective dates. Forecast inputs incorporated Schengen border infrastructure investment plans and ECHA authorization procedure completion rates.
Inputs from public procurement databases and regulatory filing repositories were available through the study window; gaps in real-time tender award values and confidential R&D expenditure disclosures introduce uncertainty bands around vendor market share estimates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market